
 Organometallic Compounds Market | 2026-2036
Organometallic Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Organometallic Compounds Market Analysis
Homogeneous catalysis is fragmenting into site-specific and single-atom architectures, forcing suppliers to reengineer ligand platforms for precision polymerization. Albemarle Corporation dominates bromine-derived organometallic precursors for flame-retardant polymers. Evonik Industries AG specializes in custom metallocene catalysts for high-performance elastomers. Umicore SA anchors its position through closed-loop recycling of platinum group metal organometallics for automotive catalytic converters.
Organometallic compounds consist of at least one direct carbon-metal bond, typically synthesized via transmetalation or oxidative addition routes, with melting points and air sensitivity varying sharply by metal center and ligand bulk. These compounds serve primarily as homogeneous catalysts, pharmaceutical intermediates, and precursors for electronic materials. Metal carbonyls command the widest margin pools due to iridium and rhodium scarcity, while alkylmetal compounds lead volume through Ziegler-Natta polymerization systems. Catalyst applications are outpacing agriculture and specialty chemicals as polyethylene producers retrofit plants for metallocene-grade output.
EPA oversight of volatile organometallic emissions shapes US manufacturing location decisions, while REACH registration thresholds in Europe restrict small-volume metal carbonyl imports. China's MEE enforces wastewater limits on organotin catalyst facilities along the Yangtze basin. India's BIS certification for agricultural organometallic formulations delays market entry for non-domestic suppliers. Stakeholders must track how carbon border adjustments and critical raw materials lists reclassify cobalt and nickel organometallics in trade policy.
Market Dynamics
Polymerization catalyst suppliers are racing to reengineer ligand architectures as polyethylene producers retrofit plants for metallocene-grade output, compressing R&D cycles and forcing platform standardization decisions.
Growth Catalysts
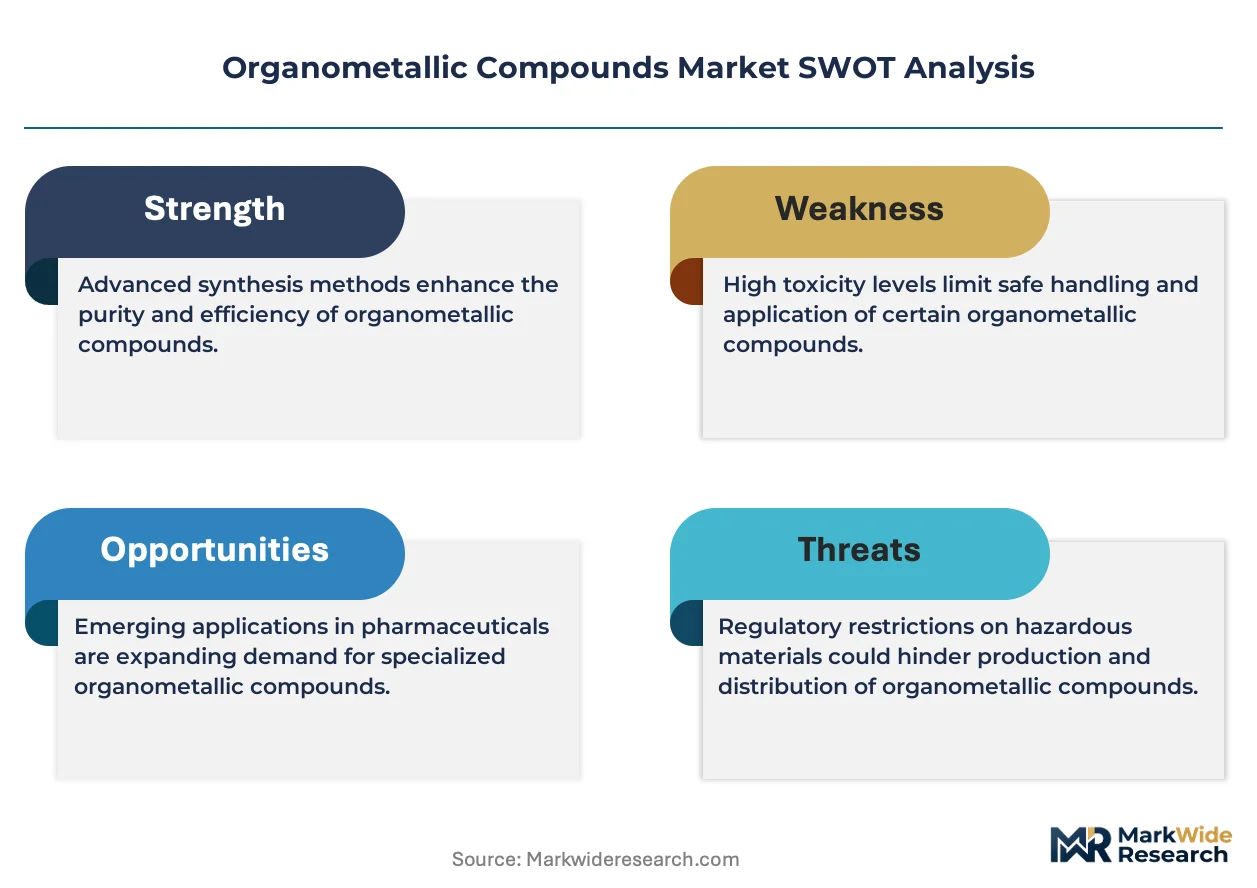
- REACH compliance tightening:Europe's purity benchmarks for metal carbonyl precursors are accelerating investments in closed-loop refining systems among specialty chemical suppliers.
- Ziegler-Natta system expansion:Refiners along the US Gulf Coast petrochemical corridor are demanding higher olefin yields, pulling alkylmetal compound volumes upward.
- China's dual carbon goals:The MEE's wastewater enforcement on organotin catalyst facilities is redirecting capital toward cleaner synthesis routes in the Yangtze River Delta.
Market Restraints
- Iridium and rhodium scarcity:Metal carbonyl margin pools face persistent pressure from concentrated PGM supply originating in South African and Russian mining complexes.
- Air sensitivity of alkylmetal compounds:Technical limitations in ambient-temperature handling constrain distribution radius and force cryogenic logistics investments.
- India's BIS certification delays:Agricultural organometallic formulations face extended approval timelines that freeze out non-domestic suppliers from seasonal procurement windows.
Strategic Opportunities
- Automotive catalytic converter recycling:Closed-loop recovery of platinum group metal organometallics offers margin capture in Germany's Ruhr chemical cluster.
- Single-atom catalysis convergence:The intersection of homogeneous and heterogeneous architectures creates white space for precision polymerization in high-performance elastomers.
- Electronic materials precursor demand:Thin-film deposition applications for semiconductors represent an underpenetrated vector for metal carbonyl suppliers.
Industry Challenges
- Transmetalation expertise scarcity:Synthetic chemists capable of oxidative addition route optimization command premium compensation, constraining production scale-up.
- EPA volatile emission compliance:US manufacturing location decisions require costly abatement infrastructure that extends facility commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organometallic Compounds Market |
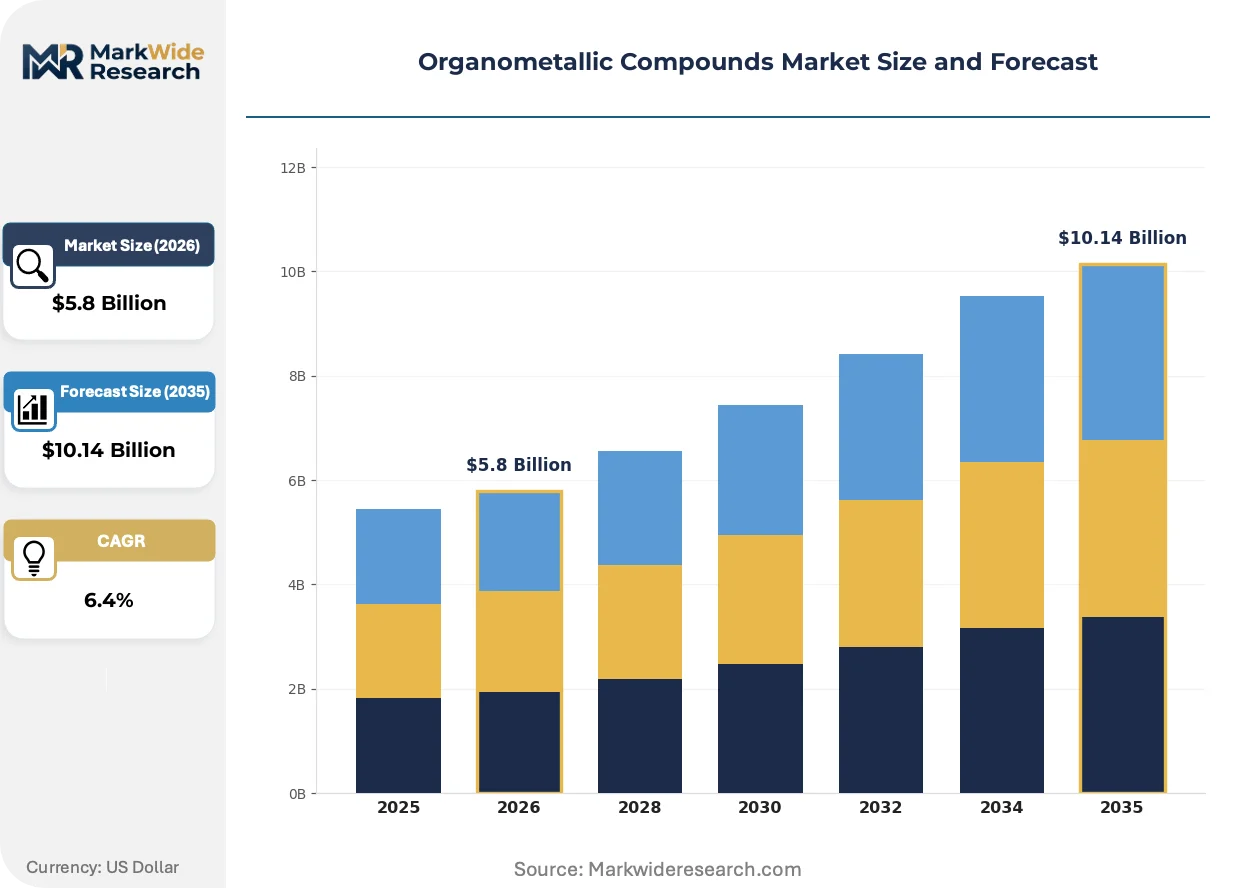
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylmetal Compounds, Arylmetal Compounds, Metal Carbonyls, Metal Alkoxides Application: Catalysts, Pharmaceuticals, Agriculture, Specialty Chemicals End User: Chemical Industry, Pharmaceutical Companies, Agriculture Sector, Research Institutions Form: Liquid, Solid, Gas, Aqueous Solution |
| Companies Covered | Evonik Industries AG, Umicore SA, BASF SE, Albemarle Corporation, Johnson Matthey plc, Dow Inc., Solvay SA, Arkema S.A., Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organometallic Compounds Market Emerging Trajectories
Computational catalyst design and regulatory chemistry are converging to compress development timelines, while procurement patterns in polymer production are fragmenting supplier relationships.
Single-atom catalyst architectures are virtualizing traditional homogeneous catalysis by isolating individual metal centers on oxide supports. Polyethylene producers in Germany and China are piloting these systems for precision stereocontrol. The technology is virtualizing conventional metallocene licensing models by enabling performance-tier customization without proprietary ligand portfolios.
REACH registration thresholds are restructuring European import patterns for low-volume metal carbonyls. Small-batch iridium and rhodium precursors now face documentation burdens that favor integrated suppliers with in-house regulatory affairs capacity. Specialty chemical distributors are consolidating their metal-organic product lines to concentrate compliance resources on higher-rotation SKUs.
Buyers of polymerization catalysts are unbundling after-sales technical service from material supply contracts. Large polyethylene producers in the US Gulf Coast are building in-house catalysis expertise, displacing traditional supplier-provided process optimization. This pattern concentrates most visibly among integrated refiners with captive research centers.
Organometallic Compounds Market Segmentation
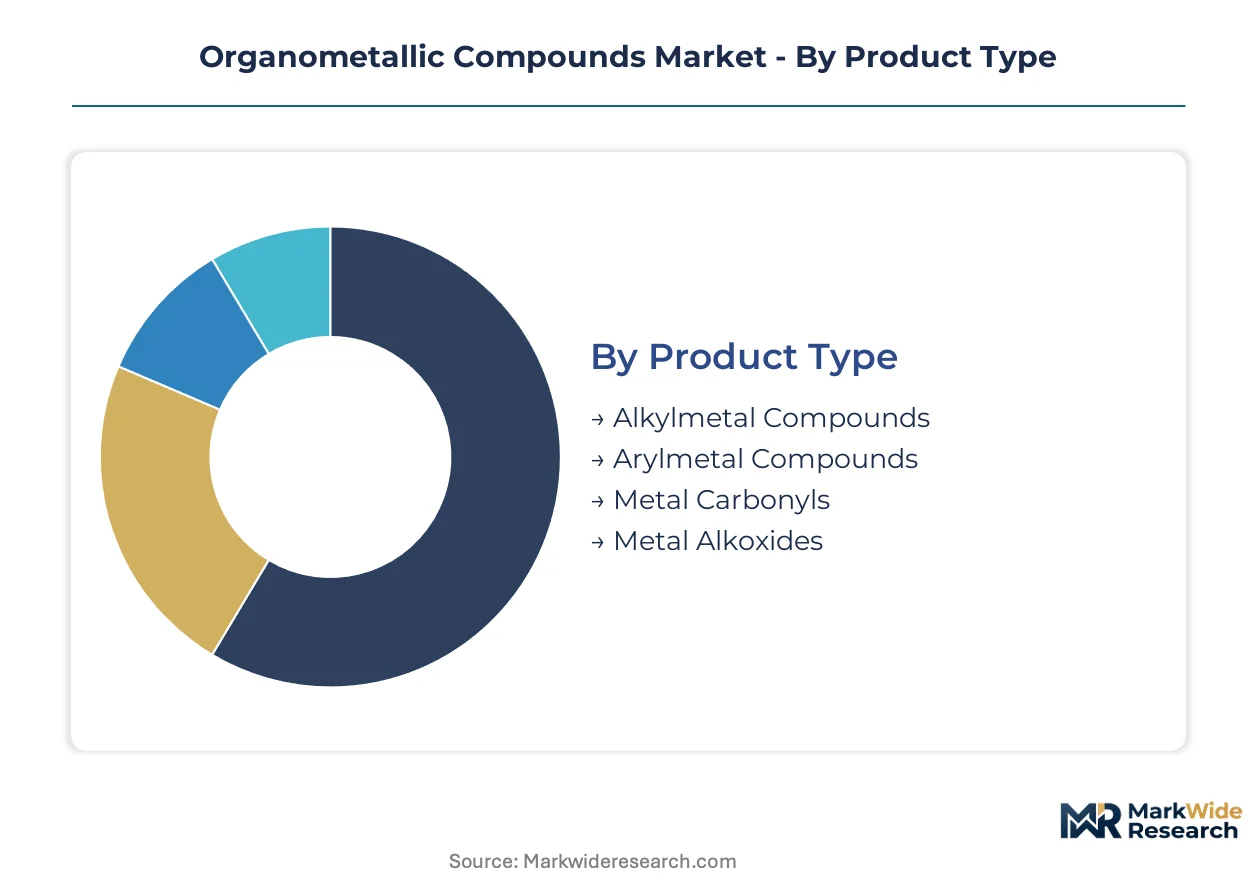
Organometallic compound procurement patterns diverge sharply across product chemistries and end-use specifications. Catalyst buyers prioritize thermal stability and air sensitivity profiles, while pharmaceutical and agricultural formulators emphasize batch-to-batch consistency and regulatory documentation.
Product Type:
Mature alkylmetal systems dominate volume throughput, while emerging metal carbonyl architectures command premium positioning in precision applications.
- Alkylmetal Compounds:These species feature direct carbon-metal sigma bonds with high reactivity toward electrophiles, requiring cryogenic handling infrastructure. Demand concentrates in Germany's Ruhr chemical cluster where polyethylene producers retrofit plants for metallocene-grade output, pulling volumes upward despite air sensitivity constraints.
- Metal Carbonyls:Coordination complexes of transition metals with carbon monoxide ligands exhibit exceptional thermal stability and defined decomposition pathways. Iridium and rhodium variants face persistent supply pressure from South African and Russian mining concentration, widening margin pools for integrated suppliers with closed-loop refining capability.
- Arylmetal Compounds:Aromatic ring-metal bonds offer enhanced thermal stability compared to alkyl analogues, serving cross-coupling applications in pharmaceutical intermediate synthesis.
- Metal Alkoxides:Oxygen-bridged structures function as sol-gel precursors and esterification catalysts, finding traction in thin-film deposition for electronic materials.
Alkylmetal compounds handle the majority of throughput; metal carbonyls are climbing the fastest on share.
Application:
Cost tier stratification separates commodity catalyst volumes from specialty pharmaceutical and agricultural premium positioning.
- Catalysts:Homogeneous and heterogeneous systems enable polymerization, hydrogenation, and C-C bond formation with stereoselective control. Refiners along the US Gulf Coast petrochemical corridor demand higher olefin yields, compressing R&D cycles and forcing ligand platform standardization decisions among suppliers.
- Pharmaceuticals:Organometallic intermediates facilitate carbon-heteroatom bond construction in active pharmaceutical ingredient synthesis. REACH registration thresholds in Europe favor integrated suppliers with in-house regulatory affairs capacity, restructuring import patterns for low-volume precursors.
- Agriculture:Organotin and organomercury compounds serve as biocides and fungicides, though China's MEE wastewater enforcement on Yangtze basin facilities is redirecting capital toward cleaner synthesis routes.
- Specialty Chemicals:Electronic materials precursors and fine chemical building blocks exploit metal carbonyl decomposition for thin-film deposition.
Catalyst applications absorb the dominant share of metal-organic output; pharmaceutical intermediates are expanding most quickly as regulatory documentation requirements favor qualified suppliers.
End User:
Customer type fragmentation distinguishes integrated chemical producers with captive R&D from outsourced pharmaceutical and agricultural formulators.
- Chemical Industry:Integrated refiners and specialty chemical manufacturers consume organometallics for captive catalytic processes and merchant catalyst production. Large polyethylene producers in the US Gulf Coast are building in-house catalysis expertise, displacing traditional supplier-provided process optimization.
- Pharmaceutical Companies:Contract development and manufacturing organizations source organometallic intermediates under stringent quality agreements. India's BIS certification delays freeze out non-domestic suppliers from seasonal procurement windows.
- Agriculture Sector:Formulators of crop protection products face extended approval timelines for novel organometallic actives.
- Research Institutions:Academic and government laboratories drive exploratory chemistry for next-generation catalytic architectures.
Chemical industry procurement dominates volume; pharmaceutical companies are gaining share fastest as outsourcing trends accelerate.
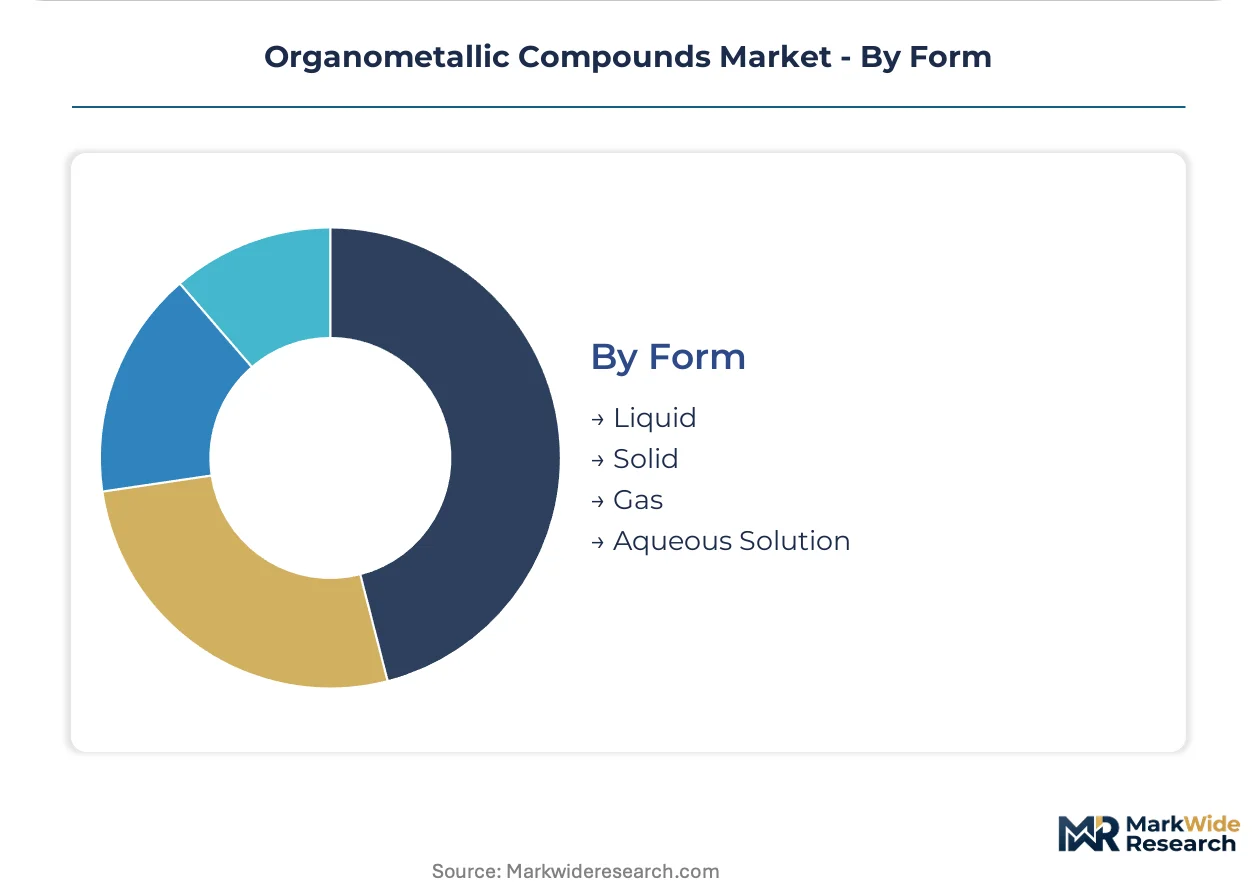
Form:
Supply concentration in cryogenic liquid handling infrastructure shapes distribution economics for air-sensitive species.
- Liquid:Solutions in hydrocarbon or ethereal solvents enable metered delivery for continuous polymerization processes, though ambient-temperature handling limitations constrain distribution radius.
- Solid:Crystalline or powder forms offer extended shelf stability for pharmaceutical and agricultural formulations requiring precise dosing.
- Gas:Volatile metal carbonyls such as nickel tetracarbonyl serve chemical vapor deposition applications in semiconductor fabrication.
- Aqueous Solution:Water-compatible formulations address environmental health and safety preferences in selected agricultural applications.
Liquid formulations carry the bulk of commercial throughput; gas-phase metal carbonyls are advancing fastest on share in electronic materials deposition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated refiners and specialty chemical manufacturers concentrate procurement in three distinct chemical corridors. Germany's Ruhr cluster, China's Yangtze River Delta, and the US Gulf Coast petrochemical belt anchor volume demand for polymerization catalysts and metal carbonyl precursors.
United States
Refiners along the Gulf Coast corridor demand higher olefin yields from metallocene-grade polyethylene retrofits. EPA oversight of volatile organometallic emissions shapes manufacturing location decisions and extends facility commissioning timelines. Houston and Corpus Christi host concentrated alkylmetal distribution infrastructure serving captive polymerization units.
Germany
Closed-loop recycling of platinum group metal organometallics for automotive catalytic converters drives circular economy investments. REACH compliance tightens purity benchmarks for metal carbonyl precursors and accelerates closed-loop refining system adoption. The Ruhr chemical cluster anchors demand for Ziegler-Natta catalyst systems among integrated polyethylene producers.
China
The Yangtze River Delta chemical corridor redirects capital toward cleaner synthesis routes as MEE wastewater enforcement intensifies on organotin catalyst facilities. Dual carbon goals tighten emissions benchmarks for metal carbonyl production. Shanghai and Ningbo host expanding metallocene catalyst manufacturing serving domestic polyethylene capacity additions.
India
Agricultural organometallic formulations face extended approval timelines that freeze non-domestic suppliers from seasonal procurement windows. BIS certification requirements delay market entry for imported biocide and fungicide actives. Gujarat and Maharashtra concentrate domestic formulator capacity for crop protection products.
Japan
Electronic materials precursor demand for thin-film deposition applications pulls metal carbonyl volumes into semiconductor fabrication supply chains. METI industrial policy supports advanced catalysis research for next-generation polymerization architectures. The Osaka-Kobe chemical corridor specializes in high-purity organometallic precursors for electronics applications.
Organometallic Compounds Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct value chain positions. The vendor base separates into integrated chemical conglomerates with captive raw material positions and focused specialists with ligand engineering expertise. Three archetypes dominate: diversified material science conglomerates, precious metal refining specialists with closed-loop capabilities, and custom catalyst engineering houses. Competitive moves concentrate on backward integration into PGM refining and technology licensing for metallocene architectures.
Within the diversified chemical conglomerate tier, BASF SE and Dow Inc. exemplify scale-driven positions spanning multiple organometallic product categories. Evonik Industries AG and Umicore SA occupy specialist positions anchored in custom catalyst design and precious metal circularity respectively. Albemarle Corporation represents the bromine-derivative vertical, while Johnson Matthey plc anchors the platinum group metal refining archetype. Arkema S.A., Solvay SA, and Wacker Chemie AG sit within European-based specialty chemical portfolios with regional concentration in polymerization and electronics applications.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Umicore SA |
| BASF SE |
| Albemarle Corporation |
| Johnson Matthey plc |
| Dow Inc. |
| Solvay SA |
| Arkema S.A. |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on South African and Russian platinum group metal mining complexes determines both margin tier spreads and supply chain configuration across metal carbonyl precursors. REACH registration thresholds and EPA volatile emission compliance create regulatory chokepoints that compress pricing power for non-integrated distributors while rewarding closed-loop refiners with captive PGM recovery.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange palladium and rhodium benchmarks dominate procurement for iridium and rhodium carbonyl precursors. Price differentiation hinges on purity certification tier and captive refining capability, with integrated suppliers commanding premium positioning over merchant distributors. Cost compression in standard-grade alkylmetal compounds is intensifying because polyethylene producers are unbundling technical service contracts and building in-house catalysis expertise. Merchant distributors exhibit highest price sensitivity due to margin pressure from regulatory documentation burdens, while integrated refiners with captive R&D centers demonstrate lowest sensitivity given backward control over ligand engineering.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from precious metal traders anchor working capital structures for iridium and rhodium carbonyl distributors. Geographic supply concentration centers on South Africa, Russia, and Canada for platinum group metal feedstock, with Germany and China hosting downstream refining and catalyst formulation. Raw material dependencies rest on mining concentrates, carbon monoxide supply, and specialized ligand precursors from the Ruhr and Yangtze chemical corridors. Single-source vulnerability from South African mining concentration poses structural risk to metal carbonyl availability. Distribution feeds from integrated chemical conglomerates through specialty distributors to polymerization catalyst end-users, with cryogenic logistics infrastructure constraining alkylmetal compound radius.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-atom catalysis architectures threaten conventional metallocene licensing models by enabling performance customization without proprietary ligand portfolios, forcing incumbents to defend substitution risk through integrated technology control.
For Market Incumbents: Pre-empt single-atom catalyst displacement by consolidating ligand engineering expertise through selective acquisition of custom catalyst engineering houses in Germany's Ruhr cluster. Deepen upstream control over platinum group metal refining capacity to secure margin capture from closed-loop automotive converter recovery, insulating against South African supply concentration risk. For New Entrants and Emerging Players: Electronic materials precursors for thin-film deposition in Japan's Osaka-Kobe corridor represent the most penetrable entry point given underexploited metal carbonyl demand from semiconductor fabrication supply chains. Agricultural organometallic formulations in India offer secondary white-space opportunity as BIS certification delays freeze established non-domestic suppliers from seasonal procurement windows. A technical service bundling go-to-market angle displaces the unbundling trend among large polyethylene producers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precious metal refining specialists with closed-loop capabilities and regulatory affairs scale. Long-term viability across the analysis window hinges on carbon border adjustment exposure and critical raw materials list reclassification for cobalt and nickel organometallics. Watch for REACH threshold tightening on low-volume metal carbonyl imports as the inflection signal for distributor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Refining | Captive iridium and rhodium supply secures margin pools from South African mining concentration. |
| Closed-Loop Recovery Facility Buildout | Germany's Ruhr cluster anchors circular economy investments for automotive catalytic converter metals. |
| Single-Atom Catalyst R&D Partnership | Virtualized metallocene licensing threatens conventional ligand portfolio value across polyethylene producers. |
| REACH Compliance Infrastructure Investment | Documentation scale advantages favor integrated suppliers over small-batch metal carbonyl distributors. |
| Cryogenic Logistics Network Expansion | Air-sensitive alkylmetal compound distribution radius constraints force infrastructure consolidation decisions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with polymerization catalyst procurement leads at Gulf Coast refiners, metallocene R&D directors in Germany's Ruhr cluster, precious metal trading desks, and regulatory affairs specialists navigating REACH and EPA compliance. Secondary validation drew from ECHA registration databases, SEC 10-K filings from disclosed organometallic producers, customs trade data for metal carbonyl imports, and ACC sector reports. Bottom-up volume modeling from application-level consumption patterns triangulated against top-down value estimates from disclosed segment revenues.
Calibration against historical capacity utilization rates and disclosed plant retrofit timelines anchored the projection framework across the modeling period. Segmentation dimensions modeled include product chemistry type, application end-use, customer integration level, and regional production hub concentration. CAGRs were derived from slope analysis of disclosed volume trends and capacity expansion announcements, with iridium and rhodium price volatility and metallocene adoption curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, olefin demand cycles, or PGM mining output would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Global Chromatography Reagents Market