
 2-Acetylthiophene Market | 2026-2036
2-Acetylthiophene Market Size, Share, and Industry Trends Forecast 2026-2036
2-Acetylthiophene Market Outlook
ISO 9001 certification is rotating as the baseline qualification gating supplier participation in pharmaceutical-grade 2-acetylthiophene procurement. Merck leverages its integrated quality systems to sustain bulk supply contracts with European drug manufacturers. Tokyo Chemical Industry anchors the Asia-Pacific specialty chemical trade through its catalog distribution network and custom synthesis capabilities. Thermo Fisher Scientific competes on specification breadth, offering multiple purity grades that align with varying regulatory thresholds across end markets.
2-Acetylthiophene is an organosulfur compound with the molecular formula C6H6OS, synthesized primarily through Friedel-Crafts acylation of thiophene with acetic anhydride, and serves as a versatile building block in heterocyclic chemistry for pharmaceutical and agrochemical applications. The reagent segment dominates current volume flows, while the intermediate category captures expanding margin pools as multi-step API synthesis grows more complex. Pharmaceutical companies represent the most quality-sensitive end user group, demanding certificates of analysis that document impurity profiles down to parts-per-million levels.
REACH registration in Europe and EPA Toxic Substances Control Act oversight in the United States impose documentation burdens that favor established suppliers with dedicated regulatory affairs teams. The FDA's active pharmaceutical ingredient guidance further tightens impurity control expectations, pushing food industry and cosmetic industry buyers toward certified sources even at premium pricing. Stakeholders must monitor evolving pharmacopeial monographs and region-specific chemical inventory listings to anticipate qualification barriers before they disrupt supply continuity.
Market Dynamics
Pharmaceutical supply chain consolidation is compressing supplier qualification timelines while simultaneously elevating purity thresholds, forcing specialty chemical manufacturers to embed regulatory documentation capabilities directly into production workflows.
Growth Catalysts
- REACH Registration Mandates:European ECHA compliance requirements are filtering out uncertified producers and redirecting volume toward registered suppliers with established dossier management systems.
- India's CRMO Expansion:Contract research and manufacturing organizations in Hyderabad and Ahmedabad are scaling heterocyclic intermediate output to serve global API supply chains.
- Friedel-Crafts Process Optimization:Catalytic efficiency improvements in acylation chemistry are reducing acetic anhydride waste ratios and lowering per-kilogram production costs.
Market Restraints
- Thiophene Feedstock Volatility:Petroleum-derived thiophene pricing fluctuates with crude oil benchmarks, compressing margins for non-integrated acetylthiophene producers.
- Chinese Supply Concentration:Bulk pharmaceutical intermediate manufacturing clusters in Jiangsu and Zhejiang provinces control significant raw material flows, creating single-source vulnerability.
- Pyridine Derivative Substitution:Certain agrochemical applications are migrating toward pyridine-based heterocycles where sulfur content creates downstream processing complications.
Strategic Opportunities
- Brazilian Agrochemical Formulation:ANVISA-registered suppliers can access expanding soybean fungicide markets requiring thiophene-derived active ingredients.
- Continuous Flow Synthesis:Microreactor technology integration with traditional batch Friedel-Crafts systems is opening modular production architectures for mid-scale pharmaceutical contracts.
- Green Chemistry Incentives:EPA Safer Choice program recognition and EU Green Deal alignment are creating preferential procurement pathways for bio-based acetic anhydride variants.
Industry Challenges
- Analytical Methodology Standardization:Harmonizing impurity profiling protocols between USP, EP, and JP pharmacopeias delays multi-region product qualification by 8-14 months.
- Specialized Sulfur Handling Infrastructure:Organosulfur compound manufacturing requires corrosion-resistant reactor alloys and dedicated effluent treatment systems that demand substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Acetylthiophene Market |
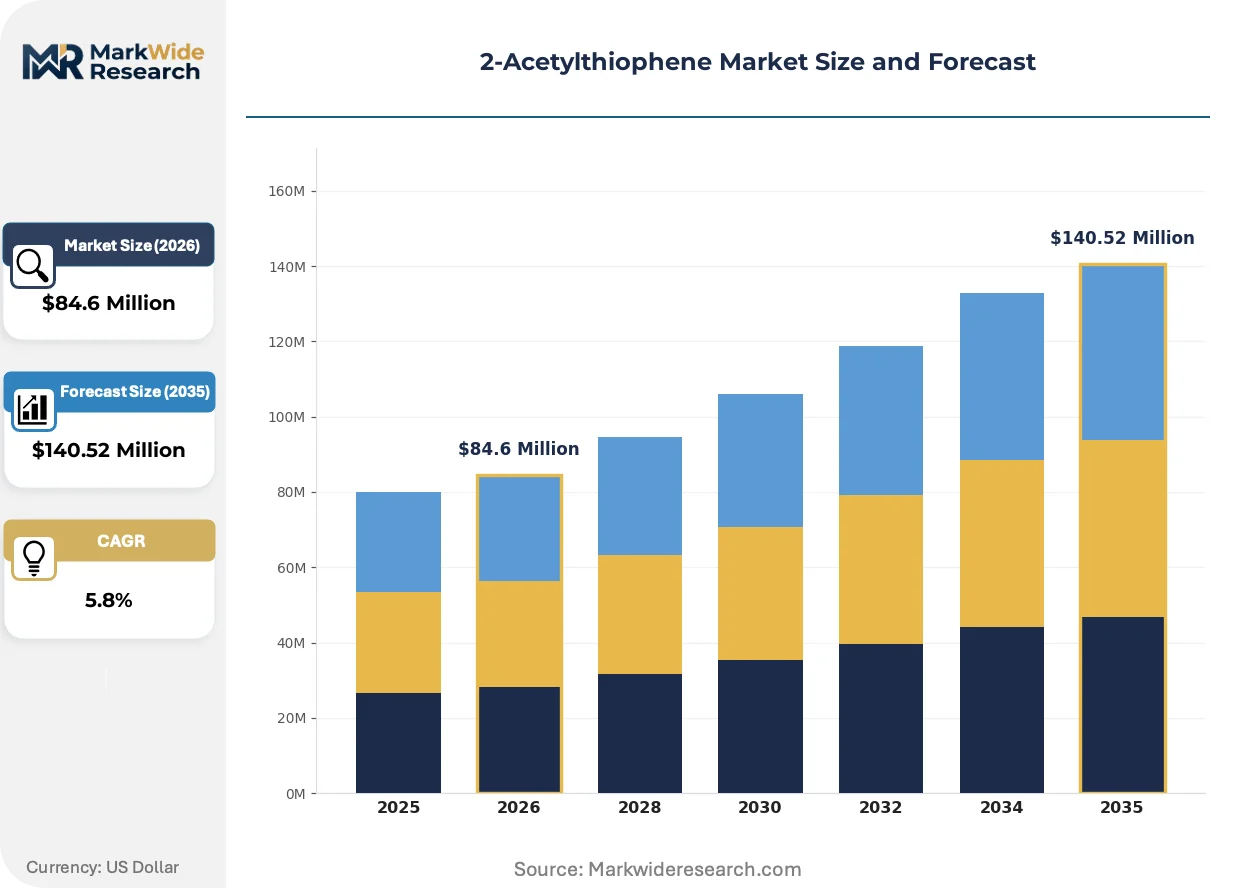
| Market Size in 2026 | $84.6 Million |
| Market Size in 2035 | $140.52 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Reagent, Intermediate, Additive Application: Flavoring Agent, Fragrance, Chemical Synthesis, Pharmaceuticals End User: Food Industry, Cosmetic Industry, Chemical Industry, Pharmaceutical Companies Distribution Channel: Online Sales, Direct Sales, Distributors, Retailers |
| Companies Covered | Tokyo Chemical Industry (TCI), Aromalake Chemical, Merck, Thermo Fisher Scientific, Glentham Life Sciences, MolCore, Acros Organics, Ark Pharm, Capot Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Acetylthiophene Market Strategic Shifts
Process intensification and regulatory data harmonization are converging to reshape how specialty chemical suppliers compete on speed-to-qualification rather than unit economics alone.
Continuous flow reactor technology is decomposing the traditional batch manufacturing paradigm for Friedel-Crafts acylation. European pharmaceutical intermediates suppliers are retrofitting pilot plants with modular microreactor trains to reduce solvent volumes and thermal excursion risks. This technology is decomposing capital barriers for mid-scale entrants while compressing campaign turnaround times from weeks to days.
EMA's revised guideline on elemental impurities (ICH Q3D) is tightening sulfur residue specifications for metal catalyst traces in heterocyclic synthesis. Drug manufacturers now demand certificates of analysis with ICP-MS data for every lot, forcing intermediate suppliers to invest in inductively coupled plasma instrumentation. API synthesis operations in Germany and Switzerland are most affected, with qualification audits extending to tier-three raw material sources.
Certificate-of-analysis-driven purchasing is consolidating buyer-seller relationships around integrated quality data platforms. Pharmaceutical procurement teams are bypassing catalog distributors for direct manufacturer contracts where electronic batch records integrate with their ERP systems. This behavioral shift is most visible in North American generic drug manufacturing, where FDA inspection readiness requirements favor suppliers with validated LIMS infrastructure.
2-Acetylthiophene Market Segmentation
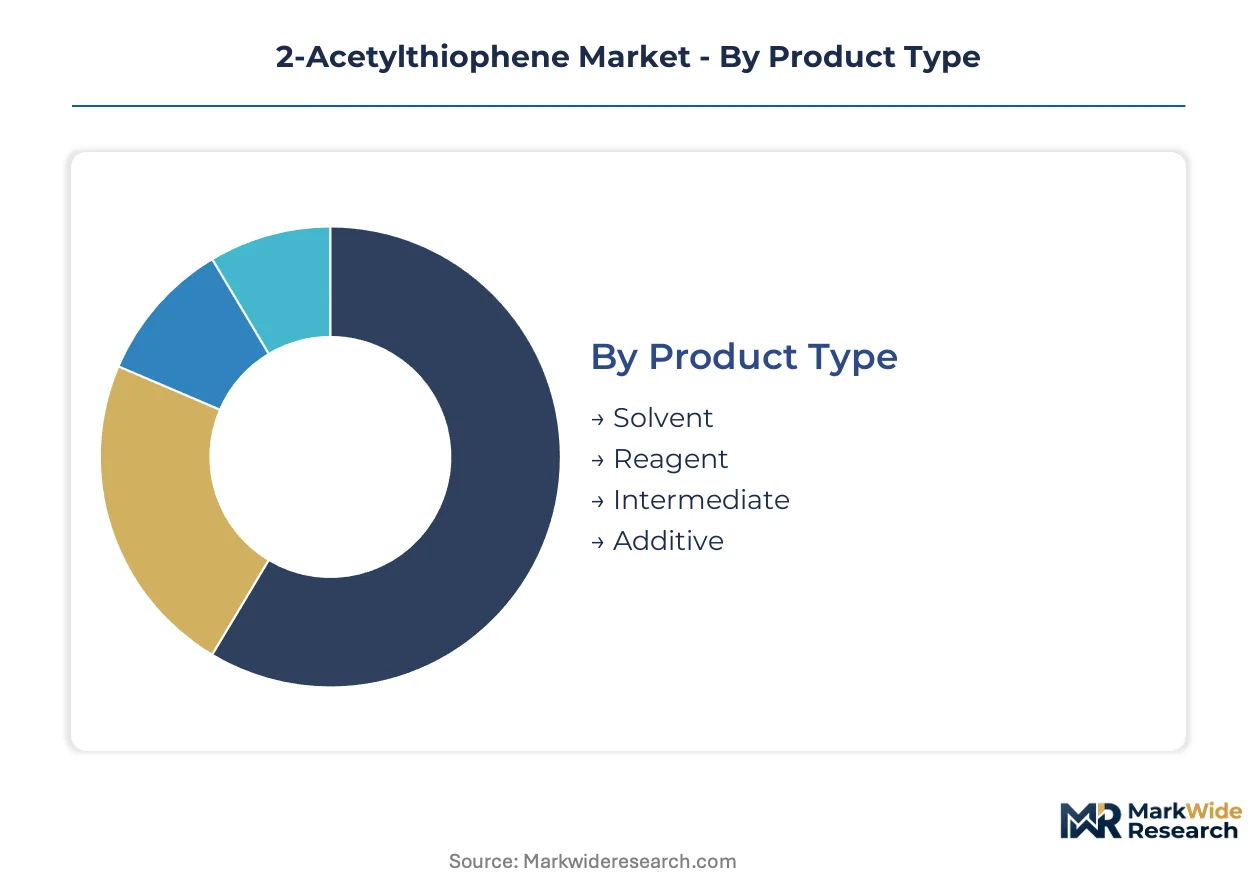
Segmentation in the 2-acetylthiophene market reveals how purity grades and regulatory certifications channel material toward distinct buyer workflows. Pharmaceutical procurement teams route high-purity lots through direct sales channels with integrated quality data platforms, while industrial buyers access standard grades via distributor networks.
Product Type:
Channel-mix patterns diverge sharply: intermediates flow predominantly through direct manufacturer contracts with pharmaceutical API producers, while reagents and solvents circulate via catalog distributors serving research laboratories and pilot-scale operations.
- Intermediate:Multi-step API synthesis demands this grade for carbonyl-functionalized heterocycle construction. Hyderabad-based CRMOs in India scale output for global drug supply chains under FDA and EMA audit protocols. Pharmaceutical companies specify impurity profiles to parts-per-million with ICP-MS documentation for every lot.
- Reagent:Laboratory-scale Friedel-Crafts acylation and heterocyclic methodology development consume this category. North American and European academic institutions and contract research organizations drive volume through Tokyo Chemical Industry and Merck distribution networks. Catalog pricing and rapid fulfillment matter more than bulk unit economics.
- Solvent:Process chemistry applications in agrochemical pilot plants utilize this grade for reaction media.
- Additive:Specialty polymer and materials science applications incorporate this segment at smaller scale.
Intermediate dominates installed base. Reagent is where expansion concentrates.
Application:
Cost-tier differentiation separates pharmaceutical-grade material commanding premium pricing from industrial-grade lots sold on specification breadth rather than certification depth.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis represents the most quality-intensive application. FDA guidance on elemental impurities and ICH Q3D compliance force suppliers to invest in inductively coupled plasma instrumentation and validated LIMS infrastructure. German and Swiss API manufacturers extend qualification audits to tier-three raw material sources.
- Chemical Synthesis:Agrochemical and fine chemical manufacturing utilize this segment for thiophene-derived fungicide and heterocycle production. Brazilian ANVISA-registered suppliers access soybean protection markets requiring sulfur-containing active ingredients. Process intensification through continuous flow microreactor technology is compressing campaign turnaround times.
- Flavoring Agent:Food-grade specifications apply with FSSAI in India and FDA food additive regulations governing purity thresholds.
- Fragrance:Cosmetic industry applications follow separate qualification protocols with emphasis on sensory rather than analytical specifications.
Pharmaceuticals commands margin concentration. Chemical Synthesis is climbing the fastest on agrochemical formulation demand.
End User:
Customer-type segmentation maps directly onto procurement sophistication: pharmaceutical companies demand electronic batch record integration, while food and cosmetic buyers prioritize certificate-of-analysis availability over system interoperability.
- Pharmaceutical Companies:The most quality-sensitive buyer group mandates ISO 9001 certification as baseline qualification. REACH registration in Europe and EPA Toxic Substances Control Act documentation in the United States filter supplier pools toward established players with dedicated regulatory affairs teams. Direct sales channels with ERP integration dominate procurement patterns.
- Chemical Industry:Agrochemical formulators and specialty chemical manufacturers purchase on specification breadth and volume pricing. Chinese supply concentration in Jiangsu and Zhejiang provinces creates single-source vulnerability for non-integrated buyers. Distributor relationships provide supply security through inventory buffering.
- Food Industry:FSSAI compliance in India and evolving FDA standards reshape purity requirements for this segment.
- Cosmetic Industry:Fragrance compounders access material through specialty chemical distributors with regional formulation support capabilities.
Pharmaceutical Companies anchor premium-tier volume. Chemical Industry represents the broadest addressable base.
Distribution Channel:
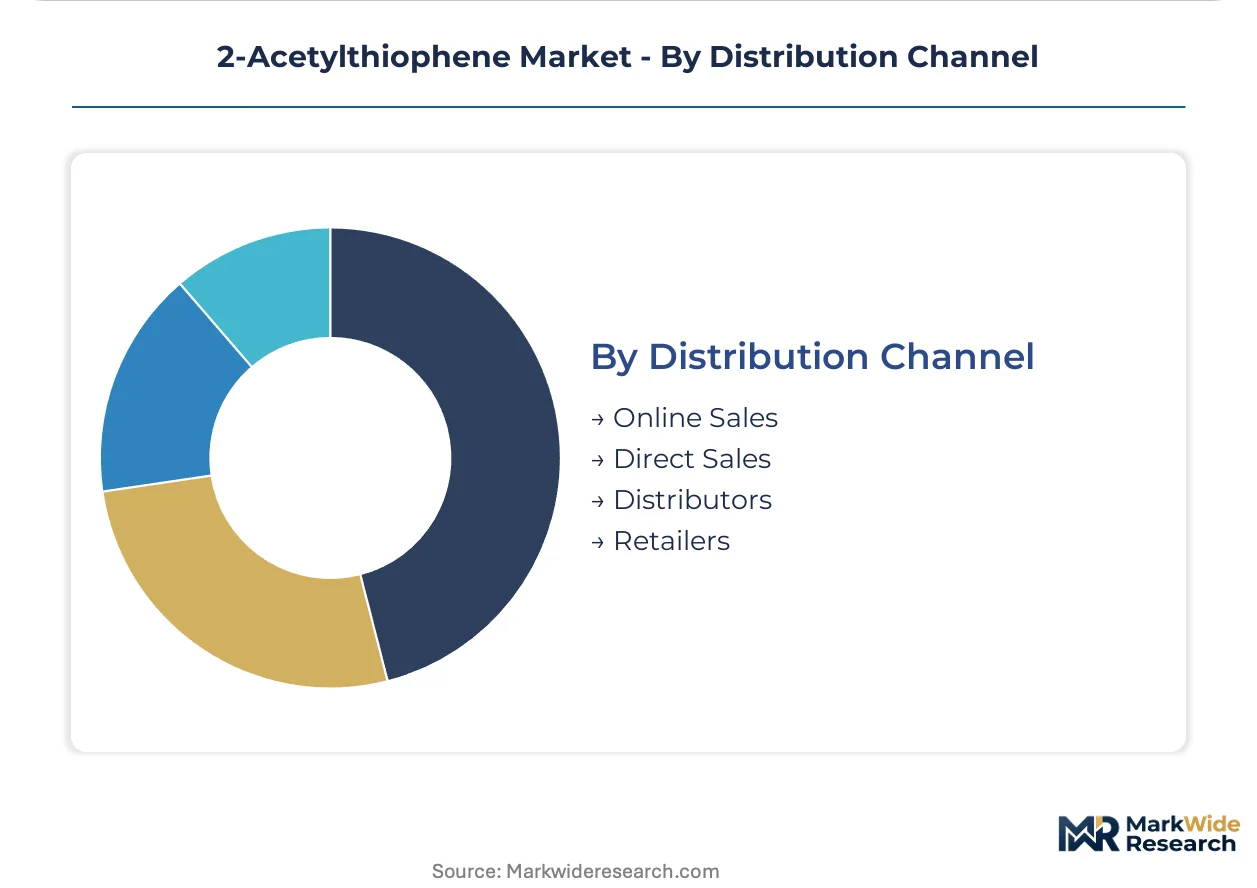
Supply concentration geography dictates channel viability: bulk pharmaceutical intermediate manufacturing clusters in China and India favor direct sales, while fragmented research chemical demand in North America and Europe sustains distributor networks.
- Direct Sales:Pharmaceutical procurement teams bypass catalog distributors for manufacturer contracts where electronic batch records integrate with their ERP systems. This channel captures the highest-margin, most documentation-intensive transactions. Thermo Fisher Scientific and Merck compete here on validated LIMS infrastructure and FDA inspection readiness.
- Distributors:Tokyo Chemical Industry anchors Asia-Pacific specialty chemical trade through catalog distribution networks serving mid-scale buyers. Regional distributors buffer inventory for agrochemical formulators in Brazil and India where ANVISA and CDSCO registration requirements create qualification barriers.
- Online Sales:Research-scale quantities for academic and early-stage discovery operations flow through this channel.
- Retailers:Minimal penetration; limited to small-scale laboratory supply outlets.
Direct Sales dominates value capture. Distributors sustain the widest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration mandates in Europe and India's PLI scheme for pharmaceuticals are redirecting 2-acetylthiophene procurement toward certified suppliers with established dossier management systems. National regulators impose divergent purity documentation burdens that reshape regional competitive positioning.
United States
Generic drug manufacturers in New Jersey and North Carolina drive pharmaceutical-grade demand through FDA inspection-ready supply chains. EPA Toxic Substances Control Act oversight filters supplier pools toward established players with dedicated regulatory affairs teams. The Boston-Cambridge biotech corridor sustains reagent-scale consumption for early-stage heterocyclic methodology development.
Germany
EMA's revised ICH Q3D guideline on elemental impurities tightens sulfur residue specifications for API synthesis operations in Ludwigshafen and Leverkusen. German API manufacturers extend qualification audits to tier-three raw material sources, compressing supplier onboarding timelines. BASF's integrated chemical parks in Ludwigshafen anchor heterocyclic intermediate production for European pharmaceutical supply chains.
India
CDSCO-registered contract research and manufacturing organizations in Hyderabad and Ahmedabad scale heterocyclic intermediate output for global drug supply chains. FSSAI compliance requirements reshape purity thresholds for food-grade applications serving domestic flavoring markets. The Gujarat Special Economic Zone clusters specialty chemical manufacturing for export-oriented pharmaceutical intermediate production.
China
Jiangsu and Zhejiang province manufacturing clusters control significant raw material flows for bulk pharmaceutical intermediate production, creating single-source vulnerability for non-integrated buyers. NMPA registration requirements and evolving GB standards impose documentation burdens that favor suppliers with validated quality management systems. The Yangtze River Delta chemical industry belt concentrates Friedel-Crafts acylation capacity for both domestic consumption and export.
Switzerland
Swissmedic-regulated API synthesis operations in Basel demand certificates of analysis with ICP-MS data for every lot, forcing intermediate suppliers to invest in inductively coupled plasma instrumentation. The country's precision chemical manufacturing tradition supports high-purity heterocyclic compound production for oncology and cardiovascular drug programs. Novartis and Roche supply chain proximity sustains premium-tier procurement relationships with direct manufacturer contracts.
2-Acetylthiophene Market Competitive Environment
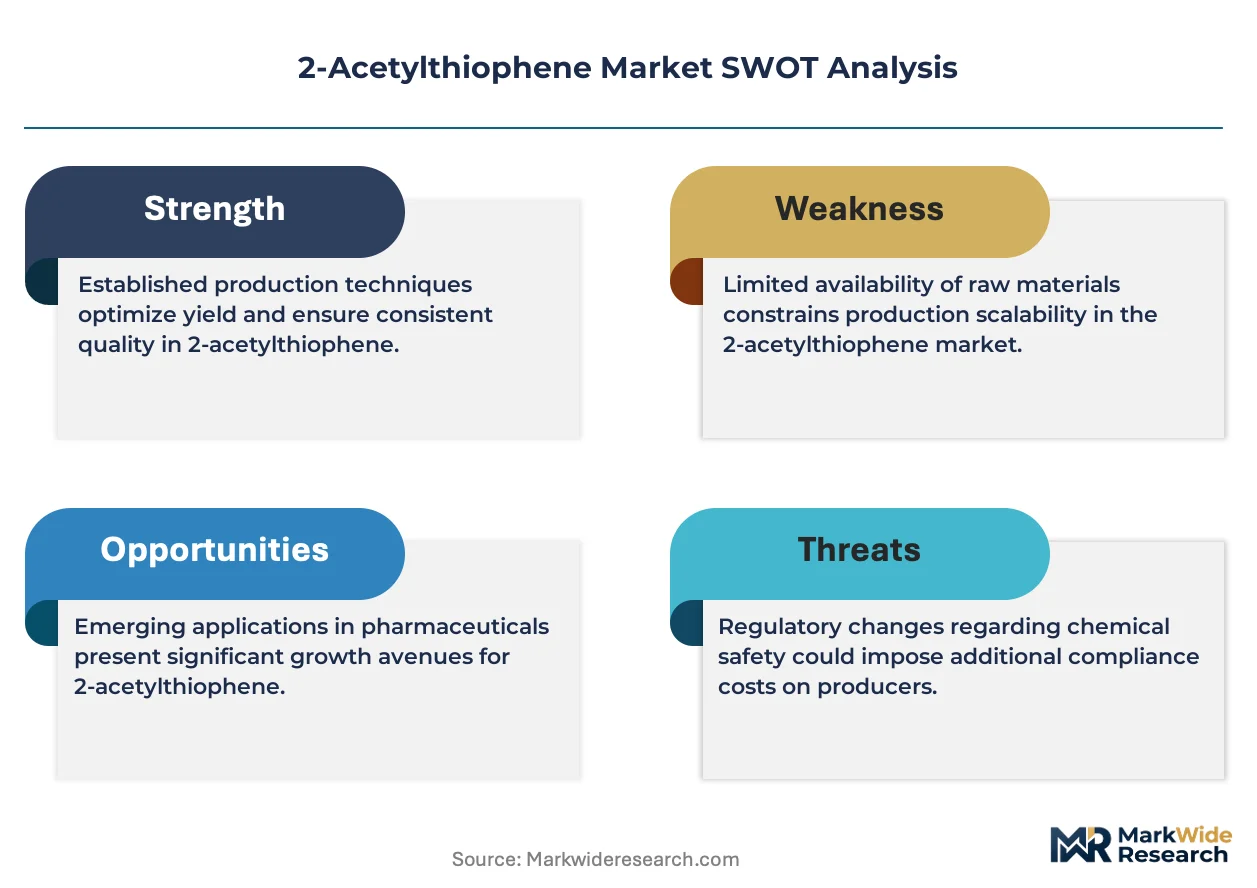
Player mix skews toward integrated life science conglomerates with validated quality infrastructure and regional specialty chemical distributors serving fragmented research-scale demand. Market structure concentrates around three tiers: multinational catalog distributors with global logistics networks, mid-scale custom synthesis houses with regional regulatory expertise, and commodity chemical producers competing on specification breadth. Dominant competitive moves include backward integration into thiophene feedstock sourcing and technology licensing partnerships for continuous flow reactor retrofits.
Within the integrated distributor tier, Merck and Thermo Fisher Scientific exemplify players competing on validated LIMS infrastructure and ERP integration capabilities for pharmaceutical procurement teams. Tokyo Chemical Industry anchors Asia-Pacific specialty chemical trade through catalog distribution networks. Among custom synthesis specialists, Capot Chemical and MolCore occupy positions serving mid-scale pharmaceutical contracts with region-specific regulatory dossier management.
| Leading Market Players |
|---|
| Tokyo Chemical Industry (TCI) |
| Aromalake Chemical |
| Merck |
| Thermo Fisher Scientific |
| Glentham Life Sciences |
| MolCore |
| Acros Organics |
| Ark Pharm |
| Capot Chemical |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day qualification timelines for pharmaceutical-grade material concentrate pricing power with established suppliers holding REACH dossiers and FDA inspection-ready infrastructure. This lead-time compression rewards incumbents with validated LIMS systems while squeezing margins for catalog distributors serving research-scale buyers.
Pricing Analysis
Certification level creates the primary spread across the market, with ISO 9001-validated pharmaceutical-grade material commanding substantial premiums over standard reagent grades. Three-tier pricing structure across premium, standard, and economy levels reflects impurity thresholds measured in parts-per-million and documentation depth rather than unit volume. Cost compression in the standard tier is intensifying because Chinese bulk intermediate producers are expanding Friedel-Crafts capacity. Academic and early-stage discovery operations exhibit the highest price sensitivity, while Swiss and German API manufacturers prioritize lot-to-lot consistency over per-kilogram economics.
Supply Chain Analysis
Thiophene feedstock availability from petroleum refining byproduct streams anchors supply security for acetylthiophene manufacturers. Production gravity centers on Jiangsu and Zhejiang provinces in China, with secondary concentrations in Gujarat's Special Economic Zone and the Yangtze River Delta. The supply chain draws from acetic anhydride, corrosion-resistant reactor alloys, and specialized sulfur-handling infrastructure. Single-source vulnerability in Chinese intermediate manufacturing clusters exposes non-integrated buyers to disruption. Distribution runs through direct manufacturer contracts for pharmaceutical volumes and catalog networks for research-scale demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyridine-based heterocycle substitution in agrochemical formulations threatens sulfur-containing intermediate demand, forcing incumbents to defend pharmaceutical-grade positioning where regulatory lock-in sustains pricing power.
For Market Incumbents: Fortify backward integration into thiophene feedstock sourcing to buffer margin compression from crude oil volatility. Deepen ERP integration capabilities with North American generic drug manufacturers facing FDA inspection readiness mandates. Prioritize continuous flow reactor retrofits to compress campaign turnaround times against Chinese batch producers. For New Entrants and Emerging Players: Lead with ANVISA-registered supply for Brazilian agrochemical formulators requiring thiophene-derived fungicide actives. Target mid-scale pharmaceutical contracts in India where CDSCO-registered CRMOs seek alternative heterocyclic intermediate sources. Emphasize green chemistry credentials aligned with EPA Safer Choice recognition to differentiate from incumbent commodity suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because REACH registration barriers and pharmacopeial monograph compliance favor consolidated supplier bases with dedicated dossier management teams. Acquisition candidates with validated ICP-MS instrumentation and tier-three audit relationships offer defensive positioning. Watch for ICH Q3D guideline expansion into additional metal catalyst specifications as the inflection signal for instrumentation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thiophene Feedstock | Captive supply from petroleum refining streams insulates margin structure against crude benchmark volatility. |
| Continuous Flow Reactor Retrofit | Microreactor technology integration compresses Friedel-Crafts campaign turnaround from weeks to days for pharmaceutical contracts. |
| REACH Dossier Expansion | ECHA registration maintenance filters competitor pools and secures European pharmaceutical procurement channels. |
| ICP-MS Instrumentation Investment | Elemental impurity documentation capability satisfies ICH Q3D mandates from German and Swiss API manufacturers. |
| ANVISA Registration Completion | Brazilian agrochemical market access opens soybean fungicide formulation demand for sulfur-derived actives. |
Study Parameters
The analysis maps pharmaceutical intermediate, reagent-grade, and agrochemical application sub-sectors, each validated through procurement directors at generic drug manufacturers, regulatory affairs leads at CRMOs, and technical R&D directors at specialty chemical distributors. Primary interview findings triangulated against customs trade data, CDSCO registration filings, ECHA dossier databases, and SEC 10-K chemical segment disclosures. Bottom-up volume estimates from named production facilities reconciled with top-down consumption models across end-use industries.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled grade tier, end-use industry, and regional regulatory cluster segmentation dimensions. CAGRs derived from regression analysis of historical price-volume relationships and forward capacity expansion announcements. Forecast inputs incorporated thiophene feedstock cost trajectories and evolving pharmacopeial monograph specifications.
Forecasts assume regulatory continuity in REACH, EPA TSCA, and FDA API guidance regimes; material policy shifts would require re-modeling around alternative compliance pathways. Practitioners should keep alternative scenarios live as ICH Q3D elemental impurity thresholds and green chemistry incentive programs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Penicillin Intermediate Market