
 Inorganic Pigments Market | 2026-2036
Inorganic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Pigments Market Analysis
Specialty chemical distribution is tilting toward direct supply agreements between pigment producers and large coatings formulators. Tronox Limited leverages vertical integration from mineral sands to chloride-process TiO2, sustaining cost advantages across multiple end uses. The Chemours Company anchors its position through technology leadership in titanium dioxide manufacturing. Venator competes aggressively in iron oxide pigments, dominating colorant supply for construction materials across European markets.
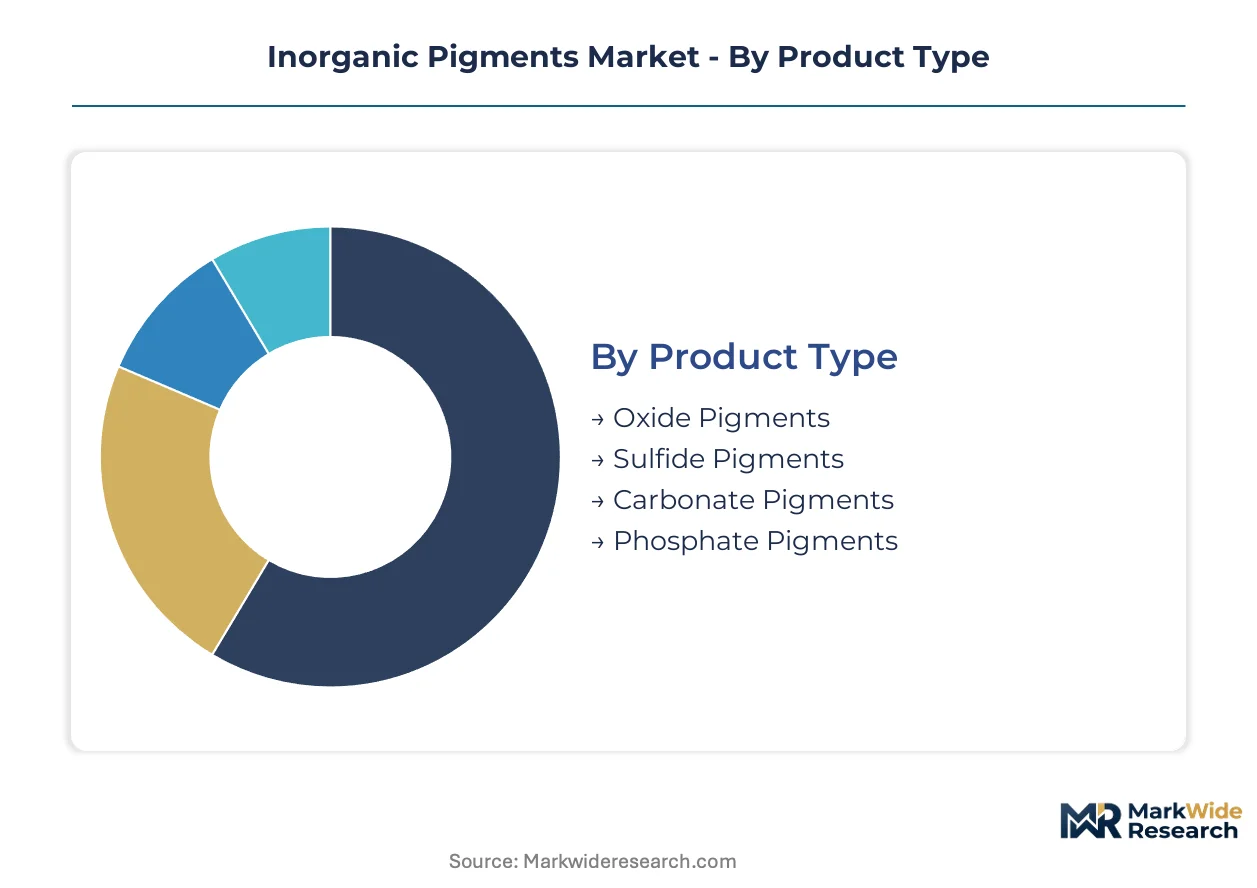
Inorganic pigments are synthetic or naturally derived colorants composed of metal oxides, sulfides, carbonates, or phosphates that deliver thermal stability, UV resistance, and opacity in matrices ranging from 0.1 to 50 micrometers particle size; they primarily serve to impart durable color in coatings, plastics, and building materials exposed to harsh environmental conditions. Oxide pigments, led by titanium dioxide and iron oxide families, command the largest value share due to their ubiquity in architectural and industrial coatings. Sulfide pigments, particularly cadmium and zinc sulfide variants, represent a faster-growing niche where reformulation away from restricted substances creates margin pools for compliant alternatives. Carbonate and phosphate pigments occupy specialized positions in cosmetics and food-contact applications where migration resistance and purity standards differentiate suppliers.
EPA oversight of heavy-metal emissions from pigment manufacturing shapes facility siting and abatement investment in the United States, while REACH registration requirements in Europe constrain market access for non-compliant producers. FDA color additive regulations govern cosmetic and food-contact applications, bifurcating certification pathways between technical and consumer-grade pigments. Stakeholders must monitor evolving MEE enforcement in China and the EU Green Deal's chemical sustainability criteria to anticipate raw material cost shifts and qualification barriers.
Market Dynamics
REACH and RoHS compliance in Europe is forcing cadmium-free reformulation across coatings and plastics supply chains, redirecting R&D budgets toward compliant sulfide alternatives while tightening heavy-metal content thresholds.
Growth Catalysts
- Construction Materials Demand:Iron oxide pigments are experiencing sustained pull from concrete and mortar applications in China, where infrastructure spending and residential development absorb substantial colorant volumes.
- REACH Registration Requirements:ECHA compliance mandates are accelerating consolidation among European pigment formulators, as smaller producers exit rather than absorb registration costs for legacy chemistries.
- Chloride-Process TiO2:Superior opacity and cleaner environmental profile versus sulfate-route material is concentrating investment in chloride technology, particularly for automotive OEM coatings specifications.
Market Restraints
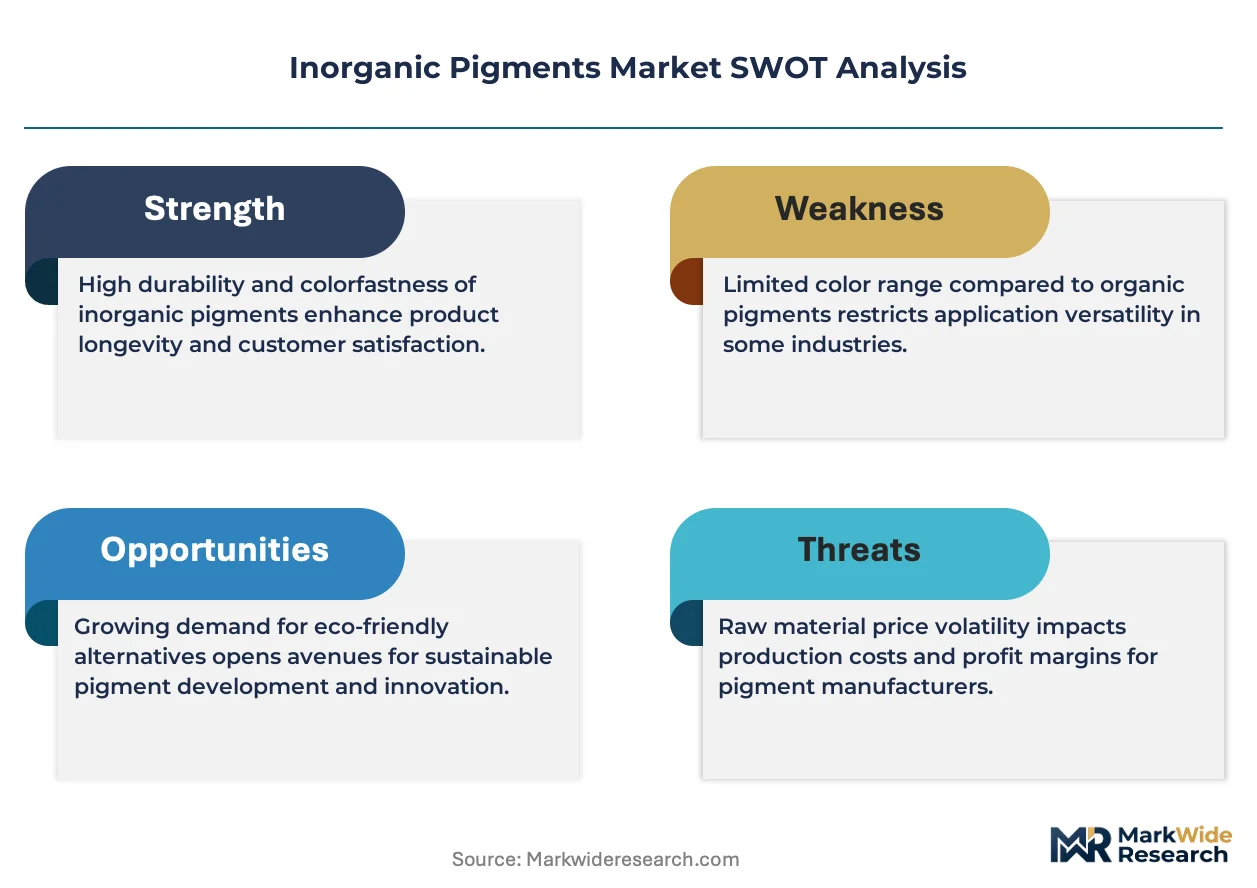
- Mineral Sands Concentration:Titanium feedstock supply concentrates in Australian and South African mining operations, exposing chloride-process producers to geopolitical and shipping disruption risks.
- Cadmium Substitution Costs:Reformulating from cadmium sulfide to bismuth vanadate or rare-earth alternatives increases raw material expenditure by 40-60% for high-chroma yellow and orange applications.
- EPA Emission Controls:Heavy-metal abatement requirements at US manufacturing facilities elevate capital intensity for greenfield pigment plants versus Asian competitors.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for specialty chemicals manufacturing are attracting pigment producers to establish local compounding operations serving domestic plastics converters.
- UV-Resistant Architectural Coatings:Climate-adaptive building materials in Middle Eastern construction markets are creating specification pull for iron oxide pigments with enhanced weathering performance.
- Direct Supply Agreements:Large coatings formulators are bypassing distributors to negotiate volume contracts with pigment producers, compressing margin pools for intermediate traders.
Industry Challenges
- Color Matching Expertise:Formulation chemists with cross-pigment-system competency are scarce, particularly for matching legacy cadmium shades with compliant alternatives across diverse resin matrices.
- REACH Data Sharing:SIEF consortium negotiations for substance registration create administrative bottlenecks, delaying market access for novel pigment chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Pigments Market |
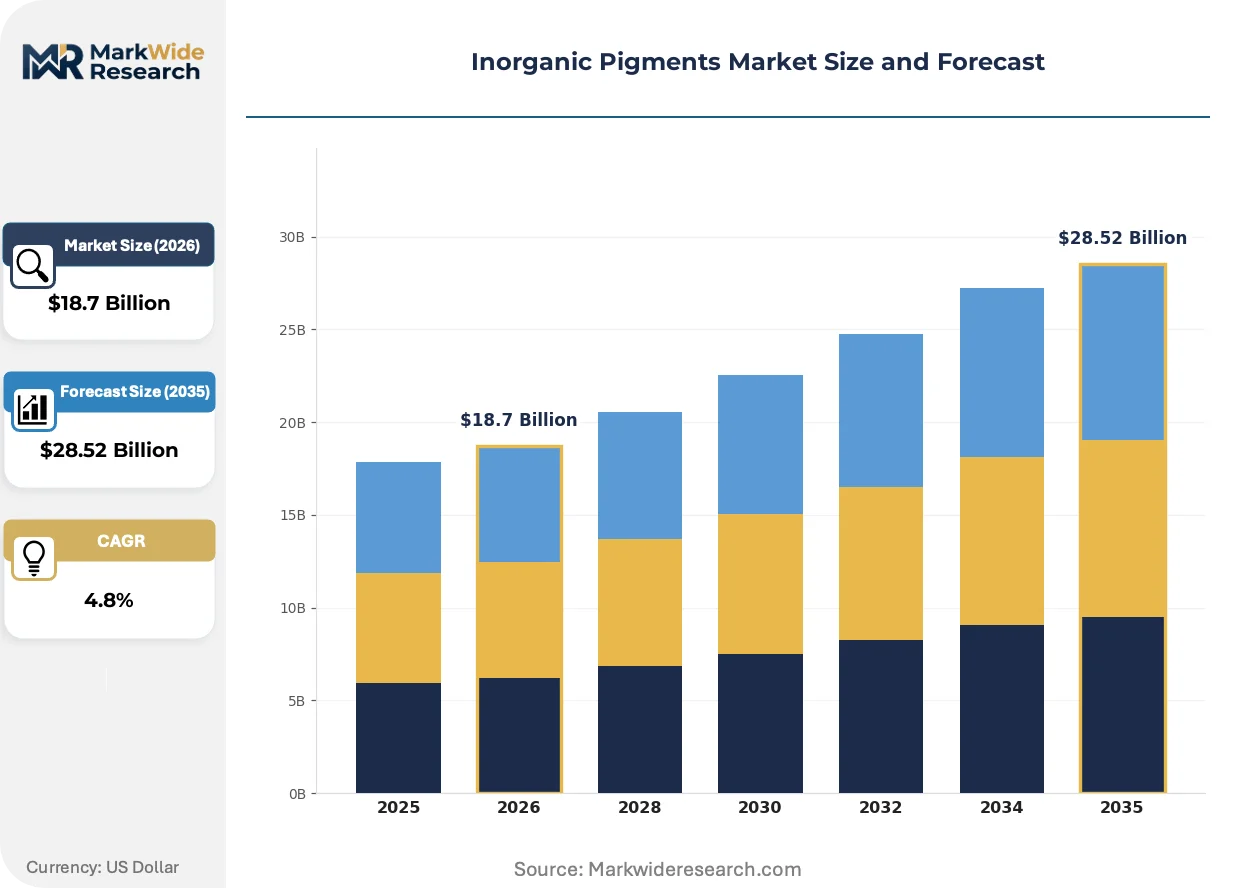
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxide Pigments, Sulfide Pigments, Carbonate Pigments, Phosphate Pigments End Use Industry: Coatings, Plastics, Construction, Cosmetics Application: Industrial Coatings, Automotive Coatings, Decorative Coatings, Printing Inks Form: Powder, Granule, Liquid, Paste |
| Companies Covered | Tronox Limited, The Chemours Company, Venator, LANXESS, Kronos Worldwide, Inc., Ferro Corporation, Clariant, INEOS Pigments, Alabama Pigments Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Pigments Market Emerging Trajectories
Digital color specification tools and predictive formulation software are compressing development cycles, while regulatory pressure on heavy-metal content accelerates substitution chemistry investment.
Computational pigment design is virtualizing traditional trial-and-error formulation. Coatings manufacturers in automotive OEM supply chains are adopting AI-driven color matching platforms that predict opacity and dispersion performance from molecular structure data. This technology is virtualizing the role of physical laboratory testing, reducing development timelines from months to weeks while compressing R&D headcount requirements at mid-tier formulators.
EU Green Deal chemical sustainability criteria are tightening permissible carbon intensity thresholds for imported pigments. ECHA is developing lifecycle assessment frameworks that will differentiate domestic European production from imports based on embedded emissions. Automotive coatings specifications in Germany and France are already beginning to reference these criteria, pressuring suppliers to document supply chain carbon footprints.
Specification authority is migrating from brand owners to raw material suppliers in high-performance segments. Pigment producers with captive technical service capabilities are capturing direct relationships with tier-one coatings formulators, displacing distributor-led technical support models. This pattern is most visible in China, where domestic titanium dioxide producers are building application laboratories to serve regional automotive and industrial coatings customers.
Inorganic Pigments Market Segmentation
Segmentation in inorganic pigments reveals distinct procurement rhythms across product chemistries and end-use specifications. Coatings formulators cycle through inventory faster than construction material producers, while specialty grades in cosmetics and automotive applications command extended qualification timelines.
Product Type:
Oxide pigments turn inventory fastest through architectural coatings channels, whereas phosphate pigments move slowest due to food-contact and cosmetic certification requirements.
- Oxide Pigments:Titanium dioxide and iron oxide families dominate procurement volumes across coatings and plastics matrices. Chloride-process TiO2 from Australian mineral sands feeds automotive OEM specifications in Germany and Japan, while sulfate-route material serves cost-sensitive construction applications in India and Southeast Asia.
- Sulfide Pigments:Cadmium and zinc sulfide variants deliver high-chroma performance in engineering plastics and specialty coatings. REACH and RoHS restrictions in Europe are accelerating substitution toward bismuth vanadate and rare-earth alternatives, compressing traditional sulfide demand in consumer-facing applications.
- Carbonate Pigments:Calcium carbonate-based colorants serve paper coatings and filler applications where brightness and dispersion control matter.
- Phosphate Pigments:Complex phosphate chemistries occupy corrosion-resistant and food-contact niches requiring migration resistance certification.
Oxide pigments anchor the volume base while sulfide pigments gain share at the steepest rate among compliant reformulation alternatives.
End Use Industry:
Margin concentration follows application complexity, with cosmetics and automotive coatings commanding premium pricing over commodity construction grades.
- Coatings:Architectural, industrial, and automotive coatings absorb the majority of titanium dioxide and iron oxide volumes. Specifications from German automotive OEMs increasingly reference EU Green Deal carbon intensity criteria, favoring chloride-process material with documented supply chain footprints.
- Plastics:Masterbatch compounders in China and India consume substantial iron oxide and sulfide pigment volumes for packaging and consumer durables. BIS certification requirements in India are tightening heavy-metal thresholds, redirecting formulation toward compliant alternatives.
- Construction:Concrete coloration and mortar applications in China absorb significant iron oxide volumes through direct supply arrangements with domestic pigment producers.
- Cosmetics:FDA color additive regulations and EU cosmetic ingredient restrictions govern titanium dioxide and iron oxide usage in personal care formulations.
Construction anchors the volume base while cosmetics gains share at the steepest rate through premium-grade specialty pigment demand.
Application:
Specification authority concentrates in automotive OEM channels, where tier-one coatings formulators negotiate directly with pigment producers.
- Industrial Coatings:Protective and marine coatings require weathering-resistant iron oxide and titanium dioxide grades. MEE enforcement in China is elevating environmental compliance costs for sulfate-process TiO2 facilities serving this segment.
- Automotive Coatings:OEM specifications demand superior opacity and dispersion performance from chloride-process TiO2. KBA type-approval requirements in Germany and equivalent Japanese certifications constrain qualified supplier pools.
- Decorative Coatings:Architectural paint producers prioritize cost efficiency through sulfate-route material and standardized iron oxide grades.
- Printing Inks:Publication and packaging ink formulators require fine particle size pigments with controlled rheology characteristics.
Decorative coatings anchors the volume base while automotive coatings gains share at the steepest rate through specification tightening.
Form:
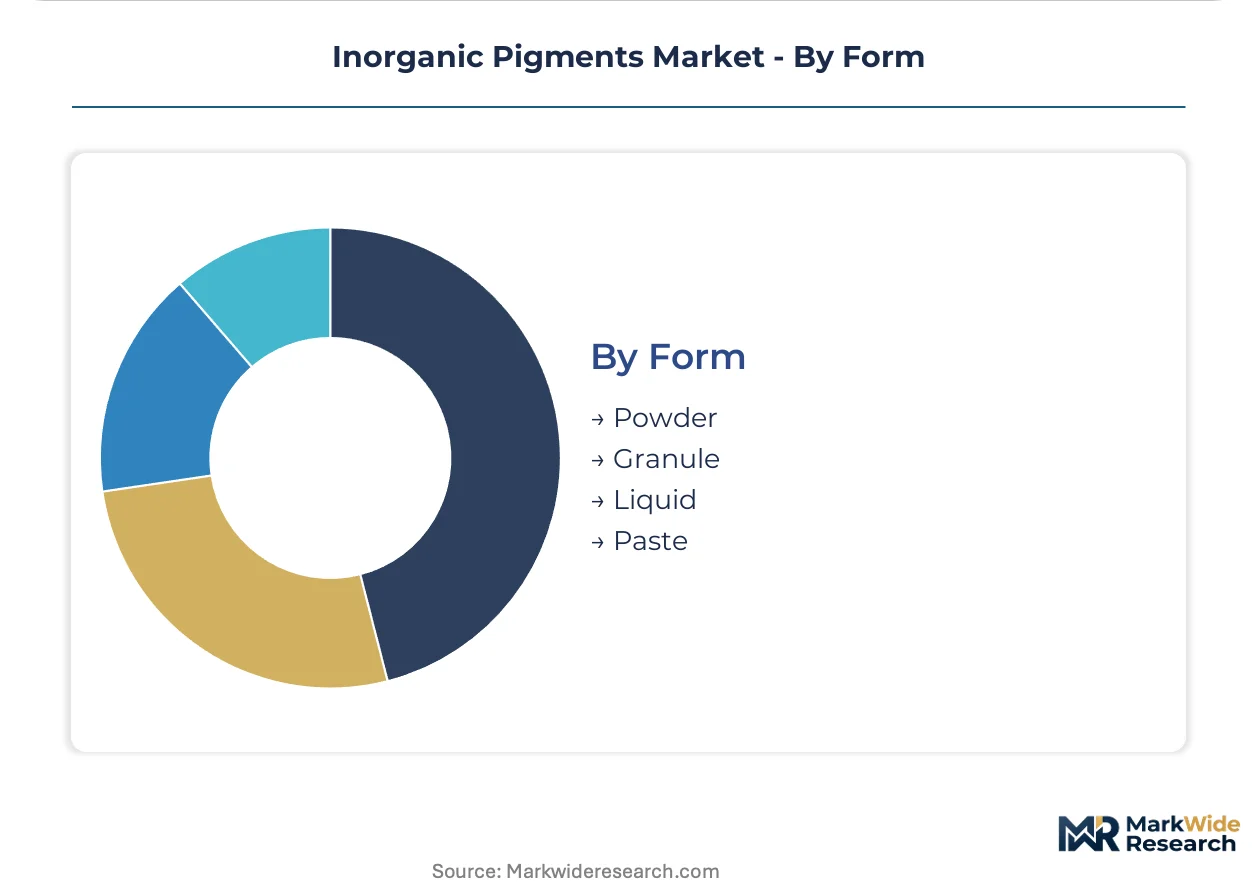
Processing economics favor powder and granule forms for high-volume applications, while liquid and paste formats reduce dust exposure and dispersion labor in specialized operations.
- Powder:Dry pigment powders dominate titanium dioxide and iron oxide shipments to coatings and plastics compounders. Bulk handling systems at major formulator facilities favor powder logistics for cost efficiency.
- Granule:Low-dust granulated iron oxides serve concrete and mortar producers where workplace exposure limits are tightening.
- Liquid:Predispersed aqueous slurries reduce milling requirements for waterborne coatings manufacturers.
- Paste:Solvent-based and universal pastes target small-batch formulators lacking dispersion equipment.
Powder anchors the volume base while granule gains share at the steepest rate through construction sector safety compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and tightened environmental enforcement in China are redirecting investment flows across the inorganic pigments supply base. REACH registration costs continue to reshape European competitive dynamics. Chloride-process capacity expansion concentrates in mineral sands-adjacent geographies.
China
Construction activity and domestic plastics production absorb substantial titanium dioxide and iron oxide volumes. MEE enforcement elevates environmental compliance costs for sulfate-process facilities serving industrial coatings segments. Jiangsu and Shandong provinces host concentrated pigment manufacturing clusters where producers are upgrading abatement systems.
Germany
Automotive OEM specifications increasingly reference EU Green Deal carbon intensity criteria for coatings inputs. KBA type-approval requirements constrain qualified supplier pools for chloride-process TiO2. The Ruhr industrial region maintains specialized iron oxide production serving continental construction material markets.
United States
EPA heavy-metal emission controls shape facility siting and abatement investment decisions for greenfield pigment plants. Coatings formulators in automotive and industrial sectors expand procurement of high-performance oxide pigments. Gulf Coast chemical corridors attract titanium feedstock processing investments leveraging port logistics.
India
The PLI scheme for specialty chemicals manufacturing attracts pigment producers establishing local compounding operations. BIS certification requirements tighten heavy-metal thresholds in packaging and consumer durables. Gujarat and Maharashtra industrial zones concentrate new masterbatch compounding capacity serving domestic plastics converters.
Japan
Automotive coatings specifications demand superior opacity and dispersion performance from qualified pigment suppliers. METI industrial standards govern chemical sustainability reporting for imported colorant materials. The Nagoya industrial corridor maintains specialized technical service capabilities for tier-one coatings formulators.
Inorganic Pigments Market Vendor Landscape
On the supply side, the industry is consolidating around mineral sands-to-pigment value chain control and technology-differentiated manufacturing positions. Three strategic archetypes dominate: vertically integrated titanium feedstock operators, specialty iron oxide colorant specialists, and regional sulfate-process commodity producers. Competitive moves concentrate on backward integration into mineral sands supply and direct supply agreement negotiations with large coatings formulators.
Among North American-based operators, Tronox Limited and The Chemours Company exemplify the integrated archetype with captive mineral sands positions. Venator occupies a specialist position within European iron oxide colorants. These three companies represent distinct strategic postures: feedstock security, technology leadership, and regional colorant dominance respectively.
| Leading Market Players |
|---|
| Tronox Limited |
| The Chemours Company |
| Venator |
| LANXESS |
| Kronos Worldwide, Inc. |
| Ferro Corporation |
| Clariant |
| INEOS Pigments |
| Alabama Pigments Company |
| Others |
Supply Flow & Price Mechanics
Mineral sands supply concentration in Australian and South African mining operations determines both the premium commanded by chloride-process TiO2 over sulfate-route material and the geographic clustering of pigment manufacturing capacity near deepwater ports.
Pricing Analysis
Certification level (REACH/FDA-grade) creates the primary spread between technical and consumer-grade pigment tiers, with automotive OEM specifications commanding substantial premiums over commodity construction grades. Three-tier pricing structure across premium chloride-process, standard sulfate-route, and economy blended grades reflects opacity performance and carbon footprint documentation. Cost compression in standard grades is intensifying because Chinese sulfate-process capacity expansion outpaces demand absorption. Construction material producers exhibit highest price sensitivity, while automotive coatings formulators prioritize performance consistency over unit cost.
Supply Chain Analysis
Export control restrictions on mineral sands processing technology limit capacity expansion outside established producer geographies, constraining supply diversification. Titanium feedstock draws from Australian ilmenite and South African rutile operations, with chloride-process TiO2 production anchored in Mississippi and Western Australia. Single-source vulnerability concentrates in mineral sands beneficiation, where three mining groups control the majority of rutile supply. Distribution runs through direct supply agreements between pigment producers and large coatings formulators, compressing distributor margins and intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inorganic pigments market tracks construction and automotive production cycles, with infrastructure stimulus programs in China and India providing near-term demand support through concrete coloration and industrial coatings procurement.
For Market Incumbents: Build captive mineral sands positions to secure feedstock cost advantages against sulfate-process competitors. Consolidate iron oxide colorant supply relationships with European construction material producers before REACH registration deadlines eliminate smaller formulators. Defensive moves should concentrate on chloride-process capacity maintenance and application laboratory expansion in Chinese automotive coatings corridors. For New Entrants and Emerging Players: Establish a beachhead in Indian masterbatch compounding through PLI-linked local production, bypassing import duties and BIS certification complexity for packaging pigment supply. Target compliant sulfide alternatives for cadmium substitution in high-chroma engineering plastics, where formulation expertise scarcity protects margin pools. Go-to-market positioning should emphasize technical service capabilities for color matching legacy shades. For Investors and Strategic Acquirers: EU Green Deal chemical sustainability criteria reshape the acquisition landscape toward pigment producers with documented supply chain carbon footprints and European manufacturing assets. Long-term viability favors specialists with captive technical service capabilities serving tier-one coatings formulators. Watch ECHA lifecycle assessment framework implementation as the inflection signal for import competitiveness versus domestic European production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sands | Captive rutile and ilmenite supply secures chloride-process cost advantages against sulfate-route competitors. |
| REACH-Compliant Sulfide Alternative Development | Bismuth vanadate and rare-earth yellow chemistry captures reformulation budgets from restricted cadmium pigments. |
| Direct Supply Agreement Expansion | Volume contracts with automotive OEM coatings formulators displace distributor intermediation and capture specification authority. |
| Application Laboratory Investment | Technical service capabilities in Chinese automotive corridors build relationships with tier-one formulators. |
| Carbon Footprint Documentation Systems | Lifecycle assessment data satisfies EU Green Deal criteria for German and French automotive coatings specifications. |
Methodological Framework
The analysis maps oxide, sulfide, carbonate, and phosphate pigment chemistries, each validated through procurement directors at coatings formulators, technical R&D managers at pigment producers, and distribution channel partners. Primary interviews with plant managers at sulfate and chloride-process facilities combined with secondary validation through ECHA registration databases, SEC 10-K filings, and Cefic industry statistics enabled bottom-up and top-down triangulation across the value chain.
Assumptions held fixed include REACH and RoHS regulatory frameworks, mineral sands supply geography, and chloride-process technology diffusion rates, while demand drivers and carbon intensity criteria varied across scenarios. Segmentation dimensions modeled encompass pigment chemistry family, end-use industry, process route, and regional production hub. CAGRs derived from production capacity utilization trends, inventory cycle analysis, and substitution elasticity estimates for compliant alternatives.
Sensitivities concentrate around MEE enforcement intensity in China, EU Green Deal implementation timelines, and mineral sands supply disruption scenarios. Forecasts reflect these documented assumptions; material shifts in heavy-metal regulatory thresholds or titanium feedstock trade flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Micronized Color Powder Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market