
 Carmoisine Market | 2026-2036
Carmoisine Market Size, Share, and Industry Trends Forecast 2026-2036
Carmoisine Market Outlook
Multi-source procurement among food colorant buyers is shifting as supply-chain resilience replaces cost-minimization logic. Dynemic Products Ltd. anchors Indian manufacturing capacity for azo-based food dyes. BASF leverages its global pigment infrastructure to serve multinational food processors with certified colorant grades. Sensient Technologies specializes in application-specific formulations that reduce batch-to-batch variation for confectionery clients.
Carmoisine, an azo dye designated E122, delivers a red-to-maroon hue through a sulfonated naphthalene-azo structure with maximum absorption near 516 nm; food processors deploy it in beverages, desserts, and meat substitutes where heat-stable coloration proves essential. Powder formats dominate volume throughput owing to extended shelf stability and lower logistics cost per color unit. Liquid carmoisine captures premium positioning in automated dosing systems at beverage bottling lines. Pharmaceutical and nutraceutical applications represent the fastest-expanding end-user channel as tablet coating specifications tighten.
FDA color additive regulations and EFSA re-evaluations of azo dye safety profiles constrain permissible daily exposure thresholds, forcing reformulation investments across supplier networks. India's FSSAI aligns with Codex Alimentarius standards while imposing additional labeling requirements that filter non-compliant imports. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure dual-certification pathways before compliance deadlines crystallize.
Market Dynamics
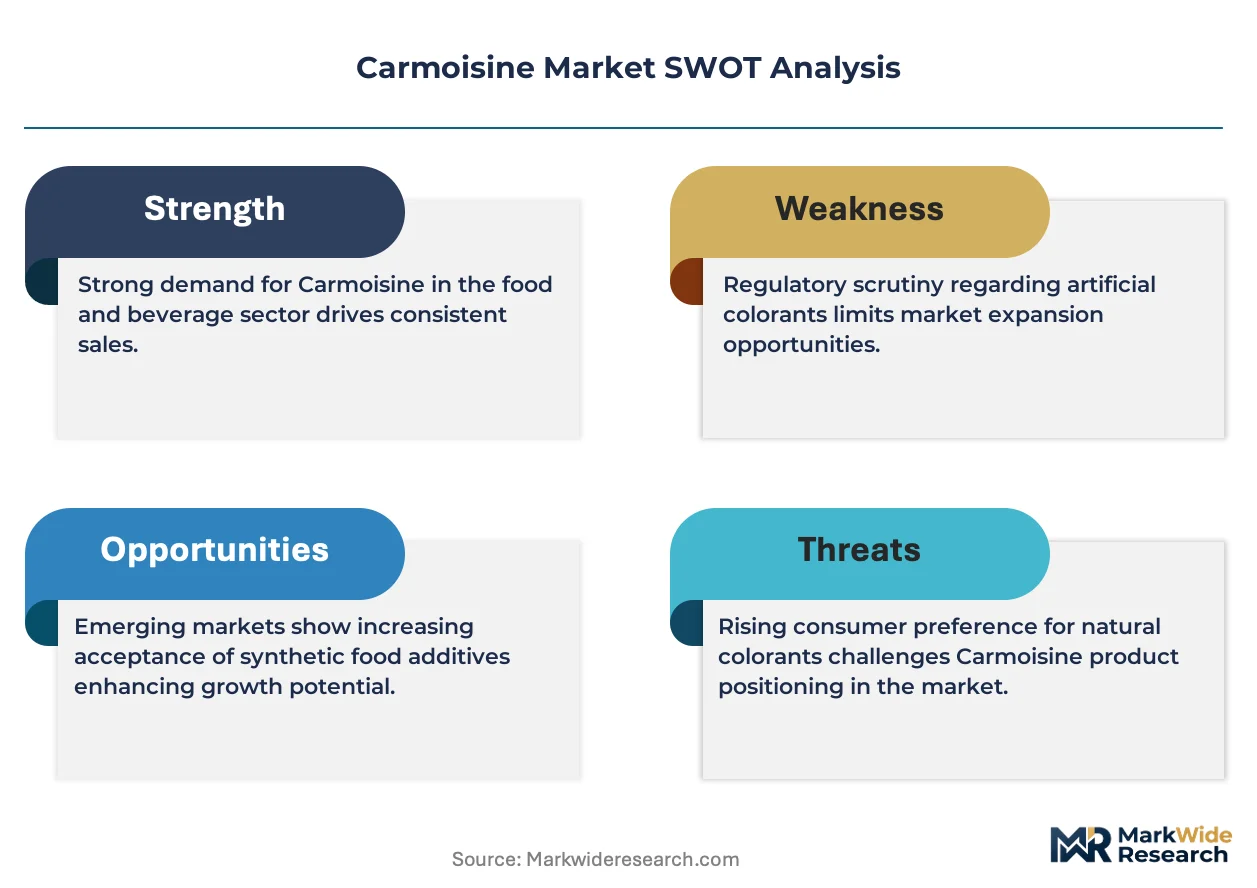
Regulatory divergence between EFSA's azo dye re-evaluations and India's FSSAI labeling mandates is fragmenting formulation standards, forcing suppliers to maintain parallel certification pathways for the same product.
Growth Catalysts
- Processed food expansion in India:Domestic confectionery and beverage manufacturers scale production lines, driving volume demand for heat-stable colorants that withstand pasteurization cycles.
- REACH compliance investments:European suppliers who achieve full registration dossiers for sulfonated azo derivatives capture preferential access to multinational food processor supply chains.
- Pharmaceutical coating specifications:Tablet film-coating protocols now require certified colorant grades with documented heavy metal limits, opening a technical-specification channel distinct from commodity food-grade sales.
Market Restraints
- Naphthalene feedstock volatility:Petrochemical-derived intermediates for azo synthesis face price swings tied to crude oil benchmarks, compressing margin predictability for dye manufacturers.
- EFSA exposure threshold reductions:Pending re-evaluations of acceptable daily intake for synthetic reds threaten reformulation costs across European confectionery applications.
- Natural colorant substitution:Beetroot-derived betalains and anthocyanin extracts displace carmoisine in premium beverage segments where clean-label positioning commands shelf price premiums.
Strategic Opportunities
- Automated dosing system integration:Liquid carmoisine formulations tailored for continuous-flow beverage bottling lines capture value from capital-intensive plant upgrades in Brazil and Mexico.
- Nutraceutical gummy applications:Vitamin-enriched chewable formats require pH-stable coloration that survives acidic fruit matrices, creating a specification-driven segment with technical barriers to commodity suppliers.
- FSSAI export certification alignment:Indian suppliers who pre-qualify for Codex Alimentarius-equivalent documentation streamline access to Middle Eastern markets with converging import standards.
Industry Challenges
- Analytical chemist scarcity:Batch-to-batch spectrophotometric consistency testing requires specialized personnel familiar with azo dye purity protocols, creating hiring bottlenecks at mid-scale manufacturers.
- Dual-certification inventory management:Maintaining separate stockpiles for REACH-registered European grades versus FSSAI-compliant Indian grades strains working capital and warehouse segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carmoisine Market |
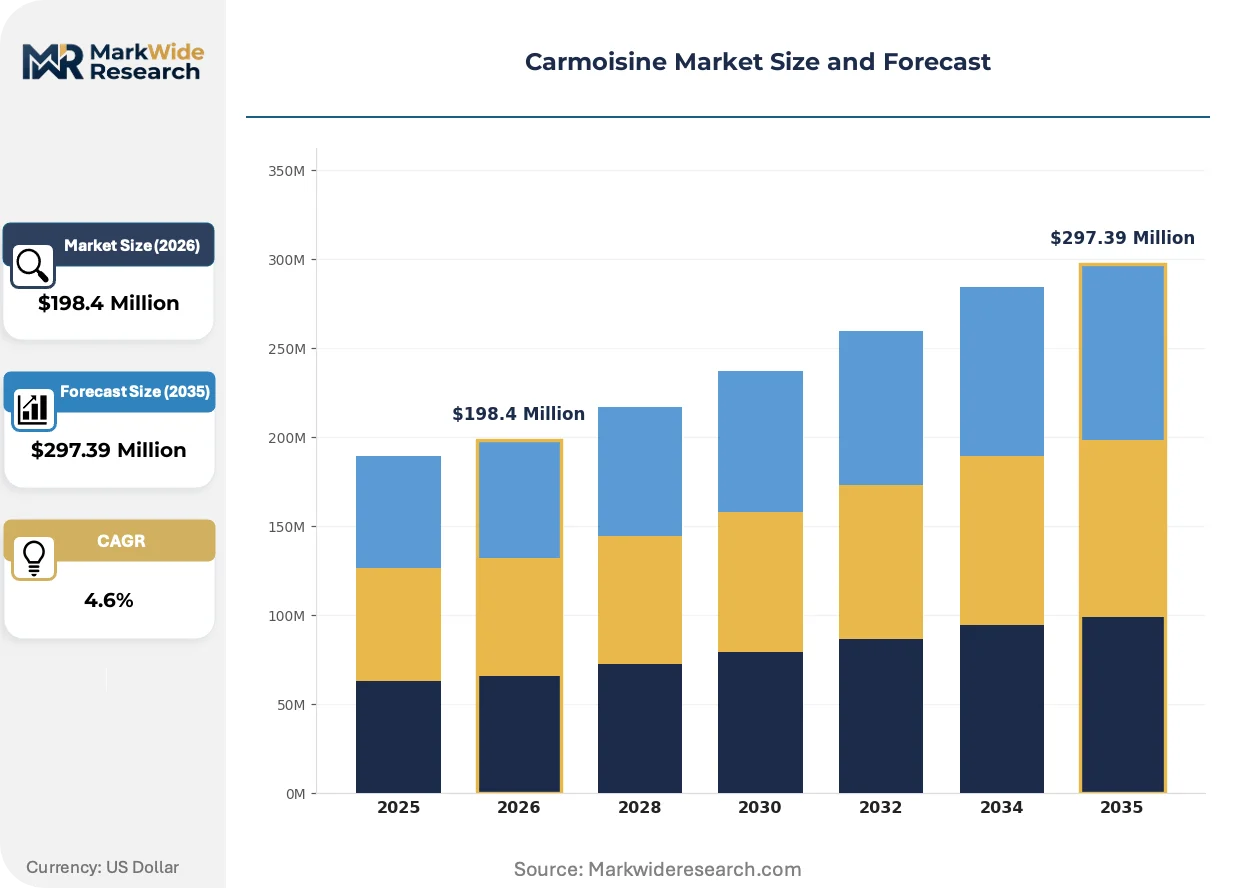
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $297.39 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Capsules End User: Food & Beverage, Pharmaceuticals, Cosmetics, Dietary Supplements Application: Food Coloring, Cosmetic Formulation, Nutraceuticals, Textile Dyes Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Matrix Pharma-Chem (I) Pvt. Ltd., Ajanta Chemical Industries, Dynemic Products Ltd., Neelikon Food Colours & Chemicals Ltd., Vinayak Ingredients (India) Pvt. Ltd., National Foods (Pvt) Ltd., BASF, Chr. Hansen, Sensient Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carmoisine Market Strategic Shifts
Microencapsulation technologies and regulatory data-sharing platforms are compressing the gap between commodity dye production and application-specific performance guarantees.
Spray-dried carmoisine microcapsules with modified starch shells is unifying heat stability and controlled-release properties in a single powder format. Confectionery manufacturers in Turkey and Thailand adopt these grades for hard-boiled candy applications where color bleeding previously limited formulation options. The technology is unifying what were previously separate procurement streams for base dye and protective encapsulant.
EFSA's systematic re-evaluation program for food additives is mandating new toxicological data packages for azo dyes first approved decades ago. European suppliers face multi-year studies to defend existing authorizations, while Indian exporters must synchronize dossier updates to maintain parallel market access. Pharmaceutical tablet coating divisions are responding by accelerating qualification of alternative certified grades before potential suspension dates.
Direct-procurement contracts between food processors and specialized dye houses are displacing traditional distributor networks in high-volume beverage applications. Major bottling groups in South Africa and Indonesia now negotiate annual tonnage commitments with Indian manufacturers, bypassing regional chemical traders. This concentration of purchasing authority is most visible in carbonated soft drink segments where color consistency across multi-plant networks outweighs spot-price flexibility.
Carmoisine Market Segmentation
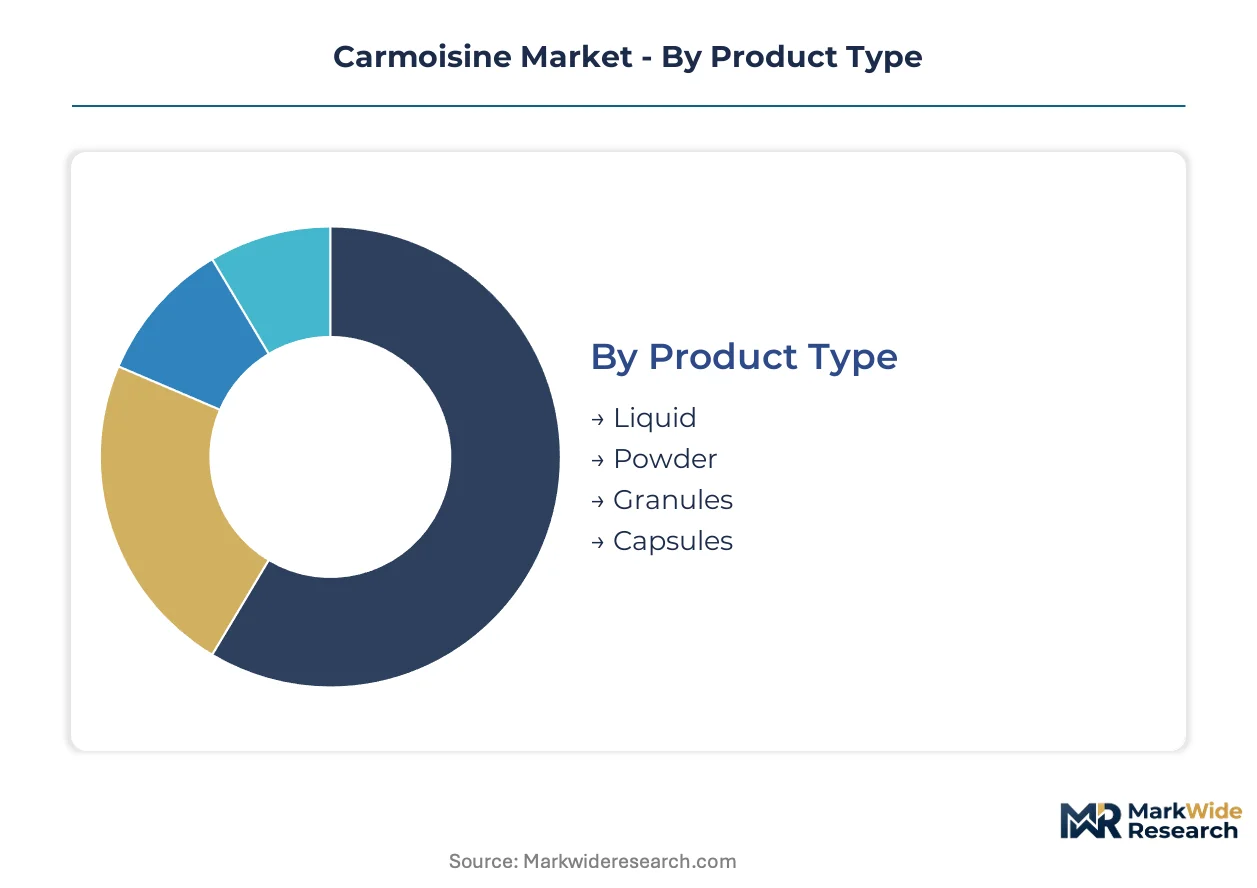
Segmentation in the carmoisine market reflects divergent technical requirements across regulatory environments and end-use specifications. Formulation format, certification grade, and application method each determine procurement patterns and margin structures for suppliers.
Product Type:
Sulfonation degree and moisture content differentiate physical formats, with each specification tier serving distinct dosing infrastructure and shelf-life requirements.
- Liquid:Pre-dissolved aqueous solutions with standardized dye content enable direct injection into continuous-flow beverage bottling lines. Brazilian and Mexican carbonated soft drink manufacturers specify liquid grades for automated dosing systems where batch-to-batch consistency outweighs per-unit cost premiums.
- Powder:Spray-dried crystals with modified starch carriers deliver extended ambient stability and lower logistics cost per color unit. Indian confectionery exporters favor powder formats for hard-boiled candy applications requiring heat-stable coloration through pasteurization cycles.
- Granules:Agglomerated particles reduce dust exposure during handling at mid-scale pharmaceutical tablet coating facilities.
- Capsules:Unit-dosed gelatin shells serve nutraceutical gummy manufacturers with limited on-site weighing infrastructure.
Powder leads on scale; liquid leads on momentum.
End User:
Certification stringency and batch documentation requirements fragment demand across customer categories with divergent compliance thresholds.
- Food & Beverage:Heat-stable coloration for pasteurized beverages and confectionery dominates volume throughput. FSSAI-aligned Indian manufacturers supply domestic processed food expansion while pursuing Codex-equivalent documentation for Middle Eastern export access.
- Pharmaceuticals:Tablet film-coating protocols now mandate heavy metal documentation and spectrophotometric purity certificates. CDSCO-registered Indian suppliers capture this specification-driven channel distinct from commodity food-grade sales.
- Cosmetics:ECHA REACH registration dossiers for sulfonated azo derivatives open preferential access to EU personal care formulators.
- Dietary Supplements:Vitamin-enriched chewable formats require pH-stable coloration surviving acidic fruit matrices.
Food & Beverage anchors volume; Pharmaceuticals climbs the fastest.
Application:
Performance specifications vary by matrix compatibility and processing conditions, with each application imposing distinct stability requirements.
- Food Coloring:Maximum absorption near 516 nm delivers red-to-maroon hues in desserts, meat substitutes, and beverages where thermal processing demands sulfonated naphthalene-azo structures.
- Cosmetic Formulation:EFSA exposure threshold re-evaluations for synthetic reds threaten reformulation costs across European lip and eye product segments.
- Nutraceuticals:Microencapsulated spray-dried grades with modified starch shells unify heat stability and controlled-release for gummy applications.
- Textile Dyes:Lower-purity industrial grades serve synthetic fiber coloration with reduced certification overhead.
Food Coloring dominates procurement tonnage; Nutraceuticals gains share fastest.
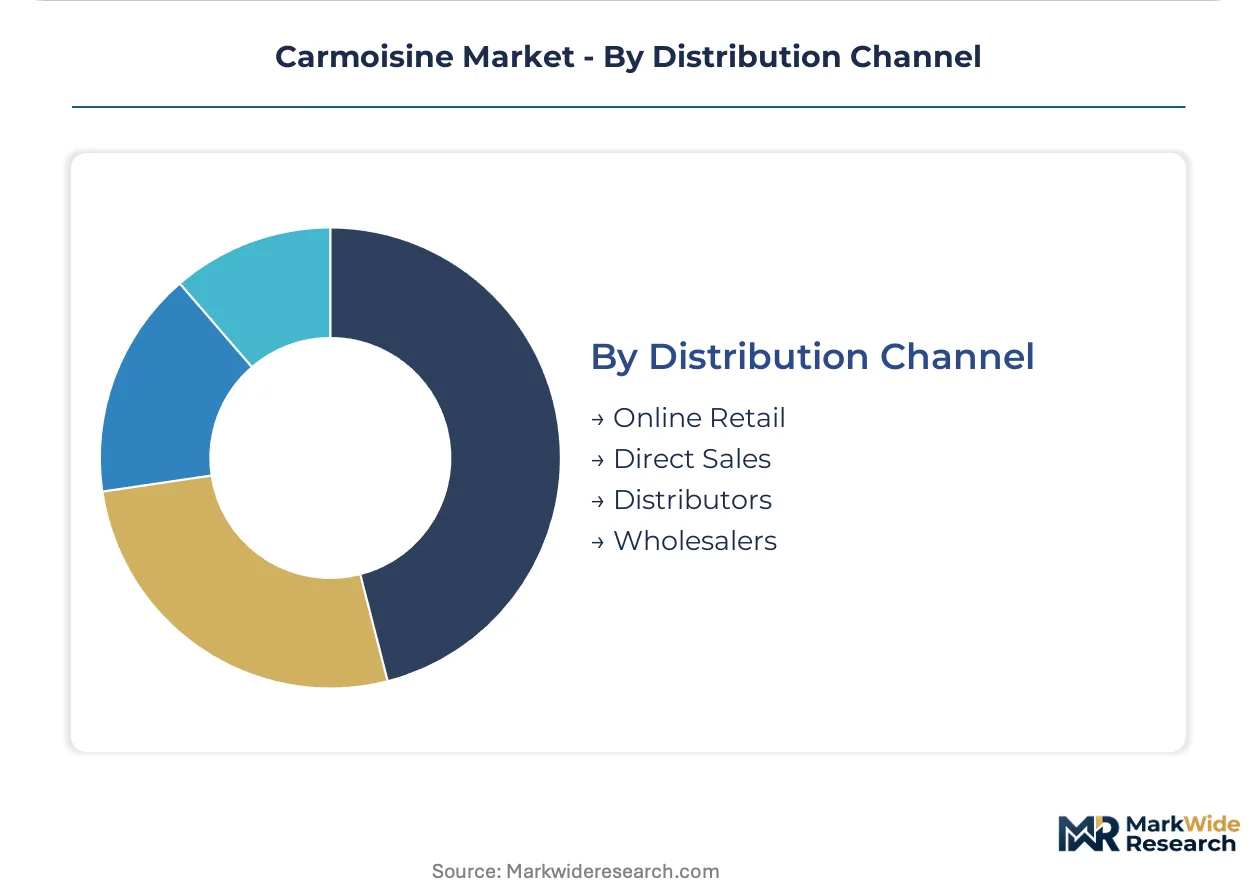
Distribution Channel:
Channel selection reflects order scale, documentation requirements, and geographic proximity to manufacturing clusters.
- Direct Sales:Annual tonnage commitments between major bottling groups and Indian manufacturers bypass regional chemical traders. South African and Indonesian carbonated soft drink networks concentrate purchasing authority here.
- Distributors:Regional chemical traders serve mid-scale confectionery and pharmaceutical coating facilities requiring smaller lot sizes with local inventory.
- Online Retail:E-commerce platforms capture artisanal food producers and research laboratories with low-volume, specification-flexible requirements.
- Wholesalers:Bulk aggregation points supply textile dye houses and industrial processors with commodity-grade material.
Direct Sales captures premium volume; Online Retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ankleshwar and Ahmedabad in Gujarat anchor global carmoisine manufacturing capacity, with Indian sulfonated azo dye clusters supplying processed food expansion across emerging economies. Regulatory divergence between EFSA exposure thresholds and FSSAI labeling mandates forces suppliers to maintain parallel certification pathways.
India
Domestic confectionery and beverage manufacturers scale production lines, driving volume demand for heat-stable colorants. FSSAI aligns with Codex Alimentarius while imposing additional labeling requirements that filter non-compliant imports. Ankleshwar chemical estates concentrate azo dye synthesis infrastructure serving pharmaceutical coating and food-grade applications.
Germany
REACH-registered European suppliers capture preferential access to multinational food processor supply chains. ECHA mandates full registration dossiers for sulfonated azo derivatives, creating compliance barriers for non-European exporters. Ludwigshafen and Leverkusen host pigment infrastructure serving certified colorant grades with documented heavy metal limits.
United States
FDA color additive standards reshape formulation requirements as beverage bottlers upgrade automated dosing systems. Evolving exposure threshold evaluations for synthetic reds threaten reformulation costs across confectionery applications. New Jersey and Delaware chemical corridors concentrate pharmaceutical coating divisions accelerating qualification of alternative certified grades.
Brazil
Carbonated soft drink manufacturers specify liquid carmoisine grades for continuous-flow bottling lines where batch consistency outweighs per-unit premiums. ANVISA import documentation requirements favor suppliers with pre-qualified Codex-equivalent certification. São Paulo state concentrates purchasing authority as major bottling groups negotiate direct annual tonnage commitments.
United Arab Emirates
Middle Eastern import standards converge with Codex Alimentarius, streamlining access for FSSAI-aligned Indian exporters. MOHAP food additive regulations prioritize documentation of heavy metal limits and spectrophotometric purity. Dubai and Sharjah free zones aggregate regional distribution for pharmaceutical and nutraceutical applications.
Carmoisine Market Competitive Environment
Global majors compete with regional champions across certification-grade supply chains, with European pigment houses and Indian azo dye specialists occupying distinct tier positions. The vendor base stratifies between REACH-registered multinationals serving pharmaceutical specifications and FSSAI-compliant domestic producers capturing processed food volume. Three archetypes dominate: global pigment infrastructure operators, India-based azo dye manufacturers, and application-specific formulation specialists. Capacity expansion in Gujarat and strategic partnerships for dual-certification dossiers represent the primary competitive vectors.
Among India-based manufacturers, Dynemic Products Ltd., Matrix Pharma-Chem (I) Pvt. Ltd., and Ajanta Chemical Industries exemplify the regional champion archetype, occupying positions within FSSAI-compliant supply chains for domestic processed food expansion and Middle Eastern export access. BASF and Sensient Technologies represent global pigment infrastructure operators with REACH-registered European grades serving multinational pharmaceutical coating protocols. These five entities collectively illustrate the market's bifurcation between specification-driven premium channels and commodity-scale food-grade throughput.
| Leading Market Players |
|---|
| Matrix Pharma-Chem (I) Pvt. Ltd. |
| Ajanta Chemical Industries |
| Dynemic Products Ltd. |
| Neelikon Food Colours & Chemicals Ltd. |
| Vinayak Ingredients (India) Pvt. Ltd. |
| National Foods (Pvt) Ltd. |
| BASF |
| Chr. Hansen |
| Sensient Technologies |
| Others |
Value Chain & Pricing Dynamics
Backward integration into naphthalene feedstock and captive sulfonation capacity anchors margin control for Indian azo dye manufacturers serving pharmaceutical coating specifications. This integration choice simultaneously insulates against petrochemical price swings and enables tiered pricing across REACH-registered European grades versus FSSAI-compliant domestic volumes.
Pricing Analysis
Naphthalene feedstock volatility passes through directly to finished dye pricing, compressing margin predictability for non-integrated manufacturers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications separates premium documentation-heavy tablet coating sales from commodity confectionery volumes. Pricing pressure stems from natural colorant substitution in premium beverage segments where beetroot-derived betalains displace synthetic reds. Mid-scale pharmaceutical coating facilities exhibit highest price sensitivity due to limited batch volumes and qualification cost burdens.
Supply Chain Analysis
Azo dye synthesis rests on Indian petrochemical intermediates, Chinese naphthalene derivatives, and European REACH-registration expertise. Naphthalene feedstock, sulfonating agents, and modified starch encapsulants constitute critical input dependencies. Single-source vulnerability concentrates in naphthalene supply chains tied to crude oil benchmarks. Distribution runs through direct-procurement contracts between major bottling groups and Ankleshwar manufacturers, displacing regional chemical traders in high-volume beverage applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in carmoisine hinges on automated dosing system integration capturing value from capital-intensive bottling line upgrades, alongside pharmaceutical-grade certification premiums separating documented heavy metal limits from commodity food-grade sales.
For Market Incumbents: Anticipate EFSA exposure threshold reductions forcing multi-year toxicological data investments to defend existing azo dye authorizations. Consolidate around dual-certification dossiers synchronizing REACH registration updates with FSSAI labeling mandates before compliance deadlines crystallize. Capacity addition in Gujarat chemical estates reinforces supply position against emerging natural colorant substitution threats in premium beverage segments. For New Entrants and Emerging Players: Microencapsulation technology with modified starch shells offers entry into nutraceutical gummy applications where pH-stable coloration surviving acidic fruit matrices creates technical barriers to commodity suppliers. Target Middle Eastern markets with converging Codex-equivalent import standards streamlining FSSAI-aligned Indian exporter access. Direct technical sales to mid-scale pharmaceutical tablet coating facilities bypasses established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for REACH-registered European pigment houses with pharmaceutical coating divisions because regulatory compliance barriers and multi-year authorization timelines limit new entrant supply. Long-term viability over the analysis window favors acquisition targets with dual-certification capabilities spanning ECHA dossiers and FSSAI documentation. Watch EFSA azo dye re-evaluation timelines as inflection indicator for reformulation cost waves across European confectionery applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthalene Feedstock | Captive supply of petrochemical intermediates insulates Indian manufacturers from crude oil benchmark volatility. |
| Dual-Certification Dossier Investment | Parallel REACH and FSSAI documentation streamlines access to European pharmaceutical and Indian food-grade channels. |
| Microencapsulation Capacity Expansion | Spray-dried modified starch shells capture nutraceutical gummy demand with technical barriers to commodity entry. |
| Automated Dosing System Partnerships | Liquid formulation integration with Brazilian and Mexican bottling lines captures value from capital upgrades. |
| Direct-Procurement Contract Concentration | Annual tonnage commitments with South African and Indonesian bottlers displace regional chemical trader networks. |
Study Parameters
Coverage spans India, Germany, the United States, Brazil, and the United Arab Emirates, with primary inputs from each market cluster. The approach combines interviews with plant managers at Ankleshwar chemical estates, procurement leads at multinational beverage bottlers, pharmaceutical coating technical directors, and FSSAI regulatory affairs specialists. Secondary validation draws from CDSCO registration databases, EFSA food additive re-evaluation dossiers, customs trade data on sulfonated azo dye shipments, and SEC filings from listed pigment manufacturers. Bottom-up volume modeling triangulates against top-down market sizing across certification-grade segments.
Granularity extends to formulation format, certification tier, end-use application, and regional regulatory cluster throughout the projection horizon. The analytical framework models powder, liquid, granule, and capsule formats separately against food-grade, pharmaceutical-grade, and industrial-grade specifications. CAGRs derive from segment-level volume trajectories weighted by regional production capacity expansion and import substitution patterns. Forecast inputs include naphthalene feedstock price indices, REACH registration timeline assumptions, and FSSAI labeling mandate implementation schedules.
The model holds under stable petrochemical feedstock pricing and gradual regulatory convergence; deviation in EFSA azo dye suspension decisions or abrupt naphthalene supply disruptions would shift volume trajectories. Forecasts reflect documented assumptions on certification timeline adherence and import standard harmonization. A small set of named triggers—EFSA exposure threshold rulings, FSSAI enforcement intensity, and natural colorant cost parity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Titanium Dioxide Color Market