
 Impact Testing Machine Market | 2026-2036
Impact Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Impact Testing Machine Market Foresight
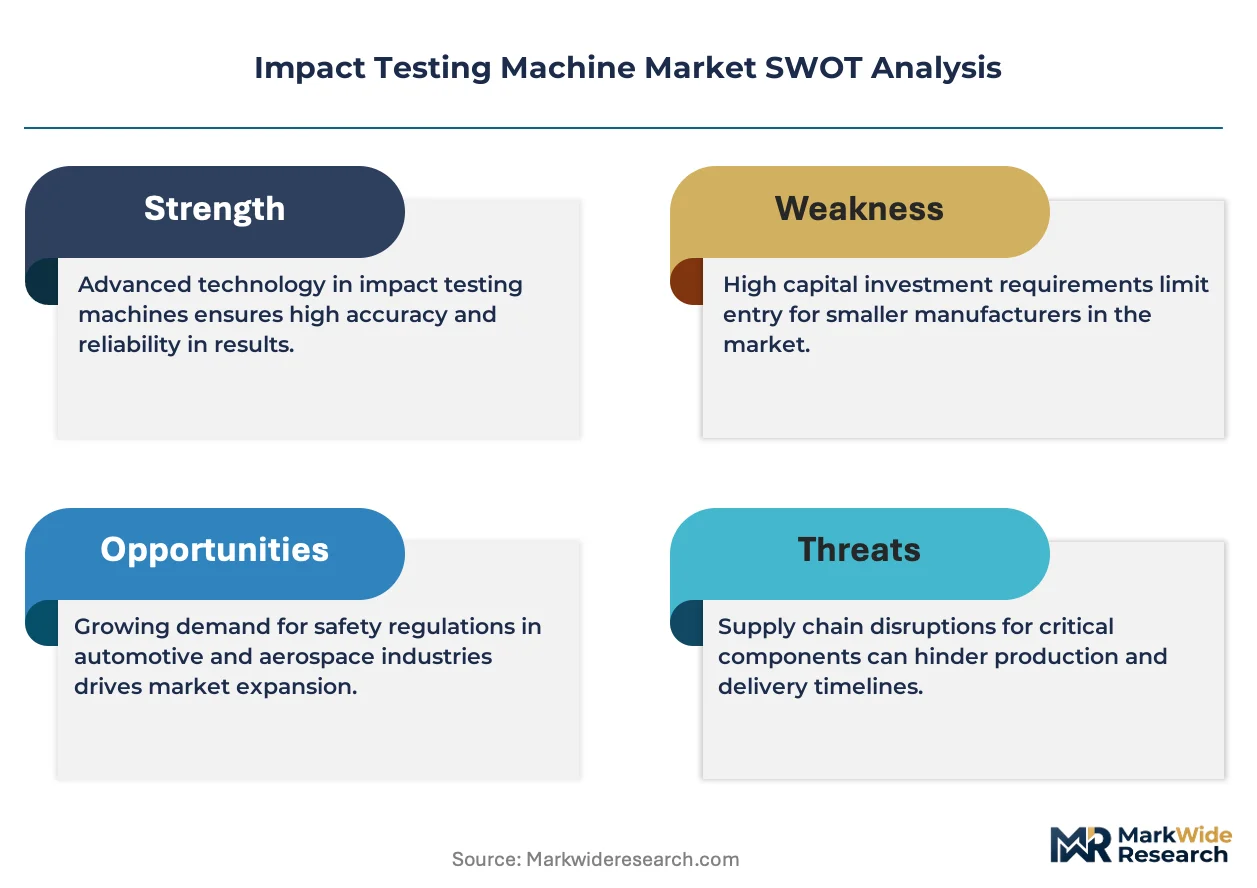
Equipment leasing and performance-based contracting is narrowing the capital barrier for mid-sized testing laboratories seeking Charpy and Izod capabilities. ZwickRoell leverages its European service network to sustain long-term instrument utilization contracts. Instron anchors its position through backward integration into load cell and software architecture. MTS competes in high-force drop weight systems for defense and energy sector clients.
An impact testing machine measures a material's resistance to sudden dynamic loads, typically quantifying absorbed energy in joules during fracture events using standardized striker geometries and pendulum or drop-weight mechanisms. These instruments validate structural integrity for metals, polymers, and composites deployed in safety-critical applications. Charpy testers occupy the mature core of product demand, while automated digital systems represent the fastest-expanding technology segment as laboratories pursue throughput gains and reproducibility. Quality assurance applications command durable budget allocations, whereas research and development segments attract premium pricing for customized striker configurations and environmental chamber integration.
FAA airworthiness standards and EASA certification specifications mandate traceable impact data for aerospace material qualifications, compelling laboratories to maintain calibrated instrument fleets. ISO 148 and ASTM E23 govern striker geometry and verification protocols, creating compliance-driven replacement cycles for aging mechanical units. Stakeholders must weigh the total cost of ownership against throughput requirements when selecting between semi-automated and fully automated platforms.
Market Dynamics
Equipment leasing penetration is compressing capital barriers for mid-sized laboratories, while aerospace certification mandates under FAA and EASA directives are accelerating replacement cycles for mechanical Charpy units across North America and Europe.
Growth Catalysts
- EASA Airworthiness Directives:Aerospace material qualification requirements in Germany and France are compelling laboratories to upgrade to digitally traceable impact testing systems.
- Automotive Lightweighting:Japanese and South Korean OEMs enforce stricter impact resistance protocols for aluminum alloys and carbon fiber composites in electric vehicle structures.
- East Asian Manufacturing Clusters:Concentrated automotive and electronics production in Japan, South Korea, and Taiwan sustains dense demand for high-throughput automated testers.
Market Restraints
- Load Cell Supply Concentration:Precision sensor manufacturing concentrates in German and Swiss component suppliers, exposing instrument builders to input bottlenecks.
- ISO 148 Compliance Friction:Striker geometry verification protocols impose extended calibration cycles that delay laboratory commissioning timelines.
- Used Equipment Arbitrage:Refurbished mechanical pendulum units from decommissioned European facilities compete against new automated platforms in price-sensitive segments.
Strategic Opportunities
- India BIS Certification Expansion:Domestic steel and polymer producers face escalating mandatory impact testing requirements under Bureau of Indian Standards quality enforcement.
- Environmental Chamber Integration:Converging thermal conditioning and impact testing capabilities opens premium pricing in aerospace R&D segments.
- Performance-Based Contracting:Long-term utilization agreements replace capital purchases, lowering entry barriers for mid-tier testing service providers.
Industry Challenges
- Metrologist Talent Scarcity:Specialized calibration expertise for striker verification and absorbed energy traceability concentrates in aging European technician pools.
- Legacy Software Integration:Automated digital systems face protocol mismatches when interfacing with existing laboratory information management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact Testing Machine Market |
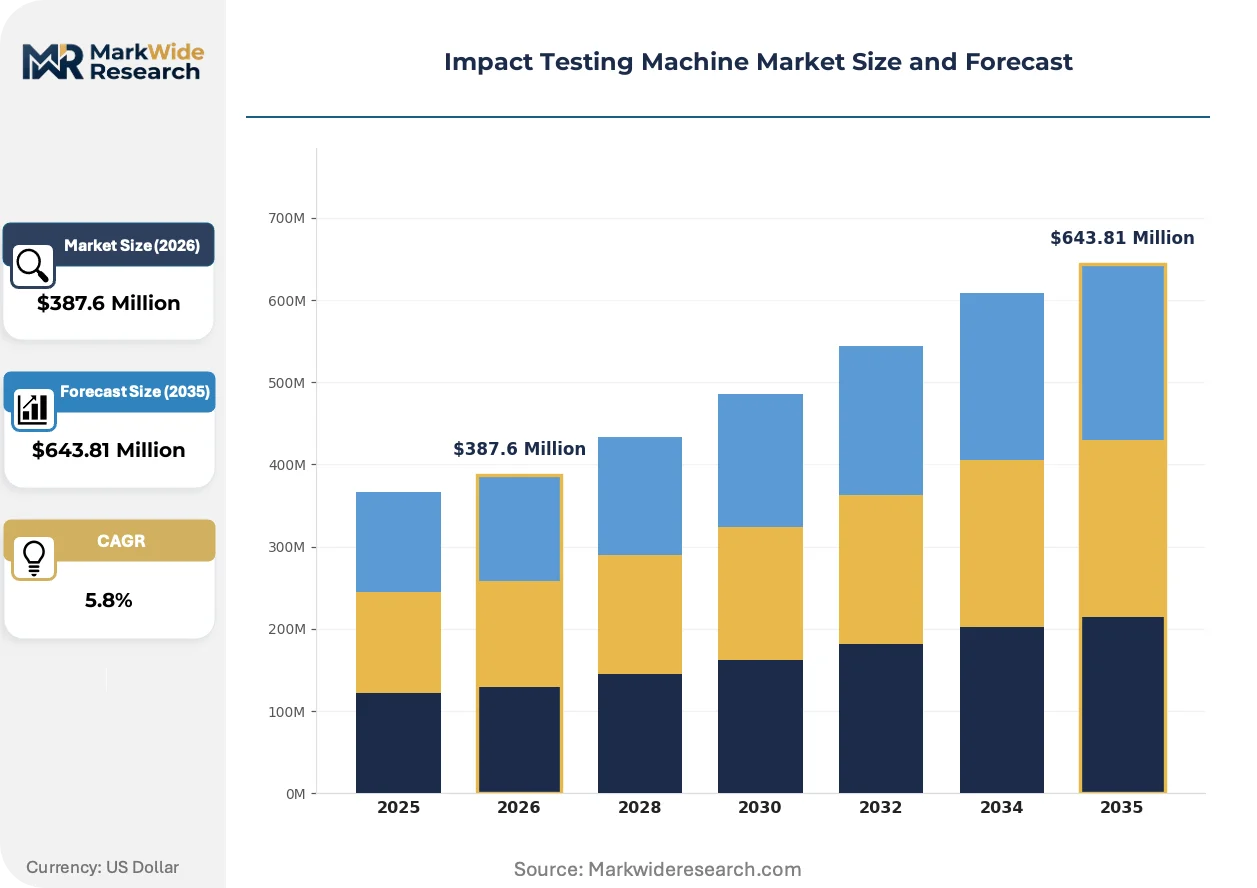
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Charpy Testers, Izod Testers, Drop Weight Testers, Pendulum Testers End User: Manufacturers, Research Laboratories, Quality Control, Educational Institutes Application: Material Testing, Quality Assurance, Product Development, Research & Development Technology: Mechanical, Digital, Automated, Semi-Automated |
| Companies Covered | ZwickRoell, Instron, Shimadzu Corporation, Tinius Olsen, ADMET, Inc., Hegewald & Peschke, Labthink Instruments, MTS, Lansmont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact Testing Machine Market Shifts & Advancements
Digital automation architectures are compressing test cycle times while regulatory data integrity mandates are reshaping instrument specification requirements across safety-critical industries.
Robotic specimen handling systems with machine vision alignment are eliminating manual loading variability in high-throughput laboratories. Automotive Tier-1 suppliers in Germany and Japan are adopting these platforms to meet OEM audit frequency requirements. Conventional semi-automated Charpy configurations are rendering obsolete in facilities processing more than five hundred specimens daily.
REACH substance restriction amendments are accelerating demand for non-metallic striker materials in European polymer testing laboratories. Composite striker tips eliminate metallic contamination risks during thermoplastic fracture characterization. German automotive suppliers and French aerospace subcontractors are prioritizing REACH-compliant instrument configurations in procurement specifications.
Consolidated testing service providers are unbundling after-sales calibration from initial equipment purchases, creating standalone service revenue streams. Large commercial laboratories in the United States and Japan now procure instruments and maintenance contracts through separate vendor relationships. This pattern compresses switching costs and intensifies competitive pressure on original equipment manufacturers to defend recurring revenue through software subscription attach rates.
Impact Testing Machine Market Segmentation
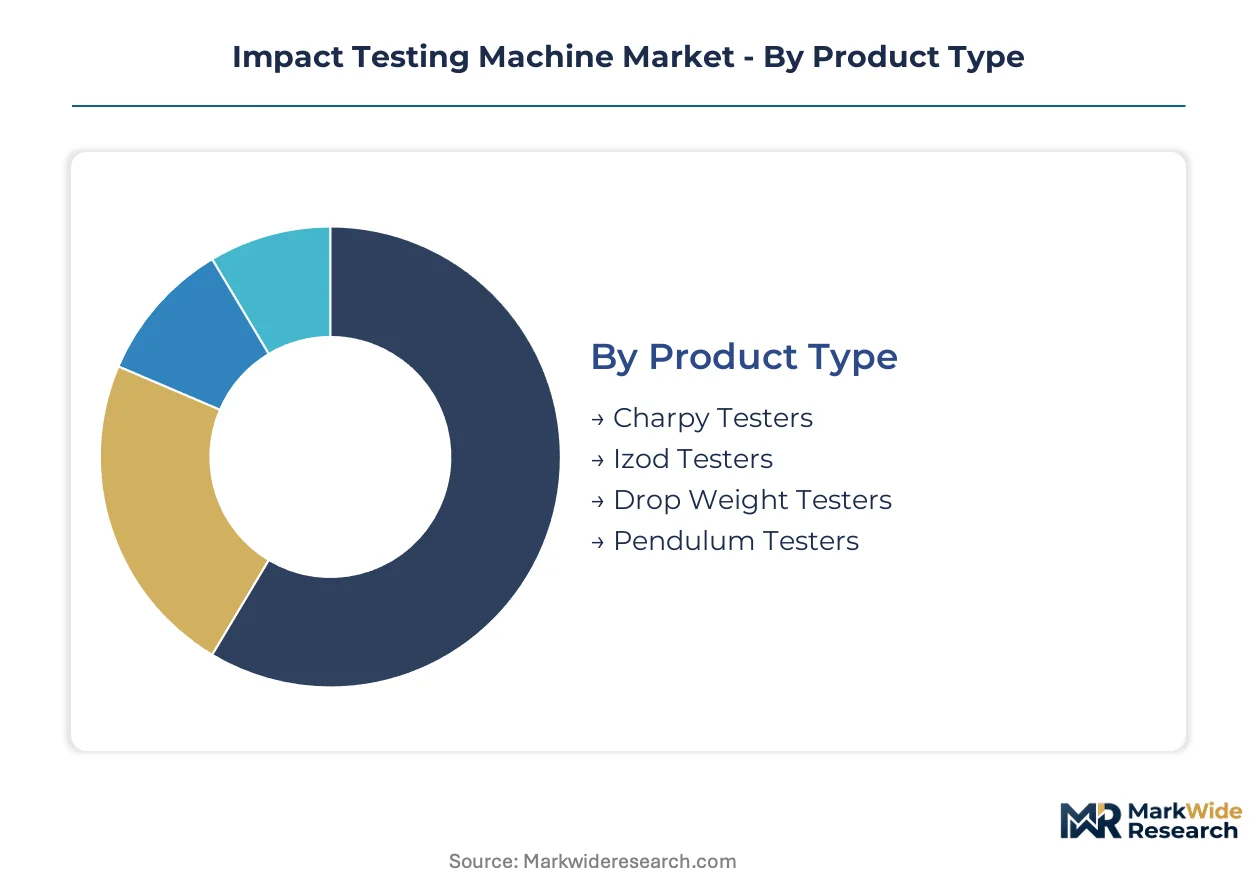
Impact testing machine procurement patterns diverge sharply across product configurations and user sophistication levels. Laboratories prioritize throughput automation while manufacturers emphasize traceable certification compliance for material qualification programs.
Product Type:
Mature pendulum architectures dominate installed base volumes while digital automation architectures reshape replacement demand.
- Charpy Testers:Standardized striker geometries measuring absorbed energy in joules remain the workhorse configuration for metals certification. German automotive suppliers and Japanese steel producers maintain dense fleets for ISO 148 compliance verification.
- Drop Weight Testers:High-force configurations accommodate large-scale composite panels and pipeline segments. Defense contractors in the United States and energy sector laboratories in France specify these systems for non-linear fracture characterization.
- Izod Testers:Cantilever beam configurations serve polymer and plastic testing protocols.
- Pendulum Testers:Conventional mechanical units face displacement by digitally instrumented platforms.
Charpy Testers retain volume leadership; Automated digital configurations hold the steepest expansion curve.
End User:
Capital intensity and regulatory exposure stratify purchasing behavior across institutional categories.
- Manufacturers:In-house testing departments at automotive OEMs and aerospace tier-1 suppliers require calibrated instrument fleets for production lot release. FAA and EASA airworthiness directives compel traceable data retention.
- Research Laboratories:Universities and national institutes pursue customizable striker configurations and environmental chamber integration for fundamental materials science.
- Quality Control:Third-party testing service providers balance throughput economics against accreditation maintenance costs.
- Educational Institutes:Training programs prioritize mechanical simplicity and durability over automation sophistication.
Manufacturers command the largest equipment budgets; Research Laboratories generate the highest per-unit pricing premiums.
Application:
Regulatory mandate intensity varies across the testing workflow spectrum.
- Quality Assurance:Production-line verification demands high-throughput automated platforms with machine vision alignment. South Korean battery manufacturers and German automotive suppliers enforce zero-defect material release protocols.
- Research & Development:Experimental striker geometries and cryogenic conditioning chambers support next-generation alloy development. Aerospace R&D facilities in France and the United States procure premium configurations.
- Material Testing:Standardized certification workflows dominate commercial laboratory revenue.
- Product Development:Iterative prototyping cycles require flexible instrument reconfiguration.
Quality Assurance absorbs the greatest instrument volume; Research & Development commands the steepest technology refresh rates.
Technology:
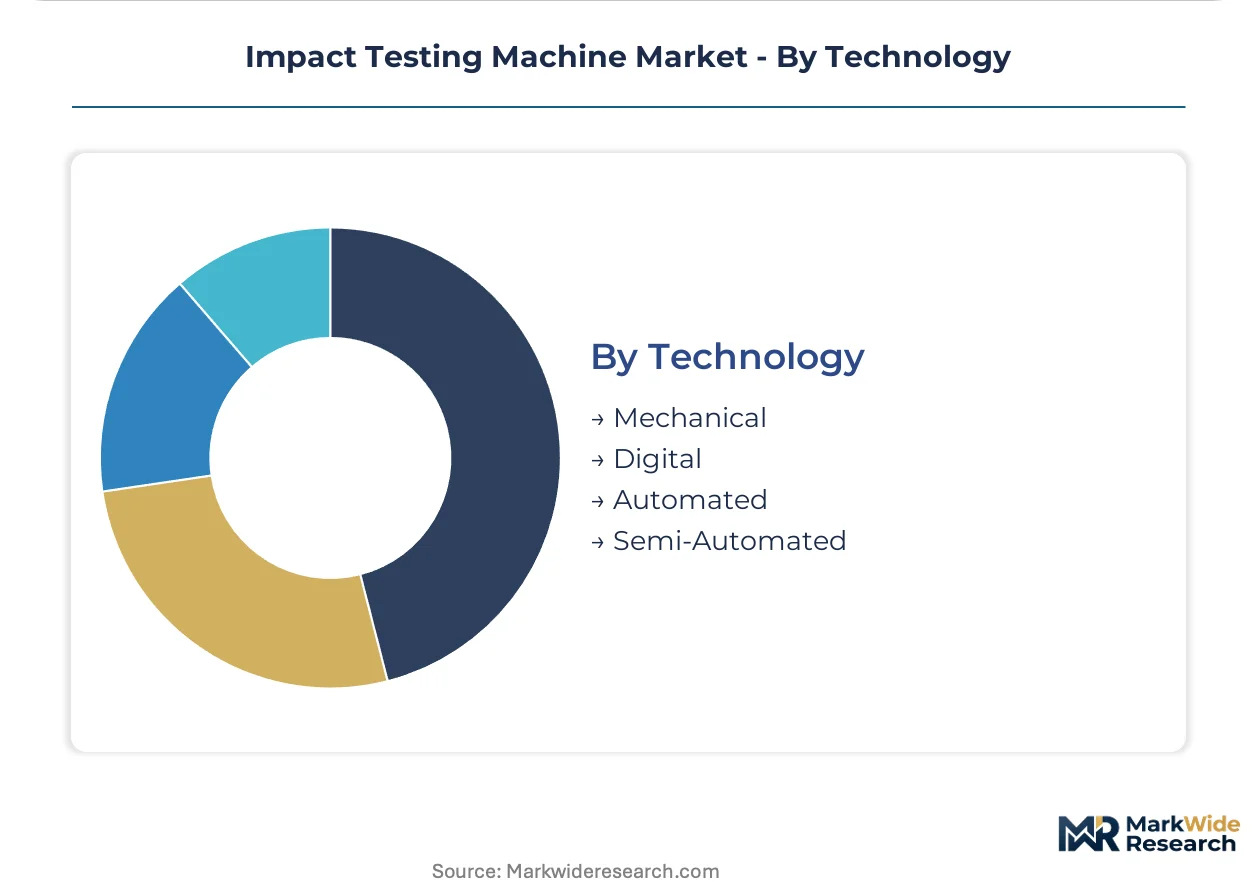
Digital instrumentation architectures are displacing mechanical legacy systems across certification workflows.
- Automated:Robotic specimen handling and machine vision alignment eliminate operator-induced variability. Japanese automotive tier-1 suppliers adopt these platforms for OEM audit compliance.
- Digital:Load cell-based force measurement and direct data capture replace analog dial indicators. European laboratories prioritize digital traceability for EASA certification specifications.
- Mechanical:Dial-indicator pendulum units persist in price-sensitive educational and developing-market installations.
- Semi-Automated:Intermediate configurations balance capital constraints against throughput requirements.
Mechanical systems retain residual installed base; Automated platforms gain share fastest among new procurements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives and EASA certification specifications are accelerating instrument replacement cycles across aerospace manufacturing corridors. Automotive lightweighting mandates in East Asia and quality enforcement expansions in India are redistributing procurement intensity toward digitally traceable testing platforms.
United States
Defense contractors and energy sector laboratories sustain demand for high-force drop weight configurations. FAA airworthiness standards mandate traceable impact data retention for aerospace material qualifications. Houston energy corridors and Seattle-Tacoma aerospace clusters maintain dense instrument fleets for pipeline and composite panel certification.
Germany
Automotive Tier-1 suppliers enforce zero-defect material release protocols requiring high-throughput automated platforms. EASA airworthiness directives compel laboratories to upgrade from mechanical to digitally instrumented Charpy systems. Stuttgart automotive belt and Hamburg aerospace subcontractor networks represent concentrated procurement zones.
Japan
Electric vehicle OEMs impose stricter impact resistance specifications for aluminum alloys and carbon fiber structures. METI industrial standards guide striker geometry verification protocols for domestic certification workflows. Nagoya automotive manufacturing corridors and Osaka polymer research institutes drive replacement demand for robotic specimen handling systems.
South Korea
Battery manufacturers and automotive suppliers require machine vision alignment capabilities for OEM audit compliance. MFDS pharmaceutical packaging regulations indirectly elevate materials testing standards across adjacent industrial sectors. Ulsan petrochemical complexes and Seoul Capital Area electronics fabrication zones sustain dense laboratory instrument deployments.
India
Domestic steel and polymer producers face escalating mandatory impact testing under Bureau of Indian Standards quality enforcement. BIS certification expansion creates first-time instrument demand among mid-sized manufacturers previously reliant on third-party testing. Maharashtra industrial corridors and Gujarat chemical manufacturing zones represent emerging procurement frontiers.
Impact Testing Machine Market Competitive Landscape
On the supply side, the industry is moderately consolidated around precision instrumentation specialists with captive metrology capabilities. European and Japanese incumbents anchor the premium tier through backward integration into load cell architecture and software ecosystems. Three strategic archetypes dominate: vertically integrated metrology houses, component-specialized regional fabricators, and testing service providers backward-integrating into instrument manufacturing. Competitive intensity concentrates on long-term utilization contracts and calibration service unbundling rather than capital equipment pricing alone.
Within the European integrated tier, ZwickRoell and Hegewald & Peschke exemplify archetypes combining instrument manufacturing with dense service networks. Instron occupies a position representing North American precision load cell and control software integration. Shimadzu Corporation anchors the Japanese industrial instrumentation complex with exposure to materials testing across automotive and electronics verticals. These three represent differentiated geographic and technological positioning without overlapping core competency claims.
| Leading Market Players |
|---|
| ZwickRoell |
| Instron |
| Shimadzu Corporation |
| Tinius Olsen |
| ADMET, Inc. |
| Hegewald & Peschke |
| Labthink Instruments |
| MTS |
| Lansmont |
| Others |
Supply & Pricing Matrix
German and Swiss precision sensor manufacturing concentrates load cell supply for instrument builders, anchoring margin pools in aftermarket calibration services and software subscription attach rates rather than equipment sales alone. This upstream concentration forces downstream pricing strategies to emphasize recurring revenue streams over transactional hardware margins.
Pricing Analysis
Certification level creates the primary spread between premium digitally traceable systems and economy mechanical units. Pricing stratifies across EASA/FAA-grade automated platforms, ISO 148-compliant digital configurations, and educational mechanical pendulum units. Cost compression in the mid-tier intensifies as refurbished European equipment arbitrages against new automated platforms. Third-party testing service providers exhibit highest price sensitivity due to unbundled procurement patterns separating instrument purchases from maintenance contracts.
Supply Chain Analysis
Load cell feedstock and precision sensor components draw from German, Swiss, and Japanese supplier networks. Instrument assembly rests on captive metrology capabilities, striker geometry forgings, and robotic handling subsystems. Single-source vulnerability concentrates in high-precision force transducer supply. Distribution runs through direct OEM sales for large manufacturers and regional distributor networks for mid-tier laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated testing service providers in the United States and Japan, where unbundled procurement patterns compress switching costs and intensify vendor pricing pressure.
For Market Incumbents: Insulate recurring revenue through software subscription attach rates and standalone calibration service contracts. Defend against refurbished equipment arbitrage by embedding digital traceability features that obsolete mechanical units. Prioritize backward integration into load cell architecture to reduce exposure to German and Swiss component bottlenecks. For New Entrants and Emerging Players: India's BIS certification expansion presents the most penetrable geographic frontier, where domestic steel and polymer producers face first-time mandatory impact testing requirements. Target mid-sized manufacturers in Maharashtra and Gujarat industrial corridors previously reliant on third-party testing. Pursue performance-based contracting models that lower capital barriers and accelerate instrument deployment. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated metrology houses with captive calibration capabilities and dense regional service networks. Long-term viability hinges on defensible aftermarket revenue streams rather than hardware shipment volumes. Watch for EASA and FAA directive amendments as inflection indicators accelerating replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Chamber Integration | Converging thermal conditioning with impact testing opens premium aerospace R&D pricing tiers. |
| Performance-Based Contracting | Long-term utilization agreements replace capital purchases for mid-tier testing service providers. |
| Robotic Specimen Handling Deployment | Machine vision alignment eliminates operator variability for Japanese automotive Tier-1 audit compliance. |
| REACH-Compliant Striker Material Transition | Composite striker tips eliminate metallic contamination risks for German polymer testing laboratories. |
| Calibration Service Unbundling | Standalone service revenue streams compress switching costs for United States commercial laboratories. |
Research Methodology
Initial hypotheses were tested against primary input from instrument calibration technicians, laboratory quality managers, aerospace materials engineers, and automotive Tier-1 procurement leads and refined through secondary validation against ISO 148 technical committee documentation, EASA certification specifications, ASTM E23 standards, and customs trade data for precision instrument imports. Bottom-up demand estimates from end-user procurement patterns were triangulated against top-down market sizing from manufacturer shipment disclosures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product configuration, end-user sophistication tier, application workflow, and technology architecture. CAGRs were derived from instrument replacement cycle analysis and regulatory mandate acceleration curves. Forecast inputs incorporated EASA airworthiness directive amendment schedules and automotive OEM lightweighting protocol evolution.
Practitioners should monitor BIS enforcement intensity in India and REACH substance restriction amendments for early signals of demand inflection. Cross-checking against FAA and EASA certification backlog data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Production Testing Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
Capacitance Meter Market