
 Ohm Meter Market | 2026-2036
Ohm Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Ohm Meter Market Analytics
China is narrowing its reliance on imported precision test instrumentation through domestic capacity expansion in Jiangsu and Guangdong provinces. Fluke Corporation leverages extensive calibration service networks to sustain aftermarket revenue across industrial user bases. Keysight Technologies anchors its position through R&D intensity in high-frequency measurement architectures. Hioki competes with specialized low-resistance modules tailored to automotive harness verification workflows.
An ohm meter measures electrical resistance between two points in a circuit, typically operating across ranges from micro-ohms to mega-ohms with accuracy thresholds reaching 0.01% in laboratory-grade units. Four-wire Kelvin connection technology eliminates lead resistance errors, enabling precise characterization of conductive materials, semiconductor junctions, and protective grounding systems. Digital ohm meters with microcontroller-based architectures dominate commercial volumes due to automated ranging and data logging integration. Portable units for field electrical testing command margin premiums over bench configurations in utility and infrastructure maintenance segments.
FDA oversight of medical device manufacturing validates ohm meter traceability in implantable electronics production, while FCC electromagnetic compatibility rules shape shielding effectiveness measurement protocols. China's NMPA and GB standards mandate insulation resistance verification for domestically produced diagnostic equipment. METI in Japan drives precision instrument export certification through JIS calibration requirements. Stakeholders must monitor how evolving dual carbon goals in China and EU CSRD reporting obligations redirect procurement toward energy-efficient measurement platforms with embedded connectivity features.
Market Dynamics
Four-wire Kelvin measurement architectures are displacing two-wire systems across battery testing workflows, compressing equipment replacement cycles and recalibrating vendor qualification criteria for automotive and energy storage procurement teams.
Growth Catalysts
- EU Green Deal industrial verification:Electric vehicle battery testing laboratories in Germany are expanding procurement of precision four-wire measurement systems under mandatory carbon accounting protocols for supply chain transparency.
- Semiconductor junction characterization:Advanced packaging for high-power electronics requires micro-ohm resolution for thermal interface material validation, pulling demand from foundries in South Korea and Taiwan.
- Domestic capacity expansion:China's NMPA and GB standards are narrowing import dependence through Jiangsu and Guangdong province manufacturing clusters serving medical device and diagnostic equipment producers.
Market Restraints
- Precision resistor input volatility:Manganin and Evanohm foil materials face supply concentration from a limited set of specialty alloy producers, compressing margins for mid-tier instrument manufacturers.
- Calibration infrastructure gaps:Field service networks for traceable resistance standards remain thin across Southeast Asian industrial corridors, extending equipment downtime for remote facility operators.
- Substitution from multifunction DMMs:Digital multimeters with dedicated low-resistance ranges are capturing price-sensitive bench applications below 0.1% accuracy requirements.
Strategic Opportunities
- India BIS certification acceleration:The country's Bureau of Indian Standards is mandating insulation resistance verification for domestically produced electrical equipment, opening procurement channels for compliant instrument suppliers.
- Embedded connectivity convergence:Integration of IoT telemetry with measurement hardware is collapsing data acquisition friction, enabling predictive maintenance contracts for utility infrastructure operators.
- Energy storage system commissioning:Grid-scale battery installations require high-current micro-ohm testing for busbar and cell-to-cell connection integrity, creating specification pull from EPC contractors.
Industry Challenges
- Metrology talent scarcity:Qualified calibration technicians capable of maintaining 0.01% traceability chains are concentrated in aging workforce pools across industrialized economies.
- Legacy system integration friction:Modern USB and Ethernet-enabled meters face protocol mismatches when interfacing with decades-old manufacturing execution systems in heavy industry facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ohm Meter Market |
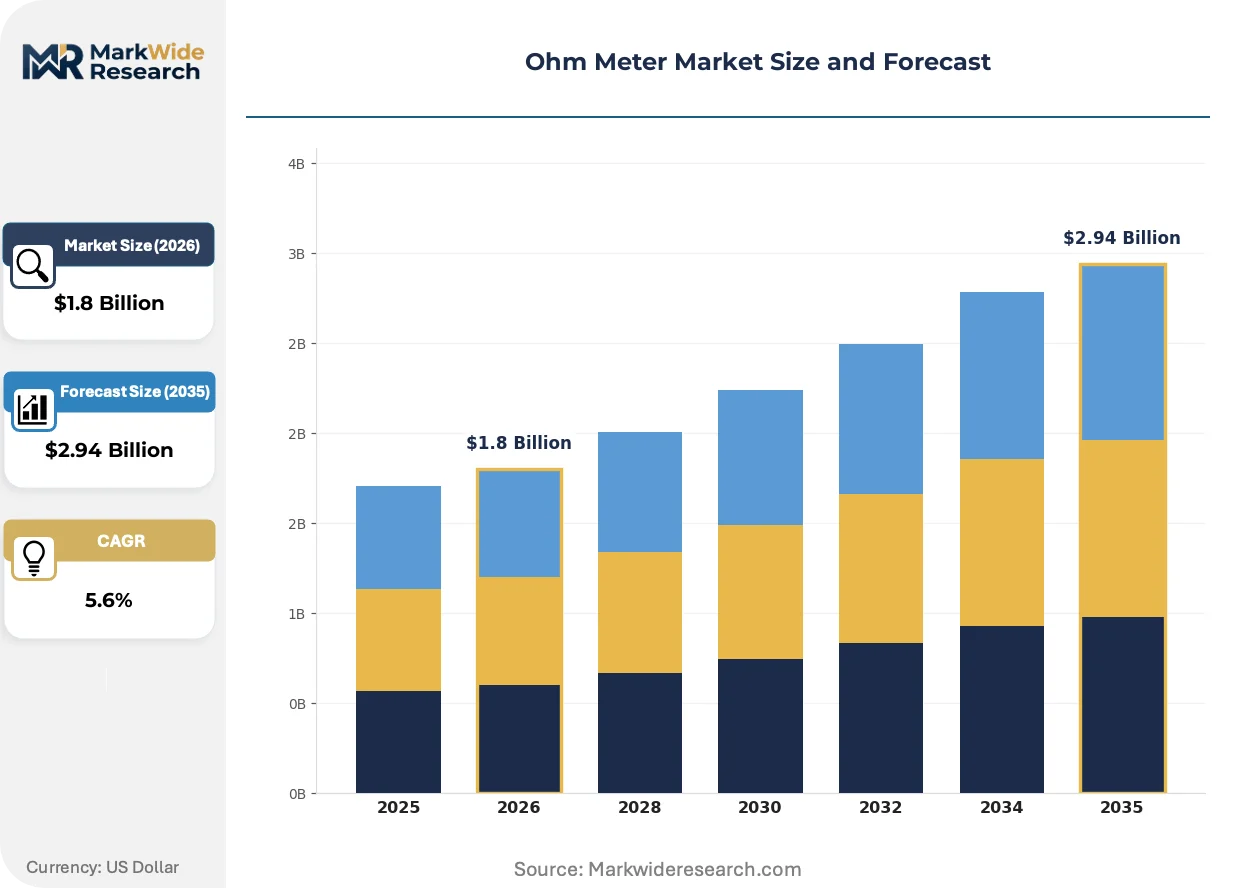
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
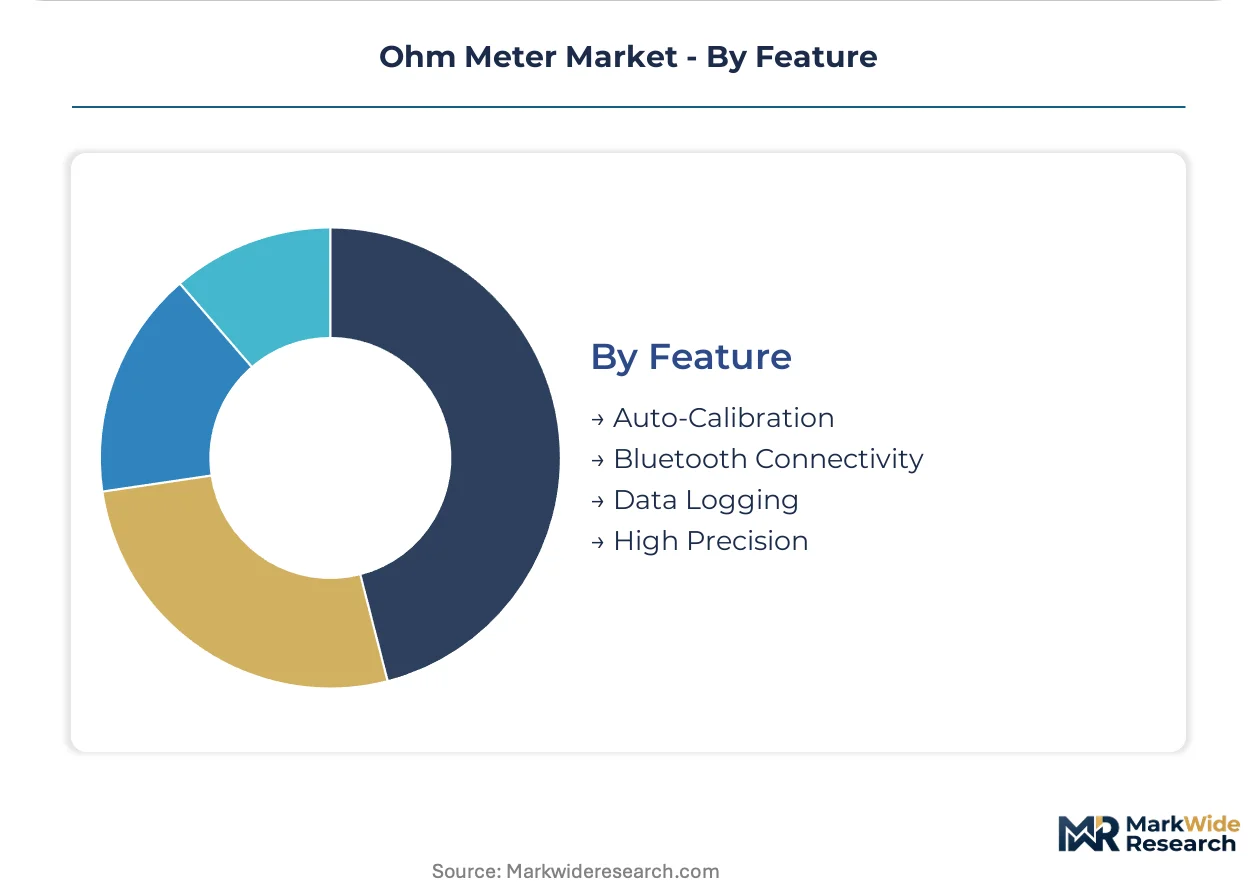
| Segmentation | Product Type: Digital Ohm Meter, Analog Ohm Meter, Portable Ohm Meter, Bench Ohm Meter Technology: Four-Wire, Two-Wire, Kelvin Connection, Microcontroller-Based End User: Manufacturing, Electrical Testing, Automotive, Education Feature: Auto-Calibration, Bluetooth Connectivity, Data Logging, High Precision |
| Companies Covered | Fluke Corporation, Keysight Technologies, Tektronix, Hioki, Yokogawa Electric Corporation, Megger, Extech Instruments, B&K Precision Corporation, AEMC Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ohm Meter Market Evolving Landscape
Measurement hardware architectures are converging with data infrastructure, collapsing the boundary between field instrumentation and enterprise analytics platforms while compressing the skill requirements for complex resistance characterization workflows.
Wireless-enabled handheld ohm meters with cloud-synced calibration certificates are collapsing documentation overhead for utility field crews and third-party inspection services. Municipal electrical departments in North American jurisdictions are piloting these units for substation grounding system verification, replacing paper-based chain-of-custody processes with automated audit trails. The structural consequence is a compression in the addressable market for traditional bench-configured logging instruments in applications below 1,000 data points per annum.
Japan's METI is tightening JIS calibration requirements for precision instrument export certification, forcing manufacturers to maintain dual-track quality systems for domestic and international product variants. The industrial consequence is a bifurcation in product portfolios, with premium-tier units carrying full metrology laboratory traceability and economy-tier SKUs limited to factory-standard calibration. Medical device manufacturers in Japan and adjacent export markets are absorbing the compliance cost premium to maintain FDA and PMDA dual-approval pathways.
Buyers in precision electronics manufacturing corridors are unbundling after-sales service contracts from hardware procurement, selecting calibration providers on per-event pricing rather than bundled annual agreements. South Korean semiconductor foundries are leading this shift, negotiating spot-rate relationships with third-party metrology laboratories while depreciating instrument hardware on shorter cycles. The geography where this behavioral shift is most visible is the Gyeonggi-do cluster, where concentrated purchasing power enables aggressive vendor management tactics.
Ohm Meter Market Segmentation

Ohm meter procurement patterns diverge sharply across application contexts, with calibration service intensity and connectivity requirements reshaping vendor selection criteria. Understanding these segment boundaries clarifies where specification premiums command durable pricing power versus commoditized volume plays.
Product Type:
After-sales service intensity varies dramatically across form factors, with portable units demanding field calibration networks while bench configurations anchor laboratory traceability contracts.
- Digital Ohm Meter:Microcontroller architectures enable automated ranging and direct data logging integration. Demand concentrates in South Korean semiconductor foundries where FDA and PMDA dual-approval pathways for medical device subcontractors mandate 0.01% accuracy thresholds with full metrology laboratory traceability.
- Portable Ohm Meter:Battery-powered handheld units with wireless-enabled cloud-synced certificates are collapsing documentation overhead for utility field crews. Municipal electrical departments across Germany and North American jurisdictions are piloting these for substation grounding verification, replacing paper-based chain-of-custody with automated audit trails.
- Analog Ohm Meter:Electromechanical galvanometer-based instruments persist in educational institutions and legacy industrial facilities where electromagnetic interference immunity outweighs digital convenience.
- Bench Ohm Meter:Rack-mounted laboratory-grade configurations with four-wire Kelvin connections serve battery testing workflows under EU Green Deal industrial verification protocols in German electric vehicle laboratories.
Digital ohm meters hold the largest share; momentum sits with portable configurations as field service networks expand.
Technology:
Measurement architecture selection directly determines acceptable accuracy thresholds and applicable regulatory compliance tiers across end-use verticals.
- Four-Wire:Kelvin connection systems eliminate lead resistance errors through separate current injection and voltage sensing paths. German automotive battery testing laboratories are expanding procurement under mandatory carbon accounting protocols for supply chain transparency, compressing equipment replacement cycles.
- Kelvin Connection:Specialized probe configurations enable micro-ohm resolution for thermal interface material validation in high-power electronics packaging. South Korean and Taiwanese foundries are pulling demand for advanced semiconductor junction characterization.
- Two-Wire:Simplified architectures dominate price-sensitive applications below 0.1% accuracy requirements where lead resistance errors remain acceptable.
- Microcontroller-Based:Embedded processing enables automated temperature compensation and direct enterprise system integration, collapsing the boundary between field instrumentation and analytics platforms.
Four-wire systems hold the largest share; Kelvin connection variants are climbing the fastest as automotive electrification intensifies.
End User:
Procurement authority structures and specification authority vary substantially across buyer categories, reshaping vendor engagement economics.
- Manufacturing:Precision electronics producers in Jiangsu and Guangdong provinces are narrowing import dependence through domestic capacity expansion serving medical device and diagnostic equipment markets under China's NMPA and GB standards.
- Automotive:Electric vehicle battery testing workflows are displacing two-wire systems with four-wire architectures, recalibrating vendor qualification criteria for procurement teams under EU Green Deal verification mandates.
- Electrical Testing:Utility infrastructure operators and third-party inspection services are absorbing embedded connectivity premiums for predictive maintenance contract enablement.
- Education:Technical training institutions prioritize cost-effective analog and basic digital units for fundamental circuit analysis instruction.
Manufacturing holds the largest share; automotive applications are gaining share fastest as electrification accelerates.
Feature:
Capability bundling strategies are fragmenting as buyers unbundle after-sales service contracts from hardware procurement, selecting calibration providers on per-event pricing.
- High Precision:Laboratory-grade 0.01% accuracy with full metrology traceability commands premium positioning in medical device manufacturing under FDA oversight and Japan's PMDA requirements.
- Bluetooth Connectivity:Wireless telemetry integration enables real-time data streaming to enterprise analytics platforms, collapsing data acquisition friction for predictive maintenance deployments.
- Data Logging:Internal storage with USB or Ethernet export serves manufacturing execution system integration in facilities with modern protocol stacks.
- Auto-Calibration:Self-diagnostic routines reduce field service dependency but require embedded reference resistors that face manganin and Evanohm foil supply concentration risks.
High precision holds the largest share; Bluetooth connectivity is expanding most quickly as utility infrastructure digitization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight anchors United States demand for ohm meter traceability in implantable electronics production. Procurement patterns diverge across industrial clusters as electrification and carbon accounting protocols reshape verification requirements.
United States
Utility infrastructure operators and municipal electrical departments are absorbing embedded connectivity premiums for predictive maintenance contracts. FCC electromagnetic compatibility rules shape shielding effectiveness measurement protocols for defense and aerospace subcontractors. The Pacific Northwest cluster concentrates procurement for grid-scale battery commissioning workflows.
Germany
Electric vehicle battery testing laboratories are expanding four-wire measurement system procurement under EU Green Deal industrial verification mandates. KBA automotive certification requirements recalibrate vendor qualification criteria for automotive harness verification. The Stuttgart and Munich industrial corridors concentrate carbon accounting protocol implementation for supply chain transparency.
China
Domestic capacity expansion in Jiangsu and Guangdong provinces narrows import dependence for precision test instrumentation. NMPA and GB standards mandate insulation resistance verification for domestically produced diagnostic equipment. The Yangtze River Delta manufacturing cluster serves medical device producers with shortened procurement cycles.
Japan
Precision instrument export certification through METI JIS calibration requirements forces manufacturers to maintain dual-track quality systems. PMDA medical device oversight validates traceability chains for implantable electronics subcontractors. The Nagoya industrial corridor concentrates automotive electrification testing workflows.
South Korea
Semiconductor foundries are unbundling after-sales service contracts from hardware procurement, selecting calibration providers on per-event pricing. MFDS medical device regulations and FDA dual-approval pathways mandate 0.01% accuracy thresholds. The Gyeonggi-do cluster leads aggressive vendor management tactics with concentrated purchasing power.
Ohm Meter Market Competitive Landscape
Capability concentration sits with laboratory-grade precision specialists; scale advantage sits with diversified test and measurement conglomerates. The vendor base organizes into three tiers: premium metrology laboratories with full traceability chains, mid-tier industrial instrument manufacturers, and price-competitive bench equipment suppliers. Strategic moves center on calibration service network expansion and embedded connectivity feature integration to capture recurring revenue streams.
Among diversified instrumentation conglomerates, Fluke Corporation and Keysight Technologies occupy positions anchoring aftermarket revenue through extensive service networks. Hioki represents the specialized module tier with focused low-resistance configurations. These three exemplify divergent competitive vectors: calibration infrastructure depth, R&D intensity in high-frequency architectures, and automotive workflow specialization respectively.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies |
| Tektronix |
| Hioki |
| Yokogawa Electric Corporation |
| Megger |
| Extech Instruments |
| B&K Precision Corporation |
| AEMC Instruments |
| Others |
Value Network & Pricing Analysis
Manganin and Evanohm foil concentration among specialty alloy producers in Germany and Japan anchors margin pools in the precision resistor tier, forcing mid-tier instrument manufacturers to absorb input cost volatility or cede position to laboratory-grade specialists with captive metallurgical supply.
Pricing Analysis
Price spreads between German automotive battery testing laboratories and Southeast Asian field service operators exceed 40% for comparable four-wire Kelvin configurations, reflecting certification-grade differentiation and embedded connectivity premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by metrology traceability depth, with FDA and PMDA dual-approval pathways commanding the widest spreads. Cost compression in the mid-tier is intensifying because multifunction DMM substitution captures bench applications below 0.1% accuracy requirements. Price-sensitive procurement concentrates in educational institutions and legacy industrial facilities, while least sensitivity sits with medical device manufacturers absorbing compliance premiums for implantable electronics traceability.
Supply Chain Analysis
Contract manufacturing for microcontroller-based architectures concentrates with EMS providers in Jiangsu and Guangdong provinces, while precision probe assembly feeds from Japanese and South Korean component specialists. Geographic supply concentration centers on China for PCB fabrication and final assembly, Germany for specialty alloy foil production, and Japan for precision galvanometer components. Raw material dependencies draw from manganin and Evanohm resistor alloys, high-purity copper for Kelvin connections, and automotive-grade microcontroller units. Single-source vulnerability runs through the limited set of certified foil producers serving 0.01% accuracy tiers. Distribution runs through direct OEM relationships for automotive and semiconductor foundry accounts, with regional distributors serving utility and education segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in South Korean semiconductor foundries and German automotive procurement teams, fragmenting vendor relationships into spot-rate calibration arrangements that compress hardware margins and accelerate replacement cycles.
For Market Incumbents: Insulate laboratory-grade positioning by deepening captive supply relationships with German and Japanese specialty alloy producers, while accelerating embedded connectivity integration to capture predictive maintenance recurring revenue streams threatened by third-party metrology laboratory unbundling. Certification investment in FDA and PMDA dual-approval pathways remains essential for medical device subcontractor retention. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification-mandated electrical equipment verification segment, where domestic production requirements and thin incumbent calibration infrastructure create procurement channel openings. Target utility infrastructure operators in Southeast Asian industrial corridors with wireless-enabled handheld configurations addressing documentation overhead pain points. Go-to-market leverage rests on per-event calibration pricing disruption against bundled annual service contracts. For Investors and Strategic Acquirers: Capital is best deployed toward precision metrology laboratories with full traceability chains and established automotive OEM qualification, as electrification intensification sustains specification pull over the coming decade. Acquisition priority sits with specialists holding JIS calibration export certification and dual-track quality systems for Japan-adjacent medical device markets. The signal to watch is EU Green Deal verification mandate expansion beyond German laboratories into French and Italian automotive testing corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Captures recurring revenue from German automotive battery testing laboratories under EU Green Deal mandates. |
| Embedded Connectivity Integration | Enables predictive maintenance contracts for North American municipal electrical departments replacing paper-based audit trails. |
| JIS Calibration Certification Investment | Maintains dual-approval pathways for Japanese medical device manufacturers serving FDA-regulated export markets. |
| Specialty Alloy Supply Agreement | Secures manganin and Evanohm foil access against concentration risk among German and Japanese producers. |
| Wireless Handheld Product Launch | Addresses documentation overhead compression for utility field crews and third-party inspection services. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry technical standards, combining interviews with precision instrument procurement managers, calibration laboratory directors, automotive battery testing engineers, and semiconductor foundry maintenance directors with validation across FDA 510(k) databases, METI export certification records, NMPA registration filings, and IEC measurement standard documentation. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments.
Forecast inputs span product type evolution, technology architecture displacement rates, end-user procurement authority shifts, and feature bundling fragmentation across the projection horizon. Segmentation dimensions modeled include form factor portability, measurement wire architecture, industry vertical concentration, and connectivity capability tier. CAGRs derive from regression analysis against historical replacement cycle compression and electrification capex intensity. Industry-specific inputs incorporate EU Green Deal verification mandate rollout pacing and China domestic capacity expansion trajectories.
Stress conditions across specialty alloy supply disruption, calibration technician workforce attrition, and multifunction DMM substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and automotive electrification investment continuity. Quarterly review of BIS certification acceleration in India, EU CSRD reporting obligation expansion, and METI JIS calibration requirement tightening is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Tube Tester Market
Test and Measurement
E-Axle and Inverter Efficiency and Reliability Test Platforms Market
Test and Measurement
Temperature Humidity Chambers Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Electromagnetic NDT Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Metrology Systems Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market