
 Marker Pens Market | 2026-2036
Marker Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Marker Pens Market Insights
Educational institutional purchasing is hardening as the dominant demand channel for marker pens. BIC Group leverages its mass-market distribution network to sustain volume leadership in school and office segments across multiple continents. Pilot Corporation anchors its position through specialized nib engineering that differentiates its product lines in technical and artistic applications. Mitsubishi Pencil Co., Ltd. competes on manufacturing scale, operating dedicated facilities that control regional supply for East Asian markets.
A marker pen is a writing instrument employing a porous fiber nib saturated with liquid ink, typically formulated with dyes or pigments suspended in water, alcohol, or oil-based solvents, designed to deposit consistent line widths on porous and non-porous surfaces. The primary commercial purpose spans permanent marking, erasable presentation, creative illustration, and industrial identification across paper, whiteboard, glass, metal, and plastic substrates. Permanent markers lead product type revenue due to industrial and logistics labeling requirements, while water-based formulations are gaining fastest in school applications driven by child-safety preferences. Brush nib variants command premium positioning within the art application segment, where Tombow Pencil Co., Ltd. and Faber-Castell AG occupy specialized margin pools.
EPA guidelines in the United States govern volatile organic compound emissions from alcohol-based inks, while REACH in Europe mandates chemical substance registration and hazard communication for imported marker formulations. BIS certification in India enforces product safety standards for school supplies, directly shaping which ink chemistries suppliers can introduce into that expanding market. Stakeholders must monitor evolving chemical restriction schedules across these three regulatory jurisdictions to anticipate reformulation costs and access barriers.
Market Dynamics
Educational procurement concentration in Southeast Asia and India is compressing margin structures while REACH and EPA chemical disclosure mandates force reformulation investments across alcohol-based ink portfolios.
Growth Catalysts
- REACH chemical registration mandates:European hazard communication requirements accelerate supplier consolidation as smaller ink formulators exit due to compliance costs, clearing shelf space for certified producers.
- Government school enrollment expansion:India's BIS certification enforcement for school supplies creates predictable demand corridors for compliant permanent marker manufacturers.
- Whiteboard infrastructure rollout:Southeast Asian educational institutions are standardizing on erasable presentation systems, pulling water-based marker demand into institutional procurement cycles.
Market Restraints
- Alcohol solvent price volatility:Input cost swings for isopropanol and n-propanol squeeze gross margins on permanent marker lines, particularly for mid-tier suppliers without long-term chemical supply contracts.
- Nib fiber supply concentration:Porous polyester and acrylic fiber production clusters in East China, creating single-source vulnerability for manufacturers dependent on imported nib materials.
- Digital whiteboard substitution:Interactive display penetration in corporate meeting rooms and premium educational facilities displaces traditional whiteboard marker consumption in tier-one cities.
Strategic Opportunities
- Indian government tender channels:Centralized state procurement for government schools offers volume anchoring for suppliers achieving BIS certification, with multi-year contract structures reducing demand volatility.
- Brush nib art segment expansion:Creative illustration applications command premium positioning as amateur and professional artists seek specialized stroke control unavailable in standard chisel or bullet nibs.
- PLI scheme alignment:India's production-linked incentive framework for manufacturing inputs rewards domestic ink formulation and nib assembly investments with tariff and tax advantages.
Industry Challenges
- Reformulation timeline compression:EPA volatile organic compound emission schedules and REACH substance restriction updates force simultaneous multi-jurisdiction compliance sprints, straining R&D bandwidth.
- Nib-to-ink interface engineering:Matching fiber porosity to new water-based and low-VOC solvent chemistries requires iterative testing cycles that extend product development calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marker Pens Market |
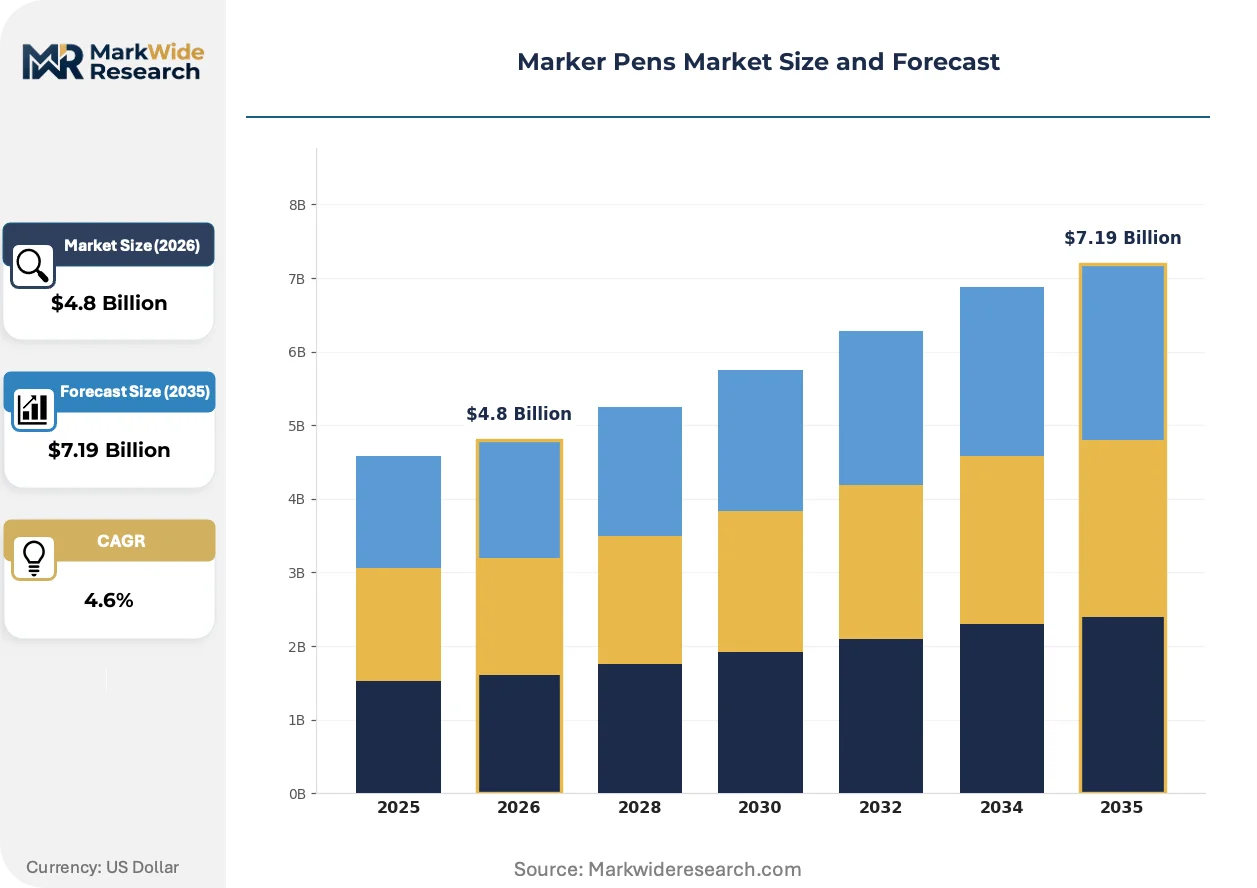
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Whiteboard, Highlighter, Washable Application: Art, School, Office, Industrial Ink Type: Water-Based, Alcohol-Based, Oil-Based, Gel Nib Type: Fine, Medium, Chisel, Brush |
| Companies Covered | BIC Group, Pentel Co., Ltd., Faber-Castell AG, Mitsubishi Pencil Co., Ltd., Sharpie, Edding Group, Pilot Corporation, Tombow Pencil Co., Ltd., Zebra Pen Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marker Pens Market Trends and Innovations
Marker pen evolution centers on chemical safety certification, nib architecture specialization, and procurement channel consolidation across institutional buyers.
Water-based ink chemistry is consolidating as the default formulation for educational applications. School districts and early-childhood facilities specify washable, low-odor products to satisfy parent safety committees and facility management protocols. This shift compresses demand for traditional alcohol-based permanent markers in the K-12 segment, reallocating R&D resources toward surfactant and pigment stability in aqueous systems.
EPA volatile organic compound emission thresholds are tightening disclosure requirements for alcohol-based marker formulations sold in the United States. Manufacturers must document solvent content and evaporation rates through certified testing protocols, adding documentation overhead but creating competitive separation between compliant and non-compliant import suppliers. Industrial labeling segments with less price sensitivity absorb these compliance costs more readily than mass-market office channels.
Institutional procurement consolidation is compressing supplier counts as school districts and government agencies move to framework agreements with pre-qualified vendors. Bulk purchasing through centralized tender platforms replaces fragmented retail and distributor relationships, favoring manufacturers with dedicated educational sales infrastructure and BIS or equivalent certification documentation. India and Indonesia exhibit this pattern most acutely, where state-level procurement bodies aggregate demand across thousands of individual schools.
Marker Pens Market Segmentation
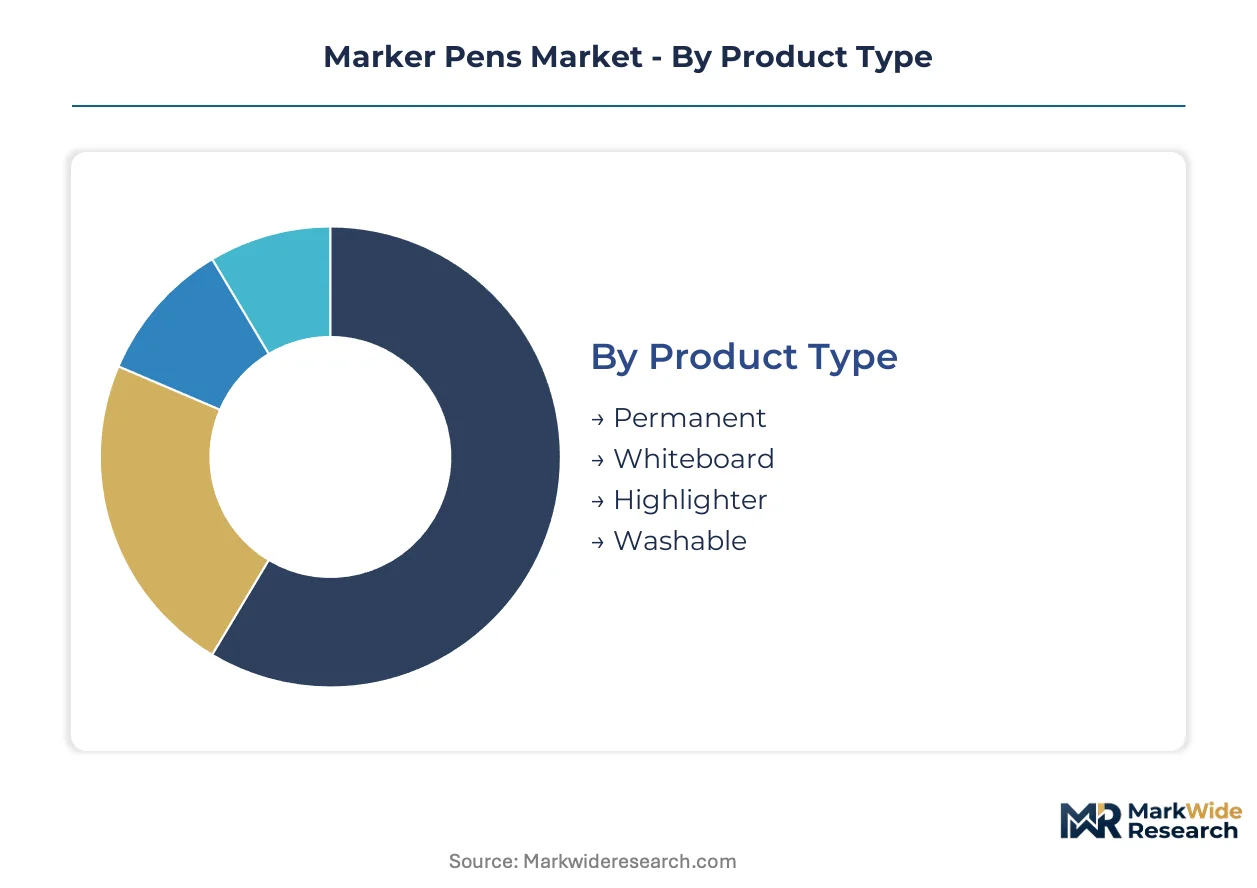
Marker pen segmentation reveals how regulatory compliance burdens and end-use specifications fragment manufacturing requirements across product lines. Suppliers must maintain parallel formulation portfolios to serve institutional buyers with divergent safety mandates and performance expectations.
Product Type:
Permanent markers require EPA volatile organic compound documentation for US distribution and REACH registration for European entry, while washable variants face BIS certification in India and child-safety labeling in multiple jurisdictions.
- Permanent:Alcohol-based solvent systems carrying dyes or pigments deliver indelible marks on metal, glass, plastic, and porous substrates. Industrial logistics operations in Germany and the United States drive volume through barcode labeling and warehouse identification protocols that demand smear-resistant permanence.
- Whiteboard:Low-odor alcohol or water-based formulations with controlled evaporation rates enable clean erasure from melamine and enamel surfaces. Southeast Asian educational procurement expansion in Indonesia, Vietnam, and Thailand is pulling demand into institutional tender channels as whiteboard infrastructure standardizes across public schools.
- Highlighter:Transparent fluorescent dyes in water-based suspensions emphasize text without obscuring underlying content. Office document management in Japan and South Korea sustains steady consumption through fluorescent yellow, pink, and green color standards.
- Washable:Surfactant-enhanced water-based pigments release from skin and fabric through standard laundering. Early-childhood facilities in India and parent safety committees in the United States are concentrating procurement toward certified non-toxic formulations.
Permanent markers sit at the top of the volume ranking, with washable variants climbing the fastest.
Application:
Application segmentation tracks how end-use environments dictate ink chemistry, nib architecture, and packaging specifications across customer types with divergent price sensitivity and performance requirements.
- Art:Brush nib configurations and expanded color gamuts serve professional illustrators and amateur creators seeking stroke variation and blendability. Tombow Pencil Co., Ltd. and Faber-Castell AG dominate premium positioning through specialized nib engineering and pigment lightfastness certification.
- School:Washable, low-odor water-based formulations dominate procurement specifications as facility managers and parent committees prioritize child safety over permanence. India's government school enrollment expansion is compressing margins through centralized state tendering while concentrating volume with BIS-certified suppliers.
- Office:Standard chisel and bullet nib configurations in black, blue, and red serve document annotation and whiteboard presentation needs. Corporate procurement consolidation in Japan and Germany favors framework agreements with established suppliers holding environmental compliance documentation.
- Industrial:Heavy-duty permanent markers withstand oil, grease, and extreme temperatures for equipment marking and safety labeling. Manufacturing facilities in the United States absorb EPA compliance costs more readily than price-sensitive mass-market channels.
School applications generate the steepest expansion trajectory as government enrollment programs accelerate across India and Southeast Asia.
Ink Type:
Ink chemistry determines regulatory exposure, with alcohol-based formulations facing tightening EPA emission thresholds and REACH substance restrictions while water-based systems navigate surfactant and pigment stability challenges.
- Water-Based:Pigment or dye suspensions in aqueous media with surfactant wetting agents. Educational procurement in India and Indonesia is consolidating demand toward washable, low-VOC formulations that satisfy child-safety protocols without industrial labeling performance.
- Alcohol-Based:Isopropanol or n-propanol solvents carrying rapid-drying dyes for permanent marking on non-porous surfaces. EPA volatile organic compound documentation requirements and solvent price volatility are squeezing mid-tier suppliers lacking long-term chemical supply contracts.
- Oil-Based:Slow-drying, water-resistant formulations for extreme environment marking including underwater and sub-zero applications. Specialized industrial maintenance operations in Russia and Canada sustain niche demand through performance requirements aqueous and alcohol systems cannot meet.
- Gel:Thixotropic pigment suspensions delivering controlled flow and reduced bleedthrough on thin paper stocks. Japanese stationery enthusiasts and precision draftspersons in Germany drive premium positioning through smooth writing experience and archival quality claims.
Alcohol-based inks retain volume leadership in industrial segments, with water-based formulations gaining share fastest through educational procurement conversion.
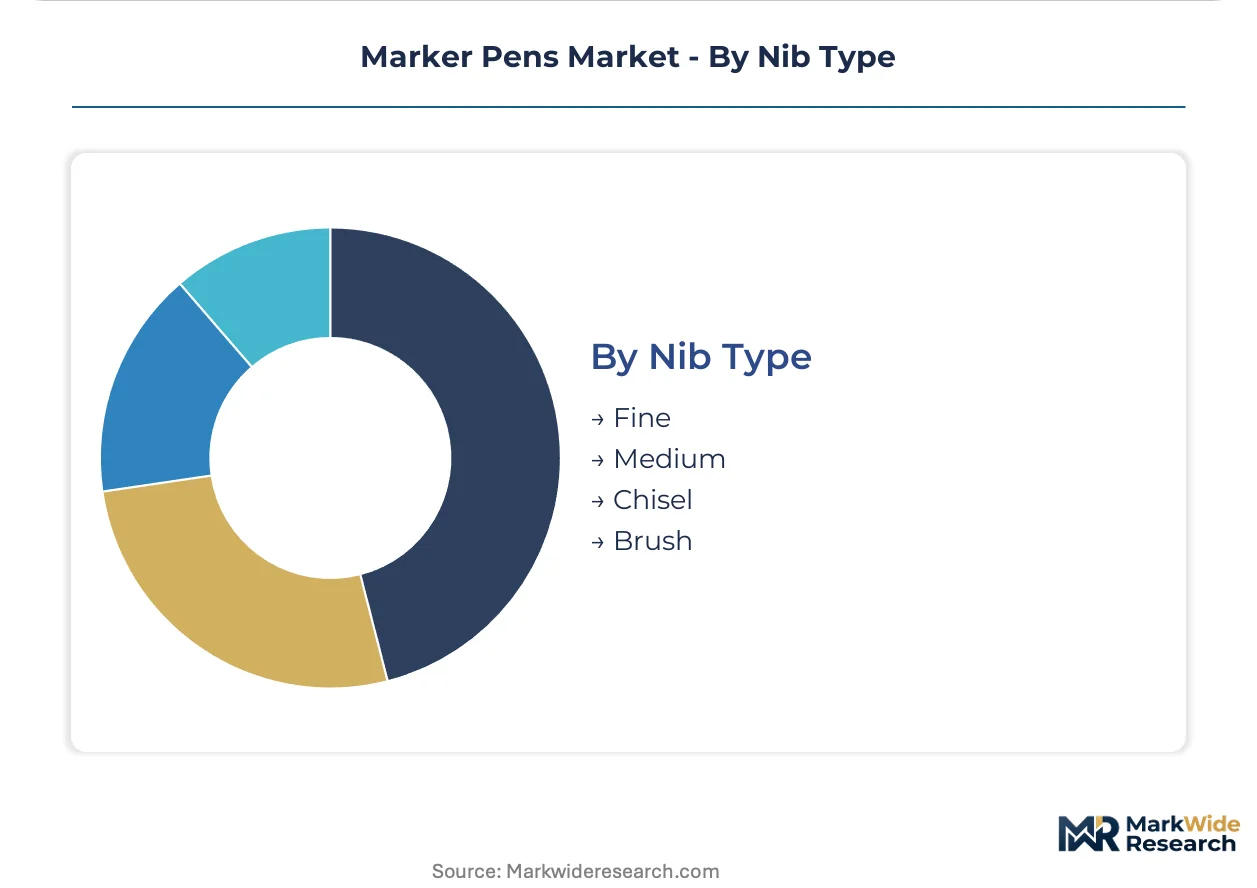
Nib Type:
Nib architecture directly determines line width control, ink flow regulation, and end-use application suitability, with fiber porosity engineering requiring iterative matching to specific ink chemistries.
- Fine:Narrow fiber bundles delivering consistent 0.5-1.0mm lines for detailed annotation and technical drawing. Precision documentation requirements in Japanese engineering offices and German technical fields sustain demand despite slower writing speed.
- Medium:Standard bullet configurations balancing line visibility and writing efficiency for general-purpose marking. Office procurement across multiple geographies treats medium nib as the default specification, compressing differentiation opportunities.
- Chisel:Angled fiber geometry enabling variable line widths from broad highlighting to narrow underlining through rotation. Whiteboard presentation standardization in Indonesian and Vietnamese schools is pulling chisel nib demand into institutional procurement cycles.
- Brush:Flexible fiber arrays mimicking paintbrush stroke variation for artistic illustration and hand-lettering. Tombow Pencil Co., Ltd. anchors premium positioning through proprietary brush nib engineering that competitors struggle to replicate at equivalent price points.
Medium nibs dominate absolute volume through office standardization, with brush configurations expanding most quickly in creative illustration segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's porous fiber manufacturing cluster anchors global nib supply, while regulatory divergence across EPA, REACH, and BIS jurisdictions fragments ink formulation requirements. Demand concentrates in government procurement corridors from Jakarta to Delhi.
United States
Industrial logistics operations in Chicago and Dallas-Fort Worth drive permanent marker consumption for warehouse barcode labeling. EPA volatile organic compound emission thresholds tighten documentation requirements for alcohol-based formulations. Nib fiber imports from Zhejiang Province supply assembly facilities in the Midwest.
Germany
Technical documentation standards in Bavarian engineering offices sustain fine-nib precision marker demand. REACH chemical registration mandates accelerate supplier consolidation as smaller ink formulators exit. The Rhine-Ruhr industrial corridor absorbs compliance costs through premium industrial labeling segments.
India
Government school enrollment expansion in Maharashtra and Uttar Pradesh concentrates bulk procurement through state tender platforms. BIS certification enforcement creates predictable demand corridors for compliant permanent marker manufacturers. Tamil Nadu's manufacturing belt hosts domestic ink formulation investments aligned with PLI scheme incentives.
Indonesia
Whiteboard infrastructure standardization across Jakarta and Surabaya public schools pulls water-based marker demand into institutional procurement cycles. National education ministry framework agreements compress supplier counts to pre-qualified vendors. Domestic distributors aggregate demand from thousands of individual institutions.
Vietnam
Educational facility modernization in Ho Chi Minh City and Hanoi drives erasable marker procurement through centralized provincial purchasing. Ministry of Education and Training specifications favor low-odor water-based formulations. Northern industrial zones host nib assembly operations serving regional supply.
Marker Pens Market Competitive Landscape
Certification-driven consolidation dominates the current landscape as compliance costs force mid-tier suppliers toward exit. The vendor base stratifies across three tiers: mass-market volume leaders with dedicated educational sales infrastructure, premium specialists commanding margin through nib engineering differentiation, and regional fabricators serving protected domestic procurement channels. Strategic archetypes include scale-driven manufacturers optimizing for government tender participation, technology specialists investing in fiber porosity matching for water-based chemistries, and brand licensors leveraging distribution partnerships for geographic reach. Portfolio diversification and geographic expansion represent the dominant competitive moves as players seek insulation from single-jurisdiction regulatory shocks.
Within the premium specialist tier, Tombow Pencil Co., Ltd. and Faber-Castell AG occupy positions defined by artistic application focus and pigment lightfastness certification. Among Japanese manufacturers, Pilot Corporation exemplifies the technology specialist archetype through nib engineering investments. At the mass-market volume end, BIC Group represents scale-driven positioning optimized for school and office segment procurement across multiple continents.
| Leading Market Players |
|---|
| BIC Group |
| Pentel Co., Ltd. |
| Faber-Castell AG |
| Mitsubishi Pencil Co., Ltd. |
| Sharpie |
| Edding Group |
| Pilot Corporation |
| Tombow Pencil Co., Ltd. |
| Zebra Pen Corp. |
| Others |
Pricing and Supply Chain Analysis
Isopropanol price benchmarks cascade through marker pen manufacturing tiers, compressing margins on alcohol-based permanent lines while water-based formulations absorb surfactant cost volatility through educational procurement contracts. Procurement concentration in Indian state tenders and Indonesian ministry frameworks amplifies buyer leverage, forcing suppliers to absorb input swings or sacrifice volume anchoring.
Pricing Analysis
Input-cost pass-through operates unevenly across alcohol solvent and water-based ink portfolios. Three-tier pricing structure across premium, standard, and economy levels separates brush nib art specialists from mass-market school suppliers and unbranded regional fabricators. Price differentiation hinges on BIS certification grade and volume scale through government tender channels. Cost compression in mid-tier permanent markers is intensifying because isopropanol supply contract coverage determines margin survival. Government procurement bodies in India and Indonesia exhibit lowest price sensitivity; unbranded distributors in fragmented retail channels face highest.
Supply Chain Analysis
Warehouse-distribution layer patterns center on regional distribution hubs in Mumbai, Jakarta, and Ho Chi Minh City that aggregate institutional demand before last-mile school delivery. Geographic supply concentration clusters in China for porous polyester fiber nibs, India for surfactant and pigment inputs, and Germany for precision nib engineering equipment. Raw material dependencies draw from East Chinese acrylic fiber production, Indian petrochemical-derived solvents, and Japanese pigment dispersion technology. Single-source vulnerability in Zhejiang Province nib manufacturing creates exposure to logistics disruption. Distribution runs through pre-qualified vendor frameworks that bypass traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marker pen market functions as a stable compounder anchored by government school enrollment programs that generate predictable replacement demand across multi-year procurement cycles.
For Market Incumbents: Anticipate regulatory compression across EPA volatile organic compound schedules and REACH substance restrictions by accelerating water-based ink R&D pipelines. Secure long-term isopropanol supply contracts to defend margin position against solvent price volatility. Prioritize BIS certification maintenance in India to retain access to state tender platforms that concentrate volume with compliant suppliers. For New Entrants and Emerging Players: The mid-tier price gap between premium brush nib specialists and economy school suppliers offers white-space entry through certified water-based formulations targeting Indonesian and Vietnamese educational procurement. Government framework agreements in Southeast Asia represent the most penetrable channel structure for qualified new suppliers. Pursue PLI scheme alignment in Tamil Nadu manufacturing zones to achieve cost parity with established Indian producers. For Investors and Strategic Acquirers: Asymmetric upside sits with technology specialists possessing proprietary nib-to-ink interface engineering capabilities that accelerate water-based product development timelines. Long-term viability favors manufacturers with diversified geographic certification coverage spanning EPA, REACH, and BIS jurisdictions. Monitor Indian state tender participation rates as the inflection signal for volume consolidation versus fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Unlocks access to Indian government school procurement corridors with multi-year contract structures. |
| Water-Based Ink Reformulation | Aligns product portfolios with EPA emission thresholds and REACH substance restrictions. |
| Nib Fiber Supply Contracting | Reduces exposure to Zhejiang Province production concentration and price volatility. |
| PLI Scheme Manufacturing Alignment | Captures tariff and tax advantages for domestic Indian ink formulation and assembly operations. |
| Brush Nib Engineering Expansion | Penetrates premium art segment margins controlled by specialized Japanese and German competitors. |
Research Methodology
Multiple input streams — primary interviews with stationery procurement officers, ink formulation chemists, and educational supply distributors, alongside secondary validation through BIS certification databases, Indonesian Ministry of Education tender records, and EPA volatile organic compound disclosure filings — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations covered state-level procurement managers in Maharashtra and Uttar Pradesh, technical directors at nib manufacturing facilities in Zhejiang, and category buyers at Indonesian distributor networks. Secondary sources included customs trade data on porous fiber imports, SEC filings of listed stationery manufacturers, and REACH registration dossiers for alcohol-based solvent systems.
Cross-referencing historical volume trajectories against panel input from procurement specialists anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, application, ink chemistry, and nib architecture alongside regional regulatory cluster divergence. CAGRs were derived through iterative reconciliation of enrollment-driven demand elasticity and reformulation cost absorption capacity. Industry-specific forecast inputs incorporated whiteboard infrastructure rollout schedules in Southeast Asian ministries and BIS enforcement timeline assumptions for Indian school supplies.
Caveats apply where solvent price volatility, regulatory acceleration, or digital whiteboard substitution could materially shift the outlook beyond modeled parameters. Forecasts reflect assumptions about procurement consolidation trajectories and certification compliance timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Cutter Staplers Market
Office Supplies
Writing Instruments Market
Office Supplies
Business Card Holder Market
Office Supplies
Stationery Products Market
Office Supplies
Dictionary Pen Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Office Supplies Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Greetings Cards Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
Letter Opener Market
Office Supplies
Writing and Marking Instruments Market
Office Supplies
Stationery Market
Office Supplies
Perforated File Market