
 Flash Cards and USB Flash Drives Market | 2026-2036
Flash Cards and USB Flash Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Flash Cards and USB Flash Drives Market Foresight
CE marking under the EU RoHS Directive is unwinding competitive access for vendors lacking hazardous-substance compliance documentation. Samsung Electronics leverages captive NAND fabrication to sustain cost leadership across memory card portfolios. Kingston Technology anchors enterprise-class USB drive demand through vertically controlled controller firmware development. ADATA Technology competes aggressively on thermal-engineered performance segments for gaming and content creation workloads.
Flash cards and USB flash drives are non-volatile solid-state storage devices employing NAND flash memory integrated with USB or flash memory interfaces, typically manufactured through semiconductor lithography processes at nodes ranging from 15nm to 176-layer 3D TLC/QLC architectures, serving primary functions in data transport, backup, and expandable device storage across consumer electronics, imaging equipment, and computing systems. MicroSD Cards and USB Type-C Drives represent the fastest-expanding product type categories as smartphone OEMs eliminate dedicated storage slots and laptop manufacturers standardize on reversible connector protocols. The 256GB storage capacity tier captures disproportionate margin contribution as bit-density economics improve and 4K video workflows proliferate among professional end users.
FCC equipment authorization governs electromagnetic emissions for USB flash drives distributed in the United States, while REACH compliance obligations within Europe constrain substrate and packaging material selections across supplier bases. China's SAMR enforces national standard GB/T 26225 for flash memory card performance and interoperability, creating localized certification burdens for foreign manufacturers. Stakeholders must monitor evolving interface protocol standards and regional material compliance deadlines to preserve market access and avoid supply chain disruption from retroactive regulatory enforcement.
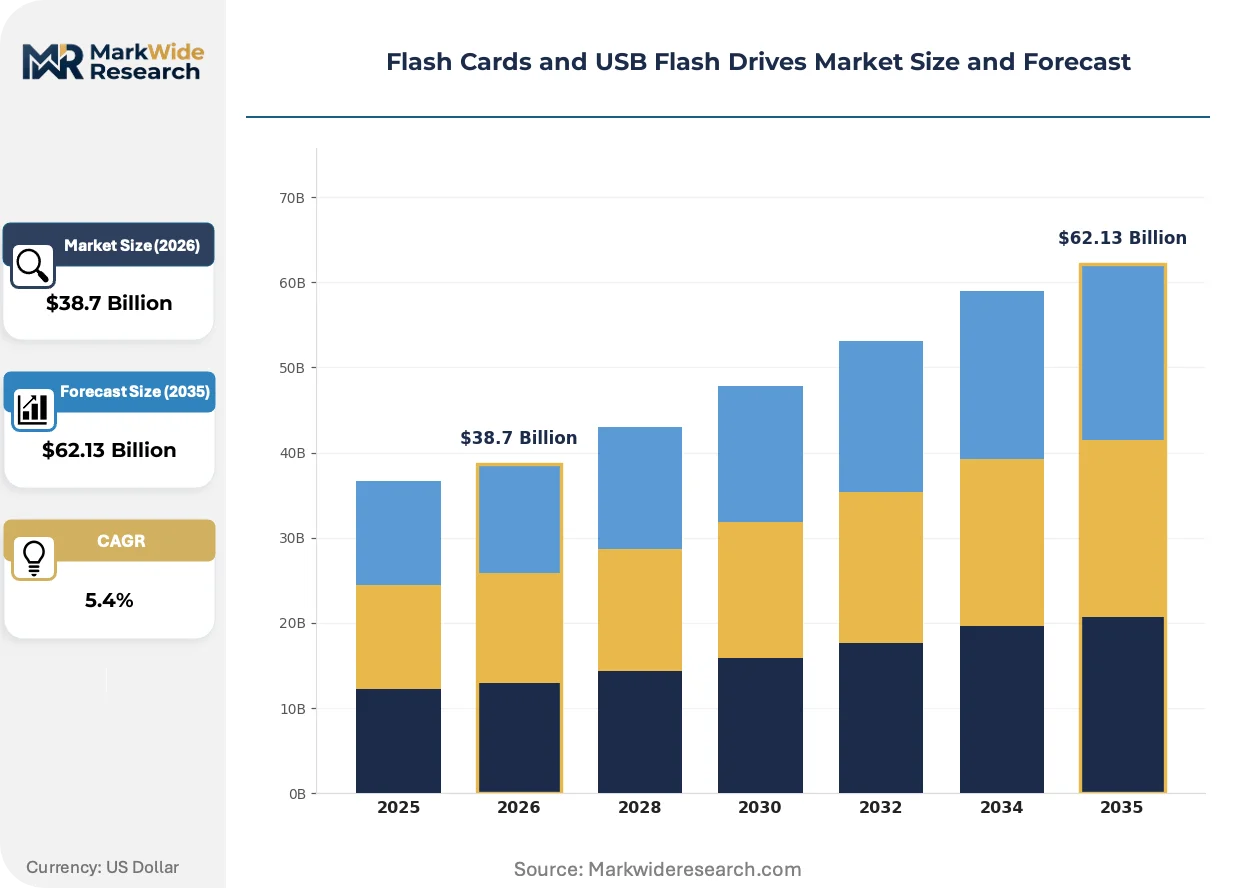
Market Dynamics
NAND flash memory process node transitions toward 3D stacking architectures are compressing cost-per-gigabyte curves while concentrating manufacturing capabilities among integrated device manufacturers with captive fabrication.
Growth Catalysts
- 4K Video Workflows:Professional content creators and imaging specialists are expanding procurement of high-capacity portable storage solutions. Bit-density economics at the 256GB tier are aligning with production-grade data requirements.
- CE Marking Compliance:EU RoHS Directive hazardous-substance documentation requirements are filtering out non-compliant vendors. Surviving suppliers are capturing displaced volume from exiting competitors.
- USB Type-C Standardization:Laptop manufacturers are eliminating legacy USB-A ports in favor of reversible connector protocols. This interface transition is refreshing replacement cycles across enterprise and consumer segments.
Market Restraints
- Captive NAND Supply Concentration:Integrated device manufacturers in South Korea and China control upstream wafer supply. Merchant memory vendors face allocation vulnerability during capacity tightness.
- Cloud Storage Substitution:Synchronous backup services and high-bandwidth connectivity are reducing physical media dependency for non-sensitive consumer data transport.
- GB/T 26225 Certification Burden:China's SAMR national standard for flash memory card performance creates localized testing requirements. Foreign manufacturers face extended approval timelines.
Strategic Opportunities
- Thermal-Engineered Gaming Segments:High-performance workloads are creating demand for heat-dissipating enclosures and sustained write speeds. Content creation and esports applications favor specialized form factors.
- Enterprise Controller Firmware:Vertically controlled security and encryption layers are differentiating enterprise-class USB drive procurement. Vertical integration into controller design is capturing compliance-sensitive accounts.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and test are attracting module-level investment. Localized production can circumvent import duty structures.
Industry Challenges
- 3D NAND Process Engineering Talent:176-layer and beyond architectures require specialized etch and deposition expertise. Foundries and memory houses compete for limited process integration specialists.
- REACH Substrate Compliance:ECHA substance restrictions on packaging materials are forcing reformulation of connector housings and PCB substrates. Reformulation cycles compress margin recovery windows.
- Legacy Interface Inventory Stranding:USB-A and micro-USB product lines face demand cliff risks as OEMs accelerate Type-C transitions. Write-down exposure concentrates in distributor and retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flash Cards and USB Flash Drives Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SD Cards, MicroSD Cards, USB Type-A Drives, USB Type-C Drives, CompactFlash Cards, Memory Sticks Storage Capacity: 4GB, 16GB, 32GB, 64GB, 128GB, 256GB End User: Consumers, Educational Institutions, Photographers, Corporate Offices, Content Creators, Government Agencies Distribution Channel: Online Retailers, Electronic Stores, Wholesale Distributors, Office Supply Stores, Specialty Shops |
| Companies Covered | Kingston Technology Corporation, SanDisk Corporation, Samsung Electronics, ADATA Technology Co., Ltd., Transcend Information, Inc., HP Inc., Toshiba, Corsair Components, Inc., Lexar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flash Cards and USB Flash Drives Market Shifts & Advancements
Interface protocol standardization and memory density scaling are simultaneously enabling new application categories and threatening incumbent product architectures across portable storage.
QLC NAND flash memory is supplanting TLC architectures in entry-level and archival-grade USB drives. Cost-sensitive enterprise backup applications are adopting QLC-based solutions despite endurance trade-offs. This density escalation is enabling terabyte-scale portable storage at sub-premium price positioning.
EU F-Gas Regulation phase-down schedules are constraining fluorinated gas availability for semiconductor etch processes. Memory foundries are retrofitting production lines with alternative chemistries. 3D NAND fabrication in European-adjacent supply chains faces process requalification delays.
Direct-to-procurement platforms are compressing distributor margins on standardized flash storage SKUs. Enterprise IT buyers are consolidating vendor lists and negotiating frame contracts with integrated manufacturers. This concentration is most visible in United States federal and healthcare sector purchasing.
Flash Cards and USB Flash Drives Market Segmentation
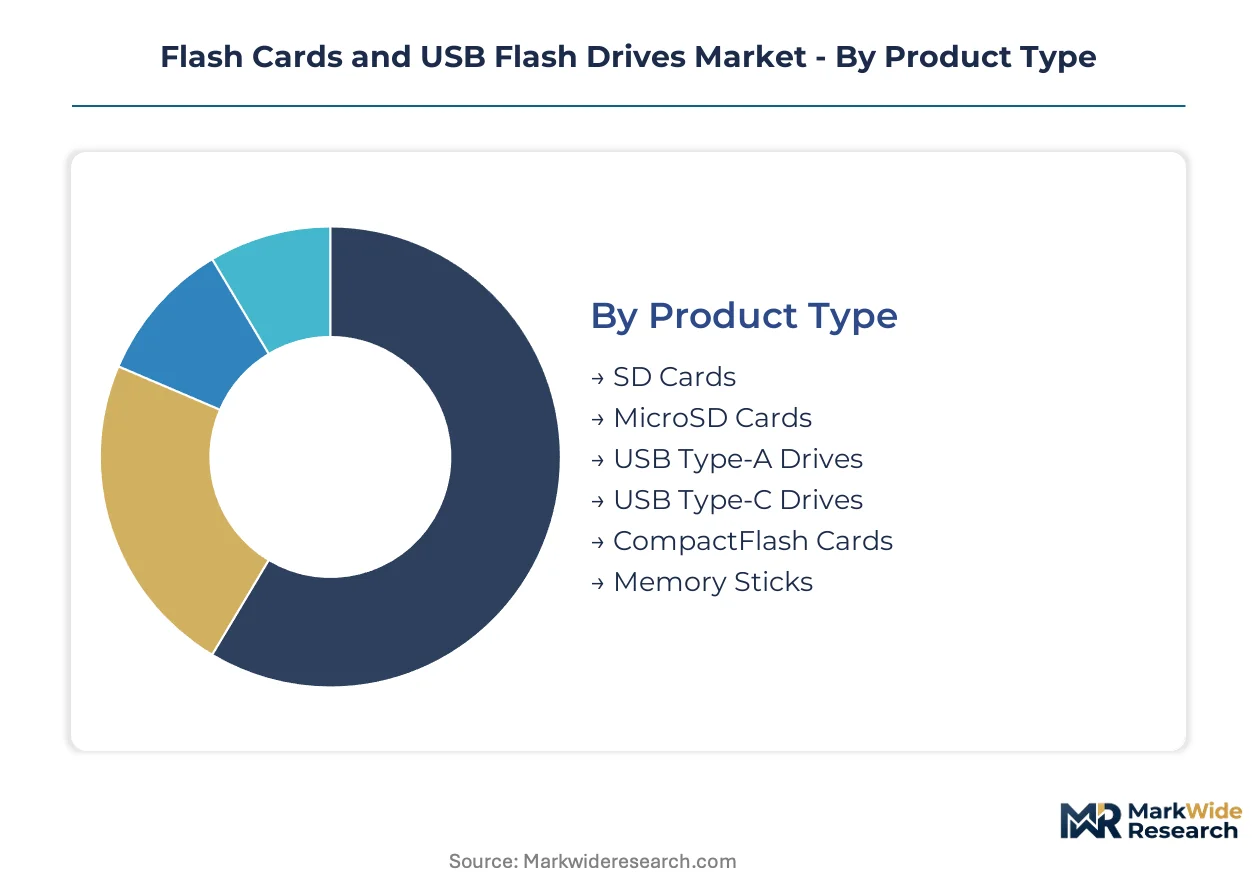
Segmentation in portable storage reveals divergent vulnerability to cloud substitution, interface obsolescence, and NAND cost curves. Each dimension carries distinct strategic implications for capacity planning, channel investment, and regional prioritization.
Product Type:
USB Type-A and MicroSD formats face the most acute substitution pressure as OEMs abandon legacy ports and smartphone manufacturers eliminate expandable storage slots.
- MicroSD Cards:Removable NAND storage in sub-15mm form factors, historically dominant in Android smartphones and action cameras. Demand concentrates in emerging market mobile users where device storage constraints persist despite cloud proliferation.
- USB Type-C Drives:Reversible connector solid-state storage with USB 3.2/4.0 protocol support, backward-compatible through adapter ecosystems. Procurement accelerates among laptop refresh cycles in the United States and China as OEMs standardize on Type-C-only chassis designs.
- SD Cards:Full-size flash memory cards maintaining relevance in professional imaging equipment and industrial applications requiring physical durability.
- USB Type-A Drives:Legacy rectangular connector storage facing demand cliff risks as enterprise IT departments accelerate Type-C migration timelines.
- CompactFlash Cards:Parallel ATA interface format retained in specialized industrial and broadcast video equipment with extended replacement cycles.
- Memory Sticks:Sony-proprietary format with residual installed base in legacy imaging and gaming hardware, minimal new design adoption.
USB Type-A anchors the volume base while USB Type-C gains share at the steepest rate.
Storage Capacity:
Cost-per-gigabyte compression at 256-layer 3D NAND nodes is collapsing price premiums across higher density tiers, reshaping procurement economics.
- 256GB:Highest bit-density tier with TLC/QLC architectures, optimized for 4K video workflows and professional content libraries. Procurement concentrates among imaging specialists in South Korea and the United States where production-grade data requirements justify premium positioning.
- 128GB:Mid-density segment balancing cost and capacity for mainstream consumer backup and transport applications. Volume concentrates in educational bulk purchasing and small business IT refresh cycles across China.
- 64GB:Entry-professional crossover tier serving document archives and compressed media libraries, vulnerable to cloud storage substitution in bandwidth-advantaged markets.
- 32GB:Legacy promotional and embedded application tier, declining as minimum viable capacity thresholds shift upward.
- 16GB:Residual tier for firmware distribution and industrial boot applications, minimal consumer relevance.
- 4GB:Niche archival and legacy system compatibility tier, sustained by industrial equipment with fixed storage requirements.
64GB and 128GB anchor the volume base while 256GB climbs the fastest on unit-value expansion.
End User:
Professional workflows with deterministic latency requirements resist cloud substitution more effectively than consumer backup applications.
- Content Creators:Video production professionals and streaming operators requiring high-throughput local storage for raw footage handling. Demand concentrates in Los Angeles and Seoul production clusters where 4K/8K pipelines demand sustained write performance.
- Photographers:Imaging specialists with field backup requirements and client deliverable workflows. Procurement prioritizes SD and CFexpress formats with weather sealing and shock resistance.
- Corporate Offices:Enterprise IT departments managing endpoint backup and secure data transport. Compliance requirements in healthcare and financial verticals favor hardware-encrypted USB solutions.
- Government Agencies:Federal and defense procurement with FIPS 140-2 certification mandates and air-gapped operational requirements.
- Educational Institutions:Bulk purchasing for student device programs and computer lab infrastructure, price-sensitive with standardized specifications.
- Consumers:General-purpose backup and file transport, most vulnerable to cloud substitution and smartphone-native storage expansion.
Consumers anchor the volume base while content creators expand most quickly on per-unit value growth.
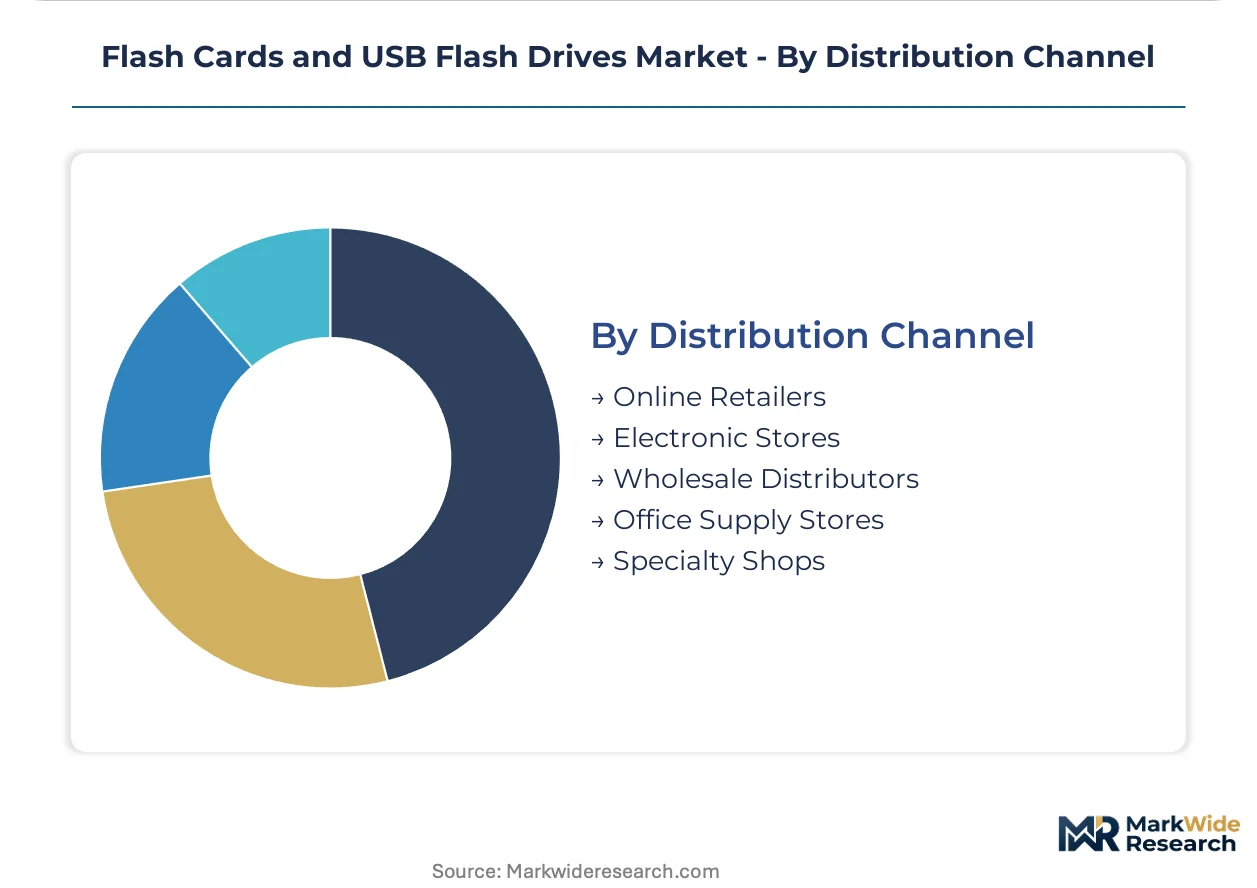
Distribution Channel:
Direct-to-procurement consolidation in enterprise segments is compressing traditional distributor margins while specialty channels retain differentiation.
- Online Retailers:E-commerce platforms with search-optimized SKU proliferation and price transparency. Amazon and Tmall capture consumer and small business procurement through fulfillment infrastructure.
- Electronic Stores:Brick-and-mortar electronics specialists with hands-on product comparison and immediate availability, retaining relevance for emergency replacement and gift purchasing.
- Wholesale Distributors:B2B volume aggregators serving system integrators and value-added resellers with credit terms and technical support.
- Office Supply Stores:Staples and Office Depot channels for corporate procurement card purchasing, standardized SKUs with minimal technical differentiation.
- Specialty Shops:Photography and gaming retailers with curated performance-tier selections and enthusiast customer relationships.
Online retailers anchor the volume base while specialty shops gain share fastest on premium segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT buyers and professional content creators concentrate procurement in the United States, China, and South Korea, where NAND fabrication clusters and consumer electronics ecosystems align most tightly. Regulatory compliance requirements in each jurisdiction reshape competitive access and channel economics.
United States
Federal healthcare and defense procurement drives hardware-encrypted USB demand with FIPS 140-2 certification mandates. FCC equipment authorization governs electromagnetic emissions for all distributed drives. Los Angeles production clusters anchor content creator procurement for 4K/8K video workflows requiring sustained write performance.
China
SAMR enforces GB/T 26225 national standards for flash memory card performance and interoperability, creating localized certification burdens for foreign manufacturers. Yangtze River Delta fabrication facilities concentrate 3D NAND wafer supply. Shenzhen electronics markets drive module-level assembly and test investment under PLI-equivalent incentives.
South Korea
Seoul production clusters house captive NAND fabrication enabling integrated device manufacturers to sustain cost leadership. MFDS-equivalent quality frameworks govern medical-grade storage applications. Busan-Ulsan industrial corridors anchor high-capacity memory card exports to imaging equipment OEMs.
Germany
CE marking under EU RoHS Directive filters non-compliant vendors from accessing industrial procurement channels. ECHA REACH substance restrictions force reformulation of connector housings and PCB substrates. Bavaria's precision engineering clusters specialize in thermal-engineered enclosures for enterprise applications.
Japan
METI industrial standards and JIS certification requirements shape enterprise storage procurement specifications. Kanto region electronics manufacturers maintain residual demand for specialized industrial formats. Nagoya automotive clusters drive embedded flash storage for manufacturing equipment with extended replacement cycles.
Flash Cards and USB Flash Drives Market Competitive Landscape
Player mix skews toward integrated device manufacturers with captive NAND fabrication and merchant memory vendors dependent on external wafer supply. Market structure concentrates upstream capabilities among South Korean and Chinese fabrication houses while downstream branding fragments across specialist and diversified electronics portfolios. Two strategic archetypes dominate: vertically integrated semiconductor houses controlling wafer-to-module supply chains, and fabless brand specialists competing on controller firmware and thermal engineering differentiation. Competitive moves center on 3D NAND capacity expansion and enterprise security certification acquisition.
Among integrated semiconductor houses, Samsung Electronics and Toshiba exemplify captive fabrication archetypes with upstream control over wafer supply. Kingston Technology Corporation occupies a position within the merchant memory tier, representing fabless brand specialists that differentiate through controller firmware development and vertically controlled security layers. ADATA Technology Co., Ltd. sits within the performance-specialist segment, exemplifying competitors that target thermal-engineered form factors for gaming and content creation workloads.
| Leading Market Players |
|---|
| Kingston Technology Corporation |
| SanDisk Corporation |
| Samsung Electronics |
| ADATA Technology Co., Ltd. |
| Transcend Information, Inc. |
| HP Inc. |
| Toshiba |
| Corsair Components, Inc. |
| Lexar |
| Others |
Supply & Pricing Matrix
Ninety-day NAND wafer inventory cycles at Yangtze River Delta foundries concentrate pricing power among integrated device manufacturers with captive fabrication, while merchant memory vendors absorb spot-market volatility through controller firmware differentiation. This lead-time compression amplifies margin pressure during capacity tightness and rewards backward integration into 3D NAND wafer supply.
Pricing Analysis
Cost-plus contracts indexed to spot NAND wafer pricing dominate procurement between module assemblers and merchant controller vendors. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 140-2 certified enterprise drives from consumer-grade USB storage and promotional-tier SKUs. Cost compression in the 128GB tier is intensifying because QLC NAND bit-density economics are collapsing price premiums. Educational institutions and bulk corporate purchasers exhibit highest price sensitivity, while government agencies with air-gapped security mandates show lowest.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane elevates inbound logistics costs for module-level assembly inputs sourced from Shenzhen electronics markets. NAND wafer supply concentrates in South Korea, China, and Taiwan, with controller IC design anchored in Taiwan and the United States. Raw material dependencies span silicon wafers, rare earth elements for connector plating, and brominated flame retardants for PCB substrates. Single-source vulnerability around 176-layer etch equipment creates supply chain risk. Distribution runs through wholesale distributors serving system integrators and direct-to-procurement platforms for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical NAND oversupply, with capital expenditure discipline at Yangtze River Delta foundries tightening wafer availability and restoring pricing power to integrated manufacturers.
For Market Incumbents: Secure captive 3D NAND wafer allocation through long-term foundry partnerships before capacity tightness accelerates. Defend enterprise accounts by accelerating FIPS 140-2 and hardware-encryption certification roadmaps against cloud storage substitution threats. Prioritize backward integration into controller firmware development to differentiate security layers and escape commodity pricing traps. For New Entrants and Emerging Players: Lead with thermal-engineered form factors targeting content creator and esports workloads where sustained write performance commands premium positioning. White-space opportunities concentrate in India's PLI-supported assembly and test corridors, circumventing import duty structures. Penetrate through specialty photography and gaming retail channels with curated performance-tier SKUs rather than competing on Amazon price transparency. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underperforming memory card divisions lacking captive NAND supply. Long-term viability over a five-to-ten-year horizon hinges on controller firmware intellectual property and security certification depth rather than brand equity alone. Monitor capital expenditure announcements from Yangtze River Delta foundries as the inflection signal for wafer pricing cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Firmware Acquisition | Captures enterprise security differentiation through vertically controlled encryption layers and FIPS compliance. |
| 3D NAND Capacity Expansion | Secures wafer supply allocation at 176-layer and beyond nodes, compressing cost-per-gigabyte curves. |
| India Manufacturing Localization | Circumvents import duty structures under PLI scheme incentives for semiconductor assembly and test. |
| USB Type-C Product Line Transition | Aligns with laptop OEM standardization on reversible connector protocols, avoiding legacy inventory stranding. |
| Enterprise Security Certification | Unlocks federal healthcare and defense procurement with FIPS 140-2 and hardware-encrypted USB mandates. |
Research Methodology
Cross-validation between primary interviews with NAND foundry procurement managers, controller IC design engineers, and enterprise IT storage administrators anchors the qualitative findings against secondary validation from customs wafer import records, SEC semiconductor segment disclosures, and SAMR GB/T 26225 certification databases. Bottom-up unit shipment estimates by capacity tier and product type triangulate against top-down NAND bit demand forecasts from foundry capacity modeling.
Sensitivity analysis across interface protocol transition speeds, cloud storage substitution elasticities, and regional regulatory compliance timelines shapes the analytical framework. Segmentation dimensions span product type, storage capacity tier, end-user vertical, and distribution channel. CAGRs derive from regression analysis of historical bit shipments against price elasticity curves. Industry-specific forecast inputs include 3D NAND layer migration schedules and EU F-Gas Regulation phase-down impacts on etch chemistry availability.
The analysis sits within stated boundaries; outcomes outside sustained NAND capital expenditure discipline, stable China-United States trade lane logistics, and gradual USB Type-C adoption curves would require recalibration. Forecasts reflect documented assumptions around wafer yield improvements and controller firmware development timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Business Card Holder Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Greetings Cards Market
Office Supplies
Diaries & Planners Market
Office Supplies
Stationery Market
Office Supplies
Global Office Stationery Market
Office Supplies
Dictionary Pen Market
Office Supplies
Office Supplies Market
Office Supplies
Letter Opener Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Copiers Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Stationery Products Market
Office Supplies
Cutter Staplers Market
Office Supplies
Erasable Ink Pen Market
Office Supplies
Writing Instruments Market