
 Greetings Cards Market | 2026-2036
Greetings Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Greetings Cards Market Analysis
Aftermarket personalization services is narrowing as a standalone revenue pool, with card manufacturers embedding custom-print tools directly into their core platforms. Hallmark Cards, Inc. leverages its vertically integrated supply chain to control production costs across paper sourcing and retail distribution. American Greetings Corporation anchors its position through licensed character portfolios that sustain recurring seasonal demand. Card Factory plc competes aggressively on price in the UK value segment while extending its online personalization capabilities.
Greetings cards are printed paper or cardstock products, typically measuring 4x6 to 5x7 inches, manufactured through offset lithography or digital printing processes, designed to convey personal messages for occasions such as birthdays, holidays, and life milestones. The Birthday product type dominates volume due to universal annual recurrence, while the Photo Card design style captures premium margins through digital integration and variable data printing. Recycled and eco-friendly materials are gaining structural share as retailer procurement policies tighten, though traditional paper grades still occupy the mass-market core. Online sales channels are reshaping distribution economics, reducing working capital requirements for inventory while demanding investment in last-mile fulfillment infrastructure.
The US EPA oversees paper product recycling standards and forestry certification requirements that shape material sourcing decisions for domestic manufacturers. The EU ECHA enforces REACH chemical compliance on inks, adhesives, and coatings used in card production exported to European markets. The UK's Environment Agency implements extended producer responsibility frameworks that increase cost accountability for packaging waste. Stakeholders must monitor how fragmented regulatory trajectories across major economies will fragment compliance costs and reshape supplier qualification criteria.

Market Dynamics
The greetings cards market faces structural pressure from EU Green Deal packaging waste directives, which are forcing manufacturers to reconfigure material sourcing and production workflows around recycled substrates and FSC-certified supply chains.
Growth Catalysts
- EU ECHA REACH compliance:Chemical safety mandates on inks and coatings are accelerating the shift to water-based, low-VOC formulations that appeal to environmentally conscious retailers.
- Digital-to-print hybrid technology:Variable data printing enables mass personalization at unit economics competitive with offset lithography, drawing Millennial and Gen Z consumers into higher-margin photo card segments.
- United States seasonal demand:Cultural retention of card-giving rituals for Christmas, Mother's Day, and Valentine's Day sustains recurring revenue pools that offset digital communication substitution elsewhere.
Market Restraints
- Pulp fiber cost volatility:Recycled paper grades command premiums of 15-40% over virgin stock, compressing margins for value-segment producers dependent on thin pricing spreads.
- Chinese substrate concentration:Specialty art papers and metallic boards for premium finishes flow through concentrated Asian supply nodes, exposing importers to freight rate swings and tariff uncertainty.
- Instant messaging substitution:WhatsApp, Instagram, and TikTok greetings displace casual card occasions among under-35 demographics, narrowing addressable volume in non-milestone segments.
Strategic Opportunities
- India urban gifting culture:Tier-1 cities exhibit rising card consumption for Diwali and weddings as organized retail expands, with local BIS standards creating compliance barriers that favor early entrants.
- Extended producer responsibility frameworks:UK Environment Agency mandates are pushing retailers to source from manufacturers with closed-loop recycling programs, rewarding certified suppliers with preferred vendor status.
- AR-enabled card experiences:Smartphone-activated augmented reality layers are collapsing the distinction between physical keepsakes and digital interaction, opening premium pricing tiers for tech-integrated products.
Industry Challenges
- Variable data printing talent scarcity:Prepress operators skilled in color-managed digital workflows command wage premiums that strain mid-tier manufacturers without captive training programs.
- Last-mile fulfillment capex intensity:Direct-to-consumer channels require investment in automated packaging lines and regional micro-fulfillment nodes to meet delivery speed expectations.
- FSC chain-of-custody certification timelines:Documentation audits and supplier qualification processes extend 12-18 months, delaying access to EU retail procurement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greetings Cards Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $27.44 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Birthday, Christmas, Thank You, Wedding Design Style: Traditional, Humorous, Artistic, Photo Card Material: Paper, Recycled, Eco-friendly, Metallic Sales Channel: Online, Retail Stores, Supermarkets, Stationery Shops |
| Companies Covered | Hallmark Cards, Inc., American Greetings Corporation, Card Factory plc, IG Design Group Plc, Avanti Press Inc., Galison Publishing LLC, Crane & Co., Archies Limited, Carlton Cards Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greetings Cards Market Emerging Trajectories
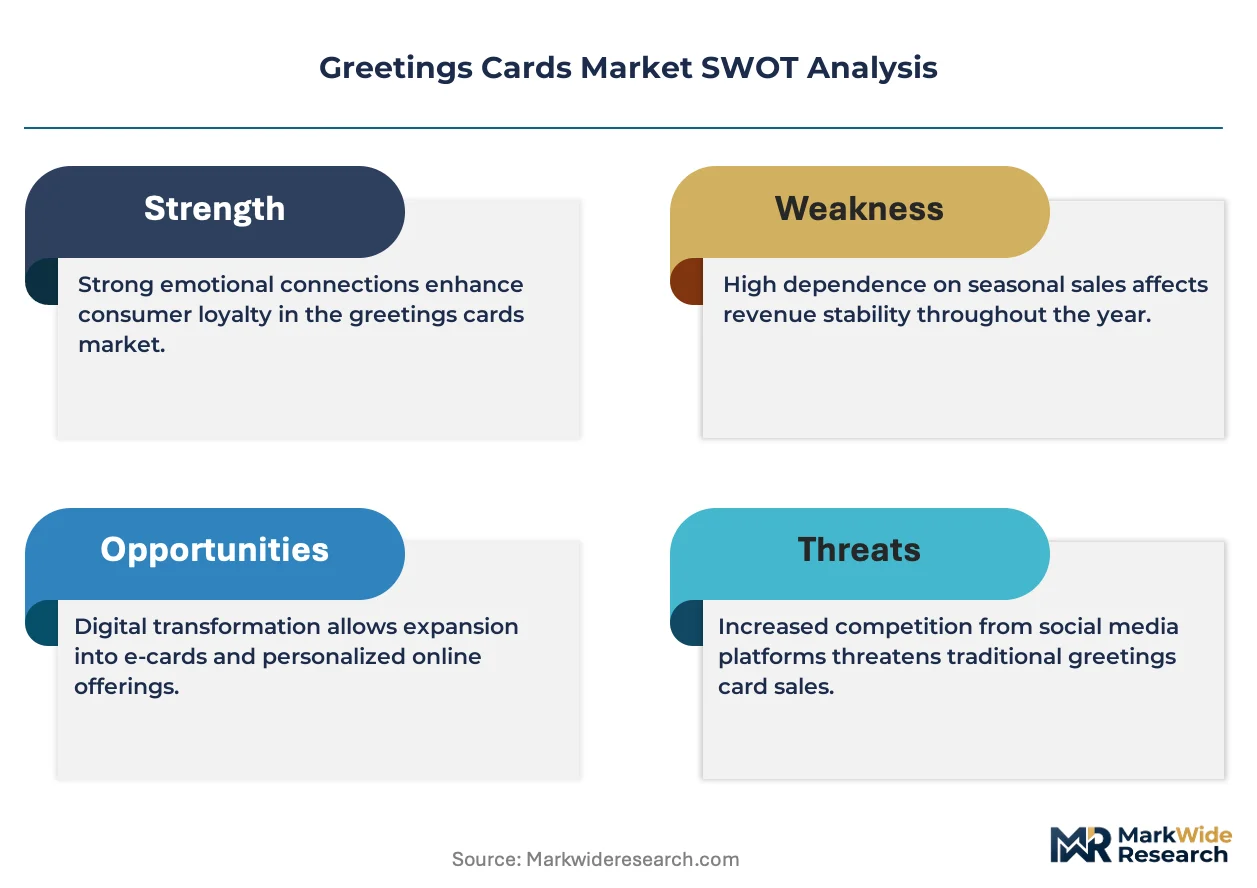
Three distinct vectors are restructuring competitive advantage in greetings cards: manufacturing technology convergence, regulatory compliance as a sourcing filter, and generational consumption pattern divergence that splits the market into ritual-driven and convenience-driven segments.
Variable data printing is collapsing the traditional trade-off between personalization scale and unit cost. Digital presses from HP Indigo and Xerox iGen enable single-pass production of unique card designs with photo integration and variable text. Specialty retailers and online pure-plays are adopting these systems to offer same-day turnaround on custom orders. The technology is collapsing minimum order quantities from thousands to single units, enabling on-demand inventory models that reduce working capital requirements by 30-50% for adopters.
REACH chemical restrictions enforced by EU ECHA are reshaping formulation strategies across the supply base. Ink manufacturers must substitute legacy phthalate-based plasticizers and heavy-metal pigments with bio-based alternatives that meet SVHC thresholds. The regulatory pressure falls most heavily on greeting card exporters targeting EU markets, who are consolidating supplier relationships around certified chemical houses with documented compliance dossiers.
Subscription-based card services are displacing occasion-driven purchase patterns among time-constrained urban professionals. Companies like Papier and Moonpig bundle annual card allotments with reminder algorithms and pre-stamped envelopes, capturing recurring revenue streams. The model exhibits strongest traction in United Kingdom and United States metropolitan markets where convenience premiums outweigh unit cost sensitivity.
Greetings Cards Market Segmentation
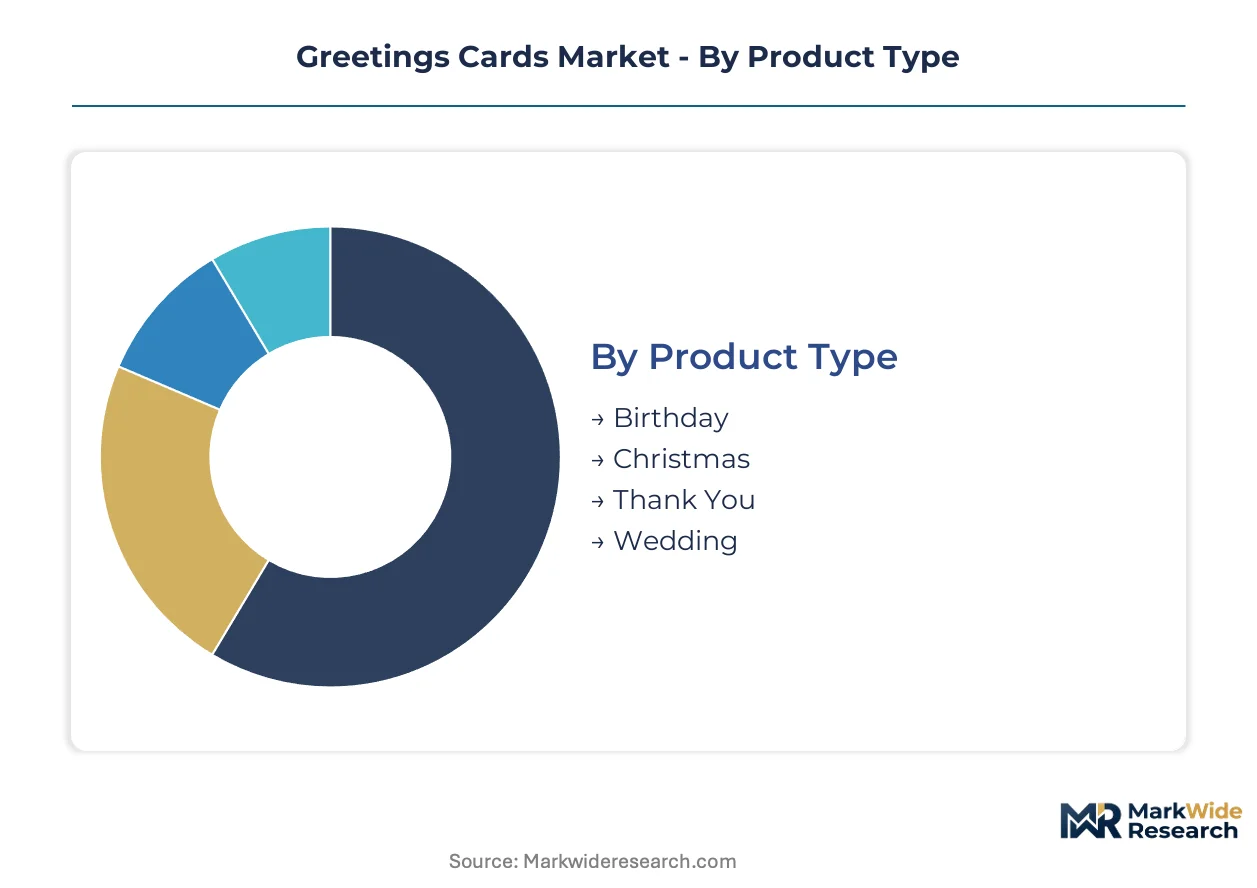
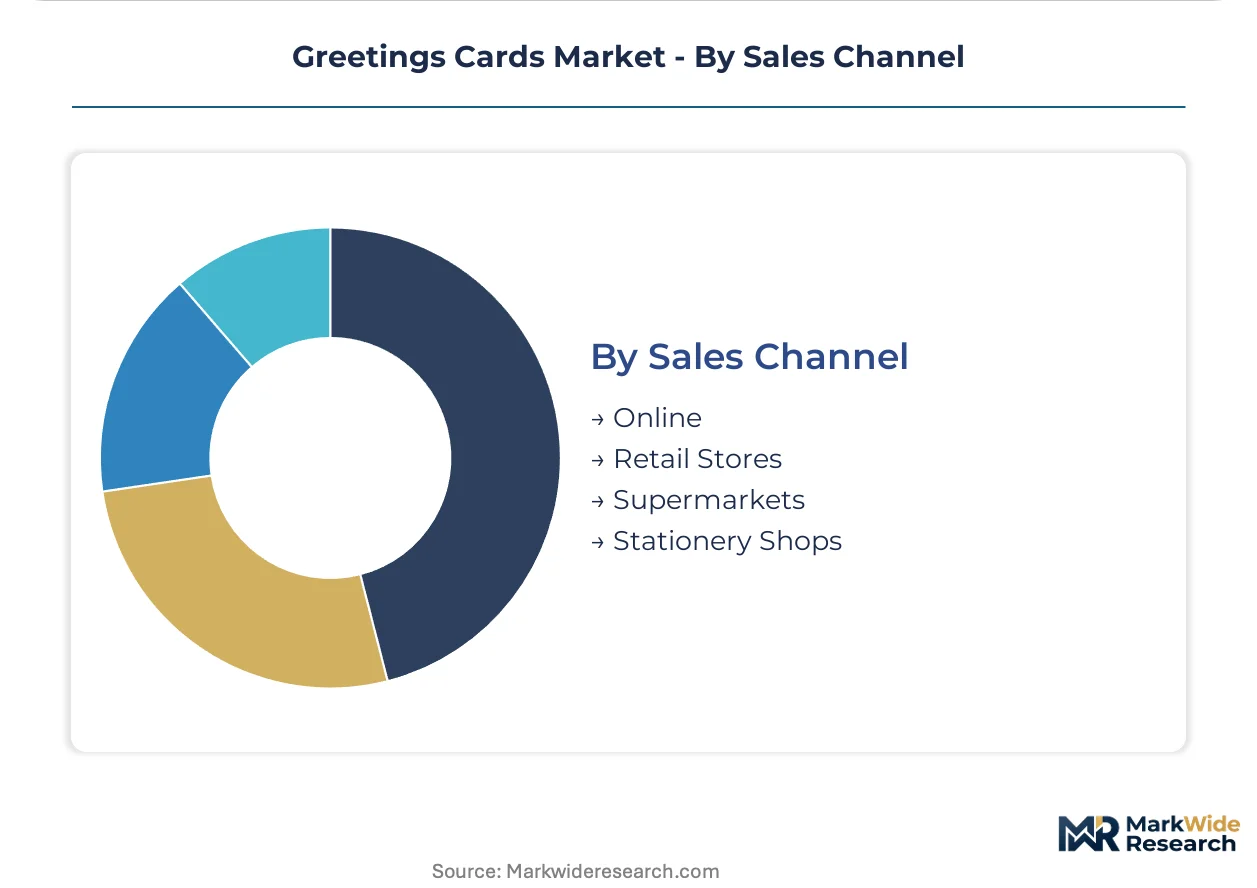
Greetings cards fragment across four distinct category axes that reshape procurement priorities and margin structures. Product type and material composition determine manufacturing workflows, while design style and sales channel govern pricing power and working capital intensity.
Product Type:
Mature occasion-driven segments anchor volume stability alongside emerging niche formats that capture premium positioning.
- Birthday:Annual recurrence across all demographics sustains the highest absolute unit demand. United States retailers stock Birthday SKUs year-round, with seasonal promotional cycles compressing margins during competitive windows.
- Christmas:Concentrated fourth-quarter demand drives 40-50% of annual revenue for specialty manufacturers. EU Green Deal packaging mandates are forcing Christmas card producers toward FSC-certified substrates ahead of other product lines.
- Thank You:Post-wedding and post-event consumption clusters in metropolitan United States markets. Digital communication substitution has compressed volume in under-35 demographics.
- Wedding:Invitation-adjacent positioning commands premium pricing through letterpress and foil-stamp finishes. Indian tier-1 cities exhibit expanding demand as organized retail penetrates gifting culture.
Birthday retains volume leadership; Photo Card holds the steepest expansion curve.
Design Style:
Cost tier stratification separates mass-market lithography from premium variable-data production.
- Traditional:Offset-printed cardstock with embossed or foil elements dominates supermarket and drugstore channels. United Kingdom value retailers source Traditional designs from high-volume Asian converters.
- Humorous:Licensed character integration and copy-driven differentiation sustain recurring seasonal demand. American Greetings Corporation anchors market position through captive IP portfolios.
- Artistic:Specialty illustration and limited-edition prints command 3-5x unit premiums over mass-market equivalents. Stationery Shops in Germany and France curate Artistic selections as destination categories.
- Photo Card:Variable data printing enables single-unit production with consumer-uploaded imagery and personalized text. HP Indigo and Xerox iGen installations are climbing fastest among online pure-plays serving Millennial and Gen Z consumers.
Traditional maintains channel breadth; Photo Card gains share fastest among digital-native demographics.
Material:
Supply concentration in Asian pulp markets shapes cost volatility across substrate grades.
- Paper:Virgin fiber cardstock remains the mass-market standard for Retail Stores and Supermarkets. Chinese substrate concentration exposes importers to freight rate swings and tariff uncertainty.
- Recycled:Post-consumer waste content of 30-100% commands 15-40% premiums over virgin grades. UK Environment Agency extended producer responsibility frameworks are accelerating Retail Store procurement shifts toward certified suppliers.
- Eco-friendly:Seed-embedded and plantable substrates appeal to sustainability-positioned brands in EU markets. FSC chain-of-custody certification timelines of 12-18 months delay supplier qualification for smaller manufacturers.
- Metallic:Specialty art papers and mirror boards for premium finishes flow through concentrated Asian supply nodes. Tariff exposure and ocean freight volatility compress margins for importers dependent on Metallic substrates.
Paper retains unit volume dominance; Eco-friendly climbs the fastest as retailer procurement policies tighten.
Sales Channel:
Customer type divergence splits the market between ritual-driven in-store purchase and convenience-driven digital subscription.
- Online:Direct-to-consumer platforms reduce working capital requirements by 30-50% through on-demand inventory models. Last-mile fulfillment capex intensity demands automated packaging lines and regional micro-fulfillment nodes.
- Retail Stores:Specialty card shops and gift boutiques sustain premium pricing through curated merchandising. Hallmark Cards leverages vertically integrated supply chains to control production costs across paper sourcing and retail distribution.
- Supermarkets:High-velocity impulse placement drives volume in Birthday and Thank You segments. Value-segment producers compete aggressively on price with thin pricing spreads.
- Stationery Shops:Destination positioning for Artistic and Wedding formats supports premium-mid-economy pricing differentiation. United Kingdom metropolitan markets exhibit strongest traction for bundled subscription services.
Retail Stores sustain margin leadership; Online expands most quickly as variable data printing collapses minimum order quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty paper mills and converting operations cluster in Germany, China, and the United States, creating supply dependencies that ripple through finished card pricing. Finished goods distribution gravitates toward retail-dense metropolitan corridors where seasonal demand concentrates. Regulatory divergence across major economies is fragmenting compliance costs and reshaping supplier qualification criteria.
United States
Christmas, Mother's Day, and Valentine's Day card-giving rituals sustain recurring revenue pools that offset digital substitution elsewhere. The EPA oversees paper product recycling standards and forestry certification requirements that shape domestic material sourcing decisions. Kansas City and Minneapolis-St. Paul anchor Hallmark's vertically integrated production and distribution network.
Germany
Stationery shops in Berlin, Munich, and Hamburg curate artistic card selections as destination categories commanding premium-mid-economy pricing differentiation. ECHA REACH chemical compliance mandates on inks and coatings are accelerating shifts to water-based, low-VOC formulations. The Rhine-Ruhr industrial corridor hosts specialized converters serving EU-wide retail procurement.
United Kingdom
Subscription-based card services exhibit strongest traction in London and Manchester metropolitan markets where convenience premiums outweigh unit cost sensitivity. The Environment Agency implements extended producer responsibility frameworks that increase cost accountability for packaging waste. Yorkshire and the Midlands concentrate value-segment production for supermarket channels.
India
Tier-1 cities including Mumbai, Delhi-NCR, and Bangalore exhibit rising card consumption for Diwali and weddings as organized retail expands gifting culture. BIS standards create compliance barriers that favor early entrants with certified supply chains. Tamil Nadu and Gujarat host emerging converting capacity serving domestic and export markets.
China
Pearl River Delta and Yangtze River Delta clusters dominate specialty art paper and metallic board production for premium card finishes. Concentrated substrate supply exposes importers to freight rate swings and tariff uncertainty. Domestic demand concentrates in Shanghai, Beijing, and Shenzhen for wedding and festival occasions.
Greetings Cards Market Vendor Landscape
Vertically integrated legacy manufacturers and digital-native personalization platforms split the market into divergent margin structures. Consolidation pressures concentrate around scale-driven procurement leverage and captive distribution networks. Three archetypes dominate: heritage brands with retail footprints, online pure-plays with variable data printing infrastructure, and value-segment converters competing on price. Competitive moves center on backward integration into paper sourcing and technology licensing for hybrid digital-to-print workflows.
Among heritage manufacturers with captive retail networks, Hallmark Cards, Inc. and American Greetings Corporation exemplify the vertically integrated archetype controlling production costs across paper sourcing and distribution. Card Factory plc occupies a position within the UK value segment while extending online personalization capabilities. These three anchors illustrate how strategic positioning around supply chain control, licensed character portfolios, and price-competitive digital expansion define competitive differentiation in the current market structure.
| Leading Market Players |
|---|
| Hallmark Cards, Inc. |
| American Greetings Corporation |
| Card Factory plc |
| IG Design Group Plc |
| Avanti Press Inc. |
| Galison Publishing LLC |
| Crane & Co. |
| Archies Limited |
| Carlton Cards Ltd. |
| Others |
Supply Flow & Price Mechanics
Pearl River Delta paper mills anchor substrate cost dynamics for premium card finishes, with their capacity utilization rates transmitting directly into downstream pricing power for converters dependent on metallic and art-grade stocks. EU Green Deal packaging mandates and US EPA forestry certification requirements are reshaping procurement premiums across virgin and recycled fiber grades.
Pricing Analysis
After-sales personalization services drive lifetime value as subscription bundles displace transactional occasion-based purchasing. Three-tier pricing structure across premium, standard, and economy levels separates photo-integrated variable data products from mass-market offset lithography and value-segment imports. Pricing pressure stems from recycled fiber premiums of 15-40% over virgin stock, compressing margins for thin-spread producers. Supermarket channel buyers exhibit highest price sensitivity, while stationery shop curators accept premium-mid-economy pricing differentiation for limited-edition artistic formats.
Supply Chain Analysis
Contract-manufacturing concentration sits with Pearl River Delta and Yangtze River Delta converters for specialty art papers and metallic boards, with Tamil Nadu and Gujarat emerging for domestic Indian supply. Raw material dependencies center on Chinese pulp fiber, FSC-certified recycled grades, and water-based ink formulations compliant with EU ECHA REACH thresholds. Single-source vulnerability runs through concentrated Asian substrate nodes exposed to ocean freight volatility and tariff uncertainty. Distribution runs through vertically integrated retail networks, direct-to-consumer platforms with regional micro-fulfillment nodes, and high-velocity supermarket impulse placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as subscription-based platforms aggregate demand and consolidate supplier relationships, fragmenting traditional occasion-driven purchase patterns into recurring revenue capture.
For Market Incumbents: Pre-empt digital-native entrants by embedding variable data printing infrastructure directly into core platforms rather than treating personalization as aftermarket add-on. Captive FSC chain-of-custody certification investment defends preferred vendor status under UK Environment Agency extended producer responsibility frameworks. Backward integration into recycled fiber sourcing insulates margin compression from pulp cost volatility.
For New Entrants and Emerging Players: Tier-1 Indian cities exhibit rising card consumption for Diwali and weddings with BIS standards creating compliance barriers favoring early certified entrants. White-space targets include AR-enabled card experiences collapsing physical-digital boundaries and closed-loop recycling programs qualifying for retailer procurement preference. Go-to-market leverage rests on same-day personalization turnaround via HP Indigo or Xerox iGen installations.
For Investors and Strategic Acquirers: Carve-out targets emerge from heritage manufacturers with captive retail footprints but underutilized digital infrastructure. Long-term viability frames around subscription model conversion rates and variable data printing capacity utilization as ritual-driven segments face messaging substitution. Monitor WhatsApp and TikTok greeting adoption curves as inflection signals for non-milestone volume erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Variable Data Printing Infrastructure Deployment | HP Indigo and Xerox iGen installations enable single-unit production at offset-competitive unit economics. |
| FSC Chain-of-Custody Certification Investment | Documentation audits qualify suppliers for EU Green Deal procurement pipelines and UK Environment Agency preferred status. |
| Subscription Model Conversion | Papier-style annual allotments with reminder algorithms capture recurring revenue from time-constrained urban professionals. |
| Closed-Loop Recycling Program Development | Retailer sourcing mandates under extended producer responsibility frameworks reward certified environmental compliance. |
| AR-Enabled Product Layer Integration | Smartphone-activated experiences command premium pricing tiers by collapsing physical keepsake and digital interaction boundaries. |
Methodological Framework
Cross-validation between primary interviews with paper mill procurement directors, retail category buyers, and digital platform operations heads and secondary sources including customs trade records, FSC certification databases, and SEC filings anchors the qualitative findings. Prepress operators and ink formulation chemists provided technical validation on REACH compliance workflows. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Calibration against historical volume trajectories and elasticity assumptions shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type, design style, material composition, and sales channel with regional regulatory cluster overlays. CAGRs derive from fitted growth curves incorporating substitution elasticity estimates for digital communication platforms and generational cohort purchasing pattern shifts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play digital entrants or regulatory acceleration beyond EU Green Deal timelines would shift outcomes. Quarterly review of recycled fiber spot premiums, FSC certification backlog durations, and subscription platform customer acquisition costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Stationery Market
Office Supplies
Cutter Staplers Market
Office Supplies
Diaries & Planners Market
Office Supplies
Copiers Market
Office Supplies
Stamp Pad Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Custom Binders Market
Office Supplies
Erasable Ink Pen Market
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Office Supplies Market
Office Supplies
Stationery Products Market
Office Supplies
Dictionary Pen Market
Office Supplies
Student Stationery Market
Office Supplies
School Stationery Supplies Market