
 Latin America School Stationery Supplies Market | 2026-2036
Latin America School Stationery Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America School Stationery Supplies Market Intelligence
INMETRO certification for child-safe school materials is unwinding the competitive landscape for imported stationery brands. BIC Group leverages its manufacturing footprint in Brazil to sustain cost advantages across the mid-range pen segment. Faber-Castell AG anchors premium positioning through specialized graphite grading systems and art supply portfolios. Tilibra dominates domestic notebook production with integrated pulp-to-binding operations serving Southeast Brazilian school districts.
Latin America school stationery supplies encompass writing instruments, paper goods, and art materials manufactured to specifications for daily academic use, with notebooks typically bound by spiral wire or thermal glue processes to withstand repetitive handling. These products serve institutional procurement cycles aligned to academic calendars and household back-to-school purchasing patterns. The product type dimension shows pens and notebooks capturing the largest volume share, while markers represent the fastest-growing category as visual learning methods expand in primary education. Distribution channel dynamics reveal retail stores maintaining the dominant transaction volume, though online marketplaces are capturing incremental share where urban logistics infrastructure permits direct-to-family fulfillment.
Brazil's INMETRO and Mexico's PROFECO enforce product safety and labeling standards that determine which suppliers qualify for public school tenders across the two largest national markets. ANVISA in Brazil and COFEPRIS in Mexico regulate chemical content in markers and adhesives, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving procurement centralization policies as ministries of education in Colombia and Chile consolidate purchasing authority under federal frameworks.
Market Dynamics
INMETRO certification mandates for child-safe art materials are restructuring supplier qualification criteria across Brazil's public procurement channels, forcing import-dependent brands to establish local testing partnerships or exit institutional tenders entirely.
Growth Catalysts
- Urban enrollment corridors:Mexico's metropolitan education zones are expanding faster than regional averages, concentrating household back-to-school demand in Mexico City, Guadalajara, and Monterrey distribution nodes.
- PROFECO labeling enforcement:Mexico's consumer protection agency is tightening origin and safety disclosure requirements, advantaging domestic manufacturers with established compliance documentation.
- Visual learning adoption:Primary education institutions are expanding marker and colored pencil procurement as project-based pedagogies replace traditional rote instruction methods.
Market Restraints
- Pulp input volatility:Integrated notebook producers face margin compression from fluctuating eucalyptus pulp prices, with Southeast Brazilian mills exposed to export market competition for fiber supply.
- Import certification timelines:ANVISA chemical content reviews for adhesives and solvents are extending lead times for Asian-sourced art material shipments by 8-14 weeks.
- Digital substitution pressure:Tablet and stylus adoption in upper-secondary private schools is compressing long-term demand for traditional writing instruments in premium price tiers.
Strategic Opportunities
- Colombian procurement centralization:The Ministry of National Education's consolidation of regional purchasing authority creates single-tender access to previously fragmented departmental school systems.
- E-commerce logistics maturation:São Paulo and Rio de Janeiro last-mile networks now support direct-to-family fulfillment for back-to-school seasons, bypassing traditional retail markups.
- Chilean federal framework expansion:The Ministry of Education's national supply program is absorbing municipal procurement functions, opening volume contracts for qualified stationery suppliers.
Industry Challenges
- COFEPRIS chemical registry gaps:Mexican health authority substance databases lack harmonization with US and EU equivalents, forcing duplicate toxicity testing for marker and adhesive formulations.
- Spiral binding equipment obsolescence:Domestic notebook producers face capital replacement cycles for wire-forming machinery as thermal glue processes gain share in premium segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America School Stationery Supplies Market |
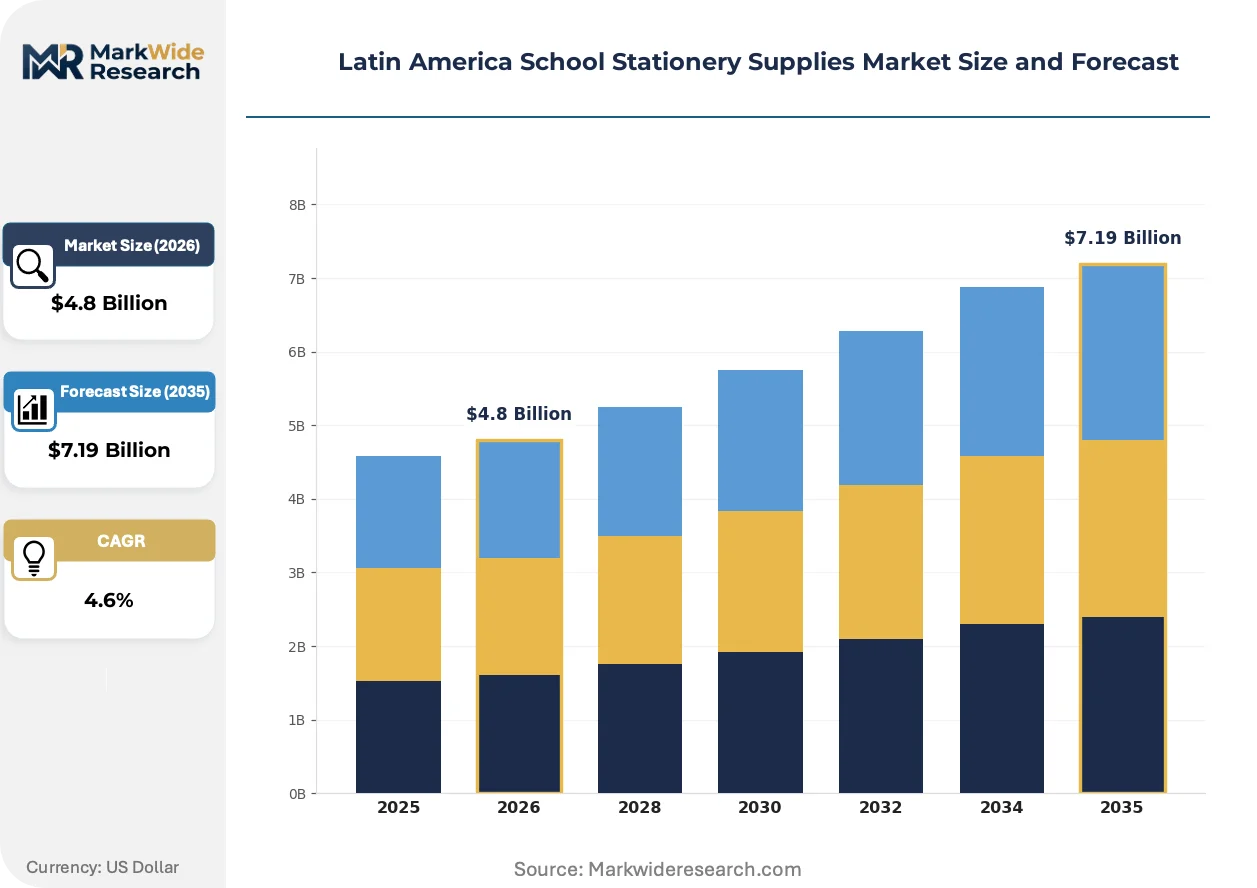
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pens, Pencils, Notebooks, Markers End User: Students, Teachers, Schools, Families Distribution Channel: Retail Stores, Online Marketplaces, Wholesale, Direct Sales Price Tier: Premium, Mid-range, Economy, Discounted |
| Companies Covered | Maped, Kokuyo Co., Ltd., BIC Group, Canson, Tratto, Faber-Castell AG, Staedtler Mars GmbH & Co. KG, Tilibra, Pilot Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America School Stationery Supplies Market Strategic Shifts & Innovations
Product safety certification is becoming the primary axis of competitive differentiation, with regulatory compliance investments now determining which suppliers qualify for institutional volume contracts across Latin America's two largest education markets.
Erasable gel ink formulations are fragmenting the traditional pen category by combining the permanence expectations of examination settings with the error-correction convenience demanded by primary-grade learners. Private K-12 institutions in São Paulo and Mexico City are piloting these hybrid instruments at scale. The technology is fragmenting procurement specifications that previously separated "exam-grade" from "practice-grade" writing tools into a single replaceable product tier.
Brazil's INMETRO Ordinance 563 is mandating child-resistant caps and non-toxic pigment disclosure for all art materials sold through public school channels. The regulation is disqualifying uncertified imports from federal procurement platforms and redirecting volume toward domestic manufacturers with accredited testing laboratories. Southeast Brazilian school districts are experiencing the fastest compliance transition as INMETRO maintains its regional certification hub in São Paulo.
Direct-to-family e-commerce fulfillment is displacing traditional retail back-to-school purchasing in urban corridors where logistics infrastructure permits scheduled delivery. Online marketplaces are capturing incremental share from stationery chains by bundling writing instruments, notebooks, and art supplies into academic-calendar-aligned kits. This channel migration is most visible in Mexico City's metropolitan zone, where enrollment growth and delivery density create viable unit economics for platform operators.
Latin America School Stationery Supplies Market Segmentation
Segmentation in Latin America's school stationery market reveals how regulatory certification and channel evolution create divergent competitive arenas. Each dimension carries distinct margin profiles and substitution vulnerabilities that reshape supplier positioning across Brazil, Mexico, and Colombia.
Product Type:
Digital substitution pressure varies sharply across writing implements versus paper goods, with art materials facing the weakest electronic displacement threat.
- Pens:Gel and ballpoint formulations dominate institutional procurement specifications. Brazil's INMETRO-certified manufacturers capture public tender volumes in Southeast districts where examination-grade permanence requirements are strictest.
- Notebooks:Spiral-bound and thermal-glued variants withstand repetitive academic handling. Integrated pulp-to-binding producers in Brazil's Southeast region defend margin positions against import competition through captive fiber supply.
- Pencils:Graphite grading systems differentiate premium positioning from commodity utility. Faber-Castell's specialized hardness scales anchor art education segments in private K-12 institutions.
- Markers:Non-toxic pigment formulations face ANVISA chemical content reviews extending Asian import lead times. Visual learning adoption in primary education drives procurement expansion fastest among all product types.
Notebooks retain volume leadership; markers hold the steepest expansion curve.
End User:
Procurement authority concentration determines which customer types offer scalable contract access versus fragmented household purchasing.
- Students:Individual back-to-school purchasing concentrates in Mexico City's metropolitan corridor where enrollment growth outpaces regional benchmarks. Erasable gel ink adoption is highest among primary-grade learners seeking error-correction convenience.
- Schools:Institutional tenders across Brazil's federal procurement platforms require INMETRO certification for art materials and child-safe cap designs. Centralized purchasing authority in Colombia's Ministry of National Education creates single-access contracts for qualified suppliers.
- Teachers:Classroom supply replenishment follows academic calendar cycles with lower per-transaction values. Marker and colored pencil procurement expands as project-based pedagogies replace rote instruction methods.
- Families:Direct-to-fulfillment e-commerce penetration is deepest in São Paulo and Rio de Janeiro where last-mile density supports scheduled back-to-season delivery. Bundle purchasing of writing instruments, notebooks, and art supplies displaces traditional retail transactions.
Schools dominate institutional contract value; families show the fastest channel migration toward platform-based fulfillment.
Distribution Channel:
Logistics infrastructure maturity creates divergent unit economics across physical and digital fulfillment paths.
- Retail Stores:Stationery chains maintain dominant transaction volume through tactile product evaluation and immediate availability. Traditional back-to-school seasonal peaks concentrate purchasing in July-August windows across Latin American academic calendars.
- Online Marketplaces:São Paulo and Mexico City delivery networks now support viable direct-to-family economics. Platform operators bundle multi-product academic kits aligned to specific grade-level requirements.
- Wholesale:Regional distributors serve fragmented municipal school systems in Colombia and Chile before federal procurement consolidation. Inventory pooling reduces working capital requirements for mid-range product tiers.
- Direct Sales:Premium art material manufacturers cultivate institutional relationships through specialized catalog offerings. Direct engagement bypasses retail markups in private K-12 segments where graphite grading and pigment quality drive selection.
Retail stores capture the largest transaction count; online marketplaces are climbing the fastest in urban enrollment corridors.
Price Tier:
Certification grade and volume scale separate competitive positioning across cost strata.
- Premium:Specialized graphite grading systems and non-toxic pigment disclosure command price premiums in private K-12 institutions. ANVISA and COFEPRIS compliance documentation adds fixed cost layers that smaller import brands cannot absorb.
- Mid-range:Branded writing instruments from Brazil-based manufacturers leverage local production footprints for cost advantage. BIC Group sustains positioning through integrated manufacturing serving Southeast Brazilian school districts.
- Economy:Unbranded commodity pens and notebooks compete on unit cost in public procurement tenders. Pulp input volatility from eucalyptus fiber export competition compresses margin sustainability for integrated producers.
- Discounted:Seasonal clearance inventory and bulk academic kit offerings target price-sensitive family purchasing. Thermal glue notebook processes gain share over spiral binding in this tier due to lower capital equipment requirements.
Mid-range tiers capture the broadest institutional access; premium segments show the strongest certification-based pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional procurement authority concentrates in federal education ministries across Brazil and Mexico, while household purchasing clusters in metropolitan enrollment corridors. Regional differentiation stems from certification requirements, logistics maturity, and centralization policies that reshape supplier access.
Brazil
Southeast Brazilian school districts drive volume demand through São Paulo's metropolitan procurement zones. INMETRO Ordinance 563 mandates child-resistant caps and non-toxic pigment disclosure for art materials entering federal tender platforms. São Paulo anchors the regional certification hub where domestic manufacturers with accredited testing laboratories capture institutional volume.
Mexico
Metropolitan education corridors in Mexico City, Guadalajara, and Monterrey concentrate household back-to-school purchasing beyond regional benchmarks. PROFECO labeling enforcement tightens origin and safety disclosure requirements, advantaging domestic manufacturers with established compliance documentation. Mexico City's delivery density enables direct-to-family e-commerce fulfillment that bypasses traditional retail markups.
Colombia
The Ministry of National Education consolidates regional purchasing authority under federal frameworks, creating single-tender access to previously fragmented departmental school systems. National procurement centralization absorbs municipal supply functions that previously required multiple distributor relationships. Bogotá's administrative concentration positions the capital as the primary channel for qualified supplier registration.
Chile
The Ministry of Education's national supply program expands federal framework coverage over municipal procurement functions. Volume contracts open for qualified stationery suppliers as centralization eliminates fragmented municipal tender processes. Santiago's metropolitan zone concentrates enrollment growth and institutional purchasing authority.
Argentina
Provincial education ministries maintain decentralized procurement structures that preserve regional distributor networks. Economic volatility compresses household purchasing power toward economy-tier products in back-to-school cycles. Buenos Aires anchors the largest metropolitan enrollment base with concentrated demand for mid-range writing instruments.
Latin America School Stationery Supplies Market Key Industry Players
Player mix skews toward integrated domestic manufacturers and multinational specialists with regional production footprints. Market structure shows moderate concentration at the premium tier and fragmentation across economy segments. Two strategic archetypes dominate: certification-compliant institutional suppliers and brand-positioned specialists in art materials. Competitive moves center on local testing partnerships for regulatory access and e-commerce logistics investments for urban household penetration.
Among European-headquartered specialists, Faber-Castell AG and Staedtler Mars GmbH & Co. KG occupy positions anchored by graphite grading expertise and art supply portfolios. Japanese manufacturers represented by Kokuyo Co., Ltd. and Pilot Corporation exemplify technology-driven positioning in writing instrument segments. These named entities sit within a broader competitive set where geographic origin and product specialization determine tier access rather than scale alone.
| Leading Market Players |
|---|
| Maped |
| Kokuyo Co., Ltd. |
| BIC Group |
| Canson |
| Tratto |
| Faber-Castell AG |
| Staedtler Mars GmbH & Co. KG |
| Tilibra |
| Pilot Corporation |
| Others |
Cost & Logistics Intelligence
Thermal glue binding processes displacing spiral wire in premium notebook segments simultaneously concentrates production geography in Brazil's Southeast pulp belt and compresses capital equipment costs for domestic manufacturers competing against import-dependent brands. This substitution dynamic tightens margin structures across mid-tier producers while rewarding integrated pulp-to-binding operators with captive fiber supply.
Pricing Analysis
Cost-plus contracts indexed to eucalyptus pulp futures dominate notebook procurement agreements between Southeast Brazilian mills and federal school districts. Three-tier pricing structure across premium, standard, and economy levels separates INMETRO-certified art materials from uncertified imports and commodity unbranded alternatives. Pricing pressure stems from export market competition for eucalyptus fiber that elevates input costs for integrated producers. Public procurement tenders show highest price sensitivity, while private K-12 institutions absorb premium positioning for specialized graphite grading and non-toxic pigment disclosure.
Supply Chain Analysis
Brazil and Mexico anchor regional manufacturing for writing instruments and paper goods, while Asian suppliers feed art material components subject to ANVISA chemical content reviews. Raw material dependencies center on eucalyptus pulp, petroleum-derived plastics for pen barrels, and titanium dioxide pigments for marker formulations. Single-source vulnerability concentrates in thermal glue adhesive formulations where COFEPRIS registry gaps force duplicate toxicity testing. Distribution runs through retail stationery chains during July-August academic calendar peaks, with São Paulo and Mexico City delivery networks enabling incremental direct-to-family e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital stylus and tablet substitution in upper-secondary private schools threatens traditional writing instrument demand, forcing incumbents to defend share through certification moats and hybrid product innovation.
For Market Incumbents: Secure INMETRO accreditation for São Paulo testing partnerships before federal procurement platform deadlines disqualify uncertified competitors. Consolidate pulp supply agreements with Southeast Brazilian mills to defend margin positions against fiber export competition. Thermal glue process adoption in premium notebooks represents the priority capacity investment lever. For New Entrants and Emerging Players: PROFECO fast-track certification for origin disclosure documentation unlocks Mexico City metropolitan corridor household purchasing concentrated in back-to-school windows. Target Colombian Ministry of National Education single-tender access created by procurement centralization absorbing fragmented departmental systems. Direct-to-family e-commerce bundling of grade-level academic kits offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors certification-compliant domestic manufacturers with accredited testing infrastructure over import-dependent brands facing extended ANVISA lead times. Long-term viability hinges on e-commerce logistics maturity enabling urban last-mile economics. Watch enrollment growth differentials between metropolitan corridors and regional averages as the inflection signal for channel investment priority.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Investment | Establishes qualification for Brazil federal procurement platforms excluding uncertified import competitors. |
| Thermal Glue Process Conversion | Reduces capital equipment requirements versus spiral binding while capturing premium notebook segment share. |
| E-commerce Logistics Buildout | Enables direct-to-family fulfillment in São Paulo and Mexico City metropolitan enrollment corridors. |
| Pulp Supply Integration | Secures captive fiber access defending margins against export market competition for eucalyptus supply. |
| Erasable Gel Ink Product Launch | Fragments traditional pen category by combining examination-grade permanence with primary-grade error correction. |
Research Approach
The analysis maps writing instruments, paper goods, and art materials segments, each validated through procurement officers at federal education ministries, category managers at retail stationery chains, plant directors at integrated pulp-to-binding facilities, and logistics heads at e-commerce platform operators. Primary interview insights triangulate against customs records for import certification timelines, ANVISA and COFEPRIS regulatory filings, academic enrollment databases, and retail audit data from Nielsen and Circana covering back-to-season purchasing patterns. Bottom-up product-type volume estimates reconcile with top-down national education expenditure frameworks.
Consistency checks validate volume and value outputs against external benchmarks including trade association production statistics and ministry procurement disclosure records across the analysis window. Segmentation dimensions model product type, end user archetype, distribution channel, and price tier dynamics throughout the forecast period. CAGRs derive from enrollment growth projections, regulatory implementation schedules, and channel migration velocity observed in urban logistics maturation. Forecast inputs incorporate eucalyptus pulp price index trajectories and digital substitution rates in private secondary institutions.
The analysis sits within stated boundaries; outcomes outside sustained federal procurement centralization in Colombia and Chile or accelerated ANVISA review timeline compression would require recalibration. Forecasts reflect assumptions regarding certification compliance cost absorption and metropolitan delivery density thresholds. Specific risks that could revise projections include COFEPRIS-Mexico health authority database harmonization delays, spiral binding equipment obsolescence acceleration, and tablet-stylus adoption inflection in upper-secondary segments. Recalibration cycles align with material shifts in regulatory enforcement intensity and enrollment corridor growth differentials.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Letter Opener Market
Office Supplies
Pencil Sharpeners Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Stamp Pad Market
Office Supplies
Business Card Holder Market
Office Supplies
School Stationery Supplies Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
Marker Pens Market
Office Supplies
Global Office Stationery Market
Office Supplies
Diaries & Planners Market
Office Supplies
Mechanical Pencil Leads Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Printer Ink Cartridge Market
Office Supplies
Office Supplies Market
Office Supplies
Cutter Staplers Market