
 United States School Stationery Supplies Market | 2026-2036
United States School Stationery Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
United States School Stationery Supplies Market Intelligence
The Consumer Product Safety Improvement Act is repositioning supplier compliance costs upward for makers of pencils, markers, and notebooks sold to minors. Crayola leverages its domestic manufacturing footprint to navigate testing mandates without cross-border delays. Pilot Corporation anchors its position through premium gel-ink formulations that command shelf space in specialty channels. ACCO Brands competes on institutional contract scale, sustaining volume relationships with multi-district purchasing cooperatives.
United States school stationery supplies encompass writing instruments, paper goods, and classroom consumables manufactured to ASTM D4236 toxicity standards and F963 physical safety benchmarks, serving the operational needs of K-12 and higher education environments. Notebooks and pencils retain the largest revenue share due to annual replenishment cycles, while markers are gaining share as visual learning methods expand across STEM curricula. Online Retail is the fastest-growing distribution channel, though Supermarkets still dominate back-to-season volume through promotional bundling with licensed character properties.
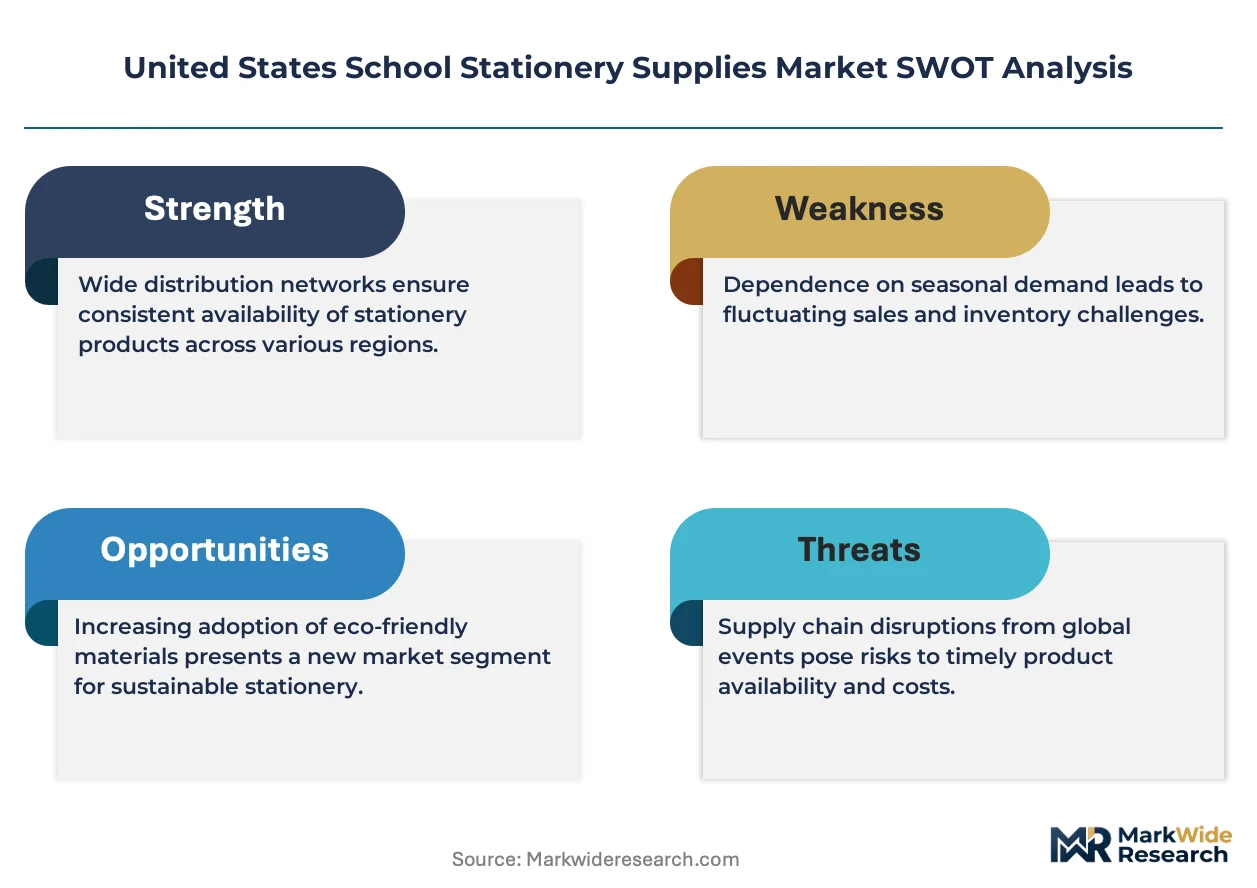
The Consumer Product Safety Commission enforces mandatory third-party testing for phthalates and heavy metals in children's products, while California's Proposition 65 adds labeling obligations that reshape packaging decisions for national suppliers. The EPA's Safer Choice program is steering institutional buyers toward certified low-toxicity formulations, filtering vendor eligibility for district-level contracts. Stakeholders must monitor how state-level curriculum shifts toward digital-hybrid classrooms will redistribute demand between disposable consumables and durable reusable tools.
Market Dynamics
The Consumer Product Safety Improvement Act is compressing supplier margins through mandatory third-party testing for phthalates and heavy metals, while K-12 district consolidation redirects procurement toward multi-year cooperative contracts that favor scale over brand loyalty.
Growth Catalysts
- Texas enrollment expansion:State education funding increases in Texas, California, and Florida are driving bulk purchasing volumes for classroom consumables.
- STEM curriculum mandates:Visual learning methods across science and mathematics programs are elevating marker demand for whiteboard and project-based instruction.
- ASTM D4236 compliance frameworks:Standardized toxicity testing protocols are creating entry barriers that protect incumbent suppliers with established laboratory relationships.
Market Restraints
- Petrochemical input volatility:Polymer feedstock price swings for plastic components in markers and mechanical pencils compress manufacturing margins unpredictably.
- Single-source testing concentration:CPSC-accredited laboratories cluster in coastal metropolitan areas, creating geographic bottlenecks for compliance documentation.
- Digital substitution pressure:Tablet and stylus adoption in upper-grade classrooms displaces traditional notebook and pen consumption in secondary education.
Strategic Opportunities
- Rural district cooperative formation:Smaller Midwestern and Mountain West districts are aggregating procurement through intermediate service agencies, opening vendor access.
- EPA Safer Choice certification:Institutional buyers are filtering vendor eligibility through low-toxicity formulation standards, creating differentiation for compliant suppliers.
- Hybrid classroom durable tools:Reusable whiteboard systems and refillable writing instruments are converging with sustainability procurement criteria in forward-leaning districts.
Industry Challenges
- Prop 65 labeling complexity:California's warning requirements force national packaging redesigns that fragment inventory management across state lines.
- Legacy procurement system integration:District-level ERP platforms lack API connectivity with vendor portals, delaying electronic purchase order processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States School Stationery Supplies Market |
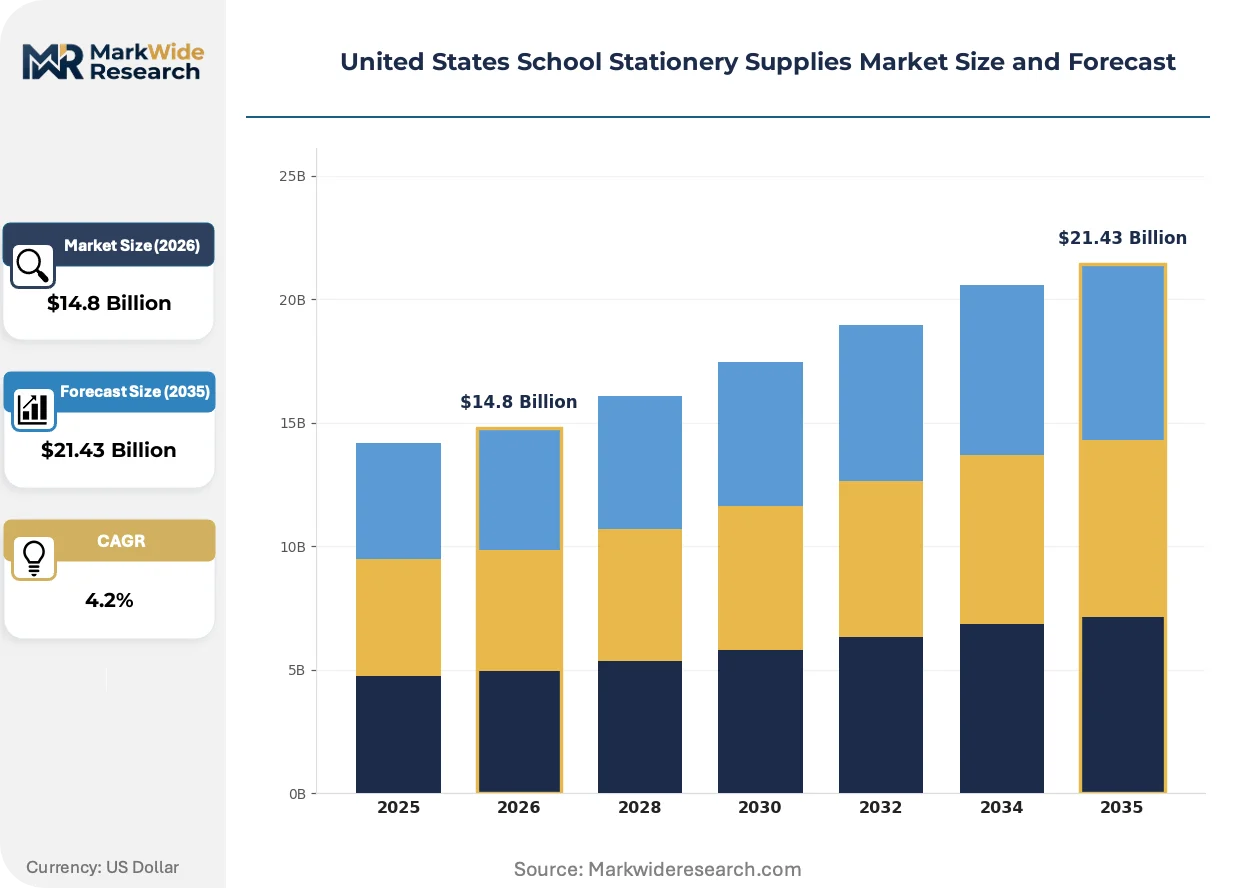
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pencils, Notebooks, Erasers, Markers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Students, Teachers, Educational Institutions, Parents Packaging Type: Bulk Packaging, Retail Packs, Eco-Friendly Packaging, Custom Packaging |
| Companies Covered | Faber-Castell, Staedtler, Pilot Corporation, Crayola, Kokuyo, Newell Brands, ACCO Brands, Staples, Societe BIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States School Stationery Supplies Market Strategic Shifts & Innovations
Stationery supply innovation is pivoting from commodity volume toward compliance-differentiated formulations and digital-hybrid classroom tools that bridge disposable and durable consumption models.
Plant-based polymer formulations are replacing petroleum-derived plastics in marker barrels and pen casings. K-12 procurement officers in coastal states are piloting these materials for sustainability reporting requirements. This bioplastic transition is converging with district carbon accounting mandates to reshape supplier R&D priorities.
The EPA's Safer Choice program is steering institutional purchasing toward certified low-toxicity ink and adhesive formulations. Manufacturers must reformulate solvent systems to meet volatile organic compound thresholds. Private-label distributors serving multi-district cooperatives are most exposed to compliance timeline pressures.
Bulk replenishment subscriptions through district-approved e-procurement portals are displacing seasonal retail stock-ups. Procurement coordinators in large urban districts are consolidating vendor lists to simplify invoice reconciliation. This channel consolidation is most advanced in Texas and Florida where state purchasing cooperatives have digitized their bid platforms.
United States School Stationery Supplies Market Segmentation
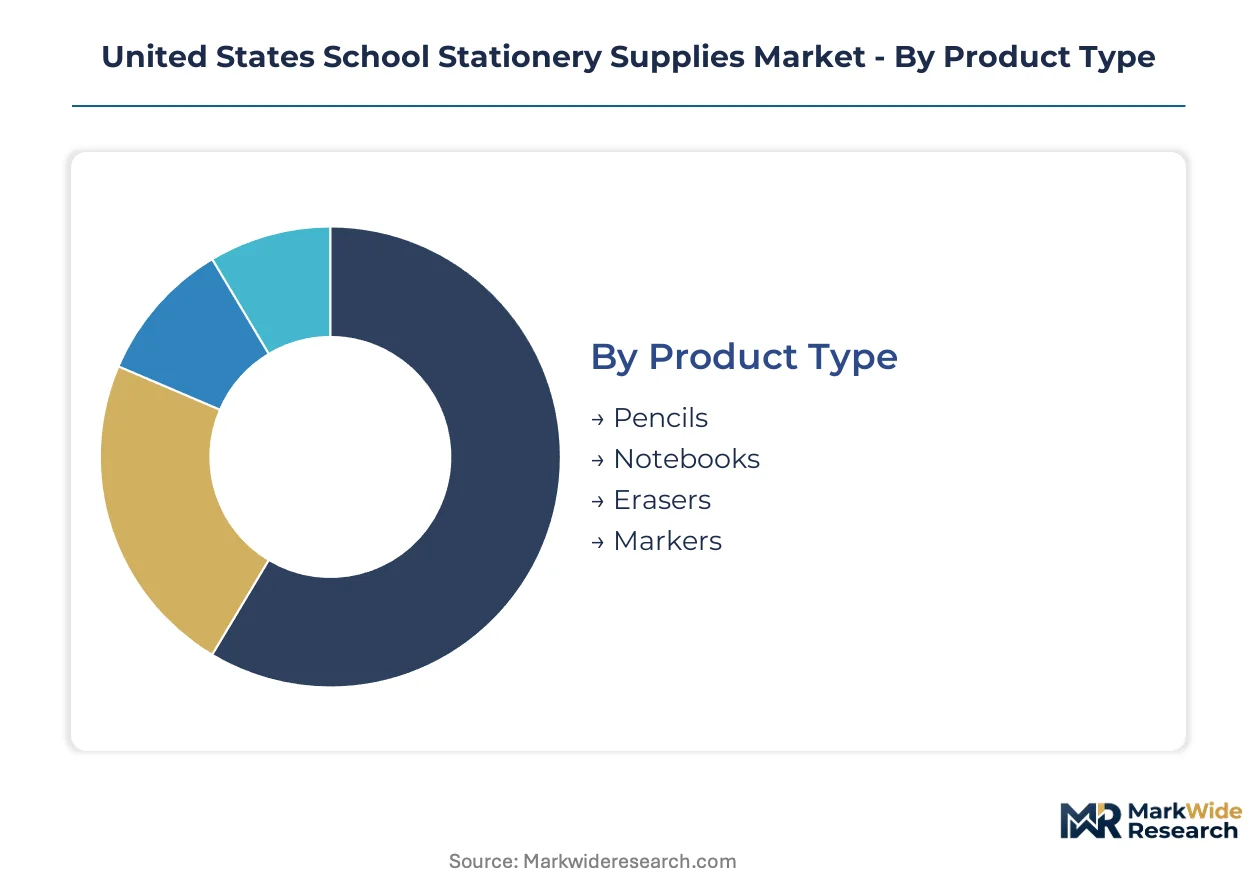
Segmentation reveals how compliance costs and procurement scale reshape competitive position across product categories. District purchasing patterns diverge sharply between high-volume consumables and premium durable tools.
Product Type:
Volume concentration dominates commodity segments while premium formulations capture margin in specialized applications.
- Notebooks:Spiral-bound and composition formats with FSC-certified paper content anchor annual replenishment cycles in K-12 districts. Texas and California districts drive bulk purchasing through state-funded procurement cooperatives, though digital tablet substitution compresses upper-grade demand.
- Pencils:Graphite and colored varieties manufactured to ASTM D4236 toxicity standards serve foundational writing instruction. Enrollment expansion in Florida and Texas sustains volume relationships with multi-district purchasing agreements despite polymer feedstock volatility.
- Markers:Whiteboard and permanent formulations gain share through STEM curriculum visual learning requirements. EPA Safer Choice certification filters vendor eligibility for institutional contracts.
- Erasers:Vinyl and natural rubber compounds complete classroom consumable sets with lower compliance burden than ink-based products.
Mature deployment sits with Notebooks. Newer deployment is concentrated in Markers.
Distribution Channel:
Channel selection reflects procurement system maturity and district scale rather than consumer preference alone.
- Supermarkets:Back-to-season promotional bundling with licensed character properties captures parent-driven replenishment in suburban markets. Seasonal volume spikes concentrate in July through September.
- Online Retail:District-approved e-procurement portals enable bulk replenishment subscriptions that displace traditional stock-ups. Texas and Florida purchasing cooperatives digitized bid platforms fastest, accelerating this channel's expansion trajectory.
- Wholesale:Intermediate service agencies aggregate rural Midwestern and Mountain West district demand, opening vendor access beyond major metropolitan corridors.
- Specialty Stores:Premium gel-ink and artist-grade formulations command shelf space through curated assortments serving independent schools and parent gift segments.
Established procurement sits with Supermarkets. Fastest digitization is occurring in Online Retail.
End User:
User type determines compliance stringency and purchasing authority concentration.
- Educational Institutions:K-12 districts and higher education procurement offices wield multi-year cooperative contracts that favor scale over brand loyalty. CPSC third-party testing mandates and Prop 65 labeling obligations reshape vendor qualification.
- Students:Individual replenishment demand concentrates in lower grades where consumable loss rates sustain replacement cycles. Parent purchasing decisions respond to retail promotional calendars.
- Teachers:Classroom supply budgets drive discretionary purchases of visual learning tools and durable whiteboard systems. Sustainability reporting requirements in coastal states steer selections toward plant-based polymer formulations.
- Parents:Back-to-school list compliance generates seasonal demand spikes with high price sensitivity outside bundled offerings.
Centralized purchasing authority sits with Educational Institutions. Fragmented decision-making persists with Parents.
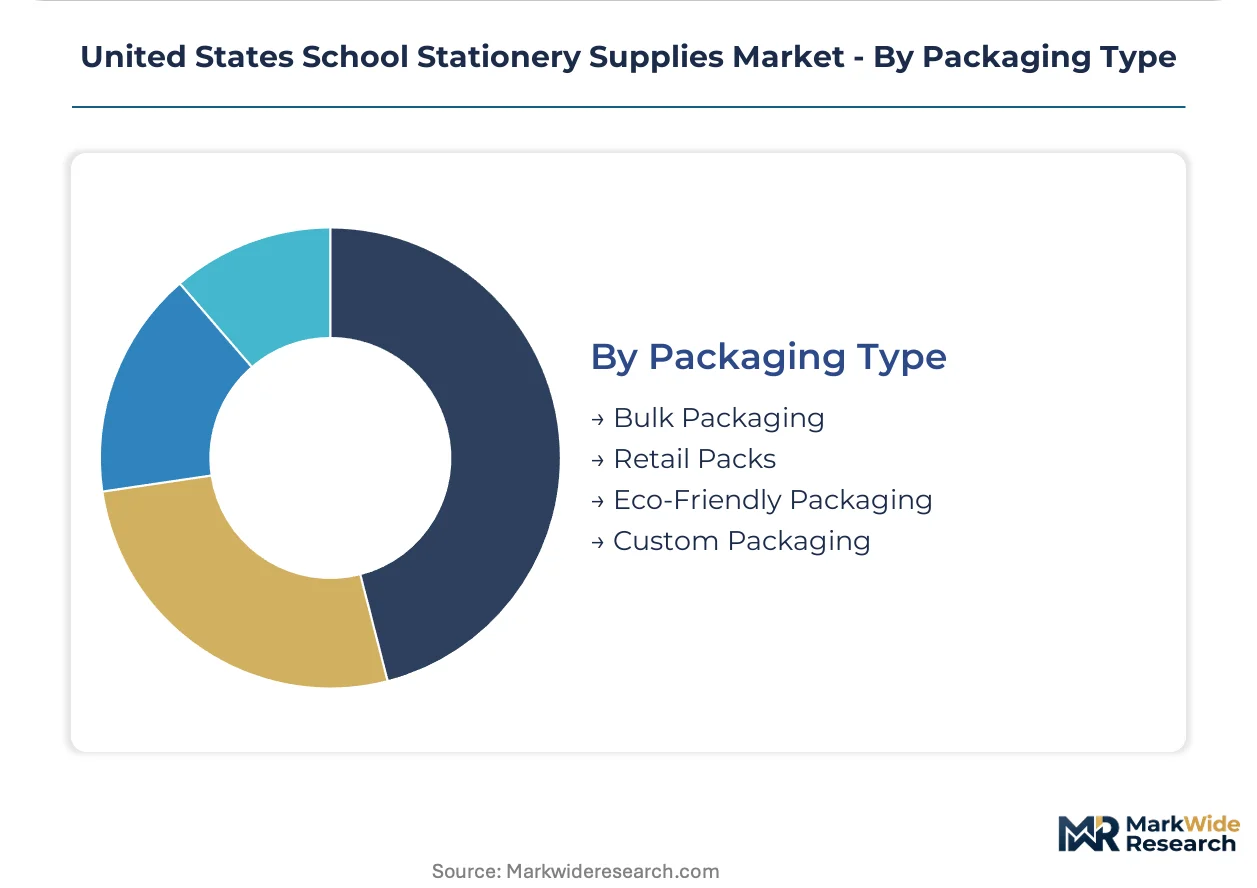
Packaging Type:
Packaging configuration aligns with procurement scale and state-level environmental mandates.
- Bulk Packaging:Case quantities and pallet configurations serve district-level ERP platforms with simplified invoice reconciliation. State education funding increases in target geographies expand contract scale.
- Eco-Friendly Packaging:Recycled content and biodegradable materials respond to district carbon accounting mandates and EPA Safer Choice program alignment. California Prop 65 labeling complexity fragments inventory management.
- Retail Packs:Blister cards and hanging displays address parent and teacher discretionary purchasing through mass merchant and specialty channels.
- Custom Packaging:District-branded or curriculum-aligned configurations serve charter school networks and private institutional segments with differentiated procurement requirements.
Standardized procurement sits with Bulk Packaging. Emerging specification growth is concentrated in Eco-Friendly Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and California drive procurement concentration through state-funded purchasing cooperatives that aggregate K-12 district demand. Federal education stimulus flows through these designated zones, compressing vendor qualification timelines for institutional contracts.
Texas
Enrollment expansion in Dallas-Fort Worth and Houston metro areas sustains bulk purchasing volumes for classroom consumables. State education funding increases channel through the Texas Education Agency's cooperative procurement system. Austin anchors vendor relationship management for multi-district contracts serving rural and urban districts alike.
California
Proposition 65 labeling mandates reshape packaging decisions for suppliers serving Los Angeles and San Francisco Bay Area school systems. The California Department of Education's sustainability procurement criteria filter vendor eligibility through carbon accounting requirements. San Diego County districts pilot plant-based polymer formulations for compliance reporting.
Florida
Miami-Dade and Broward County enrollment growth drives seasonal replenishment cycles for traditional consumables. State procurement regulations administered by the Florida Department of Education standardize bid specifications across district lines. Orlando-area intermediate service agencies aggregate demand from smaller Gulf Coast districts.
New York
Upstate rural districts leverage BOCES cooperative purchasing to match urban procurement scale. New York State Education Department mandates align with federal CPSIA testing requirements for student-facing products. Rochester and Buffalo anchor distribution networks serving Appalachian district clusters.
Illinois
Chicago Public Schools' centralized procurement office wields multi-year contracts that favor suppliers with established laboratory testing relationships. Illinois State Board of Education guidelines incorporate ASTM D4236 compliance into vendor pre-qualification. Peoria and Springfield host intermediate agencies aggregating downstate district demand.
United States School Stationery Supplies Market Key Industry Players
Domestic producers anchor the institutional contract tier; Japanese and German specialists hold premium positioning in specialty channels. Market structure concentrates around three strategic archetypes: scale-driven cooperative contract holders, compliance-differentiated domestic manufacturers, and premium formulation specialists. Consolidation pressures intensify as district procurement digitization favors vendors with integrated ERP connectivity. Capacity expansion and portfolio diversification represent the dominant competitive moves as suppliers bridge disposable and durable consumption models.
Among Japanese manufacturers, Pilot Corporation exemplifies the premium gel-ink specialist archetype through formulations commanding shelf space in specialty retail. Crayola represents the domestic compliance-advantaged fabricator leveraging manufacturing proximity to navigate CPSC testing mandates without cross-border documentation delays. ACCO Brands occupies a position within the institutional scale tier, sustaining volume relationships with multi-district purchasing cooperatives across high-enrollment states.
| Leading Market Players |
|---|
| Faber-Castell |
| Staedtler |
| Pilot Corporation |
| Crayola |
| Kokuyo |
| Newell Brands |
| ACCO Brands |
| Staples |
| Societe BIC |
| Others |
Cost & Logistics Intelligence
Compliance-certification tiering between CPSC-accredited domestic manufacturers and import-dependent suppliers manifests in both pricing premiums and distribution network configurations. District procurement officers pay lead-time premiums for verified ASTM D4236 documentation while spot-market imports compete on unit cost through fragmented wholesale channels.
Pricing Analysis
Short lead-time premiums dominate institutional contract pricing, with CPSC-compliant domestic stock commanding 15-20% spreads over spot-import alternatives. Price differentiation rests on certification tier and cooperative contract scale, with multi-district agreements securing volume discounts unavailable to single-district buyers. Cost compression in polymer-dependent categories intensifies as petrochemical feedstock volatility feeds through barrel and casing costs. Parent-driven retail replenishment shows highest price sensitivity, while district procurement offices prioritize compliance documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Chicago anchor hub-and-spoke patterns serving consolidated K-12 cooperatives. Manufacturing concentrates in the United States, Mexico, and China, with domestic fabricators controlling institutional-tier supply and Asian producers feeding retail replenishment cycles. Raw material dependencies span petroleum-derived polymers for marker barrels, graphite for pencil cores, and pulp for notebook paper. Single-source testing concentration at CPSC-accredited coastal laboratories creates geographic chokepoints for compliance documentation. Distribution runs through state purchasing cooperative portals digitized in Texas and Florida, displacing traditional wholesale stock-up patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
District procurement digitization and compliance cost escalation position this market for supplier consolidation, with CPSC testing mandates and cooperative contract scale forcing sub-scale competitors toward exit.
For Market Incumbents: Hedge margin exposure by securing captive polymer supply through backward integration into resin compounding or long-term offtake agreements with Gulf Coast petrochemical producers. Invest in ERP-integrated e-procurement portals to match Texas Education Agency platform specifications and defend position against digital-native entrants targeting cooperative contract tiers. For New Entrants and Emerging Players: EPA Safer Choice certification in the United States opens a window for differentiated positioning in coastal state districts with sustainability procurement mandates. Target rural Midwestern intermediate service agencies with plant-based polymer formulations that satisfy carbon accounting requirements without competing head-to-head with incumbent scale in Texas and Florida cooperative systems. Lead with refillable whiteboard marker systems that convert disposable marker demand to recurring ink cartridge revenue. For Investors and Strategic Acquirers: Re-rating potential sits with compliance-differentiated domestic manufacturers given CPSC enforcement intensification and cross-border documentation friction. Long-term viability favors suppliers with established laboratory relationships and multi-year cooperative contract backlogs. Monitor state education funding appropriation cycles as the signal to watch for inflection in district replenishment volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply insulates margin from petrochemical volatility and secures formulation control for bioplastic transitions. |
| ERP-Integrated E-Procurement Portal Development | API connectivity with Texas Education Agency and Florida Department of Education platforms defends incumbent cooperative contract position. |
| EPA Safer Choice Certification Investment | Low-toxicity formulation credential filters vendor eligibility in California and New York sustainability procurement frameworks. |
| Refillable System Product Line Launch | Reusable whiteboard and writing instrument platforms convert disposable consumable demand to recurring cartridge revenue streams. |
| Rural District Cooperative Penetration | Intermediate service agency relationships in Midwestern and Mountain West states open volume access beyond coastal metropolitan corridors. |
Research Approach
Document review covered SEC 10-K filings, CPSC enforcement action records, and state education agency procurement databases, complemented by interviews with K-12 district procurement coordinators, cooperative purchasing directors, stationery supply category managers, and CPSC-accredited laboratory testing directors. Secondary validation drew from U.S. Census Bureau school district finance data, National Center for Education Statistics enrollment projections, and American Forest and Paper Association pulp market reports. Bottom-up district-level demand modeling triangulated against top-down manufacturer shipment data.
Historical spending patterns from district financial disclosures were cross-referenced against panel input from procurement officers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, distribution channel maturity, end-user purchasing authority concentration, and packaging configuration aligned with state environmental mandates. CAGRs were derived from enrollment-driven replenishment cycles, curriculum shift impacts on consumable mix, and channel migration from seasonal retail to subscription-based e-procurement. Forecast inputs incorporated petrochemical price indices, state education funding appropriation trajectories, and digital substitution rates in upper-grade classrooms.
The model assumes a particular technology adoption path for digital-hybrid classroom tools; alternative pathways for tablet and stylus penetration would alter the outlook for traditional notebook and pencil demand. Forecasts reflect documented assumptions regarding state funding continuity, regulatory enforcement intensity, and cooperative procurement consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Office Supplies Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Perforated File Market
Office Supplies
Erasable Ink Pen Market
Office Supplies
Stationery Products Market
Office Supplies
Diaries & Planners Market
Office Supplies
Stationery Market
Office Supplies
Greetings Cards Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Business Card Holder Market
Office Supplies
Copiers Market
Office Supplies
Marker Pens Market
Office Supplies
Letter Opener Market
Office Supplies
Pencil Sharpeners Market