
 Office Supplies Market | 2026-2036
Office Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Office Supplies Market Intelligence
The expansion of e-commerce platforms is reconfiguring traditional distribution models for office supplies. This shift challenges legacy retailers like Staples Inc. to integrate online and offline sales capabilities. In contrast, diversified manufacturers such as 3M Company leverage brand recognition to secure placement across both digital marketplaces and established wholesale networks. The ODP Corporation also navigates this transition by focusing on business-to-business services alongside its retail presence.
Office supplies encompass a broad category of consumable and durable goods supporting administrative and communication tasks. These products range from paper goods with specific basis weights and brightness levels to writing instruments engineered for ergonomic comfort. Paper products remain a foundational, high-volume segment, while writing instruments exhibit significant price differentiation based on brand and functionality. Corporate offices and educational institutions represent the largest application segments, driving bulk procurement through specialized distributors.
Product composition and marketing claims are governed by multiple regulatory frameworks. The U.S. EPA sets guidelines for recycled content, while the EU's REACH regulation restricts chemicals in items like adhesives, and Japan's Eco Mark program certifies environmentally friendly products. Vendor success depends on navigating these diverse environmental standards while adapting supply chains to serve a more fragmented base of corporate and home office customers.
Market Dynamics
The office supplies market is being fundamentally reshaped by global sustainability mandates. These regulations, particularly circular economy principles, are forcing a systemic re-evaluation of product lifecycles, from raw material sourcing and manufacturing processes to end-of-life disposal and recycling.
Growth Catalysts
- Sustainability Mandates:The EU Green Deal and its circular economy goals stimulate demand for office products made from recycled, recyclable, or compostable materials, creating a preference for certified goods.
- Hybrid Work Models:The expansion of home and flexible office setups, especially in urban centers like New York and Tokyo, drives individual purchases of ergonomic and premium-quality supplies.
- Material Innovation:Advances in developing high-performance recycled paper that matches the brightness of virgin stock and the creation of durable plant-based bioplastics expand the viability of eco-friendly product lines.
Market Restraints
- Digital Substitution:The proliferation of cloud storage, project management software, and digital communication platforms steadily erodes the foundational demand for paper, physical filing systems, and certain types of writing instruments.
- Input Cost Volatility:Fluctuations in the global prices of wood pulp and petroleum-derived polymers directly impact the manufacturing costs of paper goods and plastic-based supplies, creating margin instability.
- Regulatory Divergence:Conflicting environmental regulations, such as the chemical restrictions under the EU's REACH and the U.S. EPA's recycled content guidelines, create compliance burdens for global manufacturers.
Strategic Opportunities
- Subscription-Based Models:Direct-to-consumer (DTC) subscription services for home office consumables provide a new channel to serve a fragmented customer base, bypassing traditional bulk distributors.
- Wellness-Centric Products:There is a growing niche for supplies that support employee well-being, including ergonomically certified writing tools, non-toxic adhesives, and air-purifying desk plants.
- Green Public Procurement:Government purchasing programs, such as those in Japan that mandate a preference for Eco Mark certified products, offer a stable, high-volume sales channel for compliant suppliers.
Industry Challenges
- Logistical Reconfiguration:Shifting distribution networks from a model based on large, centralized corporate deliveries to one that serves thousands of individual home addresses introduces significant logistical complexity and cost.
- Certification Barriers:The expense and time required to obtain and maintain multiple environmental certifications across different jurisdictions, such as EU Ecolabel and Japan's Eco Mark, can be prohibitive for smaller market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Supplies Market |
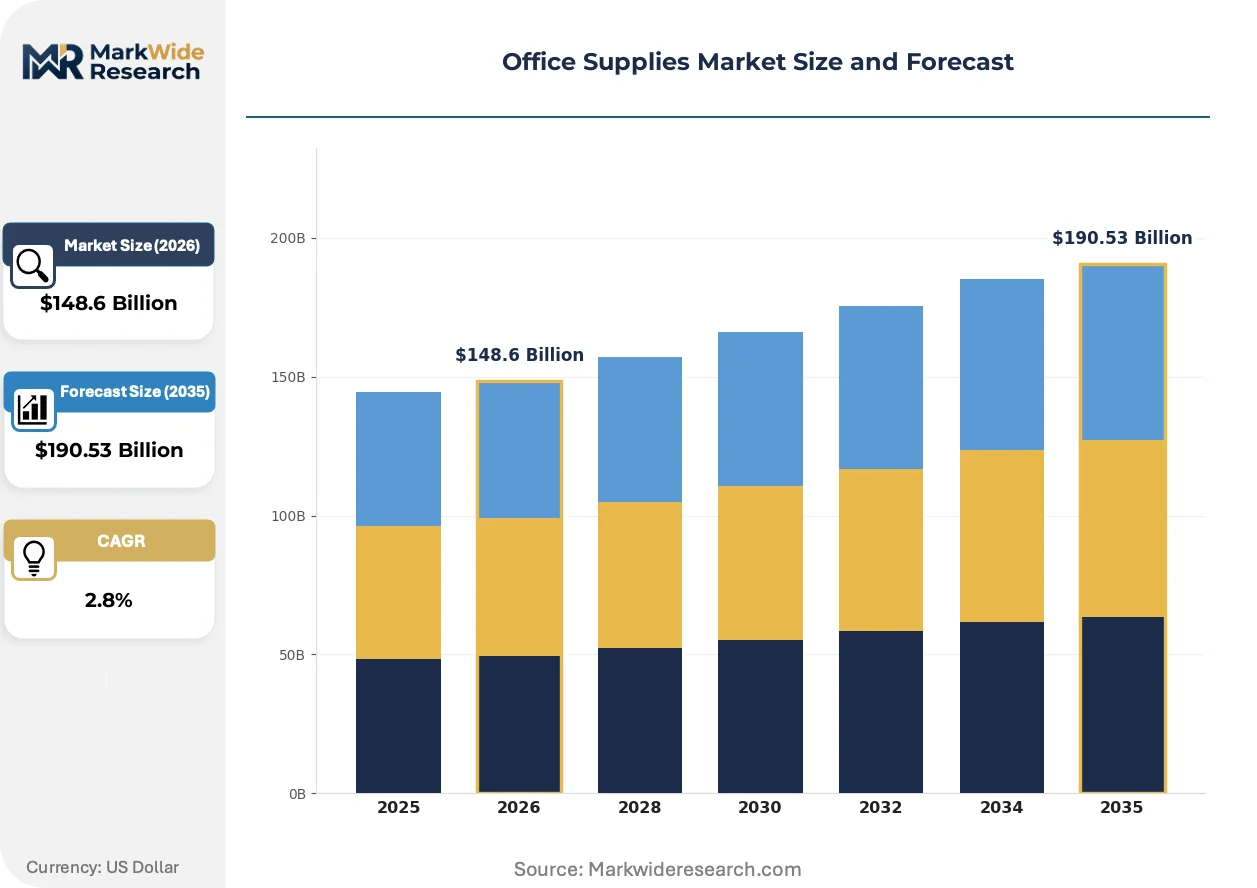
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $190.53 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Writing Instruments, Paper Products, Desk Accessories, Filing & Organization, Adhesives & Tapes, Presentation Supplies Application: Educational Institutions, Corporate Offices, Government Agencies, Nonprofit Organizations, Small Businesses, Home Offices Distribution Channel: Office Supply Stores, E-commerce Platforms, Wholesale Distributors, Supermarkets & Hypermarkets, Direct Sales, Specialty Retailers Customer Type: Administrators, Procurement Professionals, Facility Managers, Individual Consumers, Startups, Educational Administrators |
| Companies Covered | The ODP Corporation, Staples Inc., ACCO Brands Corporation, 3M Company, Office Depot, Lyreco, Newell Brands Inc, Kokuyo Co Ltd, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Supplies Market Strategic Shifts & Innovations
Product design and material science are at a critical intersection, driven by the dual pressures of environmental accountability and the integration of digital workflows. This dynamic is altering the functional purpose and material composition of core office products.
Smart paper and reusable digital notebooks integrate traditional handwriting with cloud-based digital services. These products use specialized microdot patterns on the paper and compact cameras in the pen to capture and digitize strokes in real time. Creative professionals, students, and corporate users are adopting these hybrid tools to bridge their analog and digital workflows, and this technology is collapsing the boundary between physical and digital note-taking.
The European Union's Green Deal framework, through its Circular Economy Action Plan, is setting new standards for product design. It compels manufacturers to prioritize the use of recycled content and engineer products like binders, folders, and pens for easy disassembly and material recovery. The paper products segment faces the most direct impact, with suppliers increasingly needing to provide clear verification for recycled content and sustainable forestry sources to access the EU market.
A notable behavioral shift is the decentralization of purchasing authority from central procurement departments to individual employees and team leaders. This trend favors the use of online marketplaces and direct-to-consumer e-commerce sites over traditional large-volume B2B distributors, as buyers prioritize speed and product choice. This fragmented, on-demand purchasing pattern is most pronounced within the technology and creative services industries, where remote and hybrid work models are prevalent.
Office Supplies Market Segmentation
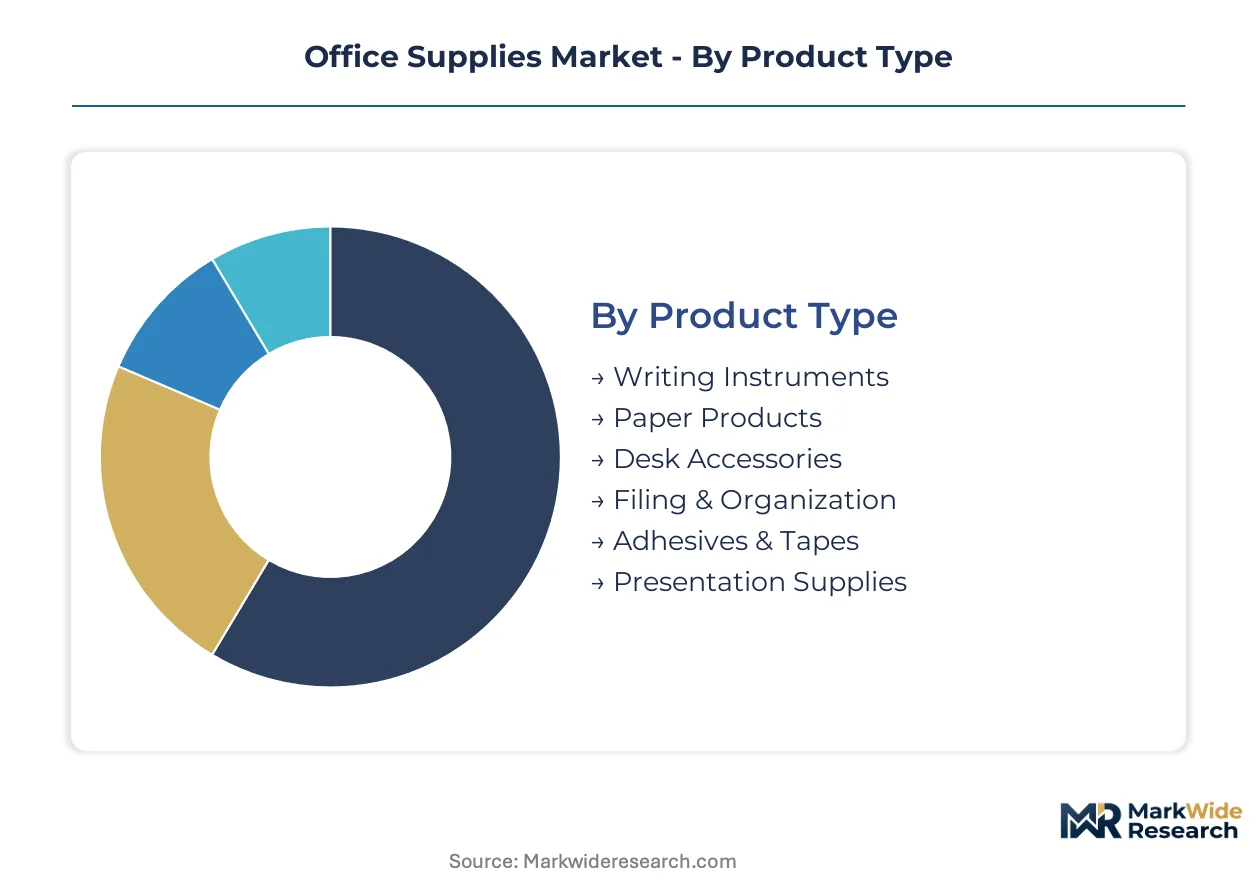
Market segmentation for office supplies provides a granular view of product utility, end-user demand, and distribution complexities. Understanding these distinct segments allows suppliers to tailor product development and marketing strategies effectively. This differentiated approach addresses the varied requirements of both corporate and individual consumers.
Product Type:
Product type delineates the core components of the office supplies market, reflecting functional utility and material composition across diverse categories.
- Paper Products:This segment includes items like printer paper, notebooks, and notepads, characterized by specific basis weights and brightness levels. Demand concentrates in corporate offices and educational institutions, driven by bulk procurement for daily administrative and learning tasks.
- Writing Instruments:Encompassing pens, pencils, and markers, these products are engineered for ergonomic comfort and various ink types. Demand concentrates in home offices and creative professionals, reflecting individual preference for functionality and brand.
- Desk Accessories:This includes organizational tools such as pen holders, staplers, and desk organizers, supporting efficient workspace management.
- Filing & Organization:Products like folders, binders, and filing cabinets facilitate systematic document storage and retrieval for businesses.
- Adhesives & Tapes:This segment covers glues, sticky notes, and various tapes, essential for assembly, repair, and temporary attachment needs.
- Presentation Supplies:Items such as whiteboards, projectors, and flip charts aid in visual communication and collaborative meetings.
Paper Products hold significant installed capacity. Writing Instruments are rotating up the share rankings.
Application:
Demand for office supplies is shaped by the specific operational needs of various end-user applications, from large institutions to individual setups.
- Corporate Offices:This segment involves bulk procurement of a wide range of supplies for administrative, operational, and communication tasks. Demand concentrates in major business hubs like New York and Tokyo, driven by large-scale administrative requirements.
- Home Offices:Catering to individual purchases, this segment focuses on ergonomic and premium-quality supplies for flexible and remote work environments. Demand concentrates in urban centers with high adoption of hybrid work models.
- Educational Institutions:This application includes schools, colleges, and universities requiring supplies for classrooms, administration, and student use.
- Government Agencies:Public sector entities procure standard and specialized office supplies through regulated purchasing programs.
- Nonprofit Organizations:These organizations typically seek cost-effective and essential supplies to support their administrative and outreach efforts.
- Small Businesses:Characterized by flexible ordering patterns, this segment requires a broad array of essential consumables for daily operations.
Corporate Offices represent the largest volume segment. Home Offices are expanding most quickly.
Distribution Channel:
The pathways through which office supplies reach end-users have diversified, reflecting evolving purchasing behaviors and logistical capabilities.
- E-commerce Platforms:Online marketplaces and direct-to-consumer websites offer convenience and extensive product choice for individual and small business buyers. Demand concentrates among individual consumers and startups, driven by speed and product variety.
- Wholesale Distributors:These channels manage large-volume procurement and logistical networks, serving corporate offices and educational institutions. Demand concentrates in large organizations seeking efficient bulk purchasing and supply chain management.
- Office Supply Stores:Physical retail outlets provide immediate access to products and in-person customer service for various buyers.
- Supermarkets & Hypermarkets:These large retail formats offer basic office supplies as part of a broader consumer goods offering.
- Direct Sales:Manufacturers or specialized vendors sell directly to businesses, often for customized orders or specialized products.
- Specialty Retailers:Niche stores focus on specific types of office supplies, such as art supplies or high-end writing instruments.
E-commerce Platforms are gaining share fastest. Traditional Office Supply Stores maintain a foundational presence.
Customer Type:
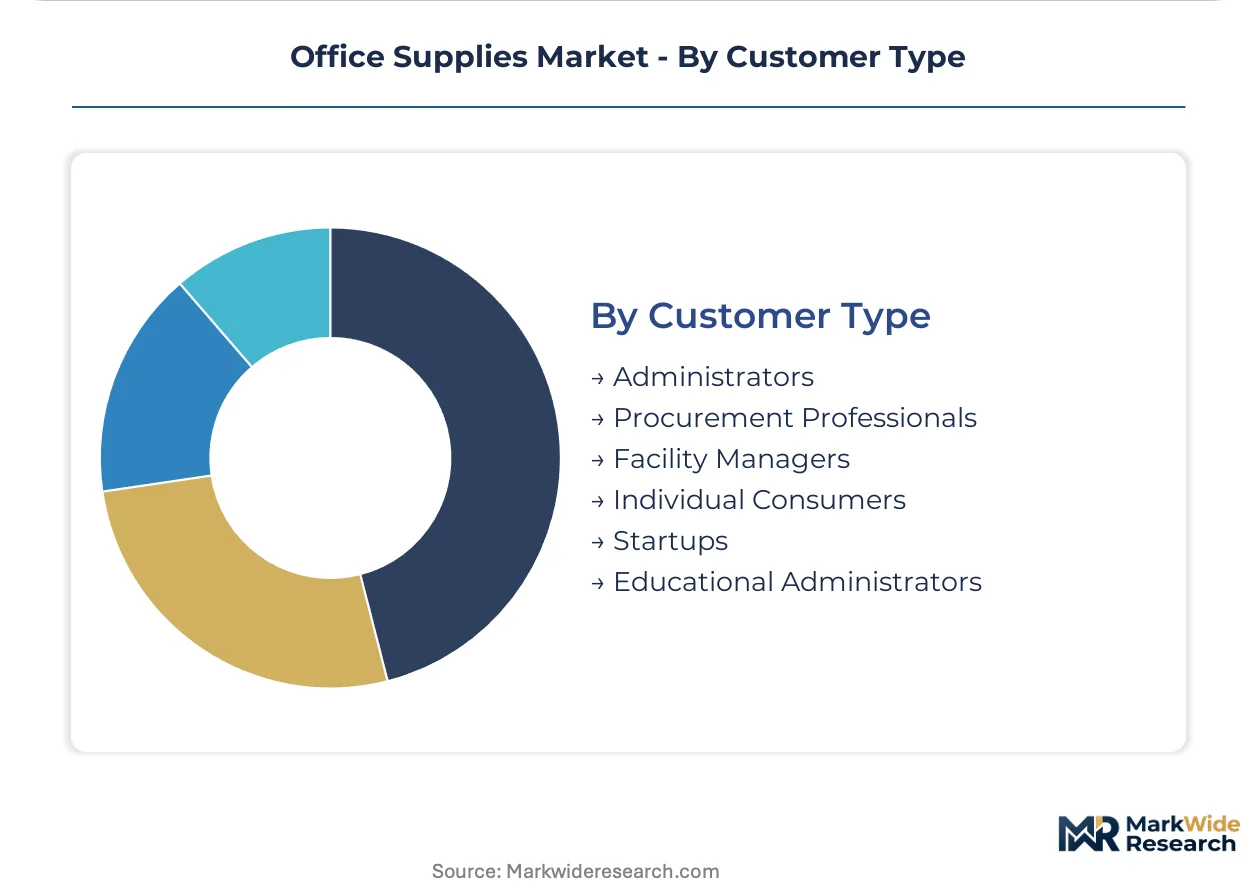
Purchasing decisions for office supplies are influenced by the roles and procurement authority of various customer types within organizations or as individual buyers.
- Procurement Professionals:These individuals manage strategic sourcing, vendor relationships, and contract negotiations for large organizations. Demand concentrates in corporate offices and government agencies, driven by cost efficiency and compliance requirements.
- Individual Consumers:Personal buyers make decisions based on specific needs, brand preference, and ergonomic considerations for home or personal use. Demand concentrates in home offices and creative professionals, reflecting personalized needs and flexible work models.
- Administrators:Office administrators manage departmental budgets and procure supplies for daily operational support and team needs.
- Facility Managers:Responsible for overall building operations, these professionals acquire general office supplies and maintenance-related items.
- Startups:New businesses often prioritize agile procurement of essential supplies to establish initial operations.
- Educational Administrators:These professionals oversee budgets and purchasing for classroom materials and institutional requirements within schools or universities.
Individual Consumers exhibit the steepest expansion trajectory. Procurement Professionals continue to drive large-scale volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for office supplies exhibits regional asymmetries, with demand in Europe and Japan favoring premium, sustainably certified products. In contrast, markets like the United States and China often balance sustainability with volume-driven procurement. This dynamic influences product development and distribution strategies across continents.
United States
Demand for office supplies in the United States concentrates in home offices and corporate procurement, driven by flexible work models. The U.S. EPA sets guidelines for recycled content, influencing product specifications. New York business hubs foster demand for specialized, ergonomic, and premium-quality supplies.
Germany
German corporate offices and educational institutions drive demand for sustainably produced office supplies. The EU Green Deal and REACH regulation restrict chemicals, mandating eco-friendly materials. Berlin's growing tech sector particularly adopts certified, high-performance recycled paper.
Japan
Japanese consumers and businesses exhibit a strong preference for premium and environmentally certified office products. Japan's Eco Mark program certifies environmentally friendly goods, guiding public procurement. Tokyo's dense business districts and expanding home office segment demand specialized, high-quality writing instruments.
China
China's vast corporate offices and educational institutions necessitate bulk procurement of a broad range of office supplies. Environmental protection regulations increasingly influence manufacturers' material choices for paper and plastic goods. Shanghai's commercial centers drive significant volume, with a growing emphasis on e-commerce distribution.
France
French public procurement programs and corporate sustainability initiatives stimulate demand for certified and circular economy-compliant office products. The EU's Circular Economy Action Plan compels manufacturers to design products for easy disassembly and material recovery. Paris business districts show a rising preference for non-toxic adhesives and ergonomically designed desk accessories.
Office Supplies Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the office supplies market. The industry exhibits a tiered structure, with diversified manufacturers competing alongside specialized product developers. Strategic archetypes include large-scale distributors, niche e-commerce providers, and material innovation companies. Dominant competitive moves involve supply chain adaptation to fragmented demand and strategic partnerships for sustainable product development.
Scale-driven players like The ODP Corporation, an American entity, exemplify the shift towards integrated business-to-business services alongside a foundational retail presence. Staples Inc., another North American player, represents the traditional office supply store model adapting its operations for comprehensive online and offline sales capabilities. Diversified manufacturers such as 3M Company, a global multinational, anchor the upstream segment with established brand recognition and material science expertise. These entities collectively illustrate the market's response to evolving distribution channels and product demands, navigating fragmented customer bases and sustainability pressures.
| Leading Market Players |
|---|
| The ODP Corporation |
| Staples Inc. |
| ACCO Brands Corporation |
| 3M Company |
| Office Depot |
| Lyreco |
| Newell Brands Inc |
| Kokuyo Co Ltd |
| Canon Inc. |
| Others |
Cost & Logistics Intelligence
Input cost volatility for wood pulp and petroleum-derived polymers determines both pricing tier spreads and the overall supply chain shape for office supplies. These raw material fluctuations directly influence manufacturing expenses and subsequent retail price points across different product categories.
Pricing Analysis
The customization-premium spread influences pricing dynamics, with specialized ergonomic writing instruments commanding higher prices than bulk printer paper. The dominant pricing structure blends per-unit transactional sales for high-volume consumables with subscription-based models for recurring home office supplies. Price differentiation stems from eco-certification levels, such as Japan's Eco Mark, and ergonomic design. Pricing softness emerges in commoditized paper products due to digital substitution, while premium segments maintain stability. Corporate offices exhibit high price sensitivity for bulk purchases, contrasting with individual consumers who prioritize specific features and brand for home office setups.
Supply Chain Analysis
Upstream feedstock sourcing for office supplies relies heavily on wood pulp from Nordic regions and petroleum-derived polymers from global producers. Geographic supply concentration includes manufacturing hubs in China for various finished goods and specialized paper mills across Europe. Raw material dependencies involve virgin wood pulp, recycled paper content, and plant-based bioplastics. Logistical reconfiguration represents a structural risk, as distribution shifts from centralized corporate deliveries to fragmented individual home addresses. The dominant downstream structure involves e-commerce platforms gaining share, alongside established wholesale distributors for large institutional clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The office supplies market sits at an early-cycle expansion story, primarily driven by the sustained tailwind of hybrid work models. This fundamental shift redefines product demand and distribution pathways.
For Market Incumbents:
Entrench existing business-to-business relationships by integrating comprehensive online ordering with efficient bulk delivery services. This strategy counters the threat of digital substitution eroding core paper product demand. Invest in environmental certifications for all product lines to meet evolving regulatory standards like the EU Green Deal. Optimize logistics networks to manage both large corporate orders and fragmented direct-to-home deliveries, leveraging technology for route optimization.
For New Entrants and Emerging Players:
Establish a beachhead in the home office segment through specialized product lines that cater to individual preferences. The most penetrable segment remains individual consumers and creative professionals seeking ergonomic and eco-friendly solutions. Leverage subscription-based models for recurring consumables, providing convenience and predictable revenue streams. Target wellness-centric products, such as non-toxic adhesives and advanced bioplastic desk accessories, to differentiate from traditional offerings.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors agile, sustainability-focused technology providers. Long-term viability is strong for companies innovating in material science and digital integration, aligning with circular economy principles. Target acquisition archetypes include niche innovators in smart paper or plant-based materials. The signal to watch is regulatory tightening around single-use plastics in office environments, indicating future market shifts and investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Introduces smart paper and bioplastic alternatives to capture hybrid work and sustainability demand. |
| E-commerce Platform Enhancement | Integrates advanced B2B and direct-to-consumer functionalities, serving fragmented customer bases efficiently. |
| Sustainability Certification Investment | Secures Eco Mark and EU Ecolabel for core products, accessing green public procurement and premium segments. |
| Logistics Network Optimization | Reconfigures supply chains for direct-to-home deliveries, addressing shifts from centralized corporate orders. |
| Strategic Technology Partnerships | Collaborates with software firms for digital integration, bridging analog and digital workflows. |
Research Approach
Findings reconcile primary fieldwork against secondary review of government environmental reports, corporate financial filings, and industry association data. Primary interviews included procurement professionals, home office users, e-commerce platform managers, and material science experts. Secondary sources encompassed U.S. EPA guidelines, EU REACH regulations, Japan Eco Mark program specifications, and annual reports from major market players. This analysis employed both bottom-up market sizing and top-down validation to ensure data integrity.
Forecast inputs being considered include historical market performance and projected shifts in end-user behavior across the analysis window. The analytical framework modeled segmentation dimensions such as product type, application, distribution channel, customer type, and material innovation adoption. Compound annual growth rates were derived from a blend of historical growth trends and anticipated impacts of sustainability mandates. Key industry-specific forecast inputs included global hybrid work model penetration rates and bioplastic material cost trends over the projection horizon.
Sensitivities concentrate around shifts in global economic stability and the pace of digital substitution for physical products. Forecasts reflect assumptions regarding regulatory evolution and consumer preference for eco-friendly goods. Cross-checking against industry trade reports and macroeconomic indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
Letter Opener Market
Office Supplies
Stamp Pad Market
Office Supplies
Stationery Products Market
Office Supplies
Global Office Stationery Market
Office Supplies
Cutter Staplers Market
Office Supplies
Business Card Holder Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Copiers Market
Office Supplies
Custom Binders Market
Office Supplies
Writing Instruments Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Writing and Marking Instruments Market
Office Supplies
Greetings Cards Market
Office Supplies
Europe School Stationery Supplies Market