
 School Stationery Supplies Market | 2026-2036
School Stationery Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
School Stationery Supplies Market Intelligence
China is tilting toward integrated manufacturing clusters for paper-based notebooks and polymer pens, consolidating raw material sourcing with finished goods production. Deli Group Co., Ltd. leverages its domestic distribution density to control shelf presence across tier-two and tier-three cities. Faber-Castell AG anchors premium graphite and colored pencil segments through in-house wood-casing operations and certified sustainable forestry programs. KOKUYO CO., LTD. competes in ergonomic notebook design and campus-focused retail formats across East Asian markets.
School stationery supplies encompass writing implements, binding materials, filing accessories, and art media formulated for educational and administrative tasks, typically manufactured through injection molding of polystyrene or ABS for pens, calendering or offset printing for paper goods, and slot-die coating for adhesive-backed products. These items serve structured learning environments, enabling knowledge recording, assignment organization, and creative skill development. Paper-based notebooks retain the largest volume share within product type segmentation, though plastic-derivative pens command higher per-unit margins and repeat purchase frequency. The arts and crafts usage segment generates outsized margin contribution relative to its volume, as specialty pigments, precision tips, and acid-free papers support premium positioning unavailable in standard classroom commodities.
EU REACH restrictions on phthalate plasticizers and heavy metal pigments constrain formulation choices for pens and markers sold across Europe, while the EU Green Deal pushes manufacturers toward recycled paper content and bio-based barrel materials. India's BIS certification mandates for school supplies ensure product safety for juvenile users, creating compliance barriers for uncertified imports. The US Consumer Product Safety Commission governs sharp point standards and small-part choking hazards, directly shaping design parameters for scissors, compasses, and mechanical pencil components. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer recycling quotas, as these will determine which material platforms and geographic production bases retain cost-competitive access to priority education markets.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing reformulation of plastic barrels and pigment systems across European supply chains, while India's PLI scheme redirects manufacturing capacity toward domestic polymer pen and notebook production.
Growth Catalysts
- K-12 enrollment expansion:Government school drives in India and Indonesia are pulling volume demand for writing instruments and paper-based materials into formal procurement channels.
- REACH compliance:European chemical restrictions on phthalate plasticizers are accelerating shifts toward bio-based barrel polymers and recycled paper content in notebook manufacturing.
- Ergonomic design adoption:Campus-focused retail formats in East Asian markets are elevating demand for precision-molded grips and acid-free paper specifications.
Market Restraints
- Petrochemical input volatility:ABS and polystyrene resin prices fluctuate with crude oil indices, compressing margin stability for injection-molded pen manufacturers.
- Supply concentration risk:Integrated manufacturing clusters in China's Yangtze River Delta control upstream pulp sourcing and finished notebook production, creating single-geography dependency.
- Digital substitution pressure:Tablet-based learning platforms and stylus-digitized assignment submission are eroding replacement rates for graphite pencils and ballpoint pens in upper-secondary segments.
Strategic Opportunities
- Bio-based material convergence:PLA biopolymers and agricultural waste fibers are opening premium positioning for barrel and paper products certified under EU Green Deal circularity criteria.
- Underpenetrated rural India:Tier-three and tier-four city school districts remain underserved by organized distribution, creating whitespace for domestic manufacturers with BIS-certified product lines.
- Extended producer responsibility frameworks:Emerging polymer recycling quotas in European markets will favor producers with captive recycling infrastructure or bio-degradable material platforms.
Industry Challenges
- Certification timeline compression:BIS safety testing for juvenile-use products in India extends lead times for new product introductions, constraining rapid SKU rotation.
- Legacy equipment retooling:Calendering and offset printing lines require capital-intensive upgrades to handle higher recycled fiber content without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School Stationery Supplies Market |
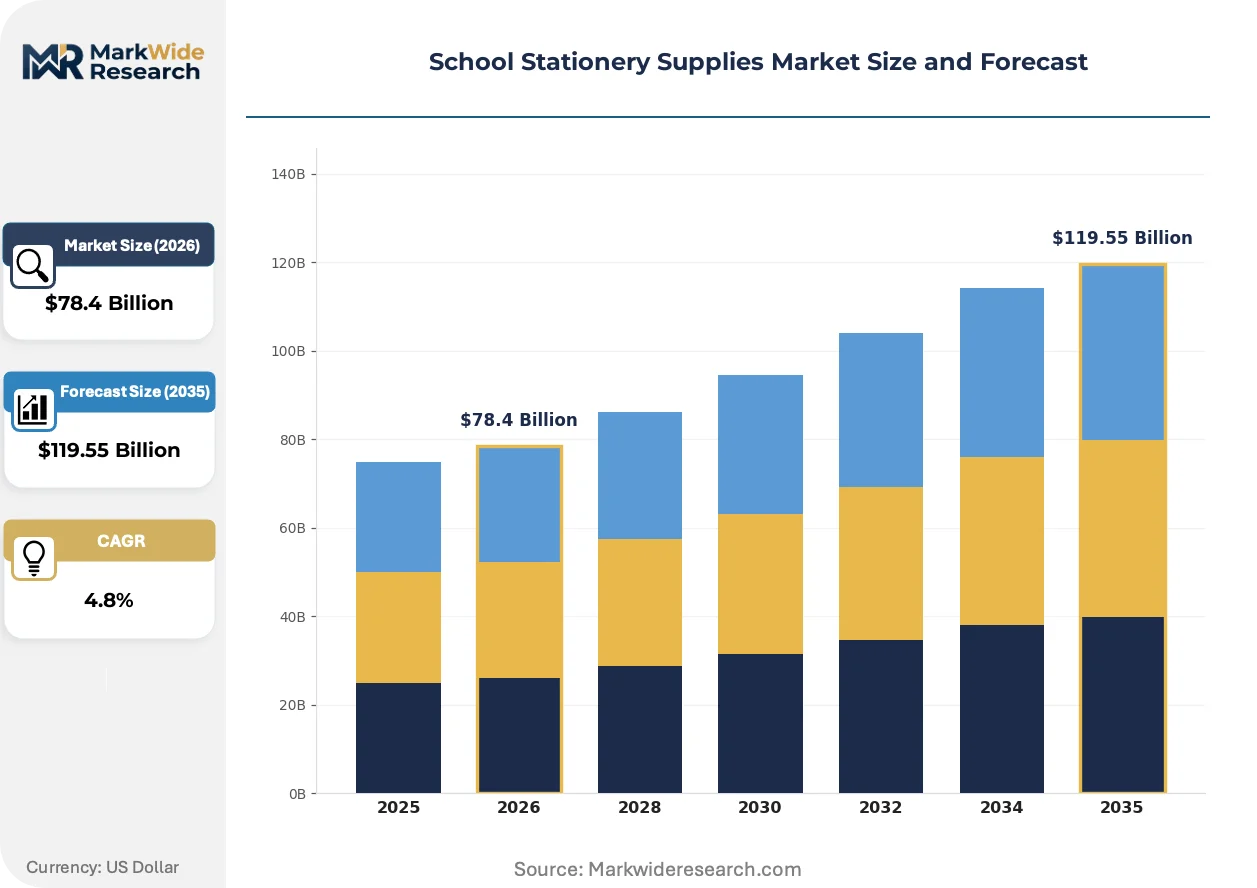
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pens, Pencils, Notebooks, Folders Usage: Home, School, Office, Arts & Crafts Material: Plastic, Paper, Metal, Wood Distribution Channel: Retail Stores, Online, Wholesale, Supermarkets |
| Companies Covered | KOKUYO CO., LTD., Deli Group Co., Ltd., Faber-Castell AG, BIC Group, Beifa Group Co., Ltd., 3M Company, Pilot Corporation, ACCO Brands Corporation, STAEDTLER SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School Stationery Supplies Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are restructuring competitive advantage around sustainable formulation and ergonomic functionality rather than commodity scale.
Plant-based polymer formulations derived from corn starch and sugarcane bagasse are penetrating premium pen barrel production. European educational procurement offices are mandating bio-based content thresholds in tender specifications. This substitution is rendering obsolete conventional petroleum-derived ABS for mid-tier writing instruments in Western European markets.
REACH Annex XVII restrictions on heavy metal pigments are tightening permissible lead and cadmium thresholds in colored pencils and art markers. Manufacturers must reformulate pigment systems or exit European distribution channels. The arts and crafts segment faces the steepest compliance costs due to specialty color breadth requirements and smaller batch production economics.
Institutional buyers are consolidating vendor relationships around full-category suppliers capable of delivering writing instruments, notebooks, and filing accessories through single-source contracts. Campus procurement offices in Japan and South Korea are displacing fragmented stationer networks with direct manufacturer partnerships. This concentration is most visible in metropolitan school districts where administrative cost reduction overrides brand loyalty considerations.
School Stationery Supplies Market Segmentation
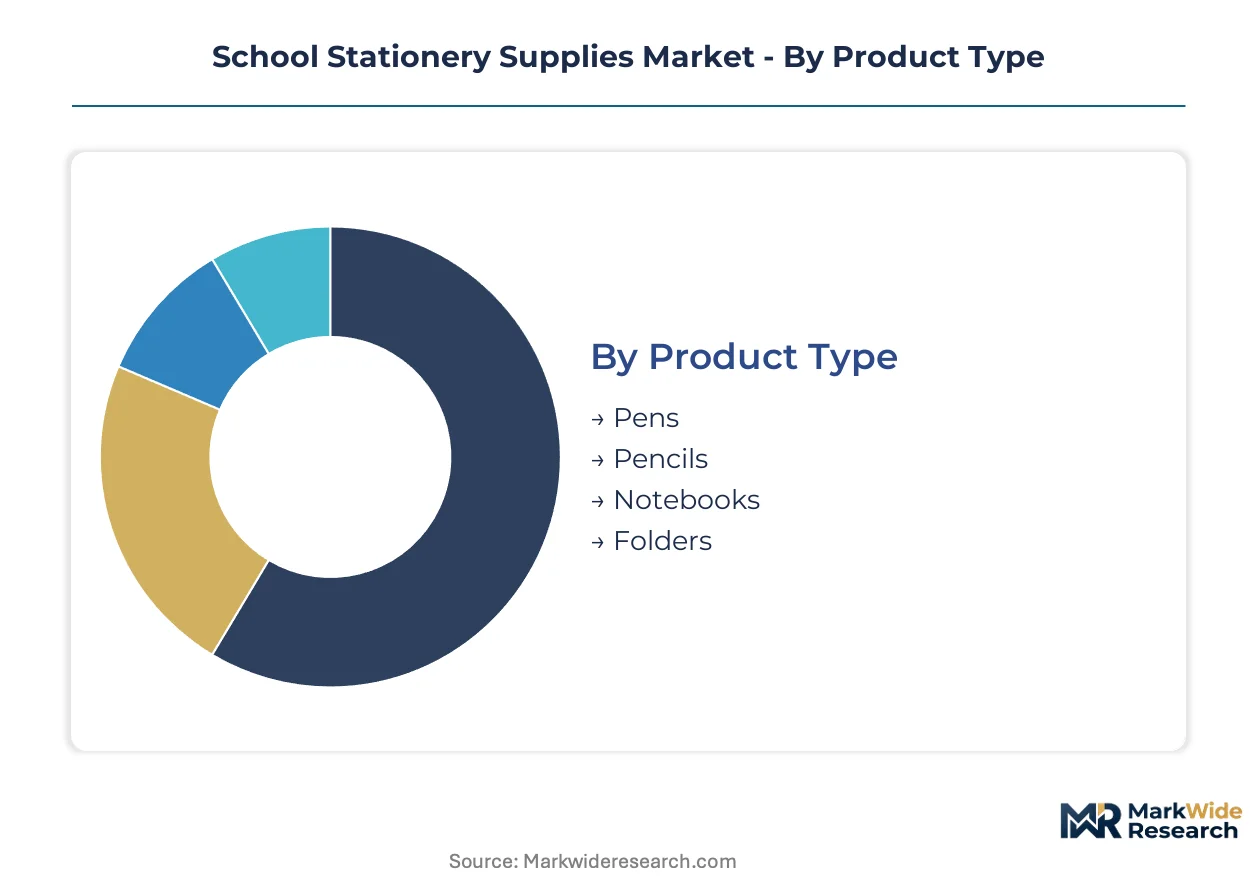
School stationery procurement patterns vary sharply by replacement cadence and institutional buying cycles. Understanding which segments turn over fastest versus which anchor long-term vendor relationships determines inventory strategy and margin capture across distribution channels.
Product Type:
Replacement frequency separates high-turn consumables from durable goods with extended replacement cycles.
- Pens:Polymer-barrel ballpoint and gel instruments dominate repeat purchase frequency. Indian government school procurement channels under the PLI scheme are pulling domestic polymer pen manufacturing capacity into formal tender systems.
- Pencils:Graphite and colored variants retain longer replacement cycles than ink-based instruments. REACH Annex XVII heavy metal pigment restrictions are forcing reformulation of colored pencil lines for European educational distribution.
- Notebooks:Spiral-bound and composition formats anchor institutional volume contracts with predictable semester-based replenishment.
- Folders:Polypropylene and paperboard filing accessories carry the slowest turnover among core categories, purchased primarily at academic year start.
Pens anchor the volume base through highest replacement frequency while notebooks gain share at the steepest rate through consolidated institutional procurement.
Usage:
Application context determines specification requirements and price tolerance across buyer types.
- Home:Individual purchase decisions favor ergonomic features and aesthetic differentiation. Parental buyers in East Asian metropolitan markets prioritize acid-free paper specifications and precision-molded grips for supplemental learning materials.
- School:Institutional procurement concentrates volume through formal tender channels. India's K-12 enrollment expansion is redirecting notebook and writing instrument demand into government-mandated procurement frameworks.
- Office:Administrative standardization favors cost-optimized bulk formats with minimal specification variance.
- Arts & Crafts:Specialty pigments and precision tips command premium positioning unavailable in standard classroom commodities. EU Green Deal circularity criteria are opening premium positioning for bio-based barrel materials in this segment.
School usage anchors procurement volume while Arts & Crafts expands most quickly through premium specification adoption.
Material:
Raw material platforms face divergent regulatory pressure and supply concentration risks.
- Plastic:ABS and polystyrene resin formulations face petrochemical input volatility. EU REACH phthalate plasticizer restrictions are accelerating shifts toward bio-based barrel polymers in European educational markets.
- Paper:Calendered and offset-printed goods retain the largest volume share within material segmentation. China's Yangtze River Delta integrated clusters control upstream pulp sourcing and finished notebook production.
- Metal:Stainless steel mechanical pencil components and compass hardware face US Consumer Product Safety Commission sharp point standards compliance requirements.
- Wood:Casing materials for graphite and colored pencils require certified sustainable forestry programs for premium European positioning.
Paper materials anchor manufacturing scale while plastic formulations face the steepest substitution pressure from bio-based alternatives.
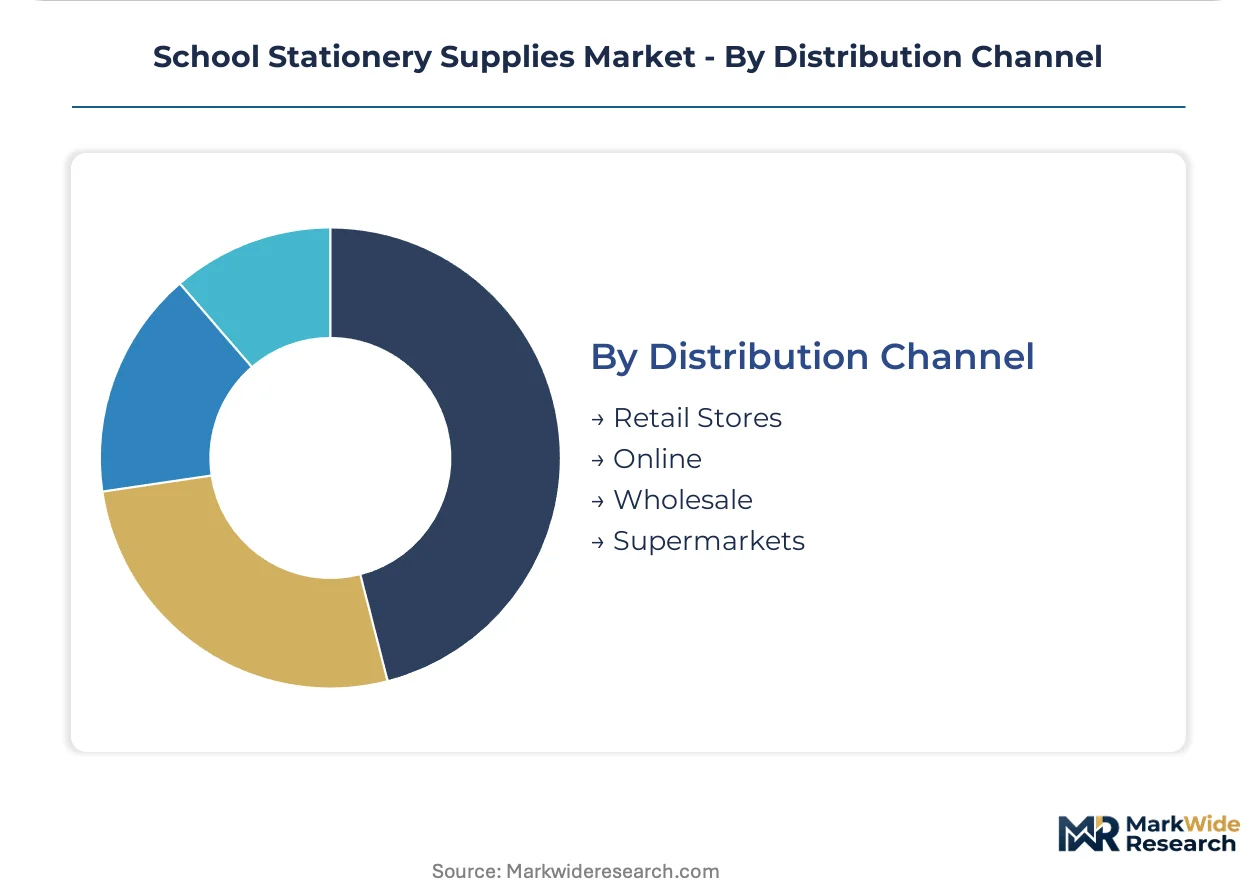
Distribution Channel:
Channel structure determines SKU breadth requirements and margin capture mechanics.
- Retail Stores:Campus-focused formats in Japan and South Korea are consolidating vendor relationships around full-category suppliers capable of single-source contract delivery.
- Online:Direct-to-institution platforms are displacing fragmented stationer networks in metropolitan school districts where administrative cost reduction overrides brand loyalty.
- Wholesale:Bulk procurement channels serve tier-three and tier-four Indian city school districts with BIS-certified product lines.
- Supermarkets:Mass retail formats concentrate standardized SKUs with minimal specification variance for price-sensitive consumer segments.
Retail Stores anchor established procurement relationships while Online channels climb the fastest through institutional buyer consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates and PLI manufacturing incentives are redirecting procurement patterns across the largest K-12 education systems. Regulatory chemistry constraints in Europe and petrochemical input volatility in East Asia are fragmenting competitive positioning across three continents.
India
Government school enrollment drives and domestic manufacturing incentives under the PLI scheme are pulling polymer pen and notebook demand into formal tender channels. BIS certification requirements for juvenile-use products create compliance barriers for uncertified imports. Manufacturing capacity concentrates in Gujarat and Maharashtra, where domestic producers are scaling injection-molding operations to serve tier-three and tier-four city districts.
China
Integrated manufacturing clusters in the Yangtze River Delta are consolidating upstream pulp sourcing with finished notebook and polymer pen production. The country's national standards regulator enforces GB quality specifications for school supplies exported to Belt and Road markets. Zhejiang and Jiangsu provinces host the densest concentrations of calendering lines and injection-molding facilities serving both domestic and export demand.
Germany
REACH Annex XVII restrictions on phthalate plasticizers and heavy metal pigments are forcing reformulation of colored pencil and marker lines for European educational distribution. EU Green Deal circularity criteria are accelerating shifts toward bio-based barrel polymers and recycled paper content. Manufacturing and R&D activity clusters in Bavaria and Baden-Württemberg, where certified sustainable forestry programs support premium wood-casing operations.
United States
The Consumer Product Safety Commission governs sharp point standards and small-part choking hazards, directly shaping design parameters for scissors, compasses, and mechanical pencil components. Tablet-based learning platforms are eroding replacement rates for graphite pencils in upper-secondary segments. Distribution and procurement offices concentrate in the Midwest and Southeast, where bulk institutional contracts anchor volume demand for standardized SKUs.
Japan
Campus-focused retail formats in metropolitan school districts are consolidating vendor relationships around full-category suppliers capable of single-source contract delivery. METI industrial standards guide ergonomic design specifications for precision-molded grips and acid-free paper products. Manufacturing and design capabilities concentrate in the Kanto and Kansai regions, where domestic producers compete on notebook functionality and campus retail presence.
School Stationery Supplies Market Key Industry Players
Scale-driven manufacturers and specialized premium houses split the market into distinct competitive spheres. The vendor base organizes around three strategic archetypes: integrated polymer processors controlling upstream resin sourcing, precision wood-casing specialists with captive forestry certification, and full-category suppliers bundling writing instruments with paper goods for institutional procurement. Competitive moves concentrate on geographic expansion into underpenetrated Indian districts and portfolio diversification toward bio-based material platforms.
Among Japanese producers, KOKUYO CO., LTD. and Pilot Corporation occupy positions within the campus-focused retail and precision instrument tiers. Chinese scale manufacturers include Deli Group Co., Ltd. and Beifa Group Co., Ltd., representing the integrated production archetype. German heritage specialists Faber-Castell AG and STAEDTLER SE exemplify the premium wood-casing and precision coloring segments. These named entities anchor broader industry patterns without exhaustively mapping competitive dynamics.
| Leading Market Players |
|---|
| KOKUYO CO., LTD. |
| Deli Group Co., Ltd. |
| Faber-Castell AG |
| BIC Group |
| Beifa Group Co., Ltd. |
| 3M Company |
| Pilot Corporation |
| ACCO Brands Corporation |
| STAEDTLER SE |
| Others |
Cost & Logistics Intelligence
Petrochemical input volatility in ABS and polystyrene resins compresses margin stability for injection-molded pen manufacturers while simultaneously widening price spreads between bio-based barrel tiers and conventional petroleum-derived alternatives across European and Indian procurement channels.
Pricing Analysis
Price differentiation between Germany and India exceeds threefold for comparable polymer-barrel ballpoint instruments due to REACH compliance costs and domestic manufacturing scale under the PLI scheme. Three-tier pricing structure across premium, standard, and economy levels separates Faber-Castell's certified sustainable forestry products from mid-tier KOKUYO campus formats and unbranded Chinese imports. Pricing pressure stems from tablet-based learning platforms eroding replacement rates for graphite pencils in upper-secondary segments. Government school procurement officers in tier-three Indian cities exhibit highest price sensitivity, while East Asian metropolitan parents purchasing supplemental learning materials show lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates in Zhejiang and Jiangsu provinces where Deli Group and Beifa Group operate integrated injection-molding and calendering facilities serving both domestic and export demand. Raw material sourcing draws from Yangtze River Delta pulp mills for paper goods and Sinopec affiliate resin producers for polymer barrels. Supply chain risk centers on single-geography dependency for upstream pulp sourcing and finished notebook production. Distribution runs through campus-focused retail formats in Japan and South Korea consolidating around full-category suppliers, alongside direct-to-institution online platforms displacing fragmented stationer networks in metropolitan school districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital stylus substitution and tablet-based learning platforms threaten volume replacement rates for conventional writing instruments, compelling incumbents to defend positioning through material innovation and ergonomic differentiation.
For Market Incumbents: Entrench bio-based material capabilities ahead of EU Green Deal circularity quota implementation, securing captive supply of PLA biopolymers and agricultural waste fibers. Deepen backward integration into certified sustainable forestry programs for premium wood-casing operations serving European educational procurement offices. Channel control through campus-focused retail formats in East Asia remains essential against direct manufacturer partnership consolidation.
For New Entrants and Emerging Players: Pursue underpenetrated tier-three and tier-four Indian city school districts where BIS certification barriers exclude uncertified imports and organized distribution remains sparse. Target government tender channels under the PLI scheme with BIS-compliant polymer pen and notebook lines. Go-to-market leverage rests on wholesale bulk procurement relationships with district education officers rather than brand building.
For Investors and Strategic Acquirers: EU REACH Annex XVII heavy metal pigment restrictions reshape the acquisition landscape toward pigment reformulation capabilities and bio-based barrel material platforms. Long-term viability across the analysis window favors producers with captive recycling infrastructure or biodegradable material certifications. Acquisition target archetype: mid-scale Indian manufacturers with BIS certification and PLI scheme alignment. Signal to monitor: European extended producer responsibility framework implementation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Material Transition | PLA biopolymer adoption satisfies EU Green Deal circularity criteria for educational procurement tenders. |
| BIS Certification Investment | Indian safety testing compliance unlocks government school tender channels under enrollment expansion programs. |
| Campus Retail Format Consolidation | Single-source vendor relationships displace fragmented stationer networks in Japanese metropolitan districts. |
| Ergonomic Design R&D | Precision-molded grips and acid-free paper specifications capture East Asian parental purchasing premiums. |
| Recycling Infrastructure Buildout | Captive polymer recycling capabilities secure cost-competitive access to European markets under emerging quotas. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across trade and regulatory sources. Primary engagement encompassed procurement officers at Indian state education departments, product development leads at Japanese campus retail suppliers, regulatory affairs managers navigating REACH compliance, and distribution channel heads in China's Yangtze River Delta clusters. Secondary sources included BIS certification registries, EU ECHA REACH Annex XVII restriction updates, Indian PLI scheme beneficiary disclosures, customs trade data for pulp and resin imports, and SEC filings from listed stationery manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across product type, usage, material, and distribution channel dimensions.
Forecast inputs considered K-12 enrollment trajectories in India and Indonesia, petrochemical price indices for ABS and polystyrene resins, and regulatory implementation timelines for EU extended producer responsibility frameworks. Segmentation modeling spanned product type replacement cadence, usage context specification requirements, material platform regulatory exposure, and channel structure margin capture mechanics. CAGRs were derived from slope analysis across the projection horizon, calibrated to historical volume-price elasticity in polymer pen and notebook categories.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, rupee-yuan exchange rates, or European regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding PLI scheme continuation and REACH restriction expansion. Quarterly review of Indian government school enrollment disbursements, EU bio-based content threshold announcements, and Yangtze River Delta pulp pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Global Office Peripherals and Products Market
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Diaries & Planners Market
Office Supplies
Marker Pens Market
Office Supplies
Copiers Market
Office Supplies
Stamp Pad Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Business Card Holder Market
Office Supplies
Cutter Staplers Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Custom Binders Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Stationery Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Student Stationery Market