
 US Cold Storage Market | 2026-2036
US Cold Storage Market Size, Share, and Industry Trends Forecast 2026-2036
US Cold Storage Market Intelligence
The influx of private equity and the use of sale-leaseback financing for facility expansion is reconfiguring the competitive field. Industry leader Lineage Logistics leverages this capital to acquire smaller regional operators and expand its network. Americold Logistics sustains its market position through a vast portfolio of automated facilities, while United States Cold Storage specializes in customized solutions for food processors.
US cold storage refers to the warehousing of goods in a temperature-controlled environment, typically maintained between -20°F for frozen items and 36°F for refrigerated products. Its primary purpose is to preserve the quality and safety of perishable items like food and pharmaceuticals. The market's service offerings are dominated by Public Warehousing, which provides flexibility for various end users. Within product types, the specialized requirements for storing seafood and processed meat command higher service fees.
The US Department of Agriculture (USDA) and the Food and Drug Administration (FDA) establish the primary regulatory framework. The FDA's Food Safety Modernization Act (FSMA) mandates verifiable temperature logs and sanitary transport, directly influencing technology adoption for monitoring systems. Operators must decide whether to invest in high-cost automation to offset labor shortages or focus on energy efficiency to manage rising operational expenses.
Market Dynamics
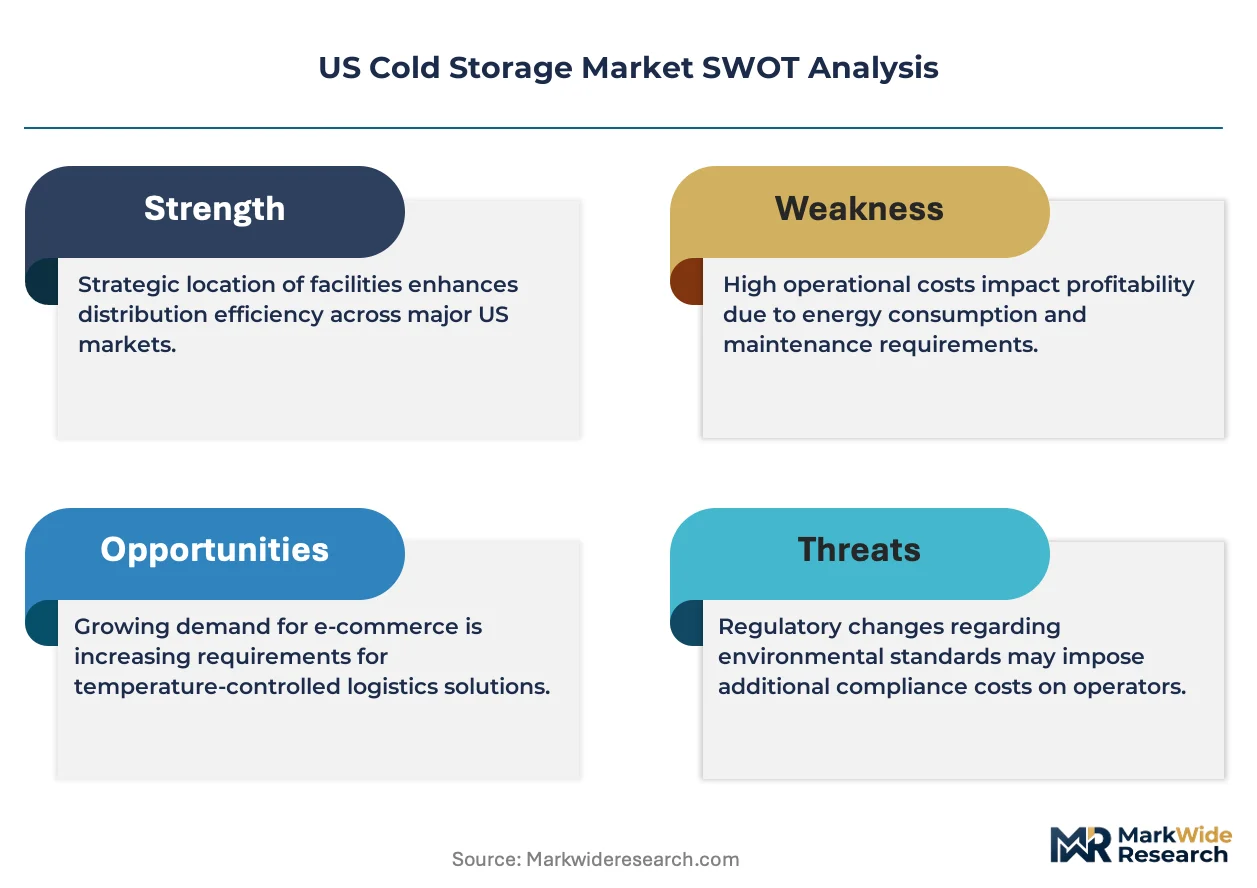
The central force shaping the US cold storage market is the intensification of regulatory requirements for supply chain integrity. Mandates from the FDA, particularly for biopharmaceuticals and perishable foods, are compelling operators to invest heavily in advanced monitoring, automation, and verifiable documentation systems to maintain compliance.
Growth Catalysts
- FDA Modernization:The Food Safety Modernization Act (FSMA) continues to drive investment in sophisticated temperature monitoring and tracking technologies, as verifiable data logs are now a prerequisite for food handling and transport.
- Biopharma Expansion:The pharmaceutical sector's demand for specialized, temperature-sensitive storage for biologics, vaccines, and cell therapies creates a high-margin service opportunity for facilities capable of meeting stringent validation and handling protocols.
- Logistics Hub Concentration:Continued investment in large-scale cold storage facilities within major logistics hubs, such as those in Texas and Florida, improves network efficiency and attracts large-volume food and pharmaceutical clients seeking national distribution.
Market Restraints
- Energy Cost Volatility:High and unpredictable electricity costs represent a significant structural restraint, directly impacting operational margins and the financial viability of older, less energy-efficient facilities.
- High Capital Intensity:The substantial upfront capital investment required to construct and equip modern, automated cold storage facilities acts as a significant barrier to entry for smaller, independent operators.
- Land Scarcity:A shortage of appropriately zoned and located industrial land near major US transportation arteries and population centers constrains new development and inflates real estate acquisition costs.
Strategic Opportunities
- Micro-Fulfillment for E-Commerce:Developing smaller, urban-centric cold storage facilities to support direct-to-consumer (DTC) grocery and meal kit delivery offers a path to serve last-mile logistics needs.
- On-Site Renewable Energy:Integrating on-site renewable energy generation, such as solar panel installations paired with battery storage, presents an opportunity to mitigate energy price volatility and lower long-term operating expenses.
- Value-Added Service Bundling:Expanding service offerings beyond basic storage to include integrated logistics, blast freezing, kitting, and packaging allows operators to capture more of the supply chain value.
Industry Challenges
- Skilled Labor Shortages:A persistent challenge is the scarcity of technicians and engineers qualified to operate and maintain the sophisticated automation and robotics systems being deployed in modern warehouses.
- Systems Integration Complexity:Operators face significant hurdles in seamlessly integrating their warehouse management systems (WMS) with the diverse enterprise resource planning (ERP) software used by their clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cold Storage Market |
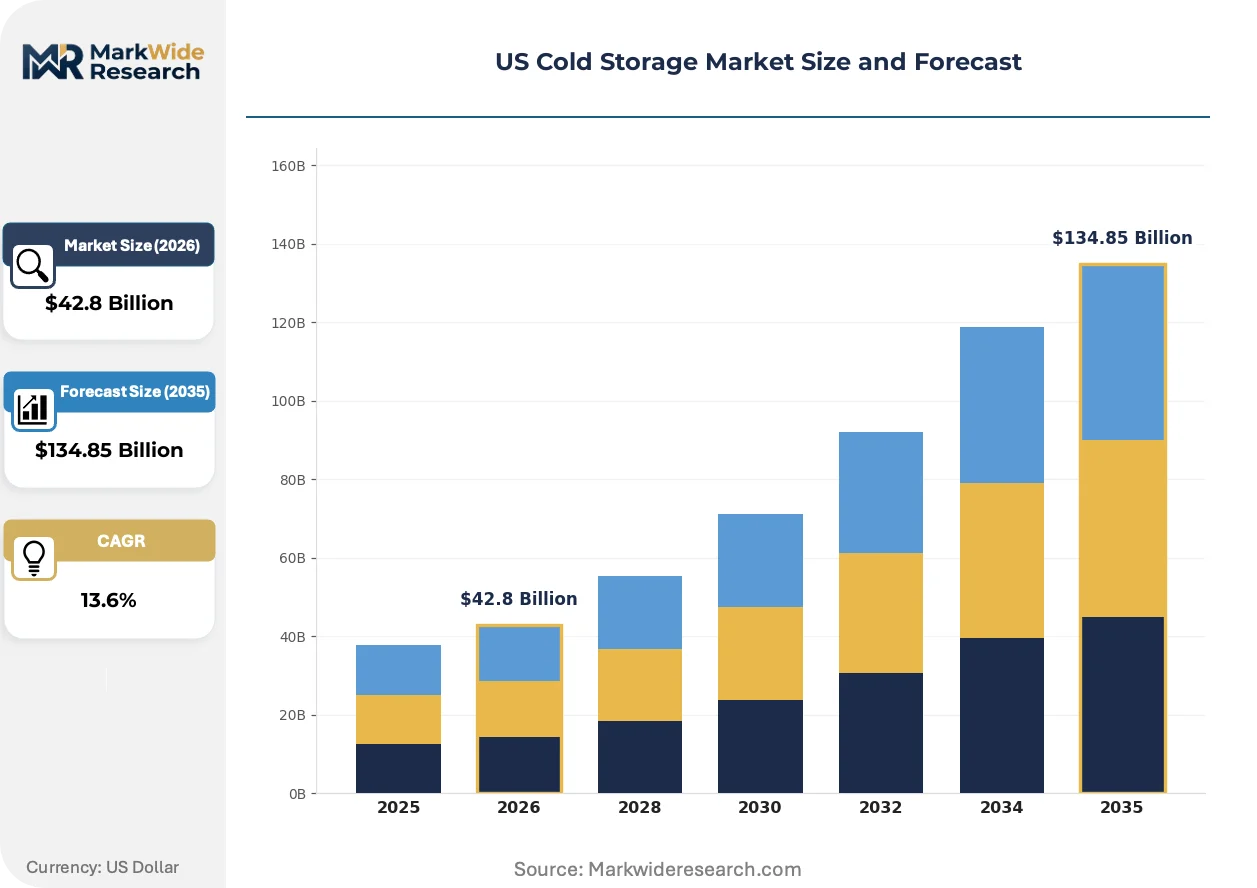
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $134.85 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy Products, Meat, Seafood, Fruits Technology: Refrigeration Systems, Freezers, Insulated Containers, Monitoring Systems End User: Retailers, Wholesalers, Food Processors, Restaurants Service Type: Public Warehousing, Private Warehousing, Third-party Logistics, Managed Services |
| Companies Covered | Lineage Logistics, Americold Logistics, United States Cold Storage, Interstate Warehousing, FreezPak Logistics, Conestoga Cold Storage, Burris Logistics, NewCold Holdings, VersaCold Logistics Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cold Storage Market Strategic Shifts & Innovations
Facility design and operational models are evolving from static storage depots into dynamic, data-driven nodes within the perishable supply chain. This transformation is driven by pressures for greater efficiency, transparency, and service customization across the US market.
Digital twin technology creates a real-time virtual simulation of a cold storage facility's physical environment and operational workflows. Large-scale operators in the food processing and pharmaceutical logistics sectors are leading its adoption. This technology is virtualizing facility management, enabling predictive maintenance on refrigeration systems, optimizing energy consumption, and simulating workflow changes to improve throughput.
The FDA's Food Safety Modernization Act (FSMA), particularly its rule on the Sanitary Transportation of Human and Animal Food, establishes stringent new compliance benchmarks. This regulation requires operators to provide verifiable proof of temperature integrity throughout the entire storage and transit journey. The fresh produce and seafood segments are most directly impacted, compelling investment in IoT sensors and cloud-based logging systems to ensure auditable compliance.
A notable shift in customer behavior involves moving away from long-term, fixed-space contracts toward more flexible, on-demand warehousing agreements. This trend disrupts the traditional public warehousing model, creating an advantage for operators who can offer variable capacity and pay-per-use pricing. This pattern is most prominent among e-commerce grocery platforms and seasonal food producers in high-demand markets like the Southeast and West Coast.
US Cold Storage Market Segmentation
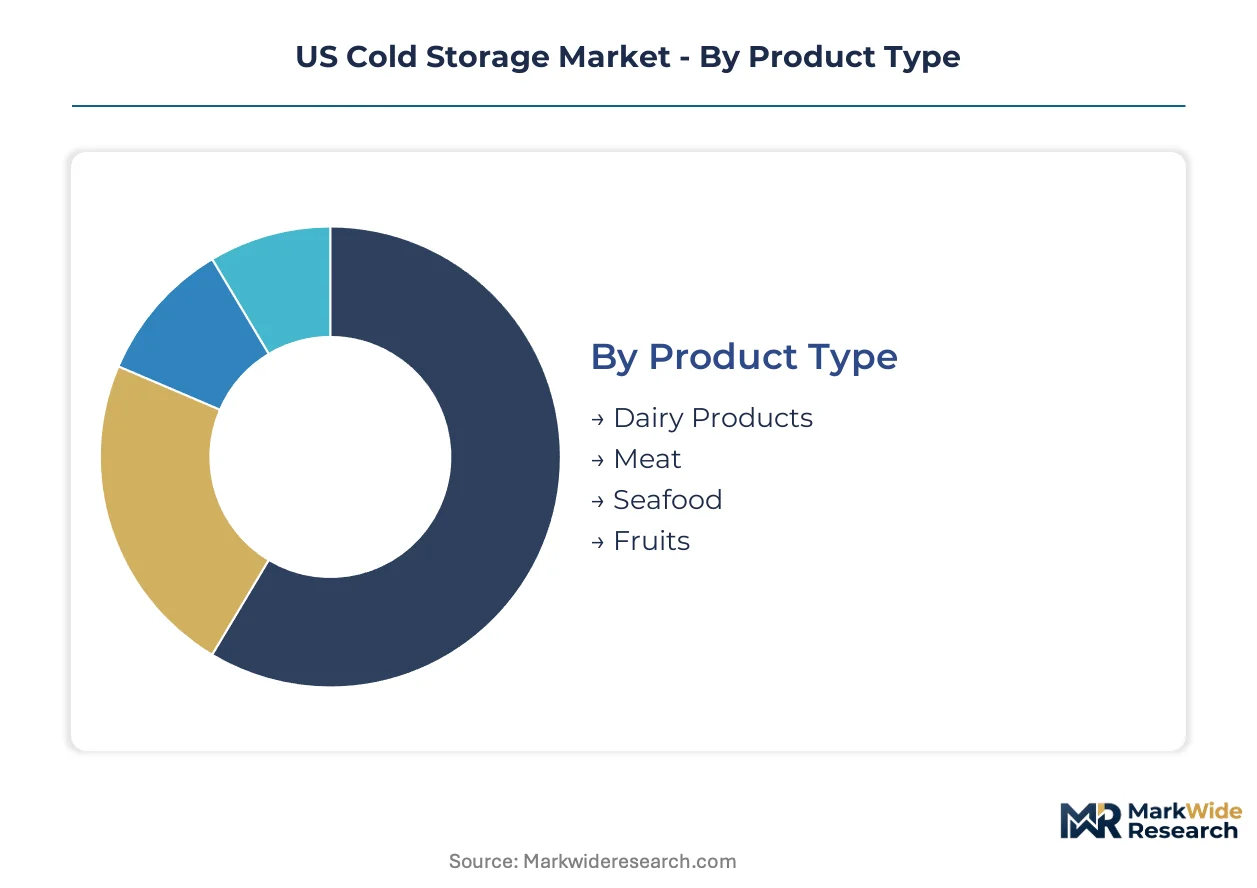
The US cold storage market's segmentation reveals the diverse operational requirements and strategic focus areas for industry participants. Understanding these distinct categories helps stakeholders identify opportunities for specialization and capital allocation across the perishable goods supply chain.
Product Type:
The US cold storage market for product types spans a maturity spectrum, from established staples to rapidly evolving specialty segments.
- Seafood:This segment requires precise temperature control, often below 0°F, to maintain quality and prevent spoilage. Demand is concentrating in coastal logistics hubs and urban centers, driven by consumer preferences for fresh and frozen seafood products.
- Meat:Storing meat products, including poultry and beef, necessitates strict temperature ranges, typically between 28°F and 32°F for refrigerated, or below 0°F for frozen. This segment sees significant demand from food processors and retail distribution networks, influenced by USDA regulations.
- Dairy Products:Dairy storage involves maintaining consistent refrigeration, usually between 34°F and 38°F, to extend shelf life and ensure food safety. This category serves a broad consumer base through grocery retailers and food service providers.
- Fruits:Fresh fruit storage requires specific humidity and temperature management to slow ripening and preserve freshness. Seasonal demand patterns significantly influence capacity utilization in this segment.
Seafood handles the majority of throughput; Meat is the fastest mover on share.
Technology:
Technology segmentation highlights the diverse functional requirements across cold chain operations, impacting efficiency and compliance.
- Monitoring Systems:These systems utilize IoT sensors and cloud-based platforms to track temperature, humidity, and other environmental parameters in real-time. Their demand is intensifying due to FDA's FSMA mandates for verifiable temperature logs, particularly for pharmaceuticals and fresh produce.
- Refrigeration Systems:This core technology includes compressors, condensers, and evaporators designed to maintain precise temperature ranges within cold storage facilities. Investment in energy-efficient refrigeration is a priority for operators managing rising electricity costs.
- Freezers:Specialized freezer units provide ultra-low temperature environments crucial for sensitive products like biologics and certain frozen foods. These systems are critical for pharmaceutical cold chain integrity and long-term food preservation.
- Insulated Containers:These passive or active containers maintain temperature during transport and temporary storage, reducing thermal excursions. They are vital for last-mile delivery and intermodal shipping of perishable goods.
Monitoring Systems are seeing the most significant investment due to regulatory pressures, while Refrigeration Systems remain central to foundational infrastructure development.
End User:
End-user segments define distinct service requirements, reflecting varied business models and scale within the US cold storage sector.
- Food Processors:These clients require customized cold storage solutions, often involving blast freezing, cross-docking, and specialized handling for raw ingredients and finished goods. Their demand is concentrated near agricultural production zones and major distribution hubs.
- Retailers:Retailers leverage cold storage for inventory management, consolidation, and distribution to their store networks or e-commerce fulfillment centers. The expansion of online grocery delivery is driving demand for micro-fulfillment and urban cold storage capacity.
- Wholesalers:Wholesalers use cold storage for bulk purchases and onward distribution to smaller businesses, restaurants, and institutions. Their operational focus is on high-volume throughput and efficient inventory turns.
- Restaurants:Restaurants typically require smaller, more frequent deliveries of refrigerated and frozen ingredients to manage fresh inventory. Their cold storage needs are often met through third-party logistics providers or local distribution centers.
Food Processors account for the largest share of capacity, with Retailers exhibiting dynamic growth based on evolving consumer habits.
Service Type:
Supply concentration varies significantly across service type offerings, influencing operational models and competitive dynamics.
- Public Warehousing:This service offers flexible, shared storage space and services to multiple clients, suitable for varying inventory levels. It remains the dominant service model, providing scalability for diverse end users across the US.
- Third-party Logistics:3PL providers offer integrated supply chain solutions beyond basic storage, including transportation, inventory management, and value-added services like kitting and packaging. This segment is growing due to companies seeking to outsource complex logistics.
- Private Warehousing:Companies own and operate these facilities exclusively for their own products, offering complete control over operations and security. This model is favored by large enterprises with consistent, high-volume storage needs.
- Managed Services:This involves outsourcing the management and operation of a client's cold storage facility to a specialized provider. It offers operational expertise and efficiency without the upfront capital investment of private ownership.
The shift towards Third-party Logistics reflects a need for operational flexibility, while Public Warehousing maintains its foundational role in market capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's Food Safety Modernization Act (FSMA) significantly influences cold storage development across the United States. This regulatory framework mandates stringent temperature controls and verifiable documentation for perishable goods. Consequently, investment concentrates in strategic logistics hubs to optimize supply chain integrity and distribution efficiency.
Texas
Demand for cold storage in Texas stems from its extensive food processing industry and growing energy sector. The USDA's stringent regulations for meat and poultry drive investment in advanced temperature-controlled facilities. Major logistics hubs like Dallas-Fort Worth and Houston serve as critical distribution points for both domestic and international trade.
Florida
Florida's cold storage market benefits from high demand for imported fresh produce and pharmaceutical distribution. FDA mandates for temperature-sensitive goods, especially biopharma, necessitate specialized facilities. Miami and Orlando function as primary hubs, facilitating extensive trade with Latin America and serving a large tourism industry.
California
California exhibits strong demand for cold storage driven by its vast agricultural exports and expanding e-commerce grocery sector. The state's environmental regulations, coupled with federal FSMA requirements, influence facility design and energy efficiency. The Central Valley and the Los Angeles/Long Beach port complex are vital for processing and distributing perishable items.
Midwest
The Midwest region experiences significant cold storage demand from its concentrated food processing and dairy industries. USDA food safety standards for processed foods directly shape operational protocols and facility investments. Cities like Chicago and Kansas City function as central distribution points, leveraging their geographic position for national cold chain logistics.
US Cold Storage Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic competitive environment in the US cold storage market. This sector features a tiered structure, including large, integrated operators and numerous regional and niche providers. Key archetypes include scale-driven consolidators, technology-focused innovators, and providers of customized solutions. Market participants frequently engage in mergers and acquisitions to expand their network and form strategic partnerships for specialized service offerings.
At the scale-driven end of the market, Lineage Logistics and Americold Logistics represent major consolidated players. Lineage Logistics exemplifies a consolidator, leveraging private equity to acquire smaller regional operators and expand its extensive network. Americold Logistics occupies a position as a technology-focused innovator, known for its vast portfolio of automated facilities. United States Cold Storage sits within the customized solution provider archetype, specializing in tailored offerings for food processors. These companies collectively anchor significant market capacity and influence operational standards across the industry.
Leading Market Players
| Leading Market Players |
|---|
| Lineage Logistics |
| Americold Logistics |
| United States Cold Storage |
| Interstate Warehousing |
| FreezPak Logistics |
| Conestoga Cold Storage |
| Burris Logistics |
| NewCold Holdings |
| VersaCold Logistics Services |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints from FDA compliance directly determine pricing tier spreads for specialized cold storage and shape the supply chain's investment in advanced facilities. This market faces structural challenges from energy cost volatility and land scarcity, impacting operational viability and expansion strategies.
Pricing Analysis
FDA validation for biopharma products creates the primary pricing spread in specialized cold storage services. Contract-based long-term offtake agreements dominate for large-volume clients, while public warehousing offers per-unit transactional pricing. Price differentiation drivers include the specific certification level required for pharmaceuticals and the automation level within facilities. Pricing pressure stems from high energy costs impacting older, less efficient facilities. Pharmaceutical companies and specialized food processors exhibit lower price sensitivity compared to general retailers and wholesalers.
Supply Chain Analysis
Sale-leaseback financing facilities enable cold storage operators to expand rapidly, impacting the supply chain's capital allocation. Supply concentration for new facilities centers on major logistics hubs in Texas, Florida, and California. The supply chain draws from refrigeration components, advanced insulation materials, and IoT sensors. Land scarcity near major transportation arteries represents a structural supply chain risk. Distribution runs through a dominant network of public warehousing and third-party logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US cold storage market presents a significant service-attach opportunity, with advanced monitoring systems and data analytics expanding faster than core physical infrastructure.
For Market Incumbents: Harden existing facility networks against energy cost volatility through on-site renewable energy integration. Consolidate market share by acquiring smaller regional operators to expand geographic reach and specialized service capabilities. Invest in automation technologies to mitigate skilled labor shortages and improve operational efficiency. Focus on achieving stringent FDA validation for biopharma storage to capture high-margin demand.
For New Entrants and Emerging Players: Establish a beachhead in micro-fulfillment for e-commerce grocery platforms within urban centers. Target niche, high-margin biopharma storage solutions requiring specialized validation and handling protocols. A go-to-market angle involving value-added service bundling, such as kitting and packaging, can differentiate offerings. Focus on flexible, pay-per-use warehousing models to attract seasonal food producers and e-commerce platforms.
For Investors and Strategic Acquirers: The FDA's Food Safety Modernization Act reshapes the acquisition landscape by prioritizing facilities with verifiable compliance infrastructure. This market represents essential infrastructure for perishable goods, driven by non-discretionary demand over the long term. Target technology-focused innovators with high automation levels or specialized biopharma facilities for strategic acquisitions. Increased M&A activity focused on facilities in logistics hubs with advanced monitoring capabilities signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Network Expansion via Acquisition | Lineage Logistics expands its national distribution capabilities for diverse food and pharmaceutical clients. |
| Automation Technology Investment | Americold Logistics enhances operational efficiency and mitigates skilled labor shortages in its facilities. |
| Renewable Energy Integration | Operators reduce energy cost volatility and improve long-term operational margins for cold storage. |
| Specialized Biopharma Validation | Facilities capture high-margin service opportunities from the pharmaceutical sector's stringent storage needs. |
| Micro-Fulfillment Hub Development | Urban-centric cold storage supports direct-to-consumer grocery and meal kit delivery for e-commerce. |
Research Approach
A standing panel of cold chain logistics directors, food safety officers, and pharmaceutical supply chain managers provided ongoing calibration. Primary interviews with these industry stakeholders were combined with secondary validation from USDA reports, FDA guidance documents, and industry association publications. Bottom-up and top-down triangulation ensured data consistency across market segments.
Scenario-bracketing was applied to model market evolution across various economic and regulatory environments. The analytical framework projected market growth across the analysis window, segmenting by product type, technology, end-user, service type, and regional logistics hub concentration. Compound annual growth rates were derived from historical data extrapolation and projected demand drivers like perishable food consumption trends and biopharmaceutical R&D pipelines.
Stress conditions across energy price fluctuations and regulatory enforcement levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding market dynamics and technology adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Nigeria Cocoa Processing Market