
 Asia-Pacific Walk-In Refrigerators and Freezers Market | 2026-2036
Asia-Pacific Walk-In Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Walk-In Refrigerators and Freezers Market Outlook
Food processing units are unwinding legacy procurement patterns as quick-service restaurants and cloud kitchen networks expand refrigerated footprint across Southeast Asian cities. Hussmann Corporation leverages its compressor technology leadership to anchor premium installations in Australia's retail grocery expansion. Daikin Industries sustains dominance in vapor compression systems through captive control over inverter-driven scroll manufacturing. Panasonic Corporation differentiates via IoT-enabled temperature monitoring platforms integrated into modular cold rooms.
Walk-in refrigerators and freezers are engineered insulated enclosures utilizing polyurethane-injected panels with thermal conductivity ratings below 0.022 W/mK, designed to maintain temperatures from -40°C to 10°C for bulk perishable storage in commercial and industrial settings. The equipment serves primary functions in food safety compliance, inventory batch holding, and pharmaceutical cold chain integrity across high-throughput facilities. Walk-in coolers occupy the largest installed base across retail stores and restaurants, while solar-powered refrigeration technology represents the fastest-expanding category as island nations and rural India deploy off-grid cold storage. Combo units command margin premiums in hotels and food processing units seeking flexible temperature zoning within constrained footprints.
Japan's METI enforces stringent energy efficiency standards under Top Runner programs that compel manufacturers to phase hydrofluorocarbon refrigerants, while Australia's Department of Climate Change, Energy, the Environment and Water administers hydrofluorocarbon import quotas aligning with Kigali Amendment commitments. India's Bureau of Energy Efficiency mandates star ratings for commercial refrigeration equipment, directly influencing procurement specifications in food processing corridors. Stakeholders must monitor refrigerant transition timelines and panel insulation fire-safety certifications as these standards tighten across the region.
Market Dynamics
Cold-chain traceability mandates from pharmaceutical regulators across Southeast Asia are forcing warehouse operators to replace aging equipment with connected, audit-ready refrigeration systems before compliance deadlines.
Growth Catalysts
- Pharmaceutical cold-chain mandates:India's CDSCO and Vietnam's drug administration now require temperature-logging documentation for vaccine distribution, accelerating replacement of non-compliant storage.
- Natural refrigerant transitions:Australia's hydrofluorocarbon import quotas under Kigali Amendment commitments are pulling demand toward ammonia and CO₂-based systems in new facility construction.
- Seafood export corridors:Vietnam's Mekong Delta processing hubs are expanding blast-freezer capacity to meet EU EFSA sanitary certification requirements for frozen shrimp shipments.
Market Restraints
- Polyurethane panel feedstock volatility:Isocyanate and blowing-agent prices fluctuate with crude-oil derivatives, compressing margins for panel fabricators serving price-sensitive Indian food processors.
- Compressor supply concentration:Scroll and semi-hermetic compressor assembly concentrates in Chinese manufacturing zones, exposing Southeast Asian integrators to shipping-cost spikes and customs delays.
- Grid reliability gaps:Rural India and Indonesian archipelago markets face voltage-stability limitations that degrade inverter-driven system performance and accelerate compressor wear.
Strategic Opportunities
- Off-grid solar cold storage:India's rural agricultural mandis and Indonesian fishing cooperatives are deploying photovoltaic-powered walk-in units where grid extension remains uneconomical.
- Modular IoT integration:Cloud-kitchen networks in Bangkok and Jakarta are specifying plug-and-play cold rooms with pre-integrated temperature-monitoring telemetry to reduce commissioning time.
- Refrigerant retrofit incentives:Japan's METI Top Runner program offers efficiency rebates for early hydrofluorocarbon phase-out, creating upgrade pull in Tokyo-Osaka logistics corridors.
Industry Challenges
- Natural refrigerant technician scarcity:Ammonia and CO₂ system installation and servicing require specialized certification pathways that remain underdeveloped across Southeast Asian vocational institutes.
- Fire-safety certification bottlenecks:Panel insulation materials must secure updated BIS and JIS fire-resistance ratings as building codes tighten, extending procurement lead times for Indian hospital and hotel projects.
- Legacy control integration:Food processors operating 15-20 year-old facilities face incompatible communication protocols when retrofitting IoT monitoring onto existing electromechanical thermostat systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Walk-In Refrigerators and Freezers Market |
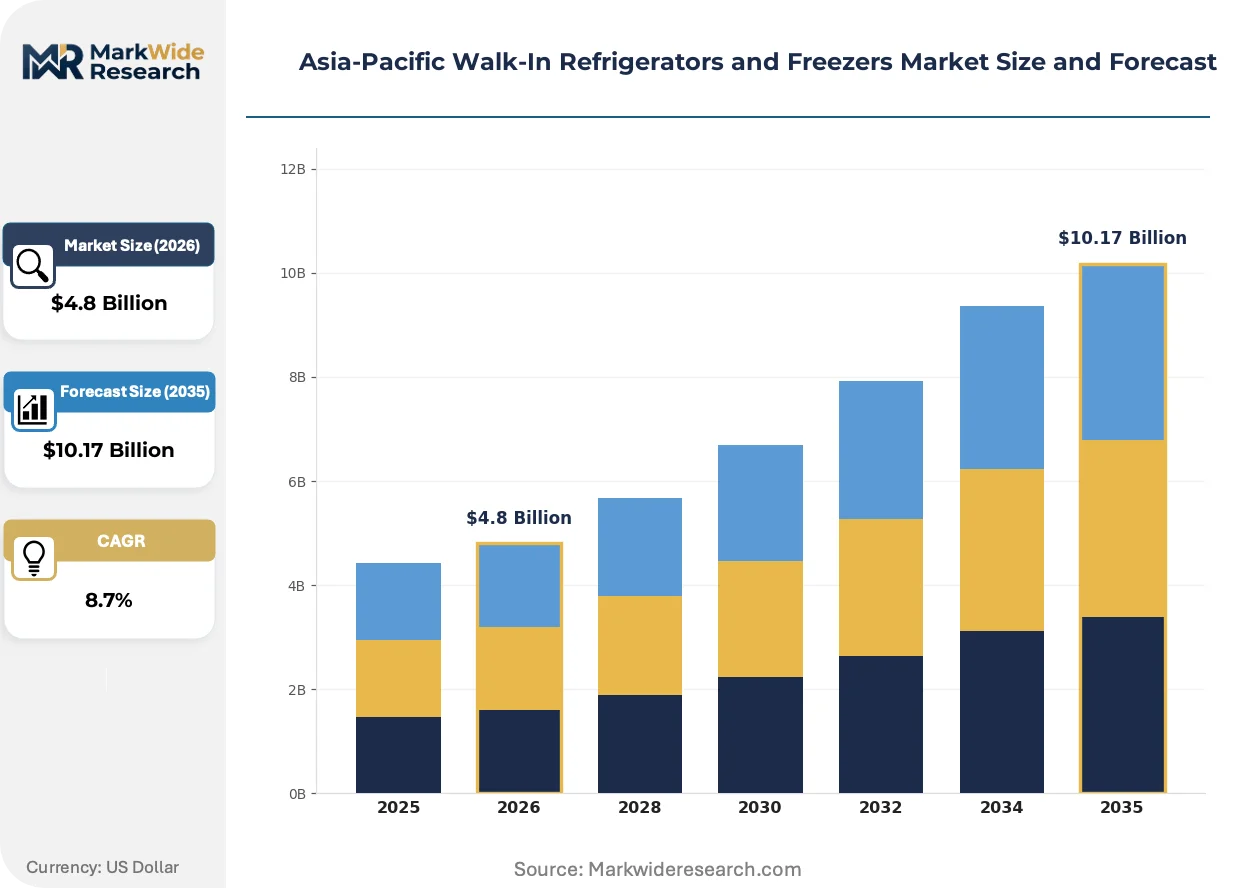
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-In Coolers, Walk-In Freezers, Combo Units, Display Freezers End User: Retail Stores, Restaurants, Hotels, Food Processing Units Installation Type: On-Site Installation, Pre-Fabricated Units, Custom Solutions, Modular Systems Refrigeration Technology: Vapor Compression, Absorption, Cascade, Solar-Powered |
| Companies Covered | Hussmann Corporation, Daikin Industries, Panasonic Corporation, Fujimak Corporation, Hoshizaki Corporation, Fukushima Industries Corporation, Frigoglass S.A.I, AB Electrolux, Haier Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Walk-In Refrigerators and Freezers Market Strategic Shifts
Equipment specification is pivoting from capacity-centric procurement toward energy-performance contracting and predictive-maintenance service bundles. Manufacturers are repositioning around total-cost-of-ownership metrics rather than upfront capital expenditure.
Variable-speed scroll compressor technology is miniaturizing. These compact inverter-driven units modulate capacity to match real-time thermal load, eliminating the energy penalty of on-off cycling. Quick-service restaurant chains in Singapore and Sydney are specifying these systems for smaller-format urban kitchens. The technology is miniaturizing footprint requirements, enabling walk-in installation in retail basements and converted parking structures previously excluded by ceiling-height constraints.
Australia's Department of Climate Change, Energy, the Environment and Water administers hydrofluorocarbon import quotas that ratchet down allowable volumes through 2036. This policy compresses availability of high-global-warming-potential refrigerants for equipment servicing. Cold-storage operators in Melbourne and Brisbane are accelerating full-system replacement rather than retrofit, prioritizing natural refrigerant platforms to lock in long-term compliance certainty.
Cloud-kitchen networks are consolidating procurement authority at regional headquarters rather than granting site-level equipment selection. This centralization favors standardized modular cold-room specifications with unified IoT dashboards across multi-city footprints. The shift is most visible in India's Bengaluru-Mumbai-Delhi triangle, where aggregator platforms negotiate fleet-scale maintenance contracts covering dozens of dark-kitchen locations under single service-level agreements.
Asia-Pacific Walk-In Refrigerators and Freezers Market Segmentation
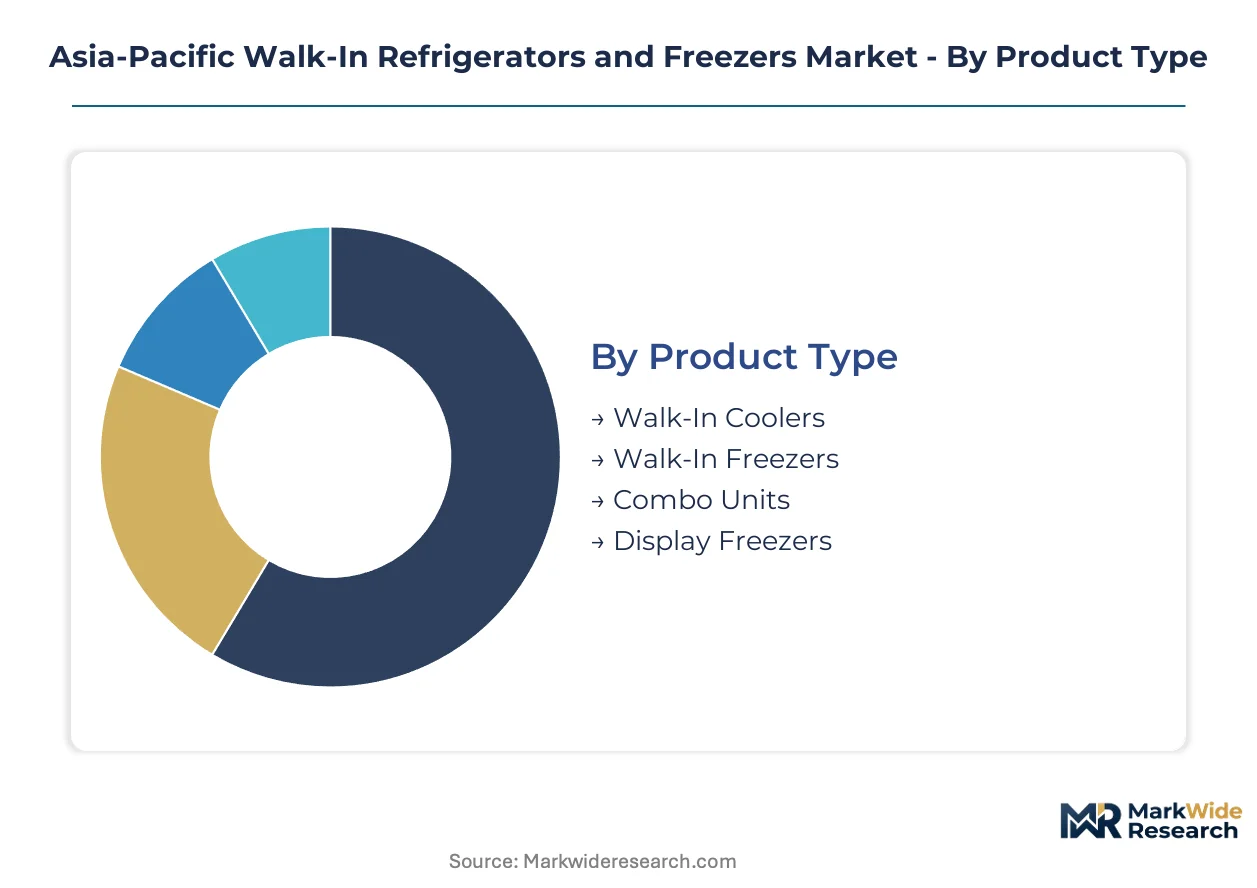
Walk-in refrigeration equipment procurement in the Asia-Pacific region fragments across four distinct dimensions. Each category reflects divergent margin structures, technical requirements, and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Margin pools concentrate in combo units and solar-powered configurations where technology premiums offset commodity panel costs.
- Walk-In Coolers:These units maintain temperatures between 0°C and 10°C using standard vapor compression cycles with polyurethane-insulated panels. India's retail grocery chains and Australia's supermarket expansions drive volume, though energy efficiency mandates from India's BEE compress pricing power.
- Walk-In Freezers:Engineered for sustained operation at -18°C to -40°C with enhanced vapor compression capacity and thicker insulation cores. Vietnam's Mekong Delta seafood processors dominate demand as EU EFSA certification requirements tighten cold-chain documentation.
- Combo Units:Dual-temperature enclosures with partitioned compartments serving hotels and food processors seeking footprint consolidation.
- Display Freezers:Glass-fronted configurations for retail merchandising with integrated lighting and defrost systems.
The dominant share belongs to Walk-In Coolers, while Walk-In Freezers is closing the gap fastest.
End User:
Application intensity varies sharply across customer types, with food processors commanding the highest specification standards.
- Food Processing Units:Industrial-scale facilities requiring continuous batch holding with redundant compressor arrangements and automated temperature logging. India's FSSAI traceability mandates and Vietnam's pharmaceutical cold-chain rules force equipment upgrades ahead of compliance deadlines.
- Restaurants:Quick-service chains and cloud kitchen networks in Bangkok and Jakarta prioritize rapid-install modular systems with IoT monitoring.
- Retail Stores:Supermarket operators in Australia and India's organized retail sector specifying energy-star-rated equipment under BEE and local efficiency programs.
- Hotels:Hospitality procurement favoring combo units for flexible banquet and kitchen operations.
Food Processing Units capture the steepest expansion trajectory, while Restaurants maintain the largest installed base.
Installation Type:
Supply chain configuration determines cost tiers, with pre-fabricated units offering standardization against custom engineering premiums.
- Modular Systems:Pre-engineered panel kits with standardized connection protocols enabling rapid deployment across cloud-kitchen networks. Aggregator platforms in India's Bengaluru-Mumbai-Delhi corridor negotiate fleet-scale procurement with unified maintenance contracts.
- Custom Solutions:Site-engineered enclosures for irregular footprints in converted urban basements and heritage hotel structures.
- Pre-Fabricated Units:Factory-assembled cold rooms minimizing on-site labor for rural agricultural mandis.
- On-Site Installation:Traditional build-out methods for large-scale industrial facilities with specialized loading dock configurations.
Modular Systems is gaining share fastest, though On-Site Installation retains dominance in industrial applications.
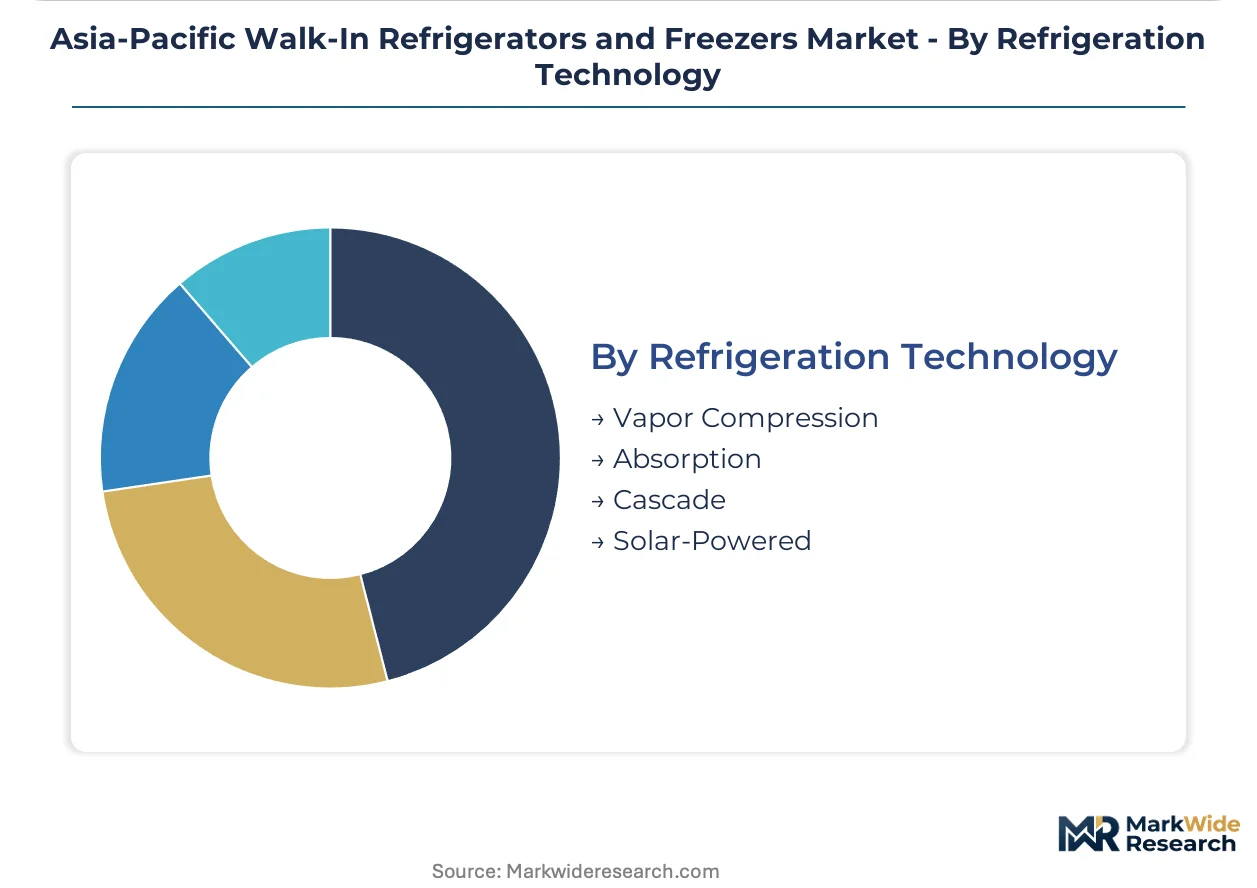
Refrigeration Technology:
Technology selection increasingly hinges on refrigerant compliance timelines rather than pure thermodynamic efficiency.
- Solar-Powered:Photovoltaic-driven units with battery storage eliminating grid dependency for off-grid fishing cooperatives in Indonesia and rural Indian mandis. India's agricultural electrification gaps and archipelago logistics constraints accelerate deployment.
- Vapor Compression:Conventional mechanical refrigeration dominating installed base with scroll and semi-hermetic compressor technologies.
- Cascade:Dual-refrigerant systems for ultra-low temperature pharmaceutical storage.
- Absorption:Heat-activated cooling for facilities with waste heat recovery potential.
Vapor Compression holds the dominant position, while Solar-Powered configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore anchors cold-chain throughput for Southeast Asian pharmaceutical distribution, while Australia's East Coast rail intermodal links connect Melbourne-Brisbane refrigerated logistics corridors to Asia-Pacific shipping lanes.
India
Food processing corridors in Gujarat and Maharashtra drive walk-in cooler installations as FSSAI traceability mandates tighten. India's Bureau of Energy Efficiency star-rating requirements compress pricing power for standard equipment. The Bengaluru-Mumbai-Delhi triangle concentrates cloud-kitchen procurement authority under aggregator platforms negotiating fleet-scale maintenance contracts.
Japan
Pharmaceutical cold-chain integrity requirements and convenience store network expansion sustain premium equipment demand. METI's Top Runner program enforces hydrofluorocarbon phase-out timelines through efficiency rebates. Tokyo-Osaka logistics corridors prioritize early refrigerant transition to lock in compliance certainty.
Australia
Supermarket retail expansion and hydrofluorocarbon import quotas under Kigali Amendment commitments reshape procurement specifications. The Department of Climate Change, Energy, the Environment and Water administers ratcheting allowable volumes through 2036. Melbourne and Brisbane cold-storage operators accelerate full-system replacement toward natural refrigerant platforms.
Vietnam
Seafood export processing in the Mekong Delta propels blast-freezer capacity expansion to meet EU EFSA sanitary certification. The country's drug administration imposes temperature-logging documentation requirements for pharmaceutical distribution. Ho Chi Minh City logistics hubs integrate connected, audit-ready refrigeration systems ahead of compliance deadlines.
Indonesia
Archipelago logistics constraints and grid reliability gaps in fishing cooperatives accelerate off-grid solar cold storage deployment. Rural agricultural mandis deploy photovoltaic-powered walk-in units where grid extension remains uneconomical. Jakarta cloud-kitchen networks specify plug-and-play modular systems with pre-integrated temperature-monitoring telemetry.
Asia-Pacific Walk-In Refrigerators and Freezers Market Competitive Environment
Concentration sits with diversified industrial conglomerates possessing captive compressor manufacturing and inverter-control capabilities. The vendor base spans three distinct tiers: integrated refrigeration specialists with end-to-end panel-to-control production, modular system integrators sourcing standardized components, and regional fabricators serving price-sensitive replacement demand. Equipment specification increasingly hinges on total-cost-of-ownership metrics and energy-performance contracting rather than upfront capital expenditure. Competitive moves center on refrigerant transition readiness and IoT-enabled predictive maintenance service bundling.
Within the integrated conglomerate tier, Daikin Industries and Panasonic Corporation exemplify archetypes combining vapor compression system dominance with captive manufacturing control over critical subsystems. Hussmann Corporation anchors premium installation positioning through compressor technology leadership. These three entities represent contrasting strategic postures: Japanese-based diversified industrials with inverter-driven scroll manufacturing integration, and North American-origin specialists leveraging equipment specification authority in retail grocery expansion.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Daikin Industries |
| Panasonic Corporation |
| Fujimak Corporation |
| Hoshizaki Corporation |
| Fukushima Industries Corporation |
| Frigoglass S.A.I |
| AB Electrolux |
| Haier Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-one-hundred-twenty-day panel procurement lead times concentrate pricing power with polyurethane insulation fabricators serving India's food processing corridors, while compressor inventory buffers in Chinese manufacturing zones buffer Southeast Asian integrators against customs-delay surcharges. This lead-time asymmetry stratifies equipment procurement into three distinct cost tiers based on refrigerant platform complexity and IoT integration depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates natural refrigerant platforms with predictive maintenance bundles from conventional hydrofluorocarbon systems and basic electromechanical configurations. Price differentiation rests on BEE star-rating certification tiers and after-sales service bundling rather than raw panel capacity. Cost compression in economy-tier vapor compression equipment is intensifying because Indian food processors face Bureau of Energy Efficiency compliance mandates without budget elasticity for connected systems. Cloud-kitchen networks in Jakarta and Bangkok exhibit lowest price sensitivity due to aggregator-negotiated fleet contracts, while rural agricultural mandis in Indonesia remain most price-constrained.
Supply Chain Analysis
China anchors scroll and semi-hermetic compressor assembly, while Japan and South Korea dominate inverter-control electronics and precision refrigeration components. Raw material dependencies draw from isocyanate and blowing-agent feedstocks tethered to crude-oil derivatives, plus copper tubing for vapor compression circuits. Single-source vulnerability concentrates in Chinese compressor manufacturing zones exposed to shipping-cost volatility and customs processing delays. Distribution runs through regional integrators in Ho Chi Minh City, Bengaluru, and Sydney who combine panel fabrication with on-site commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
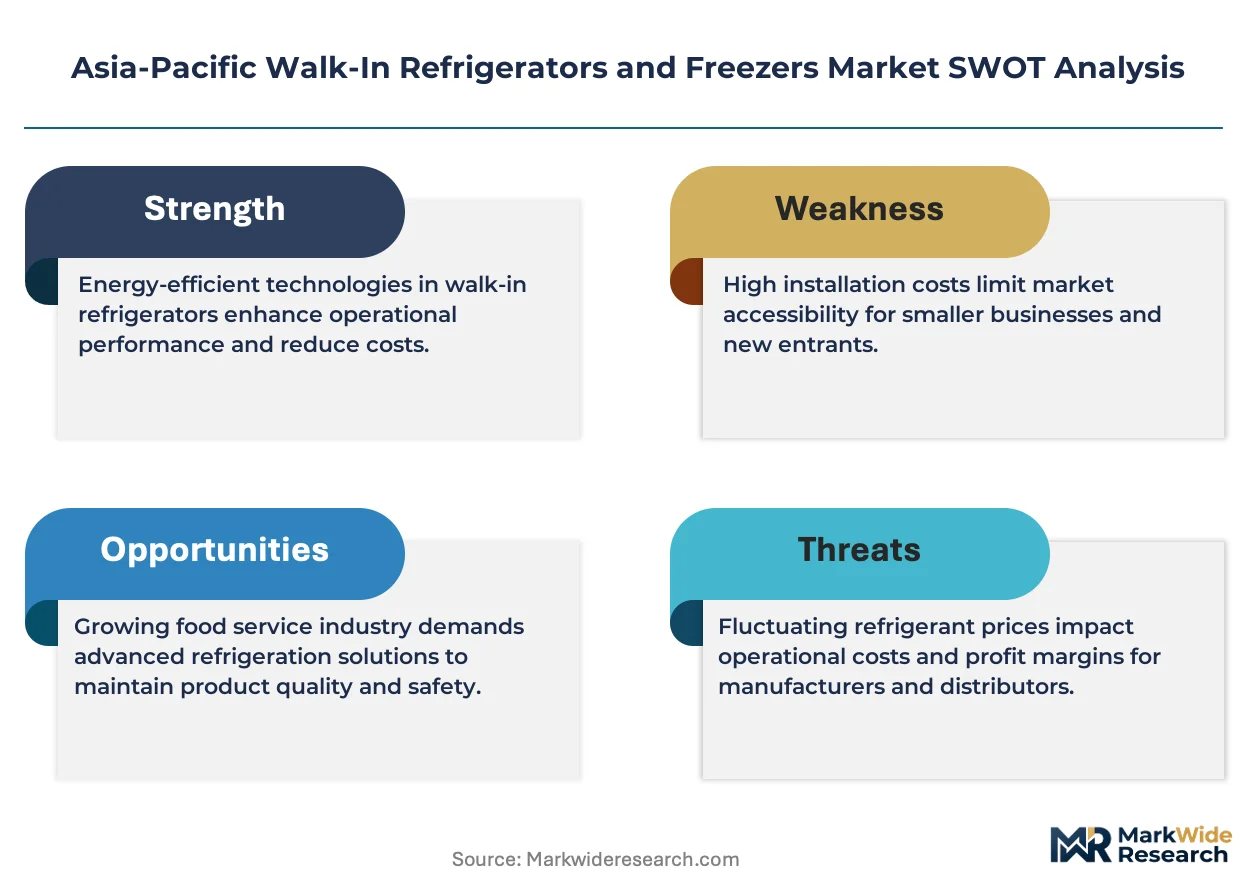
Asia-Pacific walk-in refrigeration sits in early-cycle expansion as pharmaceutical cold-chain mandates across Southeast Asia force warehouse operators toward connected, audit-ready systems ahead of compliance deadlines.
For Market Incumbents: Fortify captive compressor manufacturing positions through backward integration into inverter-driven scroll production, insulating margin structures from Chinese supply concentration risks. Deepen service bundling around predictive maintenance telemetry to lock in cloud-kitchen network contracts against modular system integrators. Priority investment targets ammonia and CO₂ certification pathways for technician training, addressing natural refrigerant scarcity before regulatory deadlines tighten. For New Entrants and Emerging Players: Lead with off-grid solar cold storage configurations targeting Indonesian fishing cooperatives and rural Indian mandis where grid extension economics fail. Penetration concentrates in photovoltaic-powered walk-in units with battery storage integration, bypassing incumbent distribution through direct agricultural cooperative sales channels. Specification authority aggregates at regional cloud-kitchen headquarters, favoring standardized modular kits with unified IoT dashboards over custom-engineered solutions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates spinning non-core refrigeration divisions lacking natural refrigerant transition readiness. Long-term viability frames around total-cost-of-ownership service bundling rather than equipment-only revenue streams. Signal to monitor: BIS and JIS fire-resistance certification bottlenecks extending procurement lead times for hospital and hotel projects, indicating panel insulation material scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Transition | Locks in compliance certainty under Australia's Kigali Amendment hydrofluorocarbon import quotas. |
| IoT-Enabled Predictive Maintenance Bundling | Captures cloud-kitchen fleet-scale contracts through unified temperature-monitoring telemetry dashboards. |
| Off-Grid Solar Cold Storage Deployment | Addresses archipelago logistics constraints and rural Indian grid reliability gaps with photovoltaic independence. |
| Technician Certification Pathway Investment | Resolves ammonia and CO₂ servicing scarcity across Southeast Asian vocational institutes before METI deadlines. |
| Modular Panel Kit Standardization | Reduces commissioning time for Bangkok and Jakarta quick-service restaurant network expansion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with cold-chain logistics directors, food processing plant engineers, commercial refrigeration procurement managers, and aftermarket service technicians. Secondary validation drew from India's BEE star-rating databases, Australia's Department of Climate Change equipment import records, Vietnam's drug administration cold-chain compliance filings, and Japan's METI Top Runner program disclosures. Bottom-up equipment shipment analysis triangulated against top-down cold-storage capacity expansion tracking across the Asia-Pacific region.
Across the analysis window, the forecasting framework modeled product type segmentation by temperature range and refrigerant platform, end-user intensity by traceability compliance burden, installation type by supply chain configuration, and refrigeration technology by grid dependency profile. CAGRs were derived from equipment replacement cycle analysis and regulatory deadline clustering. Industry-specific inputs included pharmaceutical distribution mandate timelines under CDSCO and Vietnam drug administration rules, plus solar irradiance mapping for off-grid deployment feasibility.
The analysis sits within stated boundaries; outcomes outside sustained natural refrigerant transition investment or accelerated fire-safety certification timelines would require recalibration. Forecasts reflect assumptions around polyurethane panel feedstock stability and compressor supply chain normalization. Recalibration cycles align with material shifts in Kigali Amendment quota implementation and BEE efficiency mandate enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Bread Processing Equipment Market