
 Wi-Fi SD Cards Market | 2026-2036
Wi-Fi SD Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi SD Cards Market Analytics
Professional photography workflows is restructuring demand for Wi-Fi SD cards as studios and freelancers abandon tethered shooting for wireless studio setups. Toshiba Corporation leverages its semiconductor heritage to sustain NAND flash supply advantages across Asian manufacturing corridors. Transcend Information anchors its position through ruggedized product lines targeting outdoor videographers in extreme climates. Kingston Technology dominates retail channel distribution through deep partnerships with consumer electronics superstores across North America.
Wi-Fi SD cards combine flash memory storage with embedded IEEE 802.11 wireless transceivers, enabling direct peer-to-peer or networked file transfers without removing the card from the host device. SDXC variants with 128GB capacity lead commercial adoption among wedding and event photographers managing RAW burst sequences, while Wi-Fi Direct connectivity outpaces Infrastructure mode for field shoots lacking reliable router access. Content Creators represent the fastest-expanding target market as solo operators demand instant social media publishing without laptop intermediaries.
FCC Part 15 certification governs radio frequency emissions for Wi-Fi SD cards sold in the United States, while CE marking under the EU Radio Equipment Directive mandates European market access. Japan's MIC radio law and GB standards administered by MIIT shape compliance requirements in Asia's largest consumer electronics clusters. Stakeholders must monitor whether camera manufacturers embed native Wi-Fi transfer deeply enough to displace aftermarket card solutions entirely.
Market Dynamics
Camera manufacturers embedding native wireless transfer capabilities directly into mirrorless bodies are compressing aftermarket card demand as photographers bypass external solutions entirely.
Growth Catalysts
- Social media publishing velocity:Content creators in wedding and event photography require instant RAW file offload to cloud workflows without laptop intermediaries.
- FCC Part 15 certification streamlining:US radio frequency compliance frameworks for unlicensed 802.11 transmission reduce time-to-market for new card variants.
- SDXC capacity expansion:128GB and 256GB flash densities accommodate burst-sequence RAW capture demands from sports photographers.
Market Restraints
- NAND flash supply concentration:Memory wafer fabrication clusters in Taiwan and South Korea create vulnerability to geopolitical disruption.
- Camera-native Wi-Fi maturation:Sony, Canon, and Nikon flagship bodies now ship with built-in wireless transfer, eliminating card dependency.
- EU Radio Equipment Directive compliance costs:CE marking mandates for 2.4GHz and 5GHz bands impose testing burdens on smaller manufacturers.
Strategic Opportunities
- India content creator economy:YouTube and Instagram influencer growth in Mumbai and Bangalore drives demand for affordable wireless storage solutions.
- Drone photography integration:DJI and Autel aerial platforms lack expandable storage, creating aftermarket card attachment potential.
- Japan MIC radio law harmonization:Simplified certification reciprocity with FCC Part 15 accelerates cross-border product launches.
Industry Challenges
- Firmware synchronization complexity:Card manufacturers must maintain compatibility matrices across Canon, Nikon, Sony, and Fujifilm camera OS versions.
- Heat dissipation engineering:Sustained 4K video write cycles combined with active Wi-Fi transmission thermally throttle card performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi SD Cards Market |
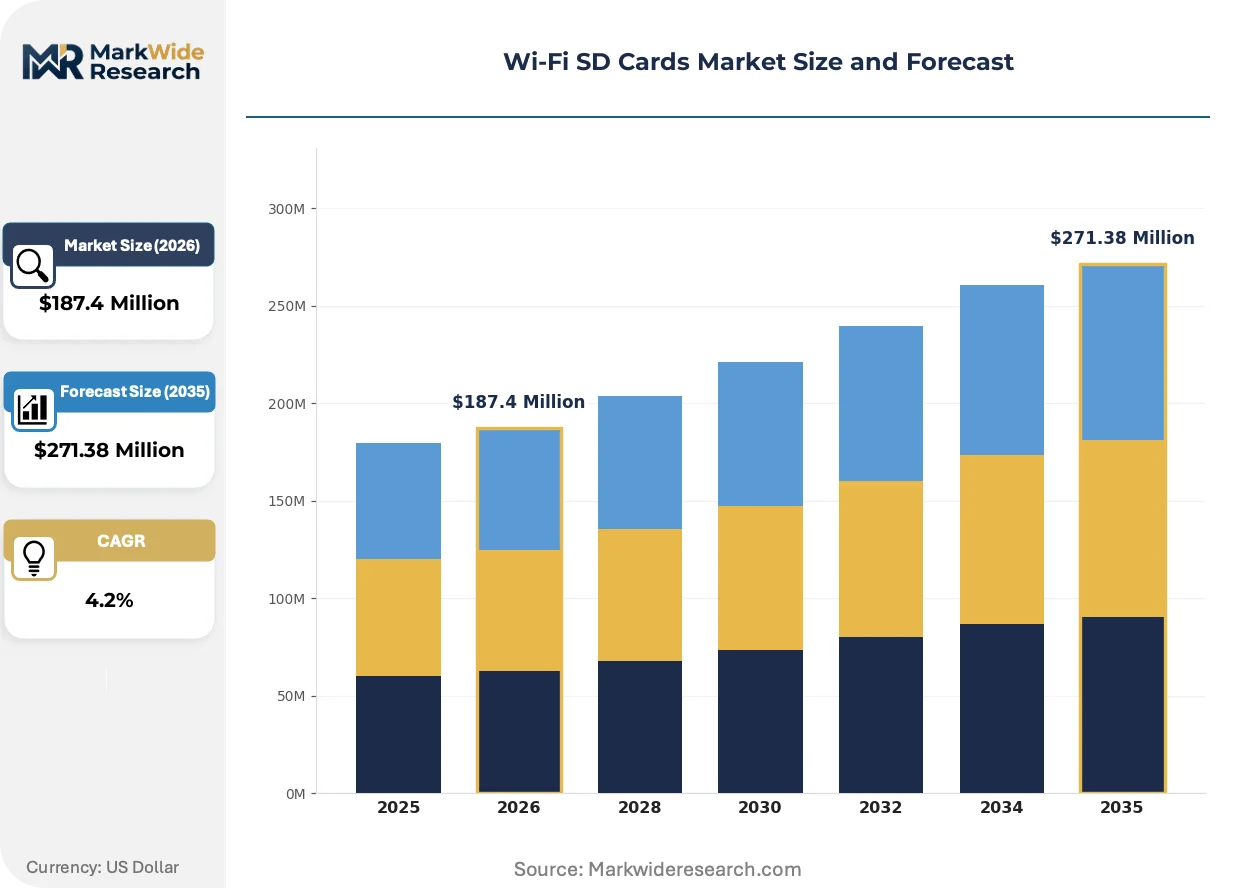
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard SD, SDHC, SDXC, miniSD Capacity: 16GB, 32GB, 64GB, 128GB Connectivity Type: Wi-Fi Direct, Ad-hoc, Infrastructure, Hotspot Target Market: Photographers, Videographers, Content Creators, Enthusiasts |
| Companies Covered | Toshiba Corporation, Transcend Information, Inc., Canon Inc., PQI, Delkin Devices, Inc., ADATA Technology Co., Ltd., Kingston Technology Company, Inc., Hoodman Corporation, NextoDI Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi SD Cards Market Evolving Landscape
Wireless storage architectures are pivoting from passive data containers to active workflow nodes, with embedded processing capabilities reshaping how photographers manage field production.
Embedded IEEE 802.11ac transceivers are automating file transfer orchestration between camera bodies and tablet-based editing stations. Wedding photographers in California and Texas deploy these setups to deliver same-day highlight reels without returning to studio infrastructure. The technology is automating client delivery timelines that previously required overnight post-production cycles.
Japan's Ministry of Internal Affairs and Communications revised MIC radio law enforcement notices in 2023, tightening spurious emission limits for 5.2GHz band devices. Card manufacturers now redesign RF shielding architectures to satisfy both Japanese and EU concurrent compliance. Professional-grade product lines absorb disproportionate certification costs, forcing economy-tier competitors toward single-market strategies.
Field procurement patterns among freelance videographers now favor direct-to-manufacturer bulk purchasing over retail channel dependency. Amazon and B&H Photo serve as fulfillment backbones, but volume buyers negotiate annual supply agreements with Transcend and Kingston distribution arms. This channel compression is most visible in the southwestern United States, where production companies serving Netflix and HBO documentary units standardize on ruggedized 128GB Wi-Fi SD configurations.
Wi-Fi SD Cards Market Segmentation
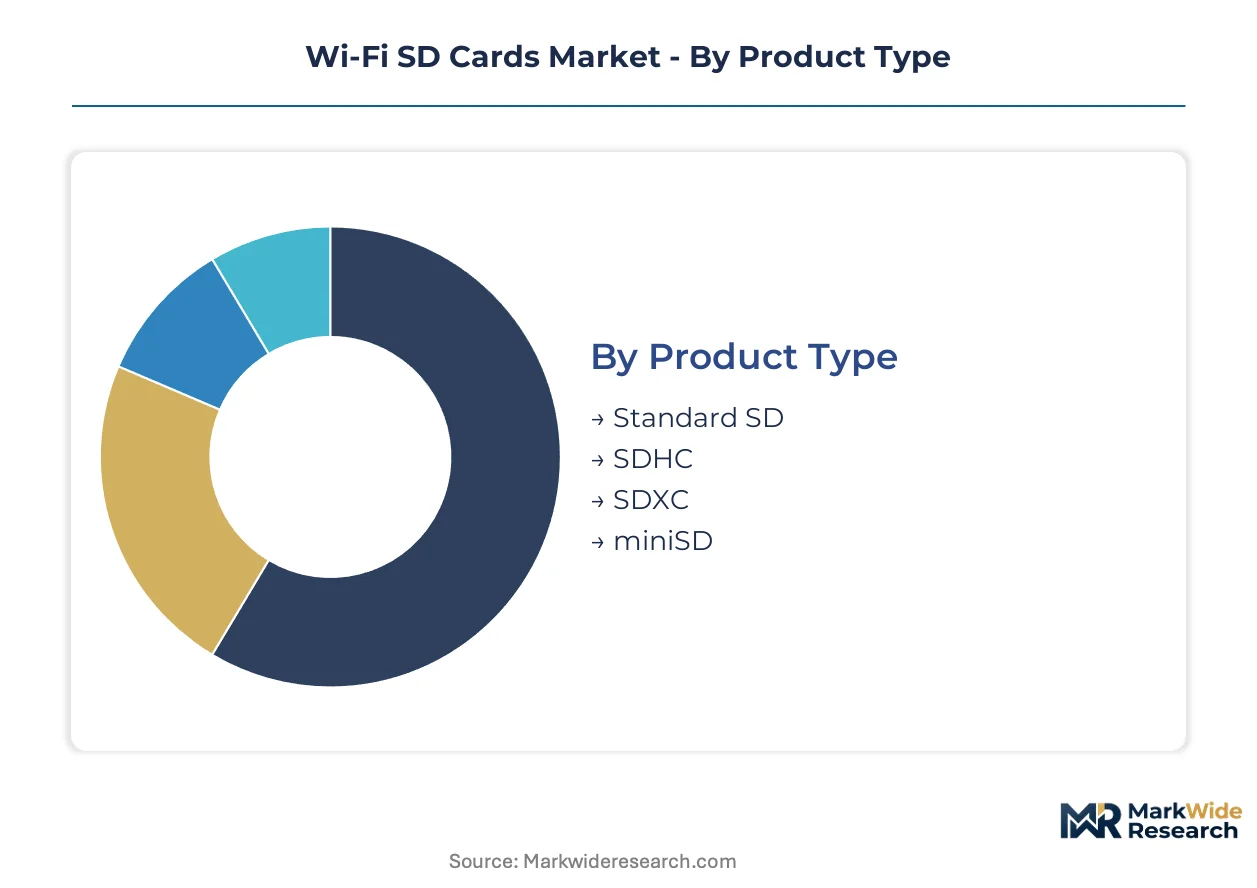
Wi-Fi SD card purchasing patterns diverge sharply across technical specifications and professional use cases. Supply chain configuration for NAND flash wafers directly shapes which product variants achieve commercial scale versus niche positioning.
Product Type:
Memory controller fabrication concentrates in Taiwan and South Korea, dictating which form factors achieve production economies.
- SDXC:Exceeds 32GB storage through exFAT file system architecture. Wedding photographers in California and Texas standardize on this format for RAW burst sequences demanding 128GB densities.
- SDHC:High-capacity designation spanning 4GB to 32GB with FAT32 formatting. Freelance event photographers in Mumbai and Bangalore favor this tier for cost-sensitive social media workflows.
- Standard SD:Legacy 2GB maximum capacity retains presence in industrial IoT sensor applications requiring minimal footprint.
- miniSD:Reduced physical dimensions serve compact drone camera modules where space constraints override capacity demands.
SDXC absorbs the bulk of installed capacity; miniSD is expanding most quickly through aerial photography integration.
Capacity:
Wafer yield economics from Samsung and SK Hynix fabs determine which density tiers reach price-competitive retail positioning.
- 128GB:Triple-level cell NAND stacking enables sustained 4K video write cycles. Netflix documentary production units in the southwestern United States negotiate annual supply agreements for ruggedized configurations.
- 64GB:Multi-level cell architecture balances unit cost against burst-sequence buffer depth. Sports photographers covering NCAA and professional leagues deploy this density for mid-length assignments.
- 32GB:Entry-level professional tier serves portrait studios managing controlled lighting environments without extended sequence demands.
- 16GB:Economy positioning targets hobbyist enthusiasts and secondary backup redundancy rather than primary capture workflows.
128GB dominates revenue contribution; 64GB climbs the fastest as sports photography workflows professionalize.
Connectivity Type:
Radio frequency certification costs under FCC Part 15 and Japan's MIC radio law fragment which connection modes achieve multi-market distribution.
- Wi-Fi Direct:Peer-to-peer protocol eliminates router dependency for field shoots. Outdoor videographers in extreme climates rely on this mode where infrastructure access remains unreliable.
- Infrastructure:Station-based 802.11 integration enables studio tethering to centralized NAS arrays. Fixed production environments in London and Paris broadcasting facilities standardize on this architecture.
- Ad-hoc:Device-to-device mesh networking serves multi-camera synchronization scenarios without external network hardware.
- Hotspot:Embedded access point functionality allows direct tablet or smartphone connection for immediate social media publishing.
Wi-Fi Direct commands the largest deployment base; Hotspot mode gains share fastest among solo content creators.
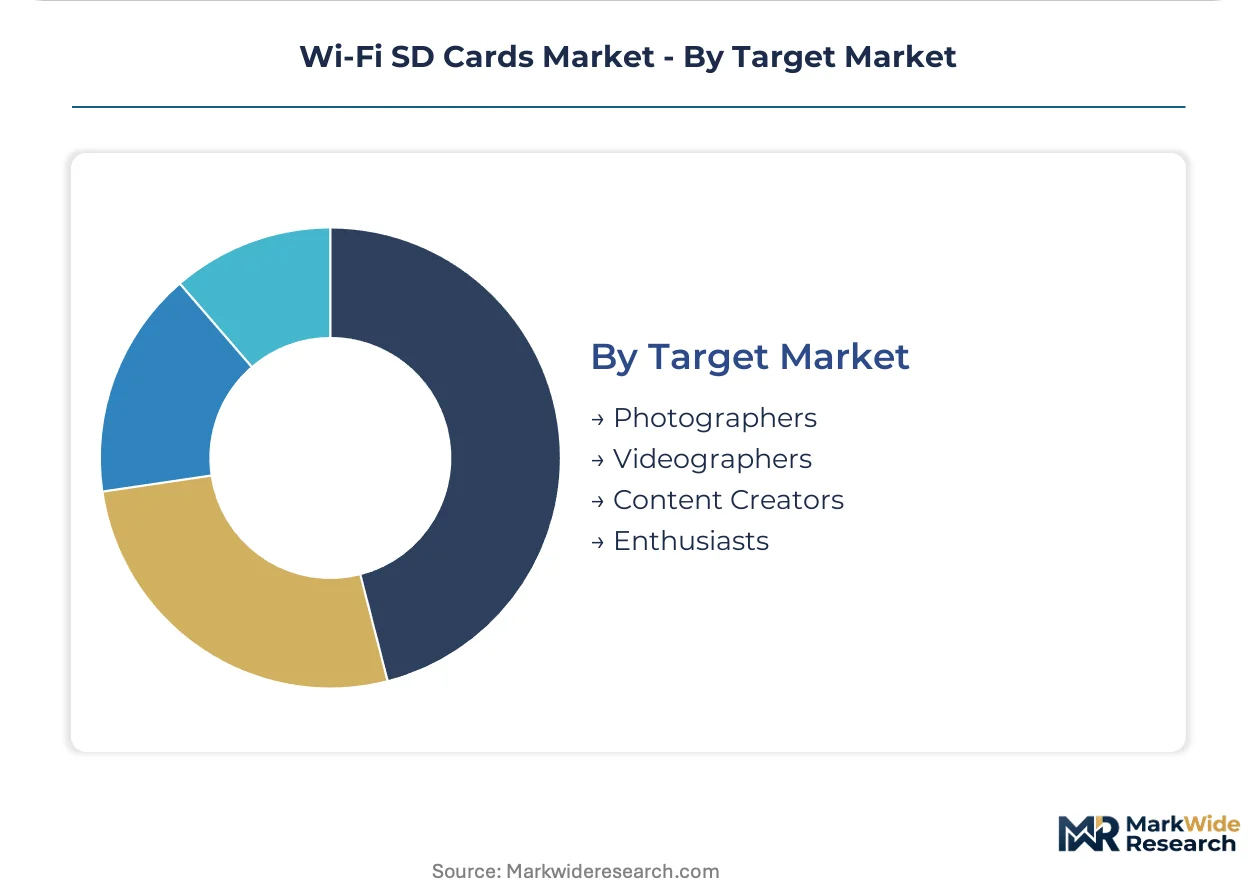
Target Market:
Procurement authority concentration distinguishes enterprise-scale production companies from individual operator purchasing patterns.
- Content Creators:Solo operators monetizing YouTube and Instagram channels demand instant publishing without laptop intermediaries. Influencer economy growth in Indian metropolitan clusters drives volume expansion.
- Photographers:Wedding and event specialists prioritize same-day client delivery timelines. Same-day highlight reel workflows in California and Texas absorb premium-tier product lines.
- Videographers:Documentary and commercial production units require sustained write performance for 4K acquisition. Netflix and HBO supplier networks standardize on ruggedized configurations.
- Enthusiasts:Hobbyist segment exhibits price elasticity and retail channel dependency through Amazon and B&H Photo fulfillment.
Photographers represent the largest revenue pool; Content Creators trace the steepest expansion trajectory through social media monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Taiwan and South Korea contrasts with consumption clusters in Japan, the United States, and Western Europe. NAND flash fabrication dominates Asian supply corridors while professional photography demand concentrates in North American and Japanese metropolitan markets. Regulatory fragmentation across FCC Part 15, Japan's MIC radio law, and EU CE marking requirements shapes cross-border product availability.
United States
Wedding photographers in California and Texas drive premium-tier procurement for same-day highlight reel workflows. FCC Part 15 certification governs unlicensed 2.4GHz and 5GHz transmission for retail distribution. Production companies serving Netflix and HBO documentary units in the southwestern United States negotiate annual supply agreements for ruggedized configurations.
Japan
Camera OEMs embed Wi-Fi SD compatibility into flagship mirrorless systems, sustaining aftermarket card demand alongside native wireless maturation. The Ministry of Internal Affairs and Communications revised MIC radio law enforcement notices in 2023, tightening 5.2GHz spurious emission limits. Tokyo and Osaka metropolitan clusters concentrate professional videographer procurement authority.
Germany
Broadcasting facilities in Berlin and Munich standardize on Infrastructure-mode connectivity for studio tethering to centralized NAS arrays. CE marking under the EU Radio Equipment Directive mandates 2.4GHz and 5GHz band compliance testing. Industrial IoT sensor applications in Bavaria retain legacy Standard SD demand for minimal footprint deployments.
South Korea
SK Hynix fabs in Icheon and Cheongju supply NAND flash wafers determining global capacity tier pricing. The country's national telecommunications regulator enforces radio equipment certification parallel to FCC frameworks. Seoul-based electronics distributors channel Wi-Fi SD inventory across Asia-Pacific content creator markets.
India
YouTube and Instagram influencer growth in Mumbai and Bangalore accelerates demand for affordable wireless storage solutions. The Bureau of Indian Standards administers electronics safety certification alongside import duty structures. Freelance event photographers in metropolitan clusters favor SDHC-tier products for cost-sensitive social media workflows.
Wi-Fi SD Cards Market Competitive Landscape
Top-tier vendors anchor semiconductor-heritage supply advantages, while mid-tier specialists compete on ruggedized product differentiation and retail channel depth. The market exhibits tiered concentration with memory fabricators, consumer electronics conglomerates, and photography-accessory specialists occupying distinct competitive positions. Strategic archetypes include NAND-integrated manufacturers, ruggedization-focused outdoor specialists, and retail-distribution dominators. Capacity expansion in Asian flash fabrication and certification harmonization across regulatory jurisdictions constitute dominant competitive moves.
Within the semiconductor-heritage tier, Toshiba Corporation leverages captive NAND supply from Japanese and Asian manufacturing corridors. Transcend Information occupies a position exemplifying ruggedization-focused specialization for extreme-climate deployments. Kingston Technology anchors retail channel distribution through consumer electronics superstore partnerships across North American markets.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Transcend Information, Inc. |
| Canon Inc. |
| PQI |
| Delkin Devices, Inc. |
| ADATA Technology Co., Ltd. |
| Kingston Technology Company, Inc. |
| Hoodman Corporation |
| NextoDI Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FCC Part 15 and Japan MIC radio law compliance tiers splits pricing power and sourcing strategies across the Wi-Fi SD card landscape. Premium-tier manufacturers absorb disproportionate testing costs for multi-market distribution while economy competitors retreat to single-jurisdiction positioning.
Pricing Analysis
Spot inventory discounts reward bulk procurement from Netflix documentary production units negotiating annual supply agreements, while short lead-time premiums apply to ruggedized configurations for extreme-climate deployments. Three-tier pricing structure across premium, standard, and economy levels reflects NAND flash density, RF shielding grade, and after-sales warranty bundling. Cost compression in the SDHC tier intensifies because Indian content creators drive volume demand for cost-sensitive social media workflows. Freelance event photographers in Mumbai and Bangalore exhibit highest price sensitivity; production companies serving HBO documentary units show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from camera manufacturers embedding native wireless transfer, while Amazon and B&H Photo fulfillment backbones serve retail-dependent enthusiast segments. NAND flash wafer fabrication clusters in Taiwan and South Korea anchor upstream supply, with memory controller production concentrated in Taiwanese foundries. Raw material dependencies include triple-level cell NAND from Samsung and SK Hynix fabs, RF transceiver modules, and specialized thermal interface materials. Single-source vulnerability around Taiwanese memory controller foundries poses structural risk. Distribution runs through Seoul-based electronics distributors channeling inventory across Asia-Pacific content creator markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-native Wi-Fi maturation from Sony, Canon, and Nikon compresses aftermarket card demand, forcing consolidation among peripheral storage specialists lacking semiconductor heritage or ruggedized differentiation.
For Market Incumbents: Deepen captive NAND supply arrangements with SK Hynix or Samsung fabs to defend margin position against memory price volatility. Invest in concurrent FCC Part 15 and Japan MIC radio law certification to maintain multi-market distribution reach against single-jurisdiction competitors. Thermal engineering R&D represents a critical lever as 4K video write cycles combined with active Wi-Fi transmission create performance throttling risks.
For New Entrants and Emerging Players: FCC Part 15 certification streamlining in the United States opens a window for agile specialists targeting drone photography integration where DJI and Autel platforms lack expandable storage. White-space concentration sits with affordable SDHC-tier products for Indian content creator economy growth in Mumbai and Bangalore. Direct-to-manufacturer bulk purchasing relationships with regional production companies offer the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with ruggedization-focused specialists given Netflix and HBO documentary supplier network standardization on extreme-climate configurations. Long-term viability favors manufacturers with backward integration into NAND flash supply or deep channel control through consumer electronics superstore partnerships. Watch for camera OEM announcements embedding native wireless transfer as the inflection indicator for aftermarket card displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Concurrent Multi-Market Certification | Simultaneous FCC Part 15 and Japan MIC compliance accelerates cross-border product launches beyond single-jurisdiction competitors. |
| Thermal Engineering Investment | Heat dissipation R&D addresses sustained 4K video write cycles combined with active Wi-Fi transmission throttling. |
| Drone Platform Integration | Aftermarket card attachment potential expands through DJI and Autel aerial platforms lacking native expandable storage. |
| Direct Bulk Procurement Relationships | Annual supply agreements with Netflix and HBO documentary production units reduce retail channel dependency. |
| India Content Creator Market Entry | YouTube and Instagram influencer growth in Mumbai and Bangalore drives demand for affordable wireless storage solutions. |
Research Methodology
SEC filings from memory fabricators, FCC equipment authorization databases, and Japan MIC radio law enforcement notices formed the secondary backbone for supply-side validation. Primary interviews with wedding photography studio operators, broadcast facility technical directors, electronics procurement managers at camera OEMs, and NAND flash supply chain specialists combined with secondary triangulation. Bottom-up unit economics from product-level bill-of-materials analysis and top-down market sizing from end-use demand aggregation were reconciled across the analysis window.
Historical trendline analysis of SD card format transitions and wireless protocol adoption curves informed the projection framework. Segmentation dimensions modeled include product type, capacity tier, connectivity mode, and target market archetype across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating camera shipment forecasts and native wireless penetration assumptions. Industry-specific inputs included NAND flash wafer yield economics from Samsung and SK Hynix and RF certification cost trajectories under evolving MIC radio law enforcement.
The model assumes a particular technology adoption path; alternative pathways for camera-native Wi-Fi transfer would alter the outlook for aftermarket card demand. Forecasts reflect base-case assumptions around regulatory harmonization and memory supply continuity that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Transparent Cache Market
Data Storage
OTG Pen Drive Market
Data Storage
Storage and Management Market
Data Storage
China Solid-State Drive Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Data Center Ssds Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
APAC SSD Caching Market
Data Storage
Storage Area Network Market
Data Storage
Enterprise Hard Drive Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Zoned Flash Market