
 Storage Area Network Market | 2026-2036
Storage Area Network Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Area Network Market Intelligence
Modular storage arrays with disaggregated compute and capacity is shifting procurement patterns toward mix-and-match configurations. Dell Technologies anchors enterprise data center deployments through extensive channel control. Pure Storage differentiates with all-flash architectures that sustain premium positioning. IBM leverages mainframe integration to dominate financial services accounts.
A Storage Area Network constitutes a dedicated high-speed network interconnecting storage devices to multiple servers, typically employing Fibre Channel, iSCSI, or NVMe over Fabrics protocols with throughput exceeding 32 Gbps to deliver block-level storage access for mission-critical applications. Fibre Channel SAN retains the largest installed base among product types due to proven reliability in enterprise environments, while NVMe over Fabrics represents the fastest-growing technology segment as latency requirements tighten for artificial intelligence and analytics workloads. Cloud SAN adoption accelerates among IT Service Providers seeking elastic capacity without capital-intensive infrastructure.
FCC regulations govern electromagnetic emissions for networking equipment deployed in US facilities, while GDPR and the EU AI Act impose data sovereignty and algorithmic accountability requirements that reshape cross-border storage architectures. BIS certification mandates in India and NMPA standards in China create compliance thresholds for imported SAN hardware. Stakeholders must weigh protocol migration timelines against existing Fibre Channel investments as NVMe over Fabrics matures.
Market Dynamics
NVMe over Fabrics is compressing protocol migration timelines as financial services and cloud providers demand sub-100-microsecond latency for real-time analytics and algorithmic trading workloads.
Growth Catalysts
- Real-time transaction processing mandates:Banking and securities exchanges in the United States and Germany require deterministic storage latency for high-frequency trading platforms.
- GDPR data sovereignty requirements:European enterprises are deploying dedicated SAN infrastructure to maintain resident data control and avoid cross-border transfer penalties.
- Cloud service provider expansion:Hyperscale data center buildouts across India and Brazil are absorbing block storage arrays for multi-tenant infrastructure services.
Market Restraints
- Fibre Channel stranded asset risk:Enterprises with sunk investments in 32 Gbps FC switches face write-down pressure during NVMe over Fabrics transitions.
- Flash memory supply concentration:NAND fabrication capacity concentrates in South Korea and Taiwan, exposing array pricing to geopolitical disruption.
- BIS certification delays:India's mandatory testing protocols extend hardware import timelines by four to six months for non-domestic suppliers.
Strategic Opportunities
- AI training cluster storage:GPU-accelerated workloads in Japan and the United States require petabyte-scale NVMe over Fabrics deployments with parallel file system integration.
- Disaggregated composable infrastructure:Software-defined storage controllers enable independent scaling of compute and capacity resources.
- EU AI Act compliance architectures:Algorithmic accountability requirements create demand for immutable audit logs and provenance-tracking storage systems.
Industry Challenges
- NVMe over Fabrics skill scarcity:Enterprise storage administrators lack RDMA networking and kernel-bypass programming expertise for protocol deployment.
- Hybrid cloud integration complexity:Consistent data services across on-premises SAN and public cloud block storage require API harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Area Network Market |
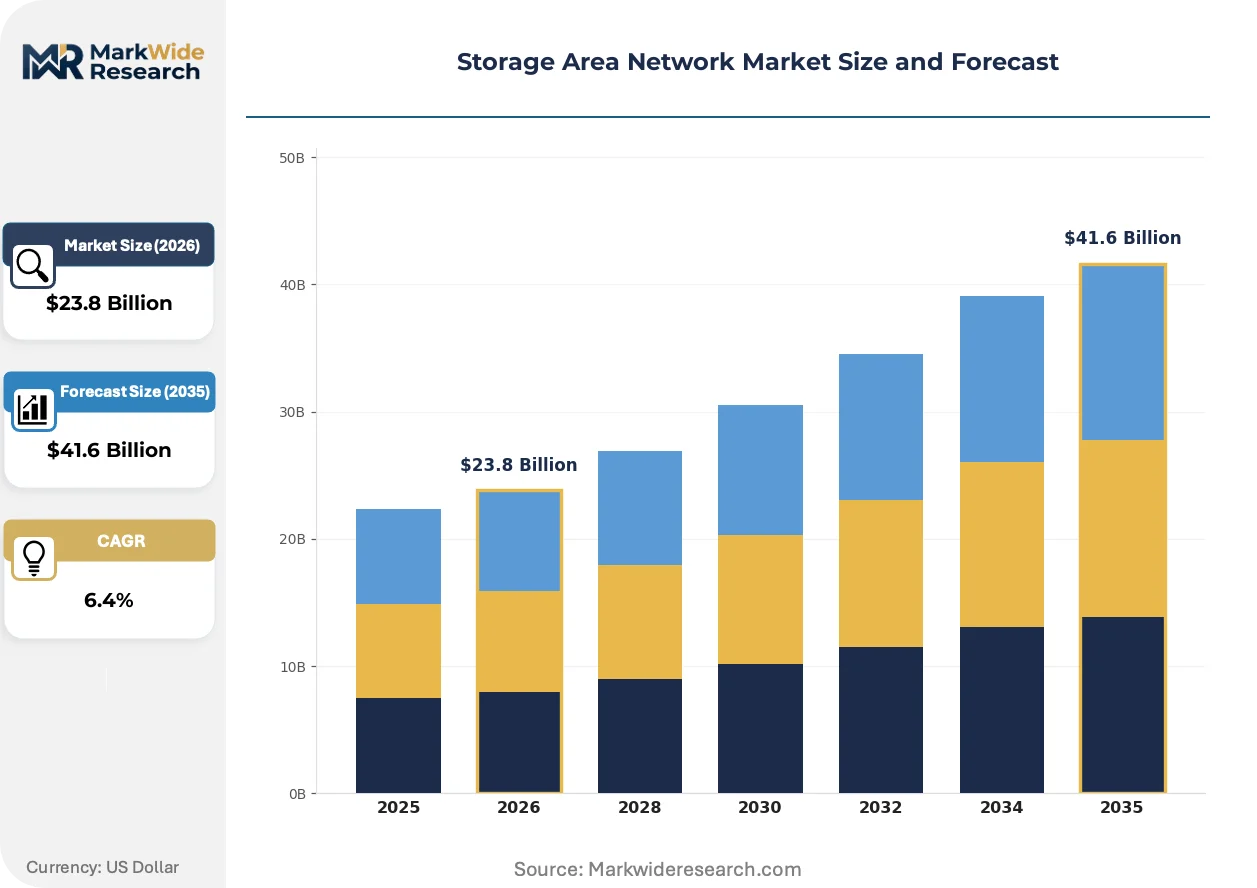
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibre Channel SAN, IP SAN, Hybrid SAN, Virtual SAN, Cloud SAN Technology: Fibre Channel, iSCSI, InfiniBand, Fibre Channel over Ethernet, NVMe over Fabrics Application: Data Centers, Cloud Computing, High-Performance Computing, Backup and Recovery, ERP Systems End User Industry: BFSI Enterprises, IT Service Providers, Telecommunication Firms, Media & Entertainment Studios, Government Agencies |
| Companies Covered | NetApp, Broadcom, Dell Technologies, Pure Storage, Hitachi Vantara, Hewlett Packard Enterprise, Cisco Systems, Oracle, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Area Network Market Strategic Shifts & Innovations
Storage architectures are fragmenting across latency tiers as artificial intelligence, financial trading, and cloud-native applications impose divergent performance requirements on underlying infrastructure.
NVMe over TCP is unifying Ethernet-based storage transport for organizations seeking Fibre Channel alternatives without specialized network hardware. Mid-market enterprises and regional cloud providers are adopting the protocol fastest, driven by existing 25 Gbps and 100 Gbps switch investments. This convergence is collapsing the traditional boundary between IP networks and dedicated storage fabrics, forcing incumbent vendors to dual-protocol support.
GDPR and the EU AI Act are mandating data residency and algorithmic traceability that reshape cross-border storage topologies. Financial institutions must maintain immutable audit trails for model training data, requiring write-once-read-many capabilities within SAN arrays. German and French regulators are inspecting these implementations most aggressively, pressuring vendors to certify compliance-specific firmware configurations.
Consumption-based financing models are displacing capital purchase cycles for enterprise storage procurement. IT service providers and regional banks are leasing capacity with embedded refresh guarantees rather than owning depreciating assets. This shift is most pronounced in the United States and United Kingdom, where operating expense treatment aligns with cloud accounting preferences and reduces balance-sheet hardware exposure.
Storage Area Network Market Segmentation
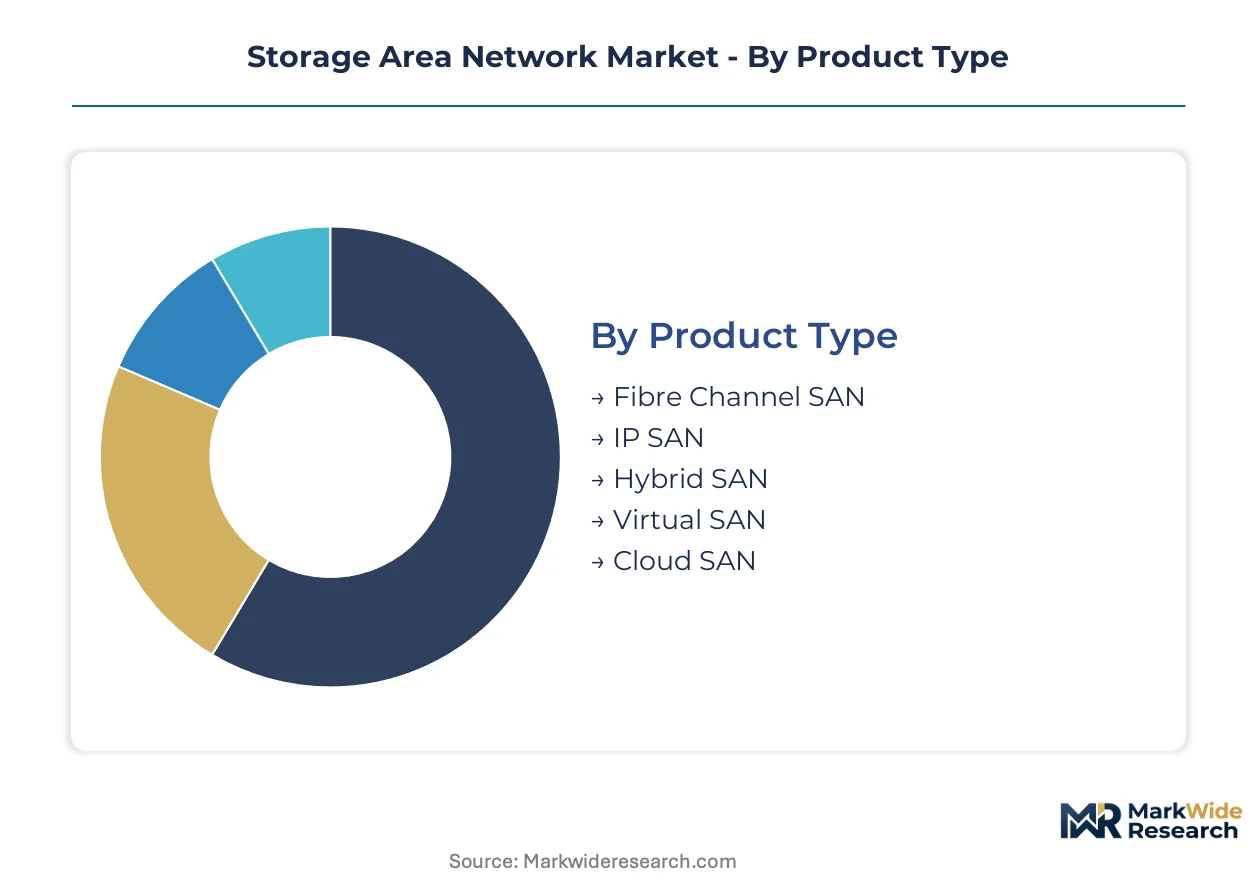
Storage Area Network procurement patterns diverge sharply across protocol maturity, workload latency requirements, and capital deployment models. Understanding segment boundaries reveals where Fibre Channel incumbents defend installed base versus where NVMe over Fabrics challengers displace legacy infrastructure.
Product Type:
Supply concentration in NAND fabrication and switch silicon shapes array availability and pricing tiers across deployment models.
- Fibre Channel SAN:Dedicated Fibre Channel switching fabric delivers deterministic latency with proven enterprise reliability. Financial services enterprises in the United States and Germany maintain this architecture for high-frequency trading platforms despite protocol migration pressure.
- Cloud SAN:Elastic block storage services provisioned via API eliminate capital-intensive infrastructure ownership. IT Service Providers in India and Brazil absorb capacity fastest as hyperscale data center buildouts accelerate.
- IP SAN:iSCSI transport over standard Ethernet reduces specialized network hardware requirements.
- Hybrid SAN:Mixed protocol support bridges Fibre Channel investments with IP-based expansion.
- Virtual SAN:Software-defined storage pools server-direct-attached capacity across hypervisor clusters.
Today's leader: Fibre Channel SAN. Tomorrow's challenger: Cloud SAN.
Technology:
Cost tier stratification separates premium RDMA-based protocols from commodity Ethernet alternatives.
- NVMe over Fabrics:Kernel-bypass networking delivers sub-100-microsecond latency for GPU-accelerated AI training clusters. Japan and United States enterprises deploy petabyte-scale configurations with parallel file system integration.
- Fibre Channel:32 Gbps and 64 Gbps signaling retains dominance in mainframe-attached enterprise storage. IBM leverages channel integration to defend financial services accounts against protocol displacement.
- iSCSI:TCP/IP transport enables block storage across existing network infrastructure without specialized adapters.
- Fibre Channel over Ethernet:Converged network adapter consolidation reduces cabling complexity in dense data centers.
- InfiniBand:Ultra-low latency interconnect dominates high-performance computing environments with RDMA native support.
Established incumbent: Fibre Channel. Steepest expansion trajectory: NVMe over Fabrics.
Application:
Volume concentration in cloud provider procurement reshapes vendor prioritization across workload types.
- Cloud Computing:Multi-tenant block storage services demand elastic scaling and API-driven orchestration. Regional cloud providers in Brazil and India drive consumption-based procurement models.
- Data Centers:Enterprise-owned facilities consolidate heterogeneous workloads on unified storage fabrics. Dell Technologies anchors deployments through extensive channel control.
- High-Performance Computing:Parallel file system integration requires specialized latency optimization.
- Backup and Recovery:Secondary storage tiers prioritize capacity economics over performance.
- ERP Systems:Mission-critical database workloads demand consistent sub-millisecond response times.
Primary volume driver: Data Centers. Fastest share gainer: Cloud Computing.
End User Industry:
Customer type segmentation separates regulated financial infrastructure from elastic cloud service provider demand.
- BFSI Enterprises:Real-time transaction processing mandates deterministic storage latency for algorithmic trading. GDPR data sovereignty requirements drive dedicated SAN deployment in Germany and France.
- IT Service Providers:Multi-tenant infrastructure services absorb block storage via consumption-based financing. United States and United Kingdom providers lead operating-expense procurement shift.
- Telecommunication Firms:5G core network functions generate distributed storage requirements.
- Media & Entertainment Studios:4K/8K content pipelines demand high-throughput sequential access.
- Government Agencies:Classified data handling imposes air-gapped infrastructure requirements.
Revenue anchor: BFSI Enterprises. Fastest-growing demand profile: IT Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise storage networking originated in United States financial data centers during the 1990s Fibre Channel era, then diffused to German manufacturing hubs and Japanese electronics clusters as latency requirements tightened across trading floors and semiconductor fabrication.
United States
Securities exchanges in New York and Chicago drive sub-100-microsecond NVMe over Fabrics procurement for algorithmic trading platforms. FCC emissions standards govern networking hardware deployment across financial data centers. Northern Virginia's hyperscale corridor absorbs cloud SAN capacity fastest as Amazon Web Services and Microsoft Azure expand block storage services.
Germany
Frankfurt's banking cluster maintains deterministic Fibre Channel infrastructure for real-time transaction settlement despite protocol migration pressure. GDPR data sovereignty mandates require resident data control, reshaping cross-border storage architectures for Deutsche Bank and Commerzbank. Bavaria's automotive electronics manufacturers deploy NVMe over Fabrics for autonomous vehicle simulation workloads.
Japan
Tokyo's financial district sustains premium all-flash SAN deployments for high-frequency trading alongside mainframe-integrated storage from IBM and Hitachi. METI industrial policy supports domestic NAND fabrication capacity expansion through subsidy programs. Osaka-Kobe manufacturing belt concentrates demand from precision machinery and robotics sectors requiring deterministic storage latency.
India
BIS certification mandates extend hardware import timelines by four to six months, favoring domestic assembly partnerships for Dell and HPE. Mumbai's banking headquarters and Bangalore's IT services corridor drive consumption-based procurement models. Cloud provider buildouts in Hyderabad and Chennai absorb elastic block storage capacity for multi-tenant infrastructure services.
Brazil
São Paulo's financial services sector anchors Fibre Channel installed base while cloud migration accelerates among regional banks. ANVISA data localization requirements for healthcare records create dedicated SAN demand. Rio de Janeiro's media and entertainment studios deploy high-throughput storage for 4K content pipelines.
Storage Area Network Market Key Industry Players
The competitive structure tilts toward diversified technology conglomerates with extensive channel control. Incumbents defend positions through mainframe integration and enterprise service relationships while challengers penetrate via all-flash architectures and consumption-based financing. Two strategic archetypes dominate: protocol-agnostic platform vendors spanning Fibre Channel to NVMe over Fabrics, and flash-native specialists capturing premium positioning through software-defined differentiation. Consolidation pressure intensifies as cloud service providers internalize storage software and direct-attached alternatives erode traditional SAN attach rates.
Within the diversified platform tier, Dell Technologies and Hewlett Packard Enterprise occupy positions defined by global channel density and service attach rates. Pure Storage exemplifies the flash-native archetype with subscription-based commercial models. IBM represents the mainframe-anchored incumbent defending financial services accounts through z/OS storage integration. NetApp and Hitachi Vantara sit within the hybrid cloud transition category, bridging on-premises SAN with public cloud block storage APIs.
| Leading Market Players |
|---|
| NetApp |
| Broadcom |
| Dell Technologies |
| Pure Storage |
| Hitachi Vantara |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Oracle |
| IBM |
| Others |
Cost & Logistics Intelligence
Kernel-bypass networking expertise concentrated in San Jose and Bangalore engineering clusters widens labor-cost spreads between premium NVMe over Fabrics deployments and commodity iSCSI alternatives, compressing margins on mid-tier Fibre Channel refresh cycles.
Pricing Analysis
Consumption-based financing with embedded refresh guarantees now dominates enterprise procurement, separating hyperscale cloud providers with volume-scale discounts from regional banks absorbing operating-expense premiums. Price differentiation hinges on latency certification tiers and software-defined controller capabilities. Cost compression in mid-market Fibre Channel arrays intensifies as NAND flash supply volatility feeds through component bills. IT service providers exhibit highest price sensitivity; financial services trading platforms demonstrate lowest elasticity due to deterministic latency mandates.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam anchor hub-and-spoke fulfillment patterns for array hardware destined to European and Asia-Pacific data centers. NAND fabrication concentrates in South Korea and Taiwan; switch silicon production centers on the United States and China. Array assembly draws from controller chipsets, high-speed optical transceivers, and enterprise-grade capacitors. Single-source vulnerability in RDMA adapter supply creates bottleneck exposure. Distribution runs through authorized channel partners with certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Storage Area Network market functions as a stable compounder, with data sovereignty mandates from GDPR and the EU AI Act generating recurring infrastructure refresh demand across European financial services.
For Market Incumbents: Acquire NVMe over Fabrics software-defined storage stacks to counter cloud-native challengers eroding Fibre Channel attach rates. Defend mainframe-integrated accounts through z/OS storage certification investments. Channel control in Germany and Japan remains the critical lever against protocol displacement. For New Entrants and Emerging Players: Launch via consumption-based financing models targeting regional cloud providers in Brazil and India lacking capital-intensive procurement capabilities. White-space concentrates in mid-market IP SAN replacements and AI training cluster storage. Lead with API-driven orchestration as the primary go-to-market angle. For Investors and Strategic Acquirers: Cloud service providers are the most active acquirers in this space, internalizing storage software to reduce third-party SAN dependency. Long-term viability rests on protocol-agnostic platform positioning. Target acquisition archetypes include flash-native specialists with subscription revenue bases. Monitor hyperscaler capex disclosure trends as the inflection signal for enterprise demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe over Fabrics Certification | Sub-100-microsecond latency validation opens algorithmic trading accounts at Frankfurt and Chicago exchanges. |
| Backward Integration into NAND Supply | Captive flash sourcing insulates array pricing from geopolitical disruption in South Korean fabrication. |
| Consumption-Based Financing Launch | Operating-expense treatment aligns with cloud accounting preferences among United Kingdom regional banks. |
| GDPR Compliance Firmware Development | Immutable audit log capabilities satisfy EU AI Act algorithmic traceability mandates for Deutsche Bank deployments. |
| Regional Distribution Partnership | BIS certification acceleration through domestic assembly reduces four-to-six-month import delays in India. |
Research Approach
Multiple input streams — storage architect interviews, channel partner surveys, hyperscaler procurement disclosures, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged data center infrastructure directors, SAN administration specialists, financial services IT procurement leads, and cloud provider capacity planners. Secondary validation drew from FCC equipment authorization databases, BIS certification registries, EU AI Act implementation guidance, and NAND supply chain trade data. Bottom-up array shipment modeling and top-down enterprise storage spend analysis were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from storage vendor executives and systems integrator delivery heads. The analytical framework projected value across the analysis window by protocol type, deployment model, workload latency tier, and end-user industry vertical. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs incorporated GPU cluster storage density trends and data sovereignty regulation expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under flash memory supply disruption or accelerated Fibre Channel write-down cycles. Outputs reflect documented assumptions regarding protocol migration timelines and cloud provider self-build rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Portable Storage Device Control Software Market
Data Storage
NOR Flash Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
HDD Head Assembly Market
Data Storage
North America SSD Caching Market
Data Storage
Ceph Storage Solutions Market
Data Storage
South Korea Data Center Storage Market
Data Storage
Enterprise Storage System Market
Data Storage
Flash-Based Array Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Storage Area Network (SAN) Solutions Market