
 Mass Notification System Market | 2026-2036
Mass Notification System Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Notification System Market Intelligence
Campus safety demand is shifting toward unified platforms that merge lockdown triggers with parent and first-responder messaging. Everbridge, Inc. leverages its threat intelligence engine to anchor enterprise and higher-ed contracts across North America. Motorola Solutions, Inc. dominates public-safety-grade voice and data networks, extending its installed base into interoperable alert systems. Johnson Controls competes through building-management integration, embedding notification logic directly into access control and fire panels.
A mass notification system is an integrated communications platform engineered to disseminate time-critical alerts across multiple channels—SMS, email, voice broadcast, mobile push, and outdoor sirens—within seconds of trigger activation, typically supporting 10,000 to 500,000 recipients per event depending on deployment scale. Its primary commercial purpose is to reduce casualty exposure and operational downtime by collapsing information latency during emergencies, natural disasters, or security breaches. Emergency alert deployments occupy the largest installed base due to government mandate density, while mobile app and social media integration segments are expanding fastest as smartphone penetration saturates even remote populations. Enterprise messaging commands premium pricing where SaaS delivery and API-based CRM tie-ins create recurring revenue pools.
The FCC enforces wireless emergency alert technical standards and participation rules for commercial mobile carriers, directly shaping product certification requirements and carrier interoperability testing. EECC mandates in Europe require member states to deploy population-wide alert capabilities by specified deadlines, forcing national procurement cycles and vendor qualification shifts. OSHA workplace emergency action plan standards in the United States drive manufacturing and chemical facility demand for site-specific notification layers. Stakeholders must monitor evolving encryption and data residency requirements as cross-border alert federation becomes technically feasible but legally contested.
Market Dynamics
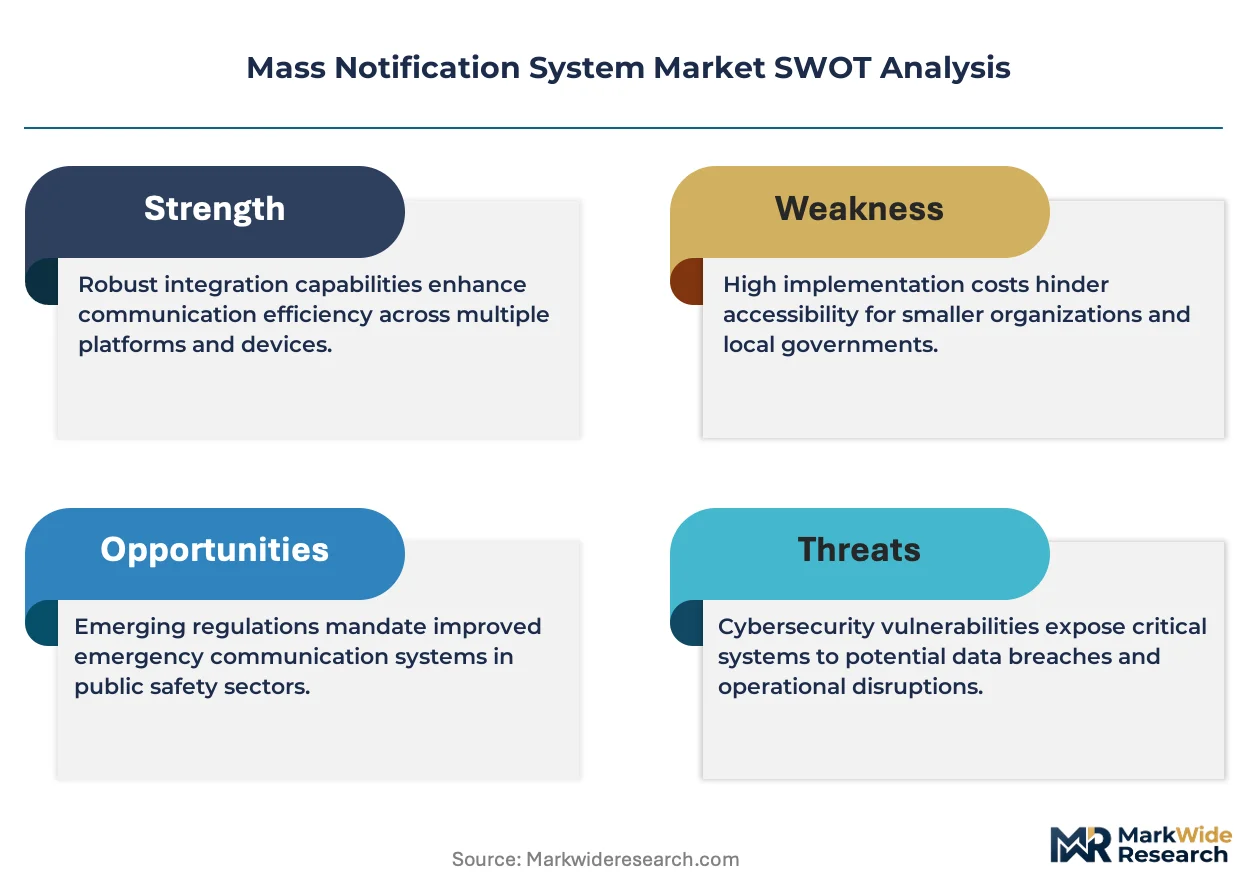
Government mandates for population-wide alerting are compressing procurement cycles and forcing vendor consolidation around multi-channel platforms that satisfy FCC wireless emergency alert rules and Europe's EECC deadlines simultaneously.
Growth Catalysts
- FCC Wireless Emergency Alert mandates:Commercial mobile carriers must maintain technical interoperability with public safety systems, creating baseline demand for certified platform upgrades across US critical infrastructure operators.
- Campus safety integration:Higher education institutions are consolidating lockdown triggers, parent notification, and first-responder dispatch into unified command interfaces, driving replacement of siloed legacy systems.
- Smartphone saturation:Mobile push notification reach now extends to remote populations previously served only by outdoor sirens, expanding addressable recipient pools for emergency managers in rural jurisdictions.
Market Restraints
- Carrier certification bottlenecks:FCC interoperability testing timelines extend vendor qualification periods, delaying revenue recognition for platform providers and freezing smaller competitors from carrier partnerships.
- Data residency fragmentation:Cross-border alert federation faces legal contestation as GDPR, state-level privacy laws, and national security frameworks impose conflicting storage and encryption requirements on cloud-hosted systems.
- Legacy infrastructure lock-in:Municipalities with sunk investment in analog siren networks face steep capital requirements to achieve IP-based integration with modern multi-channel platforms.
Strategic Opportunities
- API-native enterprise messaging:SaaS delivery with CRM tie-ins commands premium recurring revenue in manufacturing and chemical facilities seeking OSHA-compliant site-specific notification layers.
- Building-management convergence:Embedding notification logic directly into fire panels and access control systems creates sticky integration revenue streams for facility automation vendors.
- Japan critical infrastructure budgets:METI-directed spending on resilience infrastructure offers expansion terrain for vendors with proven public-safety-grade voice and data credentials.
Industry Challenges
- Interoperability engineering talent:Scarce expertise in legacy radio-to-IP protocol translation constrains development velocity for vendors pursuing public-safety contracts.
- Multi-jurisdiction deployment complexity:Federal, state, and municipal procurement rules vary across alert system implementations, lengthening sales cycles and inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Notification System Market |
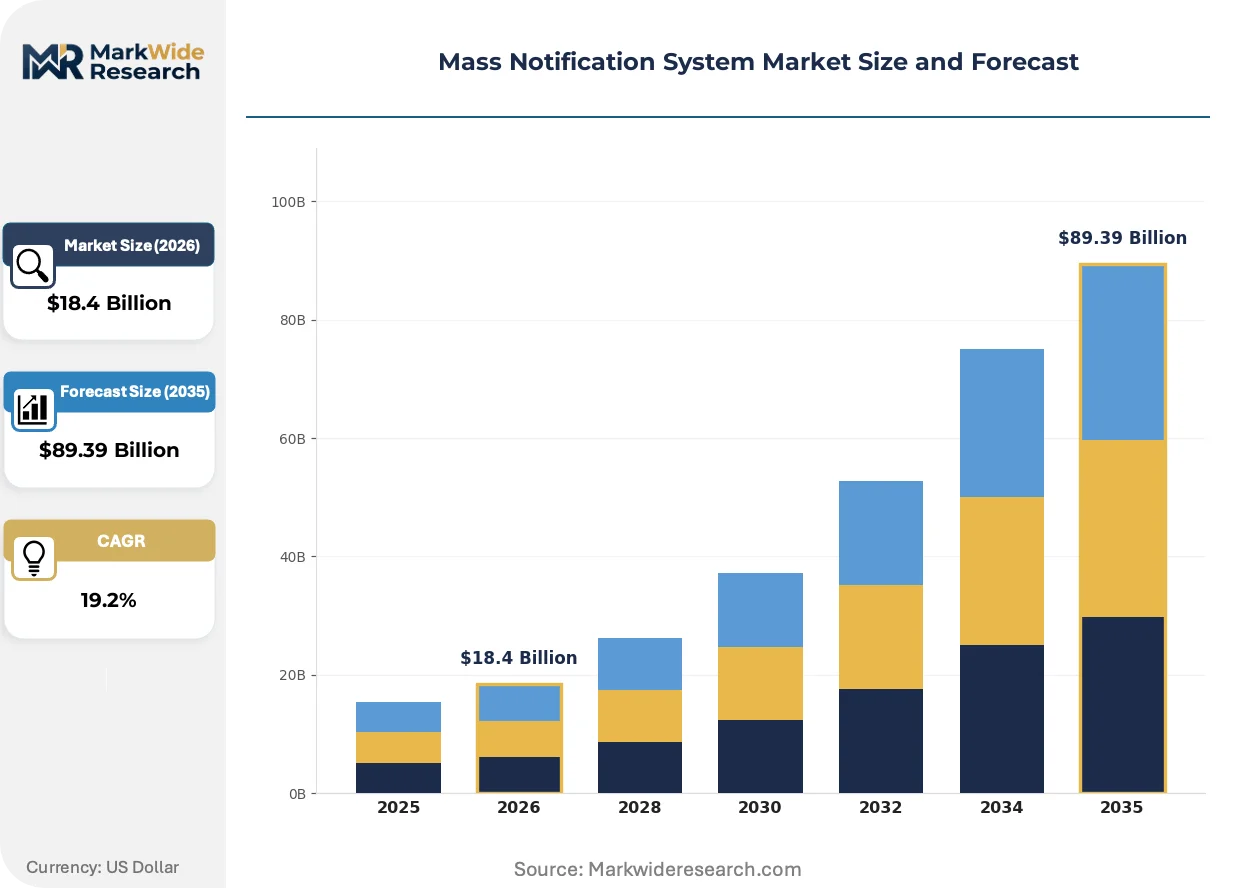
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $89.39 Billion |
| CAGR (2026 – 2036) | 19.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Emergency Alert, Public Warning, Campus Notification, Enterprise Messaging, Community Alert, Incident Communication Technology: SMS, Email, Voice Broadcast, Mobile App, Social Media Integration, Outdoor Sirens Application: Disaster Response, Facility Security, Event Management, Transportation Safety, Utility Outage, Educational Institution Safety End User: Government Agencies, Educational Institutions, Transportation Operators, Utilities Providers, Corporate Enterprises, Nonprofit Organizations |
| Companies Covered | Everbridge, Inc., Honeywell International Inc., Johnson Controls, Eaton Corporation, OnSolve, LLC, Motorola Solutions, Inc., Alertus Technologies LLC, BlackBerry Limited, Singlewire Software, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Notification System Market Strategic Shifts & Innovations
Artificial intelligence is compressing alert generation latency by fusing sensor data, social media monitoring, and threat intelligence into automated dissemination triggers that bypass human approval bottlenecks during fast-evolving emergencies.
Machine learning-based threat detection is automating the transition from anomaly identification to mass alert issuance. University campus police departments in the United States are piloting these systems for active shooter scenarios. The technology is automating response time compression from minutes to seconds, reshaping competitive bids around speed metrics rather than channel breadth alone.
Europe's EECC mandate requires member states to deploy population-wide alert capabilities by specified deadlines, forcing national procurement cycles and vendor qualification shifts. National governments are consolidating previously fragmented municipal contracts into single-source framework agreements. Germany and France are accelerating tender releases to meet compliance windows, privileging vendors with existing carrier interoperability certifications.
Enterprise buyers are unbundling after-sales service from initial platform licensing, preferring consumption-based support models tied to actual alert volume rather than fixed annual maintenance fees. Chemical facility operators in the US Gulf Coast region are leading this shift, negotiating per-incident technical support that scales with activation frequency. This pattern concentrates margin pressure on vendors with rigid service contract structures.
Mass Notification System Market Segmentation
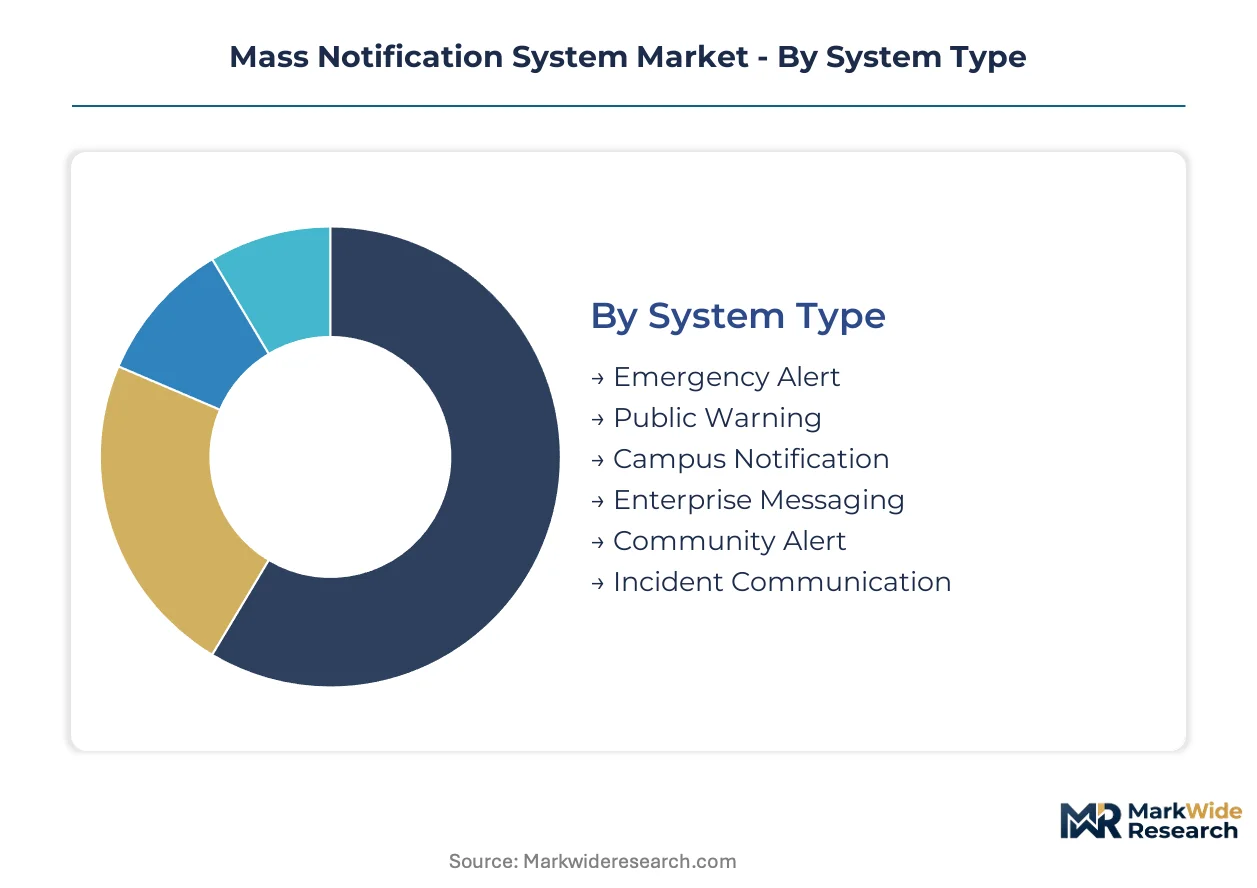
Mass notification system procurement varies sharply by deployment scale and integration depth. Standardized platforms serve municipal emergency managers with pre-certified configurations. Custom builds dominate enterprise buyers requiring API-native CRM tie-ins and building-management system convergence.
System Type:
Customization intensity tracks directly with regulatory mandate density and stakeholder complexity across this category.
- Emergency Alert:Government-mandated platforms engineered for FCC wireless emergency alert interoperability and EECC population-wide compliance. Demand concentrates in United States and Germany where carrier certification requirements compress procurement timelines.
- Enterprise Messaging:SaaS-delivered systems with API-based CRM integration and consumption-based pricing models. Chemical facility operators in US Gulf Coast region are unbundling after-sales service from licensing, negotiating per-incident technical support.
- Public Warning:Outdoor siren and broadcast infrastructure for population-scale reach.
- Campus Notification:Unified platforms merging lockdown triggers with parent and first-responder messaging.
- Community Alert:Neighborhood-scale systems for localized incident communication.
- Incident Communication:Event-specific notification workflows for operational continuity.
Most installed capacity flows through Emergency Alert. Expansion is steepest in Enterprise Messaging.
Technology:
Channel selection reflects recipient accessibility patterns and infrastructure legacy positions across deployment geographies.
- Mobile App:Push notification platforms leveraging smartphone saturation in remote populations previously served only by outdoor sirens. Rural jurisdictions in Japan and United States are expanding addressable recipient pools fastest.
- SMS:Carrier-interoperable text broadcast requiring FCC certification and commercial mobile carrier technical compliance. FCC testing timelines extend vendor qualification periods, freezing smaller competitors from partnerships.
- Email:Enterprise-grade broadcast with attachment and rich content capabilities.
- Voice Broadcast:Pre-recorded and text-to-speech telephony for non-smartphone populations.
- Social Media Integration:Automated cross-posting to municipal and institutional accounts.
- Outdoor Sirens:Analog and IP-based audible warning infrastructure with steep capital requirements for legacy network upgrades.
Channel breadth determines competitive positioning in municipal RFPs. Mobile App is gaining share fastest among new deployments.
Application:
Use-case specificity drives feature prioritization and integration architecture decisions across buyer segments.
- Disaster Response:Multi-hazard platforms fusing sensor data, social media monitoring, and threat intelligence into automated dissemination triggers. University campus police departments in United States are piloting machine learning-based active shooter detection.
- Educational Institution Safety:Lockdown trigger integration with access control and fire panel systems. Higher education consolidates parent notification and first-responder dispatch into unified command interfaces.
- Facility Security:Perimeter breach and intrusion response with building-management convergence.
- Event Management:Crowd safety and logistical coordination for large gatherings.
- Transportation Safety:Transit system passenger and operator alerting.
- Utility Outage:Customer notification for service interruption and restoration.
Disaster Response commands the largest procurement volumes. Educational Institution Safety is expanding most quickly.
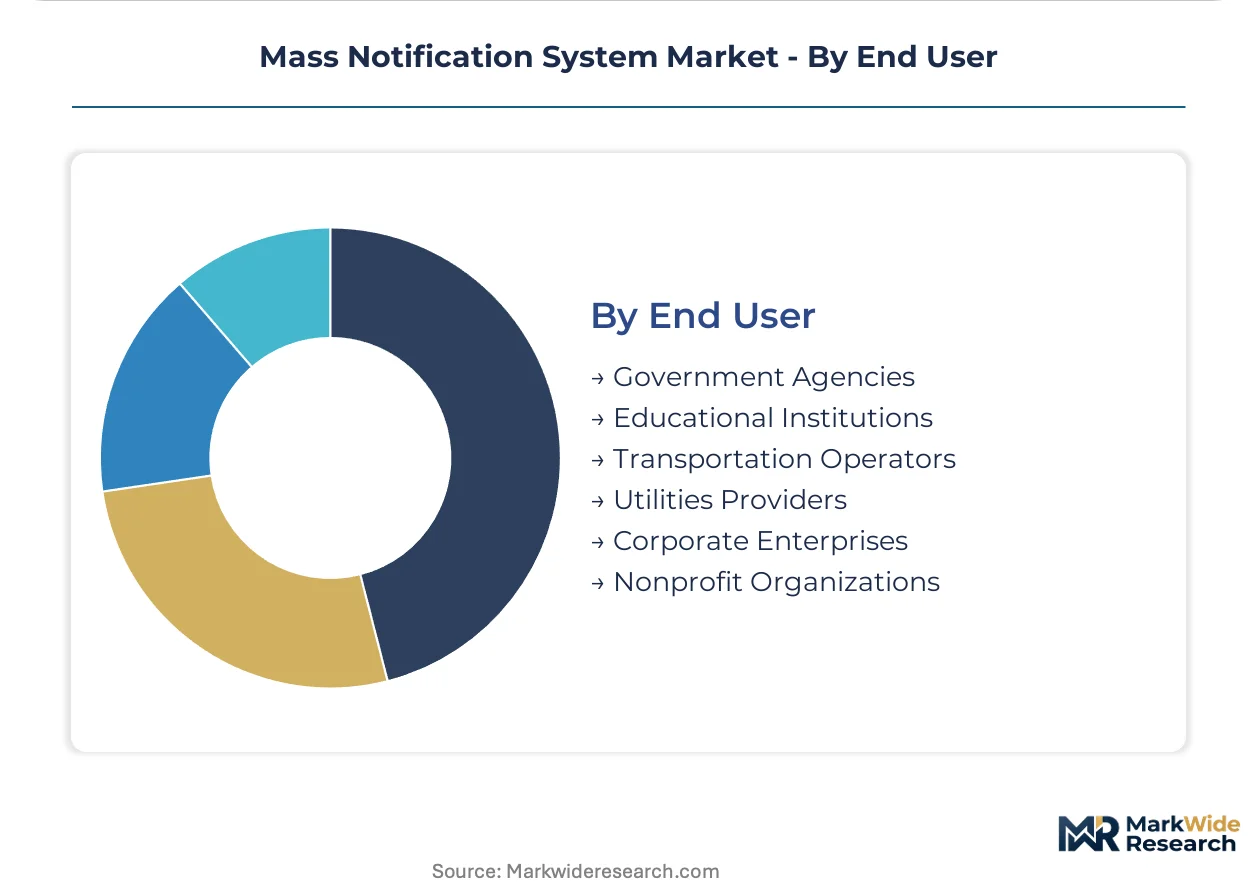
End User:
Budget authority and compliance obligation patterns segment buyer sophistication and contract structure preferences.
- Government Agencies:Federal, state, and municipal procurement with varying rules across alert system implementations. National governments in Europe are consolidating fragmented municipal contracts into single-source framework agreements.
- Corporate Enterprises:Manufacturing and chemical facilities seeking OSHA-compliant site-specific notification layers with API-native CRM tie-ins.
- Educational Institutions:Higher education and K-12 districts with campus safety integration requirements.
- Transportation Operators:Transit authorities and aviation facilities with public-safety-grade voice and data needs.
- Utilities Providers:Electric, gas, and water operators with customer notification mandates.
- Nonprofit Organizations:Community-based alerting with limited capital budgets.
Government Agencies anchor procurement volumes. Corporate Enterprises are adopting consumption-based models fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Critical infrastructure protection budgets in the United States, Germany, and Japan are expanding fastest, concentrating procurement of multi-channel emergency alert platforms in these three industrial clusters.
United States
FCC wireless emergency alert mandates and campus safety integration drive municipal and higher-ed procurement. OSHA workplace emergency action plan standards compel manufacturing and chemical facilities to deploy site-specific notification layers. University campus police departments across Texas and California are piloting machine learning-based active shooter detection systems.
Germany
EECC compliance deadlines and national framework agreements are consolidating fragmented municipal contracts. The country's central emergency management authority accelerates tender releases to meet population-wide alert capability requirements. Industrial operators in North Rhine-Westphalia and Bavaria embed notification logic into fire panels and access control systems.
Japan
METI-directed resilience infrastructure spending targets public-safety-grade voice and data network upgrades. Smartphone saturation in rural Tohoku and Kyushu expands addressable recipient pools beyond traditional outdoor siren coverage. Critical facility operators in the Kanto region prioritize multi-channel platforms with automated sensor fusion capabilities.
United Kingdom
Government procurement of emergency alert platforms intensifies following EECC transposition into national law. The country's communications regulator enforces technical standards for commercial mobile carrier participation. Municipal authorities in Greater London and the West Midlands consolidate legacy analog systems into IP-based multi-channel architectures.
India
Smart city mission funding channels investment into integrated command and control centers with mass notification capabilities. The Telecom Regulatory Authority of India shapes mobile broadcast technical frameworks for disaster management applications. State disaster management authorities in Maharashtra and Gujarat deploy smartphone-based alert systems for coastal and industrial hazard zones.
Mass Notification System Market Key Industry Players
Carrier interoperability certification dominates the current landscape, compressing vendor qualification timelines and freezing smaller competitors from public-safety partnerships. The market structures around three tiers: integrated building-automation conglomerates, pure-play SaaS alert platforms, and public-safety communications specialists. Strategic archetypes include threat-intelligence-anchored enterprise vendors, fire-and-security-panel integrators, and mission-critical voice network incumbents. M&A activity and API-native platform development represent the dominant competitive vectors.
Within the integrated systems tier, Johnson Controls and Eaton Corporation exemplify building-management convergence strategies, embedding notification logic directly into facility automation infrastructure. Everbridge, Inc. occupies a position in the pure-play SaaS segment, anchoring enterprise and higher-ed contracts through threat intelligence integration. Motorola Solutions, Inc. represents the public-safety specialist archetype, extending installed base advantages in voice and data networks into interoperable alert system procurement.
| Leading Market Players |
|---|
| Everbridge, Inc. |
| Honeywell International Inc. |
| Johnson Controls |
| Eaton Corporation |
| OnSolve, LLC |
| Motorola Solutions, Inc. |
| Alertus Technologies LLC |
| BlackBerry Limited |
| Singlewire Software, LLC |
| Others |
Cost & Logistics Intelligence
Carrier certification divergence between FCC-validated platforms and uncertified alternatives splits the market into premium public-safety-grade tiers and commoditized enterprise SaaS offerings, with pricing power accumulating to vendors who have cleared interoperability testing while supply chains fragment between cloud-native software stacks and hardware-integrated building automation systems.
Pricing Analysis
Input-cost pass-through from carrier certification testing and threat-intelligence licensing anchors subscription pricing for public-safety-grade platforms, while API-native SaaS tiers compete on consumption-based models. Price differentiation hinges on FCC wireless emergency alert certification status and after-sales service bundling. Cost compression in the mid-market intensifies as chemical facility operators unbundle maintenance from licensing. Government agencies show least price sensitivity due to mandate-driven procurement timelines.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for cellular modem chipsets and with the United States for threat-intelligence data feeds. Hardware production draws from China for outdoor siren components, Mexico for assembly integration, and Germany for industrial-grade control systems. Tariff exposure runs through cross-border cloud hosting and data residency compliance. Distribution runs through direct public-sector procurement frameworks and channel partners serving enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in API-native SaaS tiers where consumption-based pricing decouples revenue from fixed licensing, while building-automation convergence creates sticky integration revenue that resists commoditization pressure.
For Market Incumbents: Deepen carrier interoperability certification moats to freeze smaller competitors from public-safety partnerships, and accelerate threat-intelligence engine R&D to anchor enterprise contract renewals against pure-play SaaS entrants. Vertical integration into building-management systems via fire panel and access control convergence extends installed base advantages. For New Entrants and Emerging Players: API-first deployment routes offer the fastest penetration path into manufacturing and chemical facilities seeking OSHA-compliant site-specific notification layers. White-space concentrates in Japan's METI-directed resilience infrastructure spending and in rural US jurisdictions replacing analog siren networks. Target per-incident technical support models to displace rigid service contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where carrier certification bottlenecks strand sub-scale vendors without interoperability testing resources. Long-term viability favors platforms with dual revenue streams across public-sector mandates and enterprise SaaS. The signal to watch is national framework agreement awards in Germany and France as EECC deadlines compress procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Interoperability Certification | FCC wireless emergency alert validation opens public-safety procurement pipelines and freezes uncertified competitors from municipal RFPs. |
| Threat Intelligence Engine Development | Machine learning-based sensor fusion compresses alert latency from minutes to seconds for active shooter scenarios. |
| Building-Management System Convergence | Embedding notification logic into Johnson Controls and Eaton fire panels creates sticky facility automation integration revenue. |
| API-Native SaaS Platform Launch | Consumption-based pricing with CRM tie-ins captures chemical facility demand for OSHA-compliant site-specific notification layers. |
| Japan Market Expansion | METI-directed resilience infrastructure spending targets public-safety-grade voice and data network upgrades in Kanto and Tohoku regions. |
Research Approach
Direct dialogue with emergency management directors, campus safety officers, carrier interoperability engineers, and chemical facility operations managers combined with secondary validation against FCC filing databases, EECC implementation reports, SEC 10-K infrastructure disclosures, and municipal procurement records. Bottom-up and top-down triangulation cross-checks vendor revenue estimates against national budget appropriations for critical infrastructure protection.
Analytical lens alternates between bottom-up aggregation of platform deployment data and top-down calibration against government mandate spending envelopes across the projection horizon. Segmentation dimensions modeled include system type, technology channel, application use case, and end-user budget authority. CAGRs derive from logistic adoption curves fitted to smartphone saturation thresholds and regulatory compliance deadlines. Industry-specific inputs include carrier certification pipeline backlogs and METI resilience infrastructure appropriations.
The model assumes a particular technology adoption path; alternative pathways for AI-driven automated alert generation would alter the outlook if liability frameworks shift liability from human approval to algorithmic decision-making. Forecasts reflect assumptions about mandate enforcement continuity and carrier interoperability testing capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
IAM Security Services Market
Security Software
Video Intercom Devices Market
Security Software
Secaas Market
Security Software
Global User Activity Monitoring Market
Security Software
Application Control Market
Security Software
Online Background Check Market
Security Software
Japan Mobile Biometrics Market
Security Software
Quantum Key Distribution System Market
Security Software
Contactless Smart Card Market
Security Software
Encryption As A Service Market
Security Software
Smartphone Security Market
Security Software
ATM Security Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Passwordless Authentication Market
Security Software
Global Visitor Management System Market
Security Software
Global Email Verification Tools Market