
 Personal Analytics Market | 2026-2036
Personal Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Analytics Market Analysis
GDPR Article 22 on automated decision-making is recalibrating the cost-of-entry calculus for personal analytics vendors serving European users. Microsoft Corporation leverages its Azure compliance infrastructure to sustain cross-border data governance capabilities. Google LLC anchors its position through in-house biometric sensor integration across Pixel and Fitbit ecosystems. IBM Corporation differentiates via specialized health AI governance tools that navigate emerging regulatory complexity.
Personal analytics encompasses the collection, processing, and visualization of individual-level behavioral, physiological, and transactional data through embedded sensors, application interfaces, and cloud-native inference pipelines, typically operating at latency thresholds under 100 milliseconds for real-time feedback loops. Its primary commercial purpose centers on enabling self-directed optimization of health outcomes, productivity metrics, and financial behaviors through quantified-self methodologies. Cloud Solutions currently command the largest revenue share within product type segmentation, while Predictive Analytics within the technology dimension exhibits the steepest trajectory as employers demand forward-looking risk stratification for workforce health interventions. Mobile Applications retain dominant user penetration but face margin compression from platform store fees and heightened data localization mandates.
The FDA oversees software-as-medical-device classifications for diagnostic-adjacent personal analytics, while the EU AI Act imposes conformity assessment obligations on high-risk biometric inference systems, and HIPAA governs protected health information flows for employer-sponsored wellness platforms in the United States. These frameworks collectively elevate compliance spending but simultaneously create defensible moats for vendors with pre-certified quality management systems. Stakeholders must monitor the divergence between sector-specific health claims regulation and general-purpose AI governance to anticipate which compliance investments will yield durable market access advantages.
Market Dynamics
Employer-sponsored wellness platforms are recalibrating procurement criteria toward predictive risk stratification, forcing vendors to rearchitect inference pipelines for sub-100-millisecond latency thresholds while simultaneously navigating divergent algorithmic transparency mandates across the United States and European Union.
Growth Catalysts
- EU AI Act Conformity Pathways:High-risk biometric inference systems face mandatory conformity assessments, creating first-mover advantages for vendors with pre-certified quality management systems.
- Corporate Wellness Procurement:Employer-sponsored health plan administrators are mandating forward-looking workforce health interventions, concentrating demand for predictive analytics capabilities.
- Cloud-Native Inference Pipelines:Embedded sensor-to-cloud architectures enable real-time behavioral feedback loops, accelerating adoption among productivity optimization platforms.
Market Restraints
- GDPR Article 22 Friction:Automated decision-making restrictions elevate legal review costs for European deployments, compressing margins for cross-border service delivery.
- Platform Store Fee Compression:Mobile application distribution through Apple and Google ecosystems extracts 15-30% of recurring revenue, eroding unit economics for consumer-facing analytics providers.
- Data Localization Mandates:Sovereign cloud requirements in Germany, France, and India fragment infrastructure investment, preventing scale efficiencies in compute provisioning.
Strategic Opportunities
- Underpenetrated Clinical Adjacencies:Diagnostic-adjacent personal analytics outside FDA software-as-medical-device classifications offer lower compliance barriers for cardiovascular and metabolic monitoring applications.
- Biometric Sensor Convergence:Integration of photoplethysmography with accelerometry and galvanic skin response creates multi-modal inference platforms for stress and sleep architecture analysis.
- India PLI Scheme Incentives:Production-linked incentives for wearable electronics manufacturing reduce landed costs for sensor hardware, enabling price-competitive market entry.
Industry Challenges
- Health AI Governance Talent Scarcity:Shortage of professionals capable of bridging clinical validation protocols with machine learning operations pipelines delays product certification timelines.
- Legacy Electronic Health Record Integration:Employer wellness platforms face API fragmentation and data format heterogeneity when connecting to established hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Analytics Market |
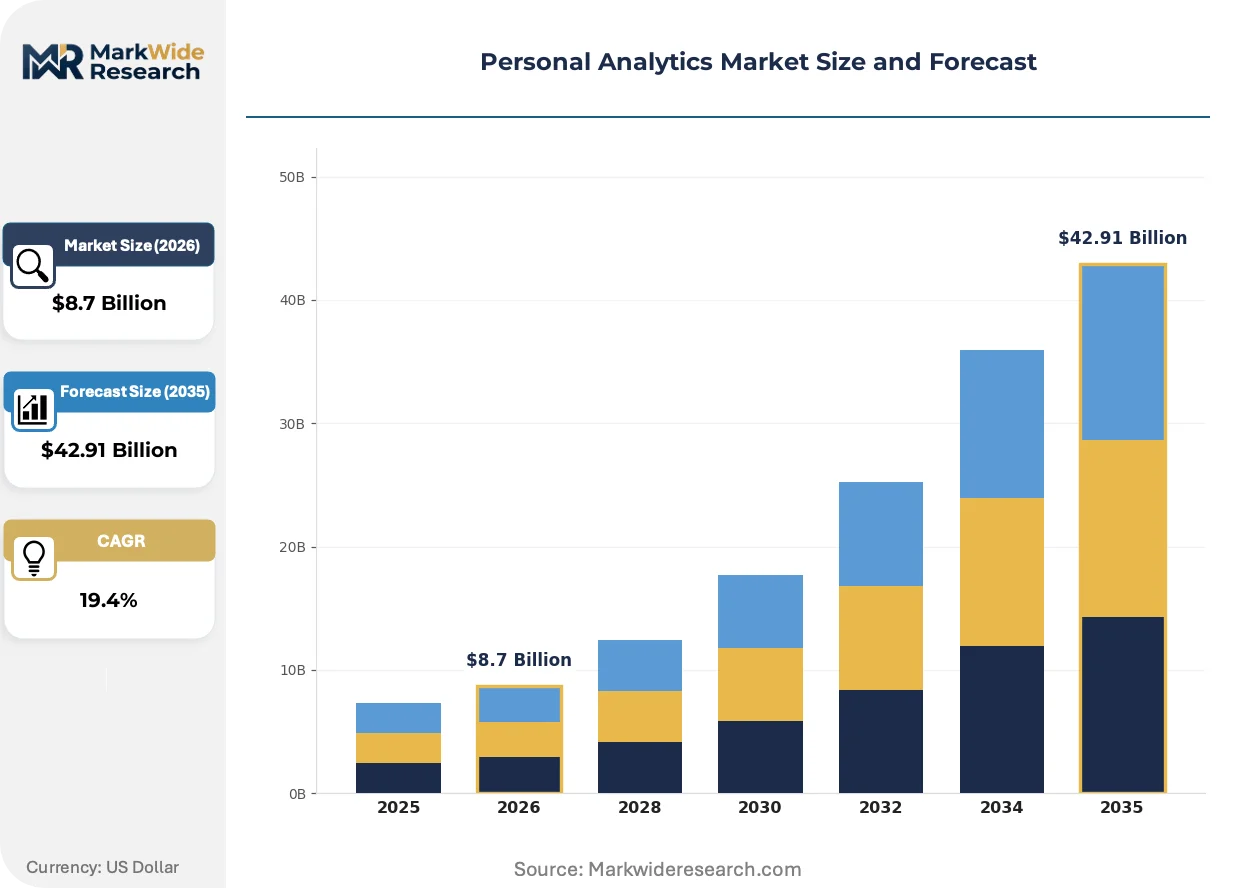
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Desktop Software, Cloud Solutions End User: Individuals, Healthcare Professionals, Fitness Coaches, Corporate Employees Technology: Artificial Intelligence, Machine Learning, Data Visualization, Predictive Analytics Application: Health Monitoring, Fitness Tracking, Behavioral Analysis, Personal Finance |
| Companies Covered | IBM Corporation, Microsoft Corporation, Google LLC, Oracle Corporation, SAP SE, Amazon Web Services, Adobe, Salesforce, Alteryx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Analytics Market Emerging Trajectories
Federated learning architectures and edge-computing inference are redistributing computational load away from centralized cloud infrastructure, while regulatory divergence between health-specific and general-purpose AI governance creates compliance complexity that favors specialized vendors.
On-device machine learning is automating biometric signal processing for glucose variability prediction and atrial fibrillation detection, eliminating round-trip latency to cloud servers. Wellness platform procurement teams at Fortune 500 employers are prioritizing vendors with edge-native architectures for data sovereignty assurance. This shift is compressing infrastructure costs for real-time feedback applications while elevating hardware BOM requirements.
The EU AI Act's high-risk system designation for biometric inference imposes conformity assessment obligations that extend FDA software-as-medical-device precedents into general wellness applications. Vendors must maintain technical documentation and post-market monitoring systems that satisfy both HIPAA business associate agreements and EU notified body scrutiny. Dual-jurisdiction compliance investments are concentrating vendor consolidation among entities with pre-existing quality management certifications.
Buyer procurement committees now mandate outcome-based contracting for workforce wellness interventions, replacing per-employee-per-month subscription models with payment contingent on measured health risk reduction. Third-party administrators and benefits consultants are intermediating this transition, capturing margin that previously accrued to platform vendors. This behavioral shift is most visible in United States self-insured employer plans above 10,000 covered lives.
Personal Analytics Market Segmentation
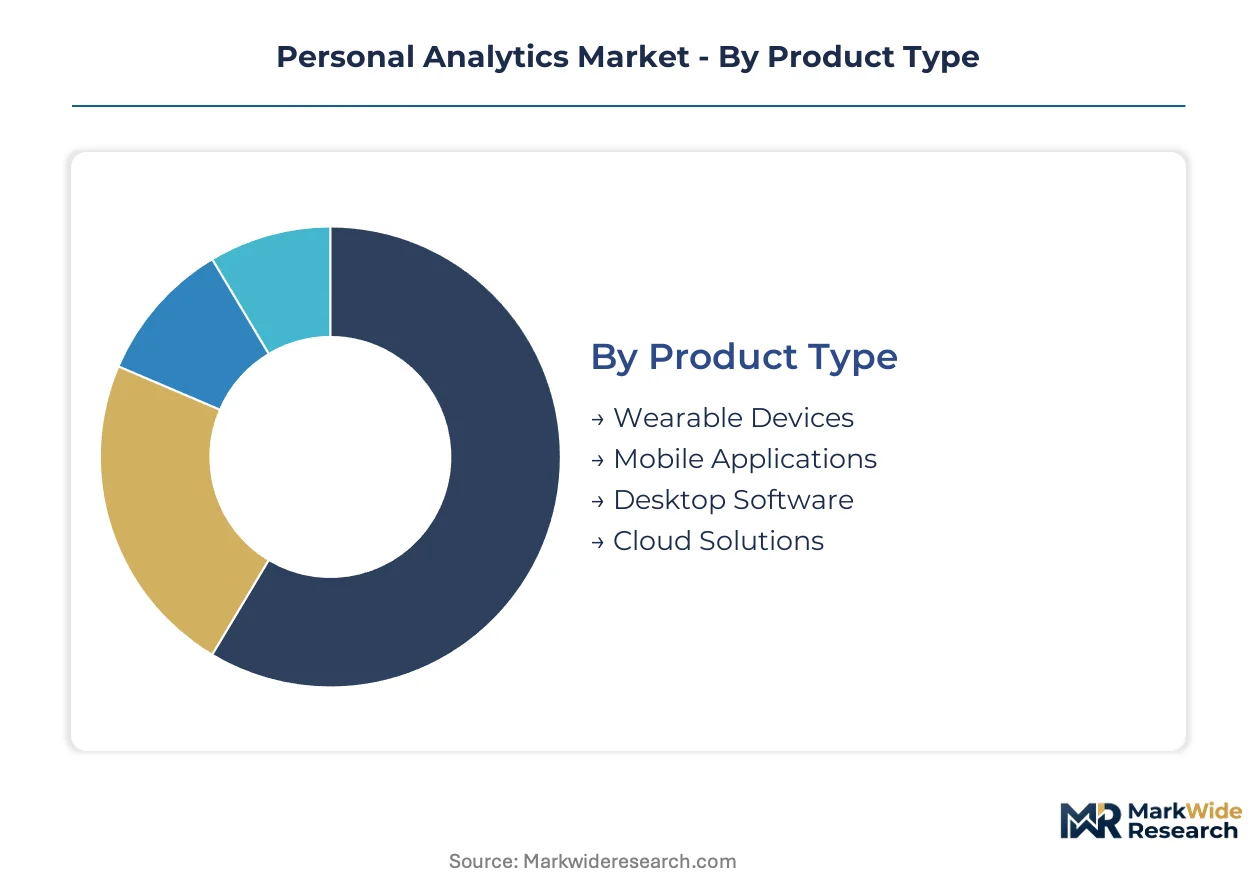
Personal analytics vendors architect product portfolios around four intersecting dimensions: delivery modality, user workflow integration, inference sophistication, and outcome domain. Procurement committees at self-insured employers and wellness platform operators evaluate segments through divergent lenses of regulatory exposure, latency tolerance, and data sovereignty requirements.
Product Type:
Latency thresholds and data residency requirements differentiate deployment architectures across hardware and software modalities.
- Cloud Solutions:Centralized inference pipelines process multi-modal biometric streams through sovereign-hosted infrastructure, satisfying GDPR Article 22 audit trails and HIPAA business associate obligations for employer-sponsored wellness platforms. Procurement committees at United States health plan administrators mandate cloud-native architectures for predictive risk stratification capabilities.
- Wearable Devices:Photoplethysmography and accelerometry sensors embedded in wrist-worn hardware enable sub-100-millisecond feedback loops without round-trip server latency. Edge-computing inference on these devices addresses data localization mandates in Germany and France while elevating BOM costs.
- Mobile Applications:Distribution through Apple and Google ecosystems extracts 15-30% platform fees, compressing margins for consumer-facing quantified-self providers.
- Desktop Software:On-premise processing satisfies financial services compliance requirements for personal finance analytics without cloud data exposure.
Mature deployment sits with Cloud Solutions. Newer deployment is concentrated in Wearable Devices.
End User:
Buyer sophistication and procurement authority create distinct margin profiles across consumer and institutional channels.
- Corporate Employees:Self-insured employers above 10,000 covered lives mandate outcome-based contracting tied to measured health risk reduction, replacing per-employee-per-month subscriptions. Third-party benefits administrators intermediate this transition, capturing margin that previously accrued to platform vendors.
- Individuals:Direct-to-consumer quantified-self adoption concentrates among cardiovascular and metabolic monitoring applications outside FDA software-as-medical-device classifications.
- Healthcare Professionals:Clinical validation protocols and EHR integration complexity delay product certification timelines for diagnostic-adjacent deployments.
- Fitness Coaches:Biometric sensor convergence for stress and sleep architecture analysis drives demand among performance optimization specialists.
Volume concentrates with Corporate Employees. Margin expansion is strongest with Healthcare Professionals.
Technology:
Inference sophistication determines compliance burden and defensible differentiation.
- Predictive Analytics:Forward-looking risk stratification for workforce health interventions demands forward-looking algorithmic transparency documentation under EU AI Act high-risk system designations. Vendors must maintain technical documentation and post-market monitoring systems that satisfy both HIPAA and EU notified body scrutiny.
- Artificial Intelligence:Federated learning architectures redistribute computational load away from centralized cloud infrastructure while preserving data sovereignty.
- Machine Learning:On-device automation of biometric signal processing eliminates round-trip latency for glucose variability prediction.
- Data Visualization:Real-time behavioral feedback loops through application interfaces operate at latency thresholds under 100 milliseconds.
Regulatory scrutiny is tightest on Predictive Analytics. Capability investment is accelerating fastest in Artificial Intelligence.
Application:
Outcome measurement rigor and reimbursement pathways shape addressable market expansion.
- Health Monitoring:FDA software-as-medical-device classifications for diagnostic-adjacent cardiovascular and metabolic applications create compliance moats for pre-certified quality management systems.
- Behavioral Analysis:GDPR Article 22 automated decision-making restrictions elevate legal review costs for European deployments of productivity optimization platforms.
- Fitness Tracking:Integration of photoplethysmography with galvanic skin response creates multi-modal inference platforms for stress quantification.
- Personal Finance:Data localization mandates in India fragment infrastructure investment for transactional behavioral analytics.
Certification requirements are most stringent for Health Monitoring. Revenue diversification is expanding most quickly in Behavioral Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Bengaluru accelerate wearable hardware concentration through production-linked incentives and duty exemptions on sensor component imports.
United States
Self-insured employers above 10,000 covered lives drive predictive analytics procurement for workforce health interventions. HIPAA governs protected health information flows for employer-sponsored wellness platforms, elevating compliance spending but creating defensible moats. Boston and San Francisco host clusters of health AI governance specialists bridging clinical validation with machine learning operations.
Germany
Data localization mandates in sovereign cloud requirements fragment infrastructure investment for personal analytics vendors. The country's national data protection authority enforces GDPR Article 22 automated decision-making restrictions, elevating legal review costs for European deployments. Munich and Berlin concentrate edge-computing inference startups addressing latency thresholds under 100 milliseconds.
India
The PLI scheme for wearable electronics manufacturing reduces landed costs for photoplethysmography sensor hardware. Production-linked incentives enable price-competitive market entry for biometric device producers. Bengaluru and Hyderabad anchor cloud-native inference pipeline development for real-time behavioral feedback applications.
China
Dual carbon goals accelerate energy-efficient edge-computing architectures for on-device machine learning in wrist-worn hardware. The national medical products administration oversees software-as-medical-device classifications for diagnostic-adjacent cardiovascular monitoring. Shenzhen's Special Economic Zone concentrates multi-modal sensor integration for stress and sleep architecture analysis.
United Kingdom
Outcome-based contracting for workforce wellness interventions replaces per-employee-per-month subscription models among Fortune 500 employer plans with UK operations. The country's national data regulator enforces algorithmic transparency requirements for health-adjacent analytics platforms. London's fintech corridor drives personal finance analytics adoption without cloud data exposure through on-premise processing.
Personal Analytics Market Vendor Landscape
United States technology conglomerates anchor the premium tier; European enterprise software specialists hold institutional workflow integration positions. The vendor base stratifies across three layers: cloud infrastructure providers with pre-certified compliance systems, wearable hardware manufacturers with captive sensor ecosystems, and vertical analytics platforms with health AI governance tooling. Two dominant competitive moves define current positioning: backward integration into biometric sensor hardware to escape platform store fee compression, and strategic partnerships with third-party benefits administrators to capture outcome-based contracting margin.
Within the cloud infrastructure tier, Microsoft Corporation exemplifies vendors leveraging Azure compliance infrastructure for cross-border data governance. Google LLC occupies a position among hardware-integrated players through in-house biometric sensor convergence across device ecosystems. IBM Corporation anchors the specialized health AI governance segment, navigating emerging regulatory complexity through dedicated tooling. These three entities represent distinct strategic archetypes rather than direct substitutes, with procurement committees evaluating each against divergent criteria of latency tolerance, algorithmic transparency documentation, and data sovereignty assurance.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Google LLC |
| Oracle Corporation |
| SAP SE |
| Amazon Web Services |
| Adobe |
| Salesforce |
| Alteryx |
| Others |
Supply Flow & Price Mechanics
Photoplethysmography sensor modules flow from Shenzhen assembly lines through tiered pricing structures that reward volume commitments from employer wellness platforms while penalizing spot purchasers with 40-60 day lead time premiums. Cloud-native inference pipeline providers in Bengaluru and San Francisco anchor subscription tiers to HIPAA certification status, creating price cliffs between compliant and non-compliant deployments.
Pricing Analysis
Short lead time premiums dominate pricing negotiations, with Fortune 500 employers paying 15-25% above baseline for sub-30-day sensor hardware delivery. SaaS-tiered subscription structures stratify across premium, standard, and economy levels based on EU AI Act conformity documentation depth and algorithmic transparency tooling. Pricing pressure stems from platform store fee compression at Apple and Google ecosystems, which extracts 15-30% of recurring revenue. Individual consumers exhibit highest price sensitivity, while self-insured employers above 10,000 covered lives prioritize outcome-based contracting over unit cost.
Supply Chain Analysis
FDA software-as-medical-device and EU AI Act high-risk system qualifications gate supplier eligibility, concentrating photoplethysmography sensor sourcing in China, Taiwan, and South Korea. Edge-computing inference chipsets draw from TSMC fabrication and Qualcomm design licensing. Single-source vulnerability sits with advanced node semiconductor access. Distribution runs through third-party benefits administrators who intermediate outcome-based contracts for employer wellness platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration races, with backward integration into biometric sensor hardware and forward integration into benefits administration intermediation as the decisive levers.
For Market Incumbents: Lock in exclusive photoplethysmography sensor supply agreements with Shenzhen manufacturers before PLI scheme capacity absorption in India accelerates. Secure EU notified body pre-certification for high-risk biometric inference systems ahead of conformity assessment bottlenecks. Platform store fee compression demands captive hardware ecosystems that bypass Apple and Google distribution tolls. For New Entrants and Emerging Players: Launch via direct-to-employer sales bypassing third-party administrator margin capture, targeting self-insured employers below 10,000 covered lives with edge-native architectures that satisfy German data localization mandates. Cardiovascular monitoring applications outside FDA software-as-medical-device classifications offer lowest compliance barriers. White-space concentrates in stress and sleep architecture analysis for fitness coach workflows. For Investors and Strategic Acquirers: Outcome-based contracting penetration above 50% in Fortune 500 employer plans is the leading indicator that platform economics have shifted decisively toward health risk reduction verification. Five-to-ten-year viability favors vendors with dual-jurisdiction compliance infrastructure spanning HIPAA and EU AI Act frameworks. Acquisition targets should display pre-certified quality management systems and edge-computing inference patents. Watch for EU notified body queue lengths exceeding 18 months as capacity constraint signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captive photoplethysmography supply escapes 15-30% platform store fee extraction at Apple and Google ecosystems. |
| EU AI Act Pre-Certification | Notified body quality management systems create defensible moats against conformity assessment delays. |
| Edge-Native Architecture Deployment | On-device inference satisfies GDPR Article 22 audit trails and German data localization mandates. |
| Benefits Administrator Partnership | Strategic alliances with third-party administrators capture outcome-based contracting margin from employer wellness platforms. |
| Federated Learning Platform Launch | Distributed computation architectures preserve data sovereignty while enabling cross-border model training. |
Methodological Framework
SEC filings, EU AI Act implementation guidance, and hospital procurement databases formed the secondary backbone, supplemented by primary interviews with CTOs at employer wellness platforms, health AI governance specialists, biomedical engineers at wearable device manufacturers, and GPO contracts managers at self-insured employers. Bottom-up triangulation across sensor hardware bill-of-materials and top-down validation against cloud infrastructure capex disclosures anchored market sizing.
Historical trendline analysis of biometric sensor shipment volumes and employer wellness platform subscription renewals informed projection modeling across product type, end user, technology, and application dimensions. CAGRs derived from segment-level growth rate differentials weighted by procurement committee prioritization of predictive analytics capabilities. Edge-computing inference adoption curves and EU AI Act compliance cost trajectories served as industry-specific forecast inputs.
Regulatory enforcement divergence between FDA software-as-medical-device and EU AI Act high-risk system designations, platform store fee structure revisions, and photoplethysmography sensor supply consolidation are the dominant revision risks. Forecasts reflect documented assumptions on employer procurement shift timing and cloud infrastructure pricing stability. A model refresh is warranted upon material change in EU notified body assessment capacity or HIPAA business associate agreement interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Content Intelligence Market
Analytics
Cloud Analytics Market
Analytics
Self Service Analytics Market
Analytics
Legal Analytics Market
Analytics
Drone Analytics Software Market
Analytics
North America Operational Intelligence Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Location Analytics Market
Analytics
Digital Analytics Solutions Market
Analytics
Statistical Analytics Market
Analytics
Predictive Analytics Market
Analytics
Big Data Analytics in BFSI Market
Analytics
Behavior Analytics Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Network Analysis Module (NAM) Market