
 Global Digital Signage Software Market | 2026-2036
Global Digital Signage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Signage Software Market Foresight
Premium digital signage software with real-time AI-driven personalization and edge analytics is decoupling from commodity content-looping platforms that offer basic scheduling. BrightSign leverages proprietary media player hardware to sustain tight integration between device firmware and management layers. Navori differentiates through advanced audience measurement algorithms that anchor its positioning in high-traffic transportation hubs. Xibo Signage competes on open-source flexibility, occupying the mid-market with customizable deployment architectures.
Digital signage software encompasses content management systems, network orchestration tools, and analytics platforms that schedule, distribute, and monitor visual media across distributed display networks, typically supporting 4K resolution, HTML5 rendering, and API-driven data feeds for live content injection. Its primary commercial purpose is enabling organizations to replace static messaging with dynamically updable visual communication that responds to audience context, time, or environmental triggers. Cloud-based deployment leads solution adoption by offering centralized control without on-site server maintenance, while analytics and reporting segments capture expanding margin pools as advertisers demand proof-of-play and demographic verification. Content management systems remain the largest solution offering by installed base, though workflow automation is gaining traction in corporate and educational settings where approval chains govern publishing rights.
The EU AI Act, GDPR, and FCC guidelines in the United States collectively shape product roadmaps by mandating consent frameworks for facial recognition, data retention limits for audience analytics, and electromagnetic compatibility standards for networked hardware. REACH and RoHS compliance in Europe further constrain material choices for on-premise server components and display peripherals. Stakeholders must monitor evolving biometric privacy legislation across multiple jurisdictions to determine whether to disable camera-based analytics entirely or invest in anonymized computer vision alternatives that preempt regulatory enforcement.
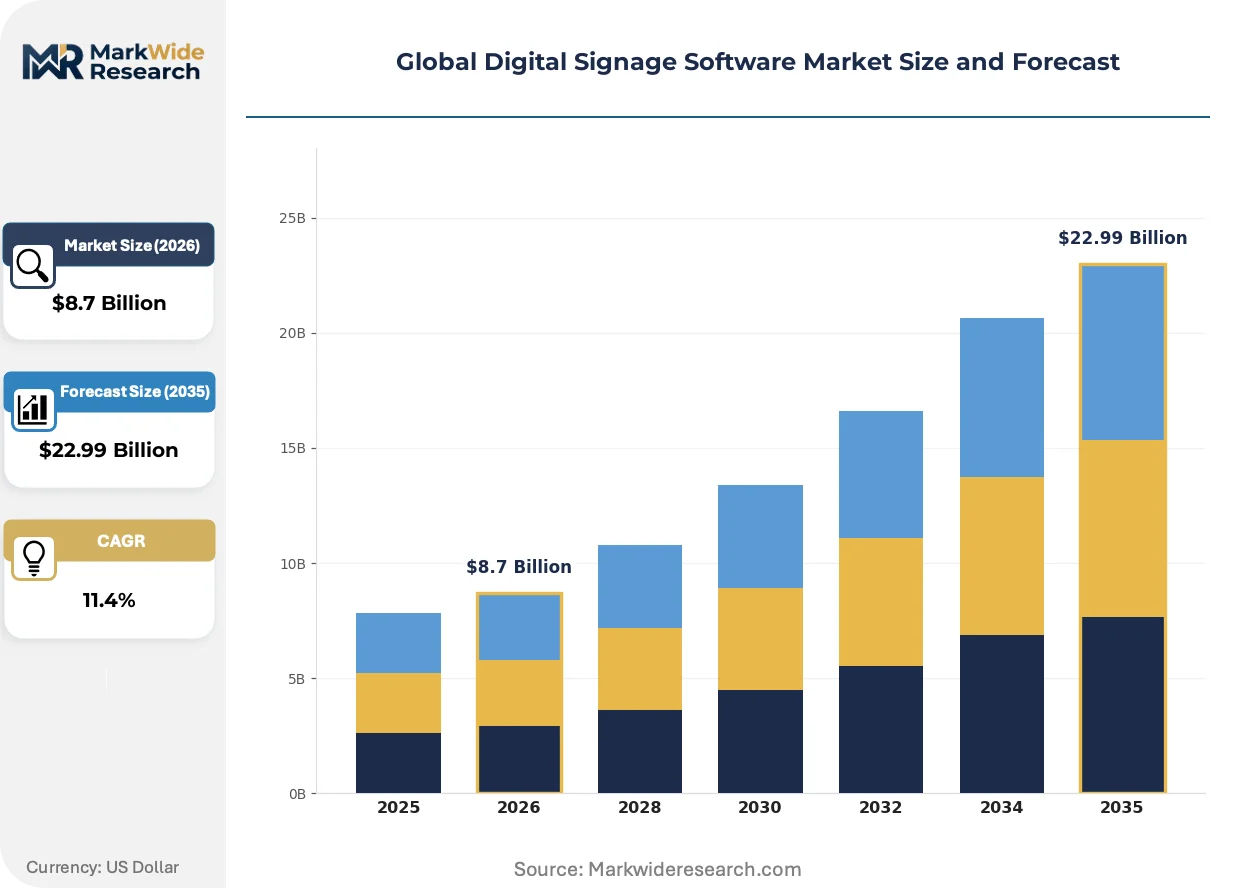
Market Dynamics
Edge computing architectures are fragmenting digital signage software into distributed intelligence layers, forcing vendors to rewrite content management systems for low-latency local processing rather than cloud-centralized orchestration.
Growth Catalysts
- Smart city infrastructure mandates:Transit authorities in Germany, South Korea, and the United States are procuring networked display ecosystems for real-time passenger information systems. These deployments require software platforms capable of API-driven data feeds and 4K rendering.
- EU AI Act compliance frameworks:Audience analytics vendors are investing in anonymized computer vision to preempt biometric privacy enforcement, creating demand for software with built-in consent management and data retention controls.
- HTML5 rendering engines:Retail chains are replacing legacy Flash-based players with modern browser cores that support dynamic content injection from live inventory systems and weather APIs.
Market Restraints
- Semiconductor supply concentration:Media player SoC availability depends on fabrication capacity concentrated in Taiwan and South Korea, creating procurement bottlenecks for hardware-integrated software bundles.
- GDPR data retention limits:Audience measurement algorithms face strict storage duration caps in European deployments, compressing the value extraction window for analytics-driven pricing models.
- Static print substitution:Cost-sensitive franchise operators in emerging markets continue deploying paper-based signage for promotional content, delaying software adoption.
Strategic Opportunities
- Workplace communication verticals:Corporate campuses in the United States are installing dashboard networks for HR announcements and KPI visualization, a segment historically served by email and intranets.
- India smart city initiatives:Municipal corporations are tendering for connected transit displays under national urban renewal programs, opening deployment opportunities for cloud-native software architectures.
- 5G network slicing:Telecommunications carriers are offering guaranteed bandwidth tiers for digital signage backhaul, enabling broadcast-quality live streaming to outdoor displays without fiber installation.
Industry Challenges
- Computer vision engineering scarcity:Vendors struggle to recruit talent capable of optimizing edge inference pipelines for ARM-based media players with thermal and power constraints.
- Legacy CMS migration friction:Enterprise customers with decade-old on-premise installations face data portability barriers when transitioning to cloud-native platforms, requiring parallel operation periods.
- REACH substance compliance:Hardware peripherals containing restricted flame retardants trigger customs delays in European ports, disrupting synchronized software-hardware rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Signage Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Offering: Content Management System, Network Management, Analytics & Reporting, Remote Monitoring, Workflow Automation End User Industry: Retail Chains, Transportation Hubs, Entertainment Venues, Corporate Offices, Educational Institutions Use Case: Advertising Campaigns, Brand Awareness, Customer Engagement, Internal Communications, Public Information |
| Companies Covered | Xibo Signage, NowSignage, ScreenCloud, SpinetiX, Navori, Carousel, BrightSign, Mvix, NoviSign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Signage Software Market Shifts & Advancements
Software-defined display management is decoupling content orchestration from proprietary hardware, enabling cross-platform deployments that span multiple media player vendors within single networks.
Containerized deployment architectures are modularizing digital signage software into microservices for content rendering, device management, and analytics processing. Transit operators in Germany and South Korea are piloting these architectures to mix hardware generations within single networks. This modularity is compressing vendor lock-in duration and accelerating procurement cycles for best-of-breed components.
GDPR enforcement actions by CNIL in France and comparable regulators in Germany are mandating explicit consent mechanisms for camera-based audience measurement. Software vendors are responding by shipping analytics modules with facial detection disabled by default and requiring opt-in configuration. European deployments now lead in adoption of privacy-preserving computer vision that processes demographic inference without biometric storage.
Subscription pricing for software-only licenses is displacing perpetual purchase models in mid-market retail and education segments. Value-added resellers in the United States are bundling these subscriptions with managed services for content creation and network monitoring. This shift concentrates recurring revenue with vendors capable of delivering 99.9% uptime SLAs across geographically distributed display footprints.
Global Digital Signage Software Market Segmentation
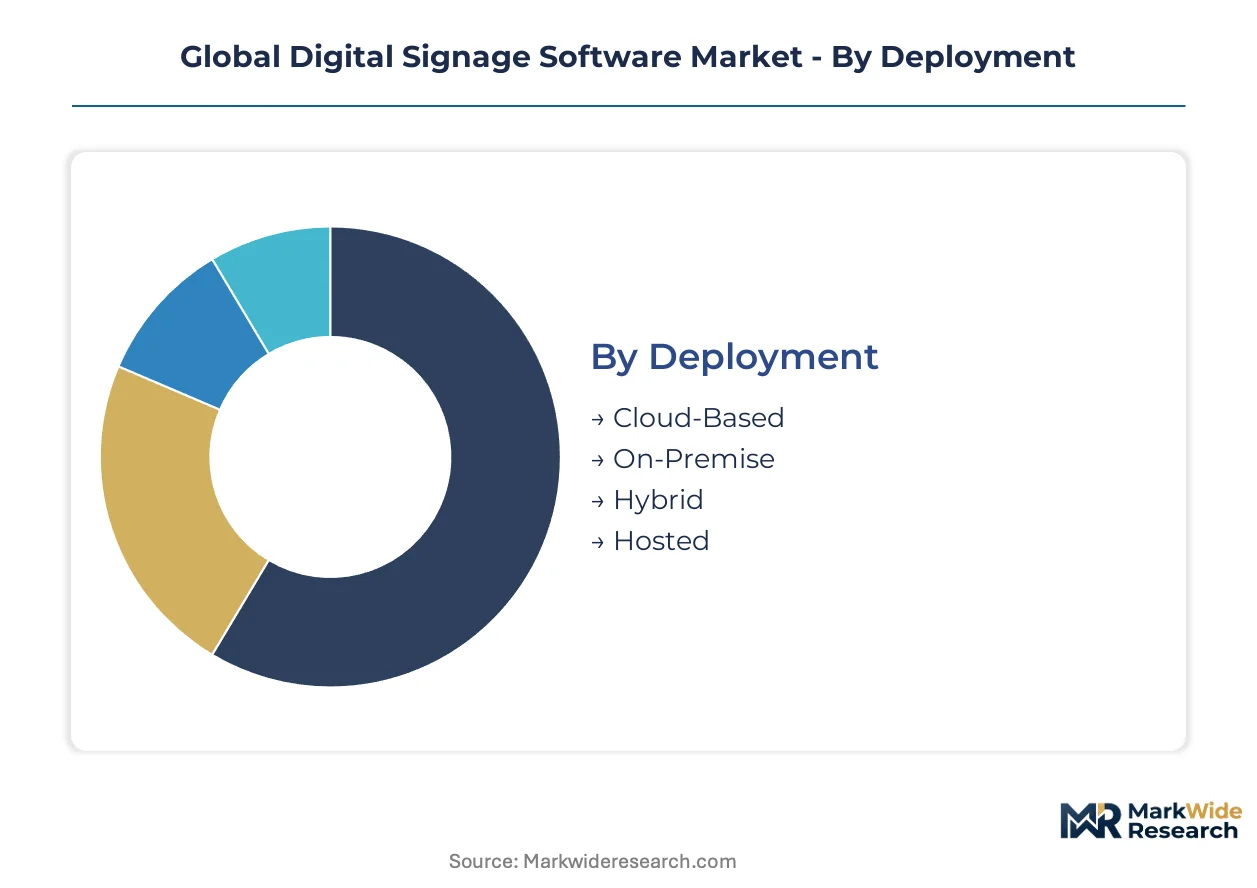
Digital signage software segments by deployment architecture, solution stack, end-user vertical, and functional use case. Each dimension shapes integration complexity, pricing models, and vendor selection criteria for procurement teams.
Deployment:
Standalone cloud deployments dominate mid-market retail and education, while embedded on-premise systems persist in high-security environments and legacy infrastructure.
- Cloud-Based:Centralized orchestration platforms eliminate on-site server maintenance and enable real-time content updates across distributed footprints. Demand concentrates in United States retail chains and German transit authorities seeking rapid scaling without capital expenditure. GDPR data residency requirements are forcing European deployments toward EU-sovereign cloud regions.
- On-Premise:Self-hosted installations retain full data custody behind corporate firewalls, supporting air-gapped networks in defense and financial services. South Korean smart city projects and United States corporate campuses specify on-premise stacks for latency-sensitive passenger information systems. Hardware refresh cycles extend 5-7 years, compressing software upgrade revenue recognition.
- Hybrid:Edge-local rendering with cloud-centralized management balances autonomy with remote oversight. German manufacturers deploy hybrid architectures to maintain production floor responsiveness while enabling headquarters dashboarding.
- Hosted:Third-party managed infrastructure offloads technical operations to specialized service providers. United States educational institutions and small-format retail operators favor hosted models for predictable operational expenditure.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
Solution Offering:
Software modules stratify by margin profile, with analytics commanding premium pricing against commoditized content scheduling tools.
- Content Management System:Core scheduling and playlist orchestration layers support 4K rendering, HTML5 widgets, and API-driven live data injection. Retail chains in the United States and Germany treat CMS as table stakes, with procurement decisions pivoting on workflow automation depth rather than baseline playback capability.
- Network Management:Device provisioning, firmware updates, and health monitoring across heterogeneous media player fleets. Transportation authorities in South Korea and Germany specify network management redundancy for 99.9% uptime SLAs on passenger information displays.
- Analytics & Reporting:Audience measurement modules process computer vision feeds or mobile signal detection to verify impression delivery. GDPR enforcement by CNIL and German regulators is mandating anonymized processing pipelines, raising engineering barriers for biometric-capable vendors.
- Remote Monitoring:Real-time display status, temperature telemetry, and predictive failure alerting. Entertainment venues in the United States deploy remote monitoring to minimize downtime during revenue-critical event windows.
- Workflow Automation:Approval chains, role-based publishing rights, and content versioning for regulated industries. Corporate offices and educational institutions specify workflow automation to govern brand compliance and legal review cycles.
Content Management System captures the largest installed base; Analytics & Reporting is climbing the fastest as advertisers demand proof-of-play verification.
End User Industry:
Vertical specialization determines feature prioritization, with transit operators emphasizing reliability and retail chains prioritizing dynamic personalization.
- Retail Chains:Flagship and franchise networks deploy dynamic pricing, inventory-linked promotions, and loyalty program integration. United States and German retailers are replacing legacy Flash players with HTML5 engines supporting live ERP data feeds.
- Transportation Hubs:Airports, rail terminals, and metro systems require fault-tolerant passenger information systems with multilingual wayfinding. South Korea's KTX stations and Germany's Deutsche Bahn deployments specify redundant edge computing for sub-second latency on arrival boards.
- Entertainment Venues:Stadiums, cinemas, and theme parks synchronize display networks with event schedules and concession operations. United States sports arenas integrate digital signage with mobile ordering platforms to compress transaction times.
- Corporate Offices:Campus-wide dashboard networks communicate HR announcements, KPI visualization, and emergency alerts. United States technology campuses treat digital signage as a workplace experience differentiator in talent competition.
- Educational Institutions:Universities and K-12 districts deploy wayfinding, event promotion, and cafeteria menu boards. German vocational schools and United States community colleges favor open-source platforms for budget-constrained multi-building deployments.
Retail Chains account for the deepest penetration; Transportation Hubs are gaining share fastest on smart city infrastructure mandates.
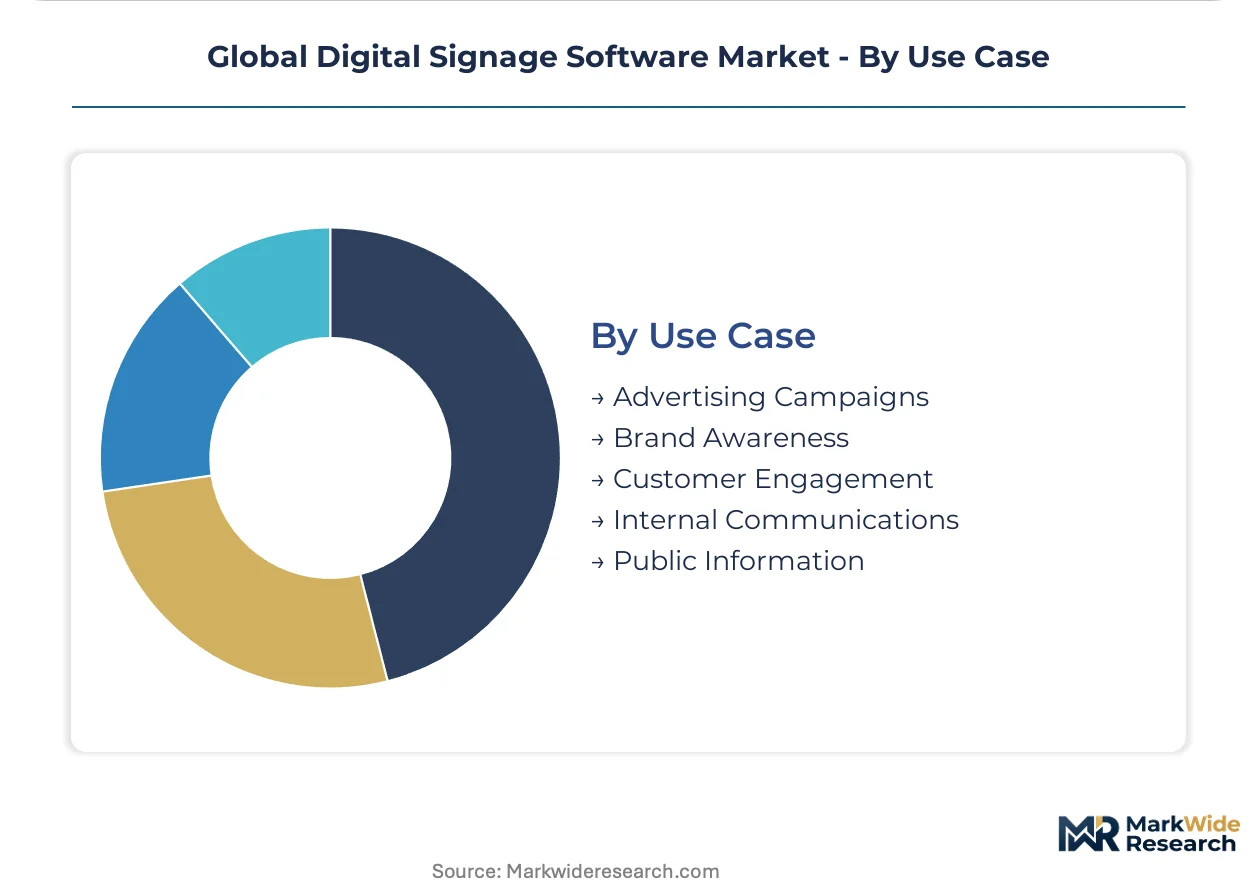
Use Case:
Functional applications segment by revenue model, with advertising-funded deployments driving analytics investment against cost-center internal communications.
- Advertising Campaigns:Programmatic media sales, impression verification, and demographic targeting for out-of-home networks. United States and German media owners are adopting anonymized computer vision to preempt GDPR enforcement on biometric data collection.
- Brand Awareness:Consistent visual identity enforcement across franchise locations and flagship experiences. South Korean consumer electronics brands deploy synchronized global campaigns through centralized cloud orchestration.
- Customer Engagement:Interactive wayfinding, product configurators, and queue management in retail and hospitality. German automotive showrooms integrate touchscreen signage with CRM systems to capture lead data.
- Internal Communications:Employee messaging, safety alerts, and operational dashboards behind corporate firewalls. United States healthcare systems and German manufacturers specify on-premise deployments for HIPAA and works council compliance.
- Public Information:Government messaging, emergency alerts, and civic service announcements. South Korean municipal corporations and United States transit authorities procure public information systems under federal infrastructure programs.
Advertising Campaigns generates the highest software spend per display; Internal Communications is expanding most quickly as corporate campuses replace email-centric communication stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the Asia-Pacific digital signage software corridor through its KTX smart station deployments and 5G-connected transit infrastructure mandates. The United States, Germany, and South Korea concentrate procurement activity for cloud-native content management platforms.
United States
Corporate campuses in Austin and San Francisco deploy workplace dashboard networks for HR messaging and KPI visualization. FCC guidelines on electromagnetic compatibility shape hardware-integrated software bundling decisions. Retail chains in Chicago and Dallas accelerate HTML5 player replacements for dynamic inventory-linked promotions.
Germany
Deutsche Bahn specifications for redundant edge computing drive demand in rail terminals across Bavaria and North Rhine-Westphalia. GDPR data retention limits enforced by German regulators compress analytics value extraction windows. Automotive showrooms in Stuttgart integrate touchscreen signage with CRM lead capture systems.
South Korea
KTX stations and Seoul Metro systems mandate sub-second latency passenger information displays with multilingual wayfinding. National smart city programs under the Ministry of Land, Infrastructure and Transport fund municipal procurement. Busan-Ulsan manufacturing clusters pilot containerized microservices for mixed hardware generation networks.
United Kingdom
London Underground and Heathrow Airport specifications emphasize 99.9 percent uptime SLAs for fault-tolerant display networks. Post-Brexit data residency requirements influence cloud provider selection for audience analytics. Media owners in Manchester and Birmingham adopt anonymized computer vision to preempt ICO enforcement actions.
India
Municipal corporations in Maharashtra and Karnataka tender for connected transit displays under national urban renewal programs. Bureau of Indian Standards certification requirements delay hardware-software bundle imports from Taiwan. Delhi-NCR corporate parks deploy cloud-native workplace communication networks as email alternatives.
Global Digital Signage Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the digital signage software stack. Hardware-integrated vendors maintain proprietary firmware layers while pure-play software houses emphasize cross-platform deployment flexibility. Three archetypes dominate: media player manufacturers with captive software stacks, cloud-native SaaS platforms with subscription pricing, and open-source middleware specialists serving budget-constrained education sectors. Consolidation pressure intensifies through strategic partnerships between analytics engine developers and network management platforms.
Within the hardware-integrated tier, BrightSign exemplifies tight firmware-to-management-layer coupling. Navori occupies a position among analytics-centric specialists targeting high-traffic transportation hubs. Xibo Signage anchors the open-source flexibility segment for customizable mid-market deployments. These three represent divergent strategic postures on vertical integration depth versus ecosystem openness.
| Leading Market Players |
|---|
| Xibo Signage |
| NowSignage |
| ScreenCloud |
| SpinetiX |
| Navori |
| Carousel |
| BrightSign |
| Mvix |
| NoviSign |
| Others |
Supply & Pricing Matrix
Captive hardware-software integration by BrightSign and SpinetiX anchors premium pricing power through proprietary firmware layers that resist commoditization, while pure-play SaaS vendors compete on subscription elasticity without silicon leverage.
Pricing Analysis
Uptime-guarantee pricing anchors enterprise contracts, with transportation authorities in Germany and South Korea paying premium rates for 99.9% SLA commitments on passenger information systems. Three-tier pricing structure across premium, standard, and economy levels separates analytics-enabled personalization engines from basic content-looping platforms. Pricing pressure stems from open-source alternatives like Xibo Signage compressing mid-market licensing fees. Franchise operators in emerging markets exhibit highest price sensitivity, deferring cloud migrations for perpetual on-premise licenses.
Supply Chain Analysis
India's Bureau of Indian Standards certification requirements and South Korea's smart city procurement rules are reshaping sourcing patterns for media player SoCs and display peripherals. Semiconductor fabrication concentrates in Taiwan and South Korea, with ARM-based processor designs feeding hardware-integrated software bundles. Memory modules, 4K display panels, and network interface controllers constitute critical input dependencies. Single-source vulnerability runs through TSMC's advanced node capacity for edge inference chips. Distribution runs through value-added resellers in the United States and systems integrators in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
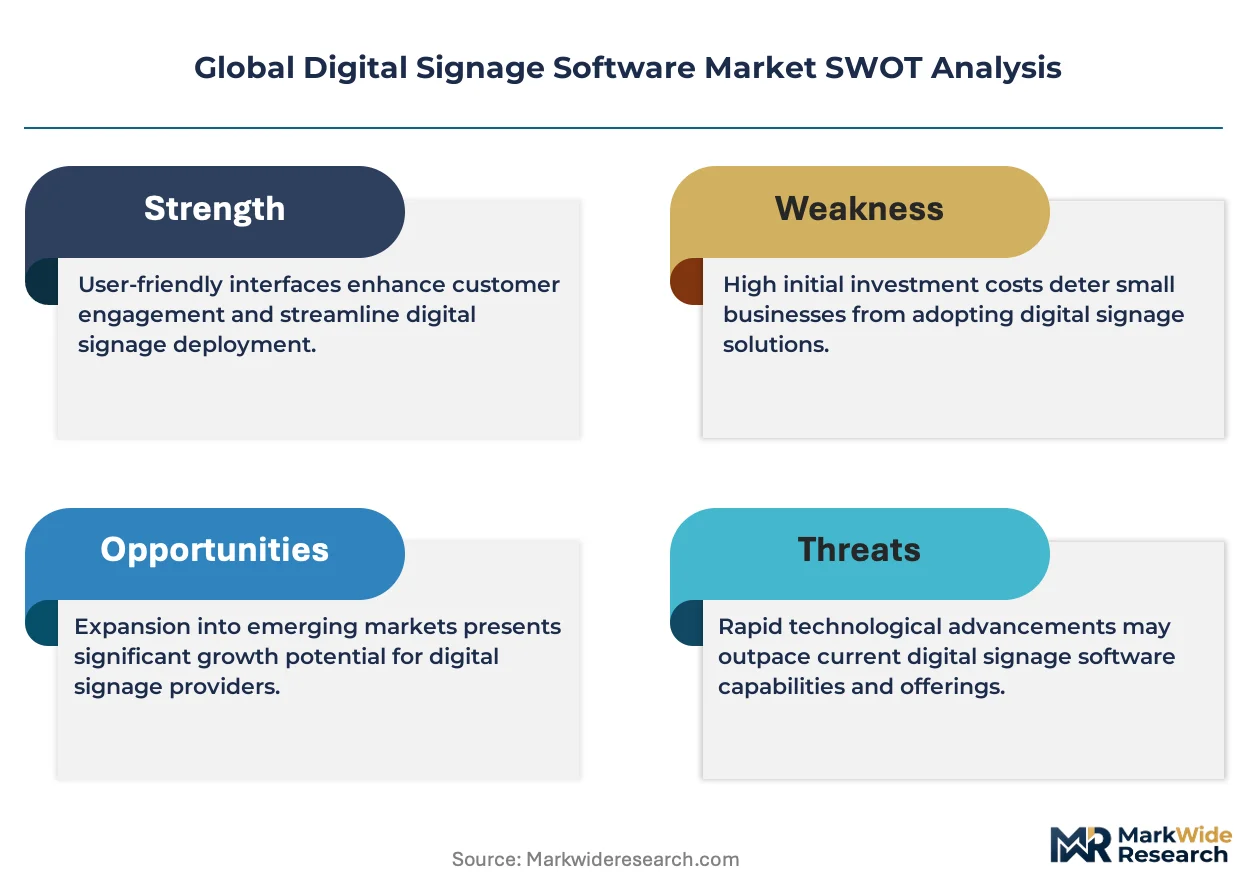
The EU AI Act and GDPR compliance burden creates a cost-of-entry moat that favors incumbent vendors with established anonymized computer vision pipelines and consent-management infrastructure.
For Market Incumbents: Hedge biometric analytics exposure by shipping facial detection disabled-by-default configurations that preempt CNIL enforcement actions. Consolidate edge computing engineering talent through targeted hiring in Seoul and Munich to defend against containerized microservices entrants. Prioritize backward integration into ARM-based media player design to sustain firmware-layer pricing power.
For New Entrants and Emerging Players: Capture workplace communication verticals in United States corporate campuses where email-centric stacks face displacement pressure. Target German vocational schools and United States community colleges with hosted open-source architectures that bypass capital expenditure barriers. Lead with workflow automation differentiation to bypass entrenched CMS incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in analytics engine developers with GDPR-compliant computer vision IP and proven transportation hub deployments. Long-term viability favors vendors with recurring revenue concentration above 60% and EU-sovereign cloud region presence. Watch 5G network slicing adoption by telecommunications carriers as inflection signal for broadcast-quality outdoor streaming demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies content management with edge analytics for Deutsche Bahn specifications. |
| Strategic Partnership | Aligns analytics vendors with 5G carriers for guaranteed bandwidth tiers. |
| Acquisition of Specialist Firm | Consolidates computer vision talent scarce in ARM optimization. |
| Geographic Expansion | Targets India municipal tenders under national urban renewal programs. |
| Product Launch | Introduces privacy-preserving modules with facial detection disabled by default. |
Research Methodology
Independent corroboration across CTOs at retail chains, IT procurement officers in transportation authorities, platform engineers at cloud-native vendors, and integration specialists at German systems integrators underwrites the qualitative findings. Secondary validation draws from SEC filings of publicly traded display technology firms, customs records of media player imports, Deutsche Bahn procurement specifications, and ECHA REACH substance restriction updates. Bottom-up deployment estimates triangulate against top-down software spend projections across the analysis window.
Rate-of-change decomposition separates volume expansion from value migration across deployment architecture, solution stack, end-user vertical, and functional use case dimensions. CAGRs derive from segment-level adoption curves weighted by procurement pipeline visibility in United States, Germany, and South Korea. HTML5 migration velocity and edge computing penetration serve as primary forecast inputs.
The model holds under stable regulatory enforcement intensity; deviation in GDPR interpretation strictness or EU AI Act implementation timelines would shift analytics module demand. Forecasts reflect documented assumptions on 5G infrastructure rollout pace and smart city funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Russian IT Software and Services Market
Software & Services
Geophysical Software Service Market
Software & Services
Global Ipad POS Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
Global Recipe Apps Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
Camera Tracking Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Simulation Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Casino Management Systems Market
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market