
 Washing Machine Market | 2026-2036
Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Washing Machine Market Intelligence
The bundling of smart washing machines with dryers and other connected home appliances is shifting consumer purchasing decisions toward integrated ecosystem solutions. Samsung Electronics leverages its broad consumer electronics portfolio to promote this connected home experience. Whirlpool Corporation sustains its market share by focusing on core laundry performance and reliability across its brands. Meanwhile, Haier Group Corporation competes on a global scale by offering a diverse product range that addresses multiple price segments.
A washing machine is an electromechanical appliance designed to clean textiles using water, detergent, and mechanical agitation from a rotating drum. Key performance parameters include load capacity, measured in kilograms, and spin cycle speed, measured in RPM. Fully automatic models continue to gain share over semi-automatic variants due to superior convenience. Within technology, inverter motors are becoming a standard feature for their energy efficiency and quiet operation, often differentiating premium from economy models.
Energy efficiency regulations are a primary influence on product design. The US Environmental Protection Agency's ENERGY STAR program and the European Union's Ecodesign directive set stringent standards for water and electricity consumption. These frameworks force manufacturers to innovate in areas like sensor technology and eco-wash cycles. Navigating the balance between advanced feature integration and compliance with evolving resource-efficiency mandates remains the central challenge for manufacturers.
Market Dynamics
The central tension in the washing machine market is the conflict between integrating advanced, power-intensive smart features and adhering to increasingly stringent global energy and water consumption mandates, such as the EU's Ecodesign directive and the US ENERGY STAR program.
Growth Catalysts
- Hospitality Sector Demand:Hotels and managed residential facilities require high-capacity, durable washing machines with rapid cycle times, driving sales of commercial-grade and premium residential models designed for high-throughput laundry operations.
- Urbanization in India:The expansion of the middle class and rapid urbanization in India are creating sustained demand for first-time purchases of automatic washing machines, shifting the market away from semi-automatic models.
- EU Green Deal:Ecodesign requirements under the EU Green Deal are compelling manufacturers to innovate in water and energy efficiency, creating a replacement cycle for older, less efficient appliances across the European Union.
Market Restraints
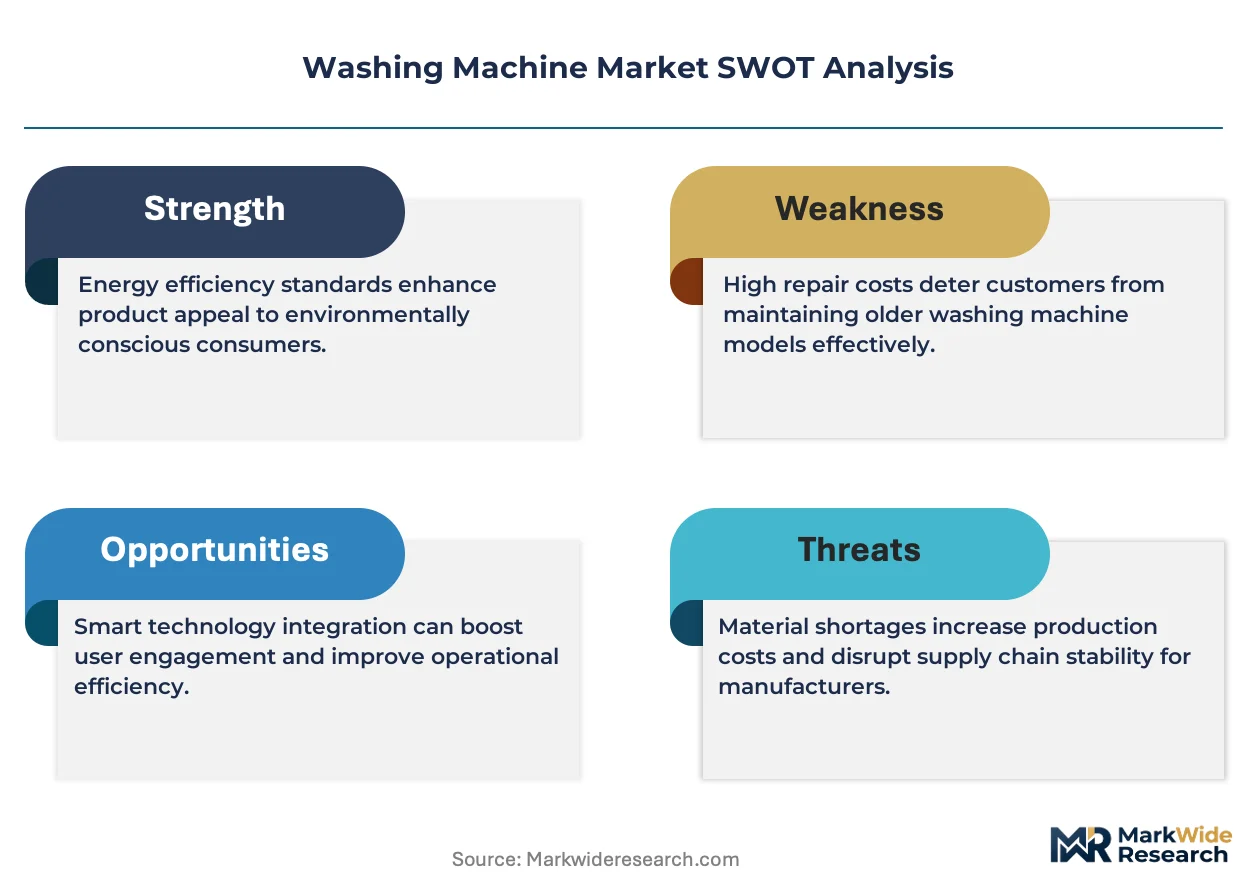
- Input Cost Volatility:Fluctuations in the prices of key raw materials, particularly steel for drums and chassis and semiconductors for control boards, create margin pressure and complicate production cost forecasting for manufacturers.
- Performance Trade-offs:Engineering designs face an inherent trade-off between achieving the ultra-low water and energy consumption figures required by regulations and delivering the fast wash cycles and high-temperature cleaning performance that consumers often prefer.
- On-Demand Service Substitution:The proliferation of app-based laundry services in dense urban centers presents a substitute for appliance ownership, particularly for younger consumers and renters who may defer or forgo a purchase.
Strategic Opportunities
- Emerging Market Penetration:Regions in Southeast Asia and Africa with rising disposable incomes and low household appliance penetration represent significant white-space opportunities for entry-level and mid-range automatic washing machines.
- AI-Powered Diagnostics:Integrating AI for predictive maintenance and fault diagnosis creates opportunities for new revenue streams through subscription-based monitoring services and optimized spare parts logistics for service technicians.
- Direct-to-Consumer Channels:Developing direct-to-consumer (DTC) sales models allows manufacturers to control the customer experience, capture higher margins, and bundle appliances with proprietary detergent subscriptions or extended warranty plans.
Industry Challenges
- Multi-Regional Compliance:Manufacturers face significant operational complexity and cost in designing and certifying products that comply with a fragmented and evolving landscape of energy efficiency labels and material standards across North America, Europe, and Asia.
- Software Development Talent:The shift toward smart, connected appliances requires a different talent pool, with manufacturers competing for skilled software engineers and data scientists to build out their connected home ecosystems and mobile applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Washing Machine Market |
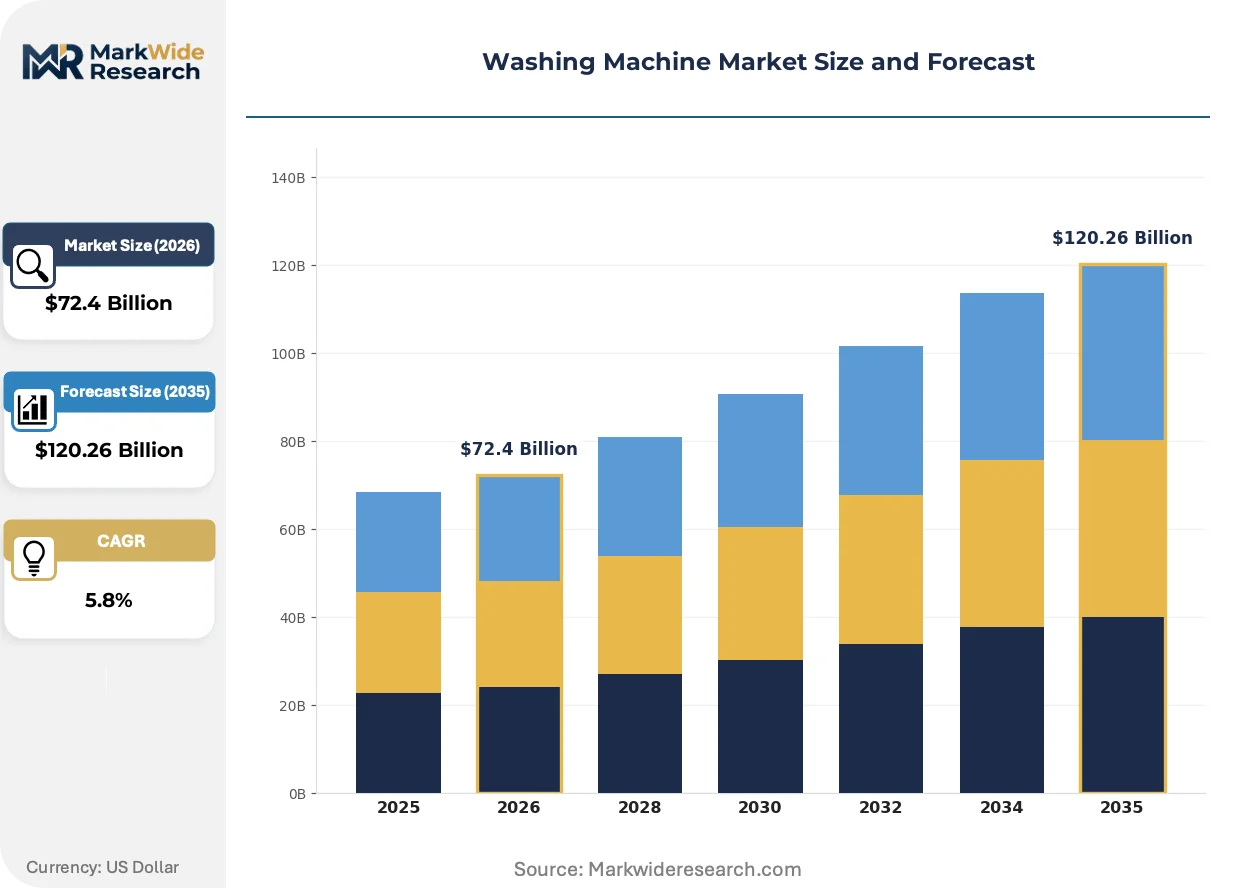
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $120.26 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Front Load, Top Load, Portable, Semi-Automatic, Fully Automatic Technology: Direct Drive, Inverter, Sensor Technology, Steam Cleaning, Eco Wash End User: Households, Laundry Services, Hospitality, Educational Institutions, Military Facilities Distribution Channel: Online Retailers, Specialty Stores, Hypermarkets, Appliance Dealers, Catalog Sales |
| Companies Covered | Samsung Electronics, LG Electronics Inc., Whirlpool Corporation, Haier Group Corporation, Electrolux AB, Panasonic Corporation, Robert Bosch GmbH, IFB Industries Limited, Godrej Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Washing Machine Market Strategic Shifts & Innovations
Product development is increasingly defined by the convergence of digital connectivity and resource efficiency. Innovations focus on automating the optimization of water, energy, and detergent use, while regulatory pressures simultaneously push for longer product lifespans and greater repairability across all market segments.
AI-powered sensor technology is a defining feature in new models, automatically detecting load size, fabric type, and soil levels. Premium and mid-tier consumer segments are adopting these smart features as a key differentiator for performance and convenience. This technology is integrating advanced diagnostics directly into the appliance, enabling predictive maintenance alerts that reduce appliance downtime and costly service interventions.
The European Union's "Right to Repair" framework is a significant regulatory shift impacting product engineering. This directive compels manufacturers to ensure the availability of spare parts for several years and to design appliances for easier disassembly and repair by independent technicians. The policy most affects the premium segment, where complex, integrated designs are now being re-evaluated to improve serviceability and extend the product's useful life.
Consumer purchasing behavior is evolving from standalone unit purchases toward integrated smart home ecosystems. This trend disrupts traditional big-box retail channels, which are optimized for single-appliance sales, in favor of bundled solutions offered directly by manufacturers or through smart home installers. This shift is most visible in new residential construction projects in North America and East Asia, where connected infrastructure is a standard offering.
Washing Machine Market Segmentation
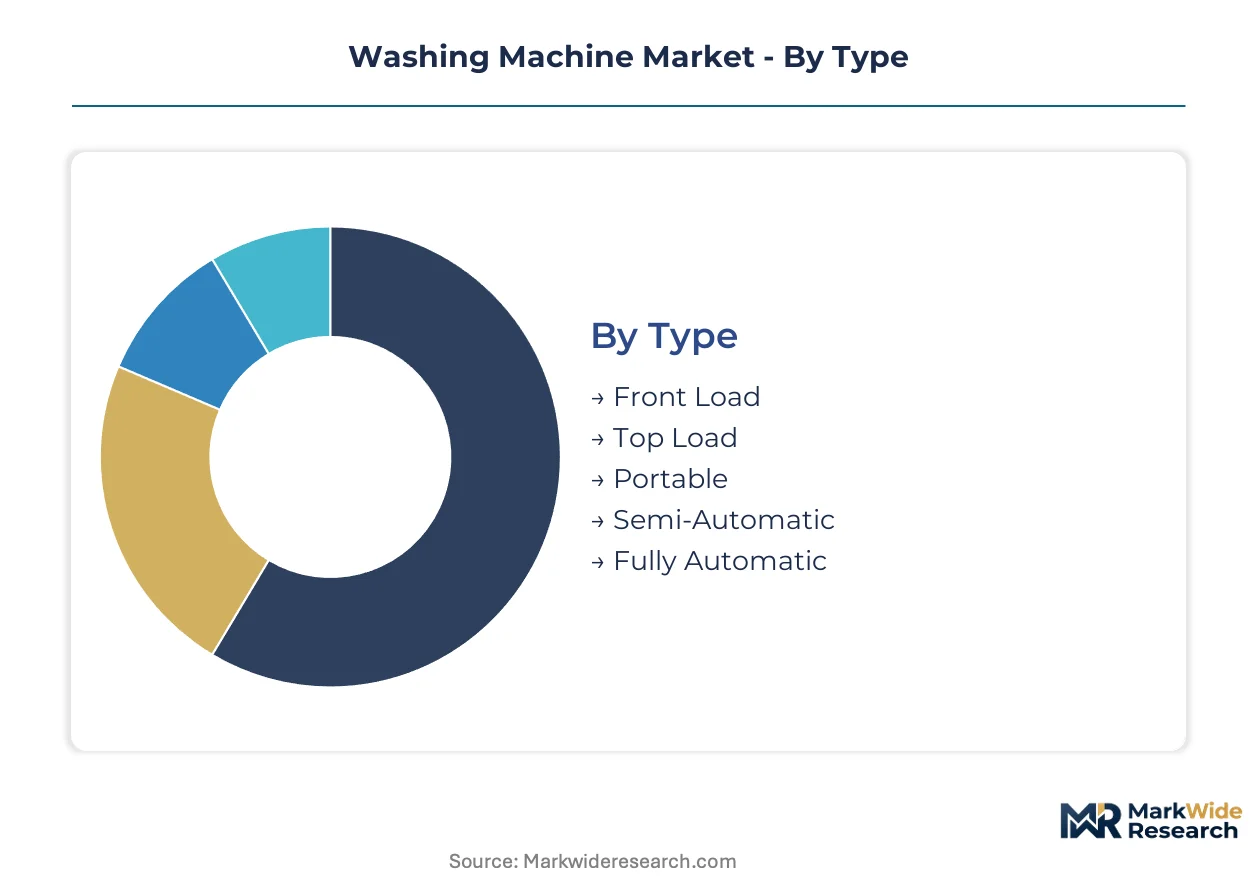
Understanding the distinct characteristics and evolving preferences across various washing machine segments is crucial for manufacturers to align product development with market demand. This granular analysis illuminates where investment in technology, capacity, and distribution channels yields the most significant returns. It also highlights the specific needs of different consumer groups and commercial entities.
Type:
Consumer preferences for convenience, space utilization, and resource efficiency significantly influence the selection of washing machine types.
- Fully Automatic:These models execute the entire wash cycle, including washing, rinsing, and spinning, without manual intervention. Their superior convenience drives strong demand in urban households in India and other emerging economies, particularly among the expanding middle class.
- Front Load:Characterized by a horizontal drum axis, front-load machines typically offer better water and energy efficiency due to lower water consumption and higher spin speeds. Demand concentrates in European markets, where stringent Ecodesign requirements favor their resource-saving capabilities.
- Top Load:These washing machines feature a vertical drum axis and are loaded from the top, often preferred for their ergonomic loading and shorter wash cycles. Many consumers in Southeast Asia and Latin America choose top-load models for their perceived durability and lower initial cost.
- Semi-Automatic:Requiring manual transfer of clothes between wash and spin tubs, semi-automatic machines offer a more economical entry point into mechanized laundry. These models maintain a presence in price-sensitive segments and rural areas.
- Portable:Compact and lightweight, portable washing machines are designed for small living spaces, renters, or as supplementary units. Their flexibility appeals to apartment dwellers and students.
Volume sits with Top Load models; growth tilts toward Fully Automatic variants.
Technology:
Performance enhancements and resource efficiency mandates shape the integration of advanced technologies within washing machines.
- Inverter:Inverter motors provide variable speed control, reducing energy consumption and noise levels compared to conventional motors. This technology is becoming a standard feature in premium and mid-tier models, differentiating them by operational efficiency.
- Sensor Technology:Integrated sensors automatically detect load size, fabric type, and soil levels to optimize water, detergent, and cycle duration. This innovation enhances washing performance and resource conservation, appealing to environmentally conscious consumers.
- Direct Drive:Direct drive motors connect directly to the wash drum, eliminating belts and pulleys, which reduces noise, vibration, and maintenance requirements. These systems offer enhanced durability and are often found in high-end appliances.
- Steam Cleaning:This technology uses steam to penetrate fabrics, loosening dirt and sanitizing clothes, often reducing the need for harsh chemicals. Steam cleaning features are gaining traction in the premium segment for their hygiene benefits.
- Eco Wash:Eco wash cycles are specifically designed to minimize water and energy consumption through optimized wash programs and lower temperatures. These features directly address regulatory compliance and consumer demand for sustainability.
Innovation in technology primarily focuses on improving energy consumption and water usage.
End User:
The diverse operational requirements and usage intensities of different customer types dictate specific washing machine features and durability standards.
- Households:This segment represents the largest volume, demanding a balance of capacity, convenience, and energy efficiency for daily personal laundry needs. Product development for households focuses on user-friendly interfaces and smart home integration.
- Hospitality:Hotels, resorts, and guesthouses require high-capacity, heavy-duty washing machines capable of continuous operation and rapid cycle times. Durability and efficiency are paramount for managing large volumes of linens and towels, driving sales of specialized commercial units.
- Laundry Services:Commercial laundromats and professional cleaning businesses utilize robust, industrial-grade machines designed for extreme durability and high throughput. These operators prioritize low running costs and minimal downtime.
- Educational Institutions:Universities and boarding schools often provide communal laundry facilities, requiring durable, semi-commercial washing machines that can withstand frequent use by multiple users. Vandalism resistance and ease of maintenance are important considerations.
- Military Facilities:Military bases and barracks need rugged, reliable washing machines that can operate in challenging environments and handle heavy-duty loads. Logistics and long-term serviceability are key purchasing criteria for these institutions.
Expanding demand from commercial sectors is driving product development for specialized use cases.
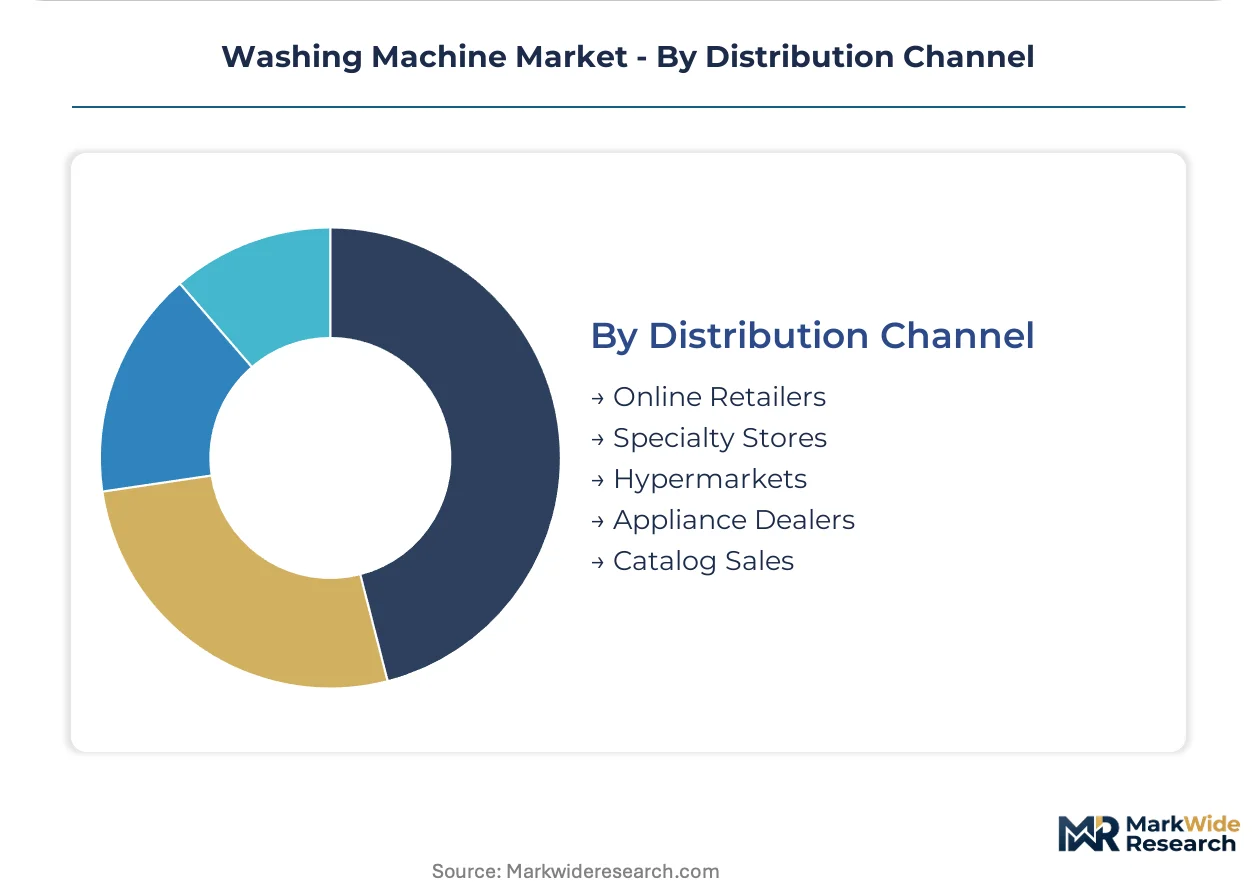
Distribution Channel:
Accessibility and consumer purchasing habits define the effectiveness of various distribution channels for washing machine sales.
- Online Retailers:E-commerce platforms offer extensive product catalogs, competitive pricing, and home delivery services, appealing to tech-savvy consumers seeking convenience. Bundled smart home appliance deals are often promoted through these channels.
- Specialty Stores:These outlets provide expert advice, personalized service, and often display a wider range of premium and advanced models. Consumers seeking specific features or high-end brands frequently visit specialty appliance dealers for informed purchases.
- Hypermarkets:Large retail chains offer a broad selection of washing machines alongside other household goods, attracting budget-conscious consumers through promotional offers. These stores serve as a convenient one-stop shopping destination for many.
- Appliance Dealers:Independent and chain appliance stores focus exclusively on home appliances, providing installation, maintenance, and repair services. These dealers cater to consumers who value comprehensive after-sales support.
- Catalog Sales:While declining in prominence, catalog sales still reach niche demographics, particularly in remote areas or for consumers preferring a traditional browsing experience. This channel often features a curated selection of popular models.
The retail landscape for appliances is shifting towards digital platforms and direct manufacturer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced manufacturing zones and technology parks are driving the concentration of washing machine production and innovation across several key geographies. These hubs foster collaboration between component suppliers and appliance manufacturers, accelerating product development cycles. Regulatory frameworks also play a substantial role in shaping regional market dynamics and consumer demand.
United States
Demand for smart, connected washing machines and high-efficiency models drives purchases in the United States. The US Environmental Protection Agency's ENERGY STAR program influences product design, promoting water and energy conservation. Technology integration centers in Silicon Valley and other tech hubs contribute to advancements in appliance connectivity and AI diagnostics.
Germany
Germany exhibits strong demand for premium, durable, and resource-efficient washing machines, aligning with consumer preferences for quality. The EU Green Deal's Ecodesign requirements compel manufacturers to prioritize energy and water efficiency in their product offerings. Major engineering and manufacturing clusters in Baden-Württemberg and Bavaria focus on precision components and advanced motor technologies.
India
Rapid urbanization and a growing middle class are fueling demand for fully automatic washing machines in India. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for appliances, influencing local manufacturing. Production facilities and electronics clusters in Maharashtra and Tamil Nadu are expanding to meet the increasing domestic market needs.
China
China's washing machine market is characterized by a diverse product range across multiple price segments and a strong e-commerce presence. National GB standards dictate product performance and safety specifications for all appliances sold domestically. The Yangtze River Delta region, including cities like Shanghai and Hangzhou, hosts significant manufacturing bases and R&D centers for white goods.
South Korea
South Korea exhibits a preference for technologically advanced washing machines, often integrated into broader smart home ecosystems. The Korean Energy Labeling Program guides consumer choices and encourages manufacturers to develop highly efficient models. The Seoul Capital Area remains a hub for consumer electronics R&D, driving innovation in smart appliance features.
Washing Machine Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in the washing machine industry. The market structure exhibits a tiered consolidation, with a few global players dominating the premium and mid-range segments, while regional manufacturers cater to specific local needs. Strategic archetypes include consumer electronics giants leveraging ecosystem integration, dedicated appliance manufacturers emphasizing core performance, and multi-segment players competing on price and feature diversity. Portfolio diversification and geographic expansion are dominant competitive moves.
Among the global consumer electronics conglomerates, Samsung Electronics exemplifies leveraging a broad product portfolio to promote integrated smart home experiences. Whirlpool Corporation represents a focused appliance specialist, sustaining its market share by emphasizing core laundry performance and reliability across its brands. Haier Group Corporation sits within the multi-segment player archetype, competing on a global scale by offering a diverse product range that addresses multiple price segments.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics Inc. |
| Whirlpool Corporation |
| Haier Group Corporation |
| Electrolux AB |
| Panasonic Corporation |
| Robert Bosch GmbH |
| IFB Industries Limited |
| Godrej Group |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's Ecodesign requirements gate qualified supply and premium-tier pricing access for washing machine manufacturers. This regulatory pressure directly impacts product development costs and influences consumer willingness to pay for resource-efficient models.
Pricing Analysis
Margin tightening across mid-tier and economy segments reflects intense competition and rising input costs. The dominant pricing structure remains transactional, with premium-mid-economy pricing differentiation based on energy efficiency ratings and smart features. Brand premium and after-sales service also drive price differentiation. Pricing pressure intensifies as manufacturers absorb fluctuating raw material costs for steel and semiconductors. Consumers in emerging markets, particularly for semi-automatic and top-load models, exhibit the highest price sensitivity, while premium segment buyers prioritize advanced features and efficiency.
Supply Chain Analysis
Online retail platforms and direct-to-consumer channels increasingly define downstream distribution for washing machines. Geographic supply concentration centers on manufacturing hubs in China, South Korea, and Germany. The supply chain relies heavily on raw materials like steel for drums and semiconductors for control boards. Input cost volatility presents a significant structural risk for manufacturers. Multi-regional compliance with diverse energy efficiency labels and material standards also adds operational complexity and cost across the supply chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The washing machine market is largely a consolidation play, with escalating regulatory compliance costs forcing weaker players out. This environment favors established manufacturers with robust R&D capabilities and diversified product portfolios.
For Market Incumbents: Acquire software development talent to enhance smart home ecosystem integration and AI-powered diagnostic capabilities. This strengthens competitive positioning against the proliferation of app-based laundry services and addresses the need for advanced features. Invest in modular design principles to meet evolving "Right to Repair" mandates and extend product lifecycles, leveraging R&D in materials science for greater durability.
For New Entrants and Emerging Players: Enter via niche segments focusing on specialized commercial units or highly repairable, entry-level automatic machines for emerging markets. Southeast Asia and Africa represent significant white-space opportunities due to rising disposable incomes and low appliance penetration. A compelling go-to-market angle involves offering appliances with extended warranty plans or subscription-based maintenance services, emphasizing long-term value over initial cost.
For Investors and Strategic Acquirers: Increased consumer adoption rates of smart home ecosystems are the leading indicator that connected appliance manufacturers offer long-term viability. Target acquisition archetypes include specialized technology providers in AI diagnostics or regional manufacturers with strong distribution networks in high-growth emerging markets. Watch for significant regulatory shifts in resource efficiency and repairability as key inflection signals for future investment strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Development Investment | Enhances smart home integration and AI-powered diagnostics for appliances. |
| Direct-to-Consumer Channel Expansion | Captures higher margins and strengthens customer relationships for manufacturers. |
| Eco-Design Compliance & Innovation | Addresses stringent EU Ecodesign requirements and consumer demand for efficiency. |
| Emerging Market Distribution Partnerships | Expands access to new consumer bases in Southeast Asia and Africa. |
| Modular Product Design Implementation | Facilitates easier repairs and extends product lifespan under "Right to Repair" policies. |
Research Approach
Document review covered regulatory body publications, industry association reports, and financial filings, complemented by interviews with appliance engineers, retail buyers, supply chain managers, and smart home integrators. This approach integrated both primary insights and secondary validation. The analysis utilized both bottom-up and top-down triangulation to ensure comprehensive market sizing and segmentation across all dimensions.
Historical data was cross-referenced against expert panel input to construct the forecast framework across the analysis window. The quantitative model segmented the market by Type, Technology, End User, Distribution Channel, and regional economic indicators. Compound annual growth rates were derived from a blend of historical performance and projected shifts in consumer behavior and technological adoption, incorporating urbanization rates and disposable income growth as key inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme raw material price fluctuations or unforeseen regulatory shifts. All forecasts reflect assumptions regarding technological advancements and market dynamics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Residential Dishwashers Market
Home Appliances
Residential Washing Machine Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
United States Household Refrigerators Market