
 Rain Apparel Market | 2026-2036
Rain Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Rain Apparel Market Analysis
Asset-light licensing and contract manufacturing is reshaping how mid-tier brands enter technical rain apparel without owning production facilities. Columbia Sportswear Company leverages its captive sourcing network across Asia to sustain margin stability. Patagonia, Inc. anchors its market position through transparent supply chain standards that differentiate its premium outerwear line. Arc'teryx specializes in alpine-grade construction techniques that dominate the high-performance segment.
Rain apparel encompasses garments engineered with waterproof-breathable membranes, seam-sealed construction, and durable water repellent (DWR) finishes to protect wearers from precipitation while managing perspiration vapor. These products serve commercial purposes spanning occupational safety compliance, recreational performance, and everyday urban mobility. Jackets command the largest revenue pool due to year-round versatility across climates and use cases. Gore-Tex membrane laminates occupy the premium tier where technical specifications justify higher price positioning. The unisex category is gaining traction as brands streamline sizing and neutral aesthetics to reduce inventory complexity.
REACH in Europe restricts perfluorinated compounds in DWR treatments, forcing reformulation of waterproof coatings across supply chains. The EU Green Deal's textile sustainability requirements are accelerating demand for recycled polyester and bluesign-certified nylon inputs. China's GB standards and MIIT technical regulations govern domestic waterproof performance testing protocols that affect import eligibility. Stakeholders must monitor evolving chemical compliance thresholds and material certification timelines to avoid stranded inventory positions.
Market Dynamics
Waterproof-breathable membrane chemistry is undergoing forced reformulation as perfluorinated compound restrictions tighten across major jurisdictions, compressing legacy supply chains while opening pathways for bio-based alternatives.
Growth Catalysts
- EU Green Deal textile sustainability mandates:Recycled polyester and bluesign-certified nylon inputs gain preferential procurement status across European retail channels, pulling material innovation investment toward circular feedstocks.
- Adventure tourism participation:Outdoor enthusiasts require alpine-grade construction for extended backcountry exposure, expanding addressable demand for technical rain shells beyond traditional occupational users.
- China's MIIT technical regulations:Domestic waterproof performance testing protocols for GB standards certification enable Chinese brands to displace import-dependent positioning with scaled technical manufacturing.
Market Restraints
- Fluoropolymer feedstock volatility:Perfluorinated compound phase-outs under REACH force DWR coating reformulation, raising R&D amortization costs for membrane laminators dependent on legacy chemistry.
- East Asian membrane concentration:Gore-Tex and comparable ePTFE laminate production clusters in Japan and Taiwan create single-source vulnerability for brands without captive alternative suppliers.
- Mechanical stretch limitations:Current waterproof-breathable laminates sacrifice elasticity for hydrostatic resistance, constraining adoption in climbing and yoga-adjacent outdoor categories where mobility is paramount.
Strategic Opportunities
- India's outdoor retail underpenetration:Himalayan trekking infrastructure expansion and domestic e-commerce fulfillment improvements create first-mover positioning for technical rain apparel distribution.
- Biomimetic membrane convergence:Integration of plant-derived polymers with electrospun nanofiber architectures enables PFAS-free waterproofing at performance parity, unlocking premium pricing for sustainability-verified products.
- Direct-to-consumer repair channels:Post-purchase DWR reapplication and seam-sealing services extend garment lifecycles while capturing recurring revenue from installed base ownership.
Industry Challenges
- Bluesign certification timeline compression:Chemical facility audits and supply chain disclosure requirements strain mid-tier manufacturers lacking dedicated compliance infrastructure.
- Seam-sealing technician scarcity:Precision taping operations for 3-layer laminate construction require skilled labor pools concentrated in Vietnam and Bangladesh, constraining capacity scaling.
- Legacy inventory stranding:REACH-compliant reformulation deadlines create write-down exposure for distributors holding pre-transition DWR-treated stock in European warehouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rain Apparel Market |
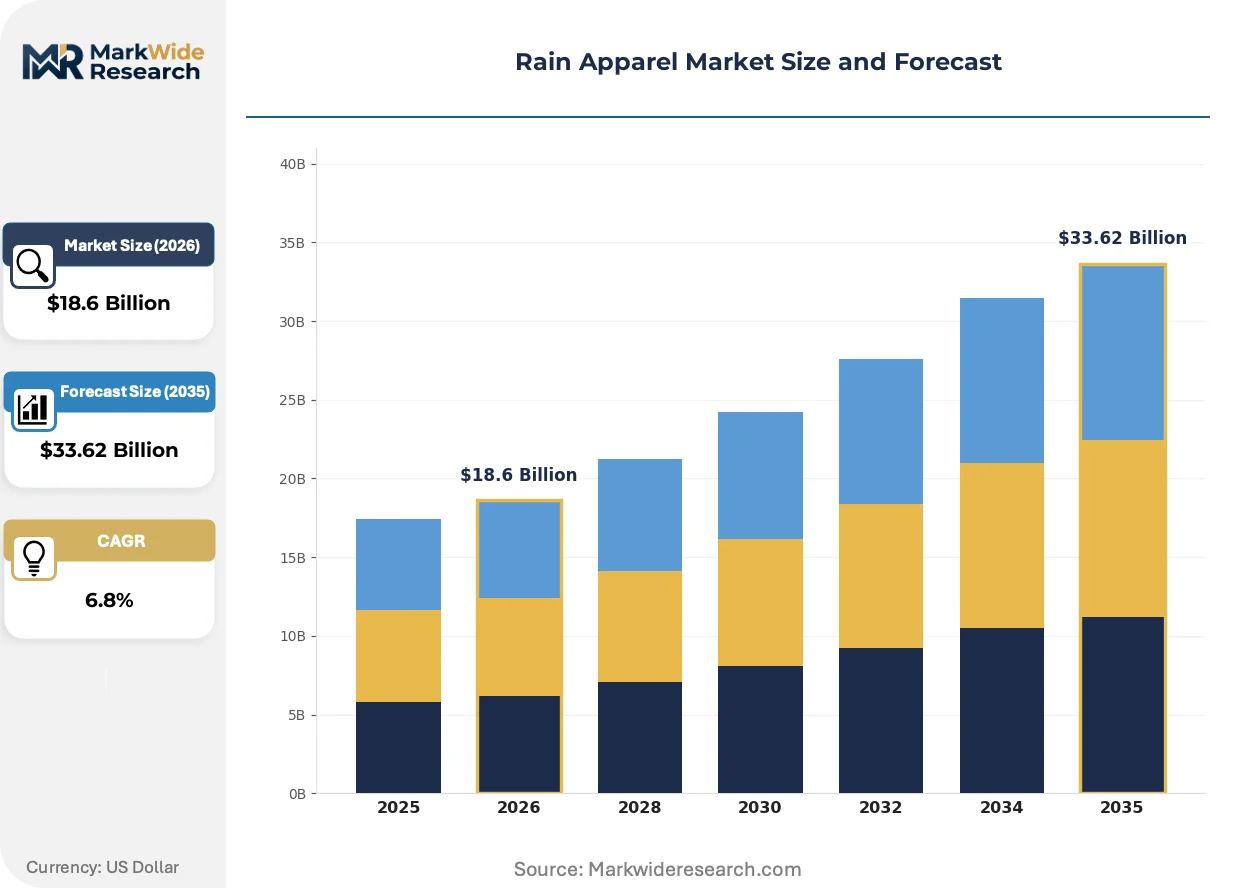
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Coats, Ponchos, Trousers Material: Polyester, Nylon, Gore-Tex, Rubber Gender: Men, Women, Unisex, Kids End User: Outdoor Enthusiasts, Casual Wearers, Athletes, Workers |
| Companies Covered | Columbia Sportswear Company, Patagonia, Inc., The North Face, Arc'teryx, Marmot Mountain, LLC, Outdoor Research, Ducktail Rainwear, Wildcraft India Private Limited, Nike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rain Apparel Market Emerging Trajectories
Membrane chemistry, regulatory compliance architecture, and ownership models are simultaneously transforming how waterproof-breathable garments reach end users and retain value through extended use cycles.
Electrospun polyurethane nanofiber membranes are migrating from laboratory-scale production to commercial outdoor apparel lines, offering equivalent breathability ratings to expanded polytetrafluoroethylene laminates without fluorinated chemistry. Specialty running and cycling brands in Germany and Switzerland are piloting these materials for high-exertion scenarios. This technology is migrating from niche alpine applications toward mass-market urban commuter jackets, compressing the historical premium commanded by Gore-Tex-dominated supply tiers.
REACH Annex XVII restrictions on perfluorinated substances in DWR treatments are forcing reformulation of durable water repellent coatings across European supply chains. Membrane laminators must resubmit chemical safety dossiers to ECHA for revised substance classifications. Jacket manufacturers serving the EU market are accelerating partnerships with bio-based coating developers to maintain import eligibility under tightened disclosure thresholds.
Corporate and institutional buyers are consolidating rain apparel procurement through rental and subscription platforms for seasonal workforce deployment. Construction, utilities, and municipal outdoor services in Scandinavia are displacing traditional uniform purchase models with circular service contracts including maintenance and end-of-life recovery. This behavior is most visible in Norway and Sweden where extended producer responsibility frameworks for textiles have activated ahead of broader EU implementation timelines.
Rain Apparel Market Segmentation
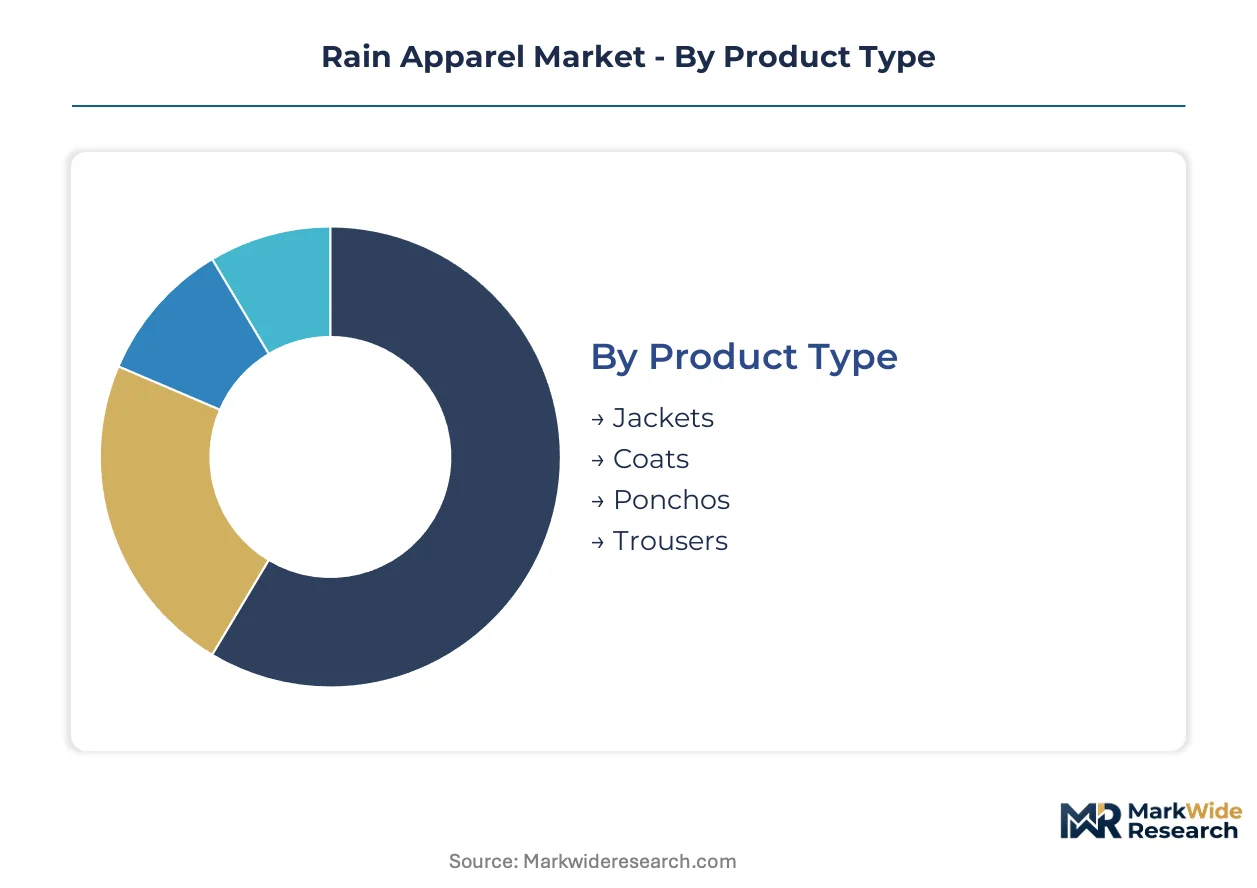
Rain apparel segmentation reveals distinct service intensity patterns across product categories. Material selection drives membrane maintenance schedules, while end-use determines warranty complexity and repair frequency.
Product Type:
After-sales service intensity varies sharply across garment architectures, with layered construction demanding specialized re-waterproofing protocols.
- Jackets:Three-layer laminate shells with seam-taped construction require periodic DWR reapplication and delamination inspection. Outdoor enthusiasts in alpine regions drive replacement cycles tied to membrane degradation rather than fashion turnover.
- Coats:Insulated waterproof parkas combine thermal fill with breathable membranes, creating dual-service pathways for both weatherproofing and loft restoration. Scandinavian municipal procurement channels favor extended-service contracts for occupational deployments.
- Ponchos:Single-sheet PVC or coated polyester designs minimize maintenance overhead through disposable economics. Emergency services and festival organizers in India favor bulk procurement with minimal lifecycle management.
- Trousers:Articulated knee construction and ankle zippers introduce failure points requiring specialized repair infrastructure. Forestry and utilities sectors in Germany specify reinforced seat panels with replacement guarantee terms.
Jackets hold the largest share; momentum sits with trousers as occupational safety mandates expand.
Material:
Cost tier stratification separates feedstock categories by certification burden and chemical compliance amortization.
- Polyester:Recycled PET feedstocks dominate mass-market production with bluesign certification becoming baseline for EU retail placement. Chinese manufacturers leverage scaled recycling infrastructure to compress unit economics.
- Nylon:High-tenacity yarns deliver abrasion resistance for climbing and cycling applications where mechanical stress exceeds hydrostatic pressure requirements. Japanese textile mills anchor premium supply tiers with proprietary spinning technology.
- Gore-Tex:Expanded PTFE membranes maintain performance leadership in extended backcountry exposure scenarios. Alpine rescue services and Himalayan expedition operators specify ePTFE laminates despite reformulation pressures under REACH.
- Rubber:Neoprene and natural latex compounds serve industrial chemical resistance applications outside breathable performance parameters. Fisheries and chemical processing facilities in Norway specify vulcanized constructions with replaceable cuff systems.
Polyester commands volume leadership; Gore-Tex faces substitution pressure fastest as bio-based alternatives achieve performance parity.
Gender:
Customer type differentiation is compressing as unisex sizing reduces inventory fragmentation for direct-to-consumer channels.
- Men:Traditional outdoor retail skews male in technical alpine categories with standardized sizing matrices simplifying e-commerce fulfillment. Japanese and Korean domestic brands target this demographic with city-commuter hybrids.
- Women:Specialized fit blocks address hip-to-waist ratio variation in performance shells, though unisex alternatives gain traction in trail running and cycling crossover segments. European specialty retailers maintain dedicated buy plans for female-specific alpine construction.
- Unisex:Streamlined sizing grids and neutral aesthetics reduce SKU complexity for brands pivoting toward rental and subscription ownership models. Scandinavian circular service platforms specify unisex grading to maximize garment utilization rates.
- Kids:Growth-accommodating features and reinforced knee panels address accelerated wear patterns in school and recreational use. Chinese domestic brands scale production for this segment through integrated textile-to-garment facilities.
Men's retains the largest installed base; unisex is climbing the fastest as inventory efficiency priorities reshape brand architecture.
End User:
Application context determines membrane specification, with occupational deployments demanding certified compliance documentation absent from recreational use.
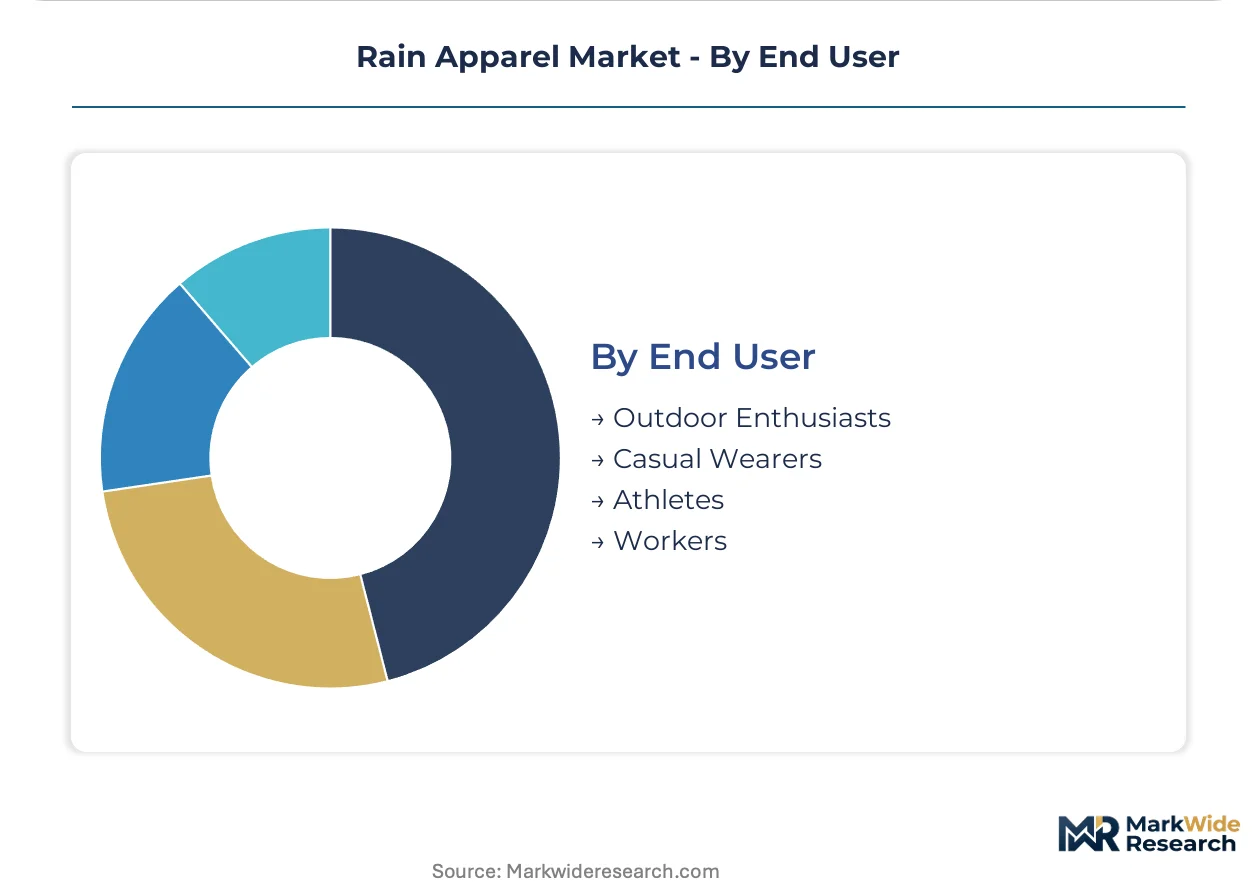
- Outdoor Enthusiasts:Extended backcountry exposure drives demand for alpine-grade construction with repairable design features. Adventure tourism infrastructure expansion across Nepal and Bhutan pulls technical shell procurement toward local distribution partnerships.
- Casual Wearers:Urban mobility scenarios prioritize packability and aesthetic versatility over hydrostatic head ratings. German and Swiss cycling-commuter demographics favor breathable softshell hybrids with reflective detailing.
- Athletes:High-exertion output demands maximum moisture vapor transmission rates, favoring air-permeable constructions over absolute waterproofing. Trail running brands in Colorado and Chamonix pilot electrospun nanofiber membranes for this segment.
- Workers:Safety compliance mandates specify visibility standards and chemical resistance certifications with documented inspection protocols. UK rail infrastructure and Netherlands offshore wind maintenance contractors specify EN-certified garments with centralized procurement oversight.
Outdoor enthusiasts represent the largest addressable spend; workers are expanding most quickly as industrial safety regulations tighten across European jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal textile sustainability mandates and China's MIIT technical regulations are redirecting investment flows toward compliant manufacturing clusters across four distinct national markets.
United States
Adventure tourism infrastructure expansion across Colorado and the Pacific Northwest sustains demand for alpine-grade construction. EPA oversight of perfluorinated substance discharge limits affects DWR coating facilities in North Carolina. Seattle and Portland anchor technical apparel design clusters where electrospun nanofiber development accelerates.
Germany
REACH Annex XVII enforcement tightens chemical disclosure thresholds for membrane laminators serving European retail channels. ECHA substance classification reviews compress reformulation timelines for waterproof coating developers. Bavaria's textile engineering corridor concentrates bluesign-certified facility audits and supply chain verification services.
China
Domestic brands scale technical manufacturing capacity to displace import-dependent positioning in waterproof performance apparel. MIIT GB standards certification governs hydrostatic head testing protocols for domestic market eligibility. Guangdong and Zhejiang provinces host integrated textile-to-garment facilities capturing unisex segment volume.
Japan
METI circular economy roadmaps accelerate demand for garment repair and DWR reapplication services. JIS standards for waterproof-breathable performance maintain rigorous certification barriers for membrane suppliers. Osaka and Nagoya metropolitan areas concentrate ePTFE laminate production expertise for premium outdoor brands.
India
Himalayan trekking infrastructure expansion creates distribution opportunities for technical rain shell procurement. BIS technical regulations for protective clothing compliance affect import eligibility for occupational safety garments. Maharashtra and Karnataka states develop domestic e-commerce fulfillment networks for outdoor retail penetration.
Rain Apparel Market Vendor Landscape
On the supply side, the industry is bifurcated between captive membrane technology holders and contract-dependent apparel assemblers. Gore-Tex and comparable ePTFE patent estates create tiered access to premium waterproof-breathable specifications. Three strategic archetypes dominate: integrated membrane-to-garment operators, licensed brand marketers, and pure-play manufacturing contractors. Capacity expansion and strategic licensing agreements represent the primary competitive moves reshaping market access.
Within the integrated membrane-to-garment tier, Columbia Sportswear Company and Patagonia, Inc. exemplify divergent sourcing philosophies. Arc'teryx occupies a position representing alpine-grade construction specialization. These three entities collectively illustrate how supply chain transparency standards, captive Asian sourcing networks, and technical performance positioning differentiate competitive positioning across price tiers.
| Leading Market Players |
|---|
| Columbia Sportswear Company |
| Patagonia, Inc. |
| The North Face |
| Arc'teryx |
| Marmot Mountain, LLC |
| Outdoor Research |
| Ducktail Rainwear |
| Wildcraft India Private Limited |
| Nike |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Vietnamese seam-sealing operations compresses contractor margins while concentrating bargaining power with membrane laminators holding captive chemistry access. This utilization asymmetry forces mid-tier brands toward asset-light licensing models and accelerates price divergence between certified and uncertified supply tiers.
Pricing Analysis
Certification level creates the primary spread between supply tiers, with bluesign-certified laminates commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium Gore-Tex laminates, standard PU membranes, and economy PVC coatings reflects this compliance gradient. Price erosion runs through the standard tier as Chinese manufacturers scale recycled polyester integration. Workers segment exhibits highest price sensitivity due to procurement consolidation, while outdoor enthusiasts accept premium positioning for repairable alpine-grade construction.
Supply Chain Analysis
Extended payment terms from European retail buyers strain working capital for Bangladeshi and Vietnamese assembly contractors. Geographic concentration centers on China for membrane lamination, Vietnam for precision seam-sealing, and Japan for ePTFE production expertise. Raw material dependencies include fluoropolymer feedstocks for DWR coatings, recycled PET chips for shell fabrics, and thermoplastic polyurethane for adhesive tapes. Single-source vulnerability pervades the ePTFE membrane tier. Distribution runs through specialty outdoor retail, direct-to-consumer channels, and emerging circular service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of skilled seam-sealing technicians constrains capacity scaling and creates defensive moats for incumbent operators with established training pipelines. This bottleneck justifies capability-building investments ahead of demand inflection.
For Market Incumbents: Entrench membrane chemistry leadership through backward integration into bio-based coating development before REACH deadlines strand legacy inventory. Secure captive seam-sealing capacity in Vietnam through long-term technician training partnerships. Prioritize circular service infrastructure to capture recurring revenue from garment lifecycle extension. For New Entrants and Emerging Players: Establish a beachhead in India's Himalayan trekking corridor where technical shell penetration remains nascent and domestic e-commerce fulfillment is improving. Target the unisex segment with streamlined sizing to reduce inventory complexity for direct-to-consumer launch. Partner with European rental platforms to bypass traditional retail gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biomimetic membrane development as electrospun nanofiber production scales from laboratory to commercial lines. Long-term viability favors operators with integrated textile-to-garment capabilities and established regulatory compliance infrastructure. Monitor bluesign certification timeline compression as an inflection signal for mid-tier manufacturer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Biomimetic Membrane Scale-Up | Electrospun nanofiber commercialization unlocks PFAS-free premium positioning under REACH constraints. |
| Circular Service Platform Launch | Scandinavian extended producer responsibility frameworks pull rental and repair revenue models ahead of EU adoption. |
| Backward Integration into Coating Chemistry | In-house DWR formulation secures supply continuity as ECHA substance reviews accelerate reformulation cycles. |
| Direct-to-Consumer Repair Channel | Post-purchase DWR reapplication captures recurring revenue from installed base ownership in outdoor enthusiast segment. |
| GB Standards Certification Investment | MIIT compliance enables Chinese brands to displace import-dependent positioning in domestic technical apparel. |
Methodological Framework
Cross-validation between primary interviews with membrane laminators, brand sourcing directors, and specialty retail buyers anchors the qualitative findings against secondary trade data and regulatory filings. Bottom-up triangulation incorporates customs records from Vietnamese and Bangladeshi export authorities, ECHA substance classification databases, and MIIT technical standard publications. Top-down calibration draws from outdoor industry association membership data and circular service platform transaction disclosures.
Calibration against historical capacity utilization rates in Vietnamese seam-sealing clusters and Chinese membrane lamination facilities refines volume assumptions across the analysis window. Segmentation dimensions modeled include product architecture, material certification tier, end-use application, and gender category. CAGRs derive from elasticity-adjusted demand curves incorporating adventure tourism participation indices and occupational safety mandate implementation timelines. Electrospun nanofiber adoption rates and REACH compliance cost amortization schedules serve as industry-specific forecast inputs.
Stress conditions across fluoropolymer feedstock availability, seam-sealing technician wage inflation, and European retail inventory destocking were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and substitution technology performance parity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Hosiery Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Rolle Market
Apparel Textiles
Japan Denim Jeans Market