
 Europe Textile Garment Market | 2026-2036
Europe Textile Garment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Textile Garment Market Foresight
Asset-light manufacturing partnerships and third-party production financing is reshaping competitive entry in the Europe textile garment sector. Lenzing AG leverages its wood-based cellulosic fiber technology to anchor sustainable material supply for premium European brands. Sioen Industries dominates technical textile applications with flame-retardant and high-visibility fabrics for industrial end-uses. Aquafil S.p.A. specializes in ECONYL regenerated nylon, positioning closed-loop material systems at the center of circular garment production.
Textile garments encompass finished apparel constructed from woven, knitted, or non-woven fabrics, typically requiring seam sealing, dye fixation, and finishing treatments to achieve specified durability and dimensional stability standards. The primary commercial purpose centers on body covering, environmental protection, and social signaling across consumer and professional contexts. Cotton and wool materials sustain heritage positioning and thermal performance premiums in European outerwear and formal segments. Polyester competes on cost-efficiency and blend versatility across fast-fashion and athletic applications. Online distribution channels are capturing incremental volume as direct-to-consumer platforms reduce intermediary margins and accelerate trend responsiveness.
REACH chemicals regulation and the EU Green Deal textile strategy constrain conventional dye chemistry and mandate fiber-to-fiber recyclability benchmarks, redirecting R&D investment toward bio-based alternatives and mechanical recycling infrastructure. ECHA substance restrictions on per- and polyfluoroalkyl substances are eliminating water-repellent finishes from multiple garment categories, forcing reformulation across Schoeller Textil AG's functional fabric portfolio. Stakeholders must monitor enforcement timelines for extended producer responsibility schemes and calibrate material sourcing decisions against emerging eco-modulated fee structures.
Market Dynamics
EU Green Deal textile mandates are forcing fiber-to-fiber recyclability benchmarks across European supply chains, redirecting capital from conventional dye chemistry toward bio-based alternatives and mechanical recycling infrastructure.
Growth Catalysts
- REACH chemical compliance:ECHA substance restrictions on per- and polyfluoroalkyl substances are eliminating toxic water-repellent finishes, creating certified demand for reformulated functional fabrics in outdoor and workwear segments.
- Milan-Como manufacturing concentration:Italy's heritage luxury clusters sustain premium positioning through artisanal finishing capabilities that command price premiums from French and German luxury houses.
- Wood-based cellulosic fibers:Lenzing AG's TENCEL lyocell production is anchoring sustainable material supply for premium European brands seeking biodegradable alternatives to petroleum-based synthetics.
Market Restraints
- Petrochemical input volatility:Polyester feedstock costs fluctuate with crude oil and purified terephthalic acid spot markets, compressing margins for fast-fashion producers dependent on synthetic blend fabrics.
- Single-source technical textile concentration:Sioen Industries dominates flame-retardant industrial fabric supply, creating procurement risk for safety garment manufacturers during capacity constraints.
- Mechanical recycling yield limits:Fiber-to-fiber mechanical recycling degrades tensile strength after three cycles, capping circular material volumes below EU Green Deal targets without chemical recycling scale-up.
Strategic Opportunities
- Poland-Czechia nearshoring:Central European manufacturing zones offer 15-20% labor cost advantages against Italian production with equivalent EU regulatory compliance and shorter lead times to German retail markets.
- Direct-to-consumer platform expansion:Athletic apparel brands are bypassing wholesale intermediaries through proprietary e-commerce, capturing full margin and real-time demand signals from Nordic and Benelux consumers.
- Extended producer responsibility schemes:France's AGEC law and pending EU-wide EPR implementation create fee-modulated incentives for design-for-recycling investments and take-back infrastructure development.
Industry Challenges
- Dye chemist talent scarcity:REACH-compliant bio-based dye formulation requires specialized polymer chemistry expertise concentrated in Swiss and German technical universities, with insufficient graduate pipeline for industry demand.
- Legacy ERP integration friction:Material traceability systems for EPR compliance must interface with decades-old textile mill production planning software, delaying real-time carbon footprint reporting.
- Multi-certification timeline compression:OEKO-TEX, GOTS, and EU Ecolabel concurrent audits demand 8-14 month approval windows, slowing product launch cycles for seasonal collections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Textile Garment Market |
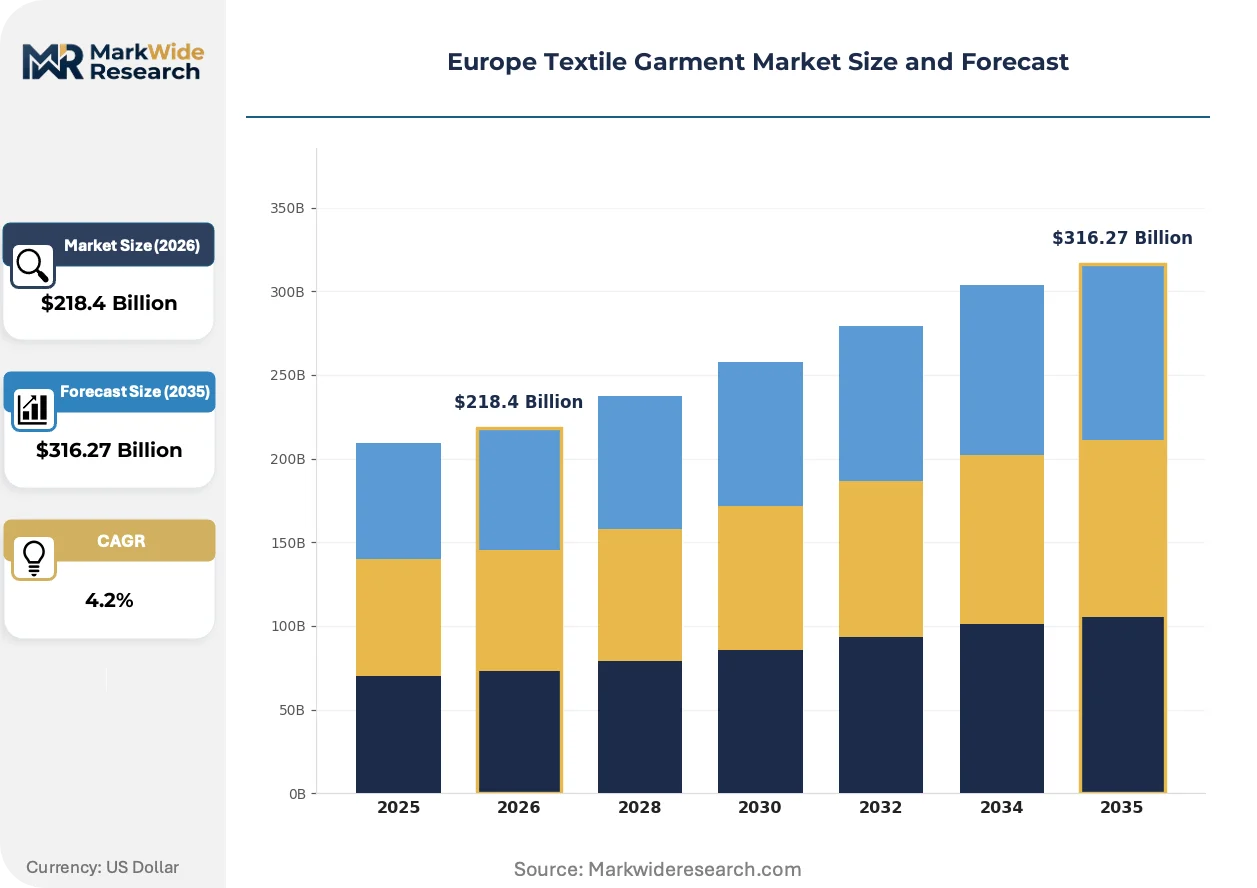
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $316.27 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirts, Dresses, Trousers, Coats Material: Cotton, Linen, Polyester, Wool Customer Type: Men, Women, Children, Unisex Distribution Channel: Online, Boutiques, Department Stores, Outlets |
| Companies Covered | Lenzing AG, Sioen Industries, Aquafil S.p.A., Marzotto Group, Schoeller Textil AG, Freudenberg Group, Eurojersey S.p.A, Beaulieu International Group, Toray Industries, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Textile Garment Market Shifts & Advancements
Digital sampling and virtual garment prototyping are compressing traditional 12-week development cycles, enabling European brands to respond to micro-trends without physical sample production waste.
ECONYL regenerated nylon from Aquafil S.p.A. is virtualizing virgin polymer demand in swimwear and activewear segments. Italian luxury sportswear houses are adopting closed-loop material systems for capsule collections. This technology is virtualizing conventional petrochemical supply chains by substituting ocean-recovered and post-industrial waste feedstocks at equivalent performance specifications.
EU Green Deal textile strategy implementation is mandating minimum recycled content thresholds and harmonized extended producer responsibility frameworks. ECHA enforcement timelines are eliminating conventional fluorinated finishes from Schoeller Textil AG's functional fabric portfolio. German industrial workwear manufacturers are accelerating reformulation partnerships with Swiss chemical suppliers to maintain water-repellency certification under tightening substance restrictions.
Athletic apparel procurement patterns are consolidating toward vertically integrated suppliers offering certified sustainable materials plus cut-make-trim services. Nordic outdoor brands are disintermediating traditional fabric merchants through direct partnerships with Portuguese and Romanian full-package manufacturers. This concentration is most visible in Denmark and Sweden, where sustainability transparency requirements exceed standard wholesale purchasing protocols.
Europe Textile Garment Market Segmentation
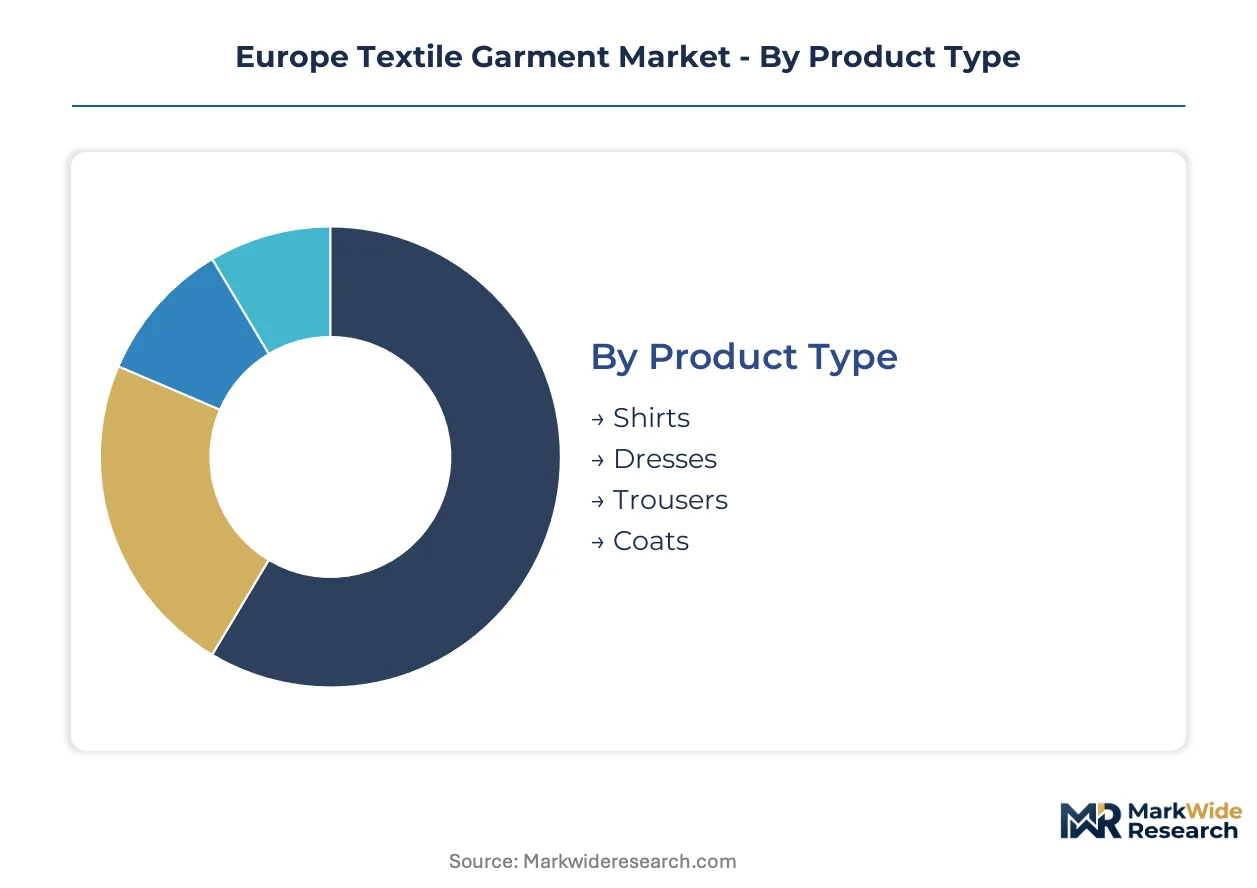
Segmentation in Europe's textile garment market reveals how regulatory pressure and consumption patterns fragment commercial opportunity across material certifications, channel economics, and demographic purchasing power. Distinct margin profiles emerge between heritage craft positioning and mass-market synthetic efficiency.
Product Type:
Formal and casual apparel categories span daily utility through ceremonial occasion, with Italian artisanal finishing commanding premiums in outerwear and structured garments.
- Shirts:Woven cotton and cotton-blend constructions dominate business and smart-casual wardrobes. German and French corporate procurement drives certified organic cotton demand for workplace dress codes under CSRD supply chain disclosure requirements.
- Dresses:Feminine silhouettes incorporate woven viscose, silk, and printed cotton with seam-bias draping. Milan's luxury houses concentrate couture-grade finishing for occasion wear, while Portuguese manufacturers supply mid-tier printed day dresses to Nordic retailers.
- Trousers:Tailored and casual pant constructions utilize stretch cotton, wool flannel, and technical synthetics for performance workwear.
- Coats:Outerwear requires interfacing, lining integration, and weather-resistant finishing that concentrates production in Como and Veneto heritage clusters.
The dominant share belongs to Shirts, while Dresses is closing the gap fastest through occasion-wear premiumization and rental platform integration.
Material:
Raw material selection determines regulatory compliance pathways, recycling eligibility, and end-of-life cost structures under emerging EU extended producer responsibility frameworks.
- Cotton:Natural cellulosic fiber sustains heritage positioning and thermal comfort premiums in European formal and casual segments. GOTS-certified organic cotton carries 15-25% sourcing premiums that compress fast-fashion margins.
- Polyester:Petroleum-derived synthetic dominates cost-efficient production and athletic blend versatility. REACH-compliant recycled PET feedstocks are displacing virgin polymer in Benelux and German sportswear procurement.
- Linen:Bast fiber from flax cultivation provides breathable summer-weight constructions with natural texture variation.
- Wool:Protein fiber from sheep fleece delivers insulation and crease recovery for outerwear and suiting. British and Italian merino grading systems maintain quality differentiation for heritage mill sourcing.
Polyester retains volume leadership through blend ubiquity, though certified organic Cotton is climbing fastest as EPR fee modulation penalizes synthetic environmental externalities.
Customer Type:
Demographic targeting aligns with sizing standardization, style trend velocity, and household purchasing authority across life-stage transitions.
- Women:Higher purchase frequency and style experimentation drive seasonal collection turnover. French and Italian luxury houses concentrate womenswear SKU proliferation, while Nordic brands emphasize modular capsule wardrobes with traceable material passports.
- Men:Lower frequency, higher per-transaction values favor quality signaling through fabric weight and construction detail. British and German menswear retailers emphasize repair services and lifetime garment guarantees.
- Children:Rapid size turnover and safety certification requirements create distinct sourcing protocols for chemical-free dyes and choking-hazard-free trims.
- Unisex:Gender-neutral sizing and styling reduces SKU complexity for direct-to-consumer brands targeting sustainability-conscious urban demographics.
Women's segments command the dominant revenue position, while Unisex is expanding most quickly among Gen Z purchasing cohorts rejecting traditional gendered merchandising.
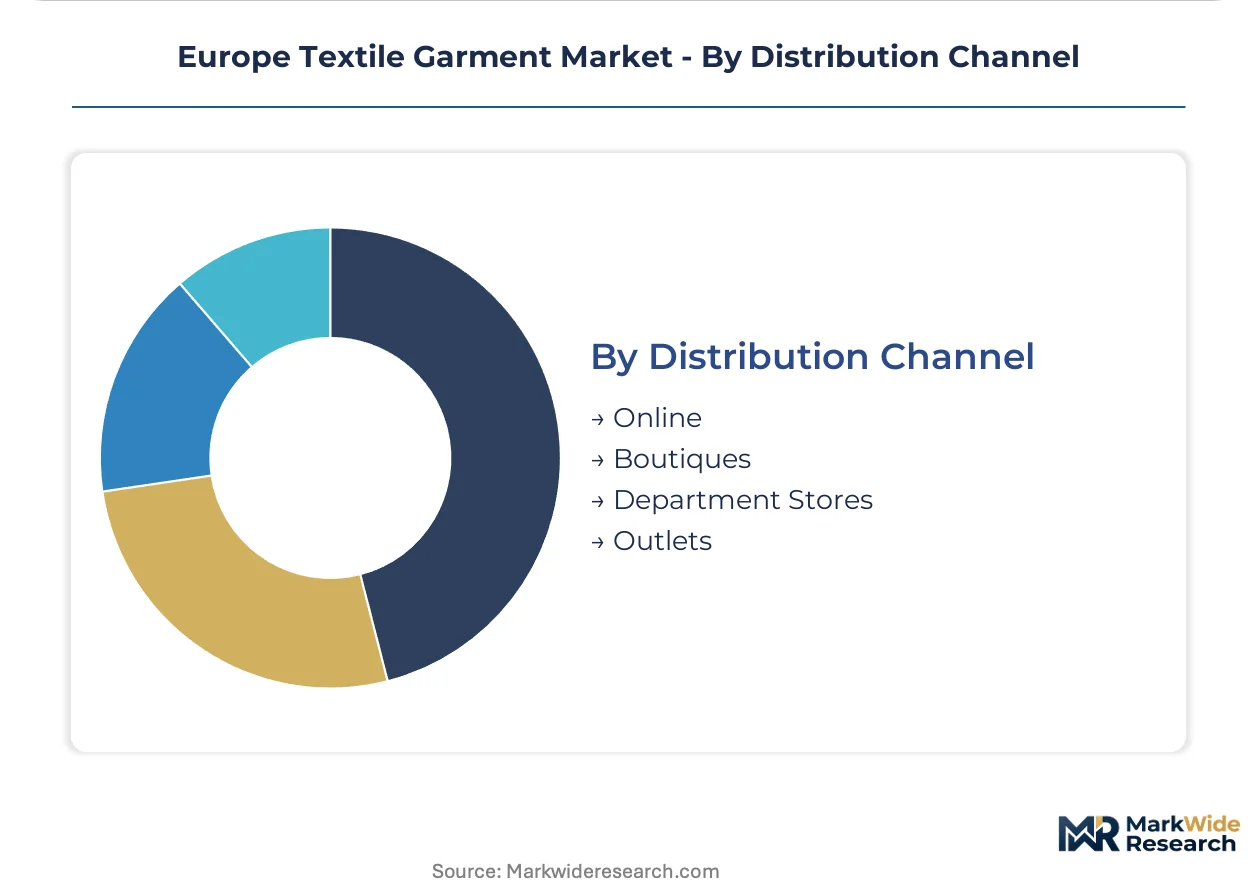
Distribution Channel:
Channel economics determine margin capture, inventory risk allocation, and consumer data access for demand forecasting and personalization.
- Online:Direct-to-consumer platforms eliminate wholesale intermediary margins and enable real-time trend responsiveness. Danish and Swedish athletic apparel brands leverage proprietary e-commerce for full-margin capture and carbon footprint transparency.
- Department Stores:Multi-brand retail provides discovery and service infrastructure for established labels. German and British department store consolidation is reducing available floor space for mid-tier European brands.
- Boutiques:Curated independent retail sustains artisanal brand discovery and personalized styling services.
- Outlets:Off-price channels manage excess inventory and past-season clearance with margin sacrifice.
Online channels have seized volume leadership, though Boutiques maintain the steepest expansion trajectory through experiential retail investments in Milan, Paris, and Copenhagen design districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal textile mandates and extended producer responsibility schemes are redistributing manufacturing investment across the continent. REACH chemical compliance costs and EPR fee structures now determine viable production locations more than labor arbitrage alone.
Italy
Milan and Como anchor heritage luxury manufacturing through artisanal finishing capabilities. France's AGEC law influences cross-border sourcing decisions for Italian suppliers serving French luxury houses. The Veneto region concentrates outerwear production with integrated lining and weather-resistant treatment facilities.
Germany
Industrial workwear procurement drives flame-retardant and high-visibility fabric demand from domestic safety garment manufacturers. ECHA enforcement of PFAS restrictions forces reformulation partnerships with Swiss chemical suppliers. The North Rhine-Westphalia corridor hosts technical textile R&D clusters focused on REACH-compliant functional finishes.
France
Parisian luxury houses sustain premium demand for Como-sourced silk and wool constructions. The AGEC law's extended producer responsibility framework creates fee-modulated incentives for design-for-recycling investments. Occitanie and Hauts-de-France regions develop mechanical recycling infrastructure to meet EU circularity benchmarks.
Poland
Central European manufacturing zones capture nearshoring volume from German retailers seeking 15-20% labor cost advantages against Italian production. EU regulatory compliance equivalence eliminates non-tariff barriers to German market access. The Łódź textile belt expands cut-make-trim capacity for Nordic athletic apparel brands.
Portugal
Full-package manufacturing capabilities attract direct partnerships from Nordic outdoor brands disintermediating traditional fabric merchants. REACH-aligned chemical management systems satisfy sustainability transparency requirements exceeding standard wholesale protocols. The Porto and Lisbon industrial zones specialize in quick-turnaround production for direct-to-consumer seasonal cycles.
Europe Textile Garment Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated material-to-garment platforms and specialized technical textile suppliers. Three strategic archetypes dominate: wood-based cellulosic fiber innovators anchoring sustainable material supply, regenerated nylon specialists enabling closed-loop swimwear and activewear production, and heritage luxury fabric mills preserving artisanal finishing premiums. Competitive moves concentrate on strategic partnerships for bio-based dye formulation and geographic expansion into Central European nearshoring zones.
Among Austria-based fiber innovators, Lenzing AG exemplifies the sustainable material supply archetype through its TENCEL lyocell production. Belgian technical textile leader Sioen Industries occupies a position within industrial safety fabric supply. Italian regenerated nylon specialist Aquafil S.p.A. anchors the closed-loop material systems tier with its ECONYL platform for swimwear and activewear applications.
| Leading Market Players |
|---|
| Lenzing AG |
| Sioen Industries |
| Aquafil S.p.A. |
| Marzotto Group |
| Schoeller Textil AG |
| Freudenberg Group |
| Eurojersey S.p.A |
| Beaulieu International Group |
| Toray Industries, Inc. |
| Others |
Supply & Pricing Matrix
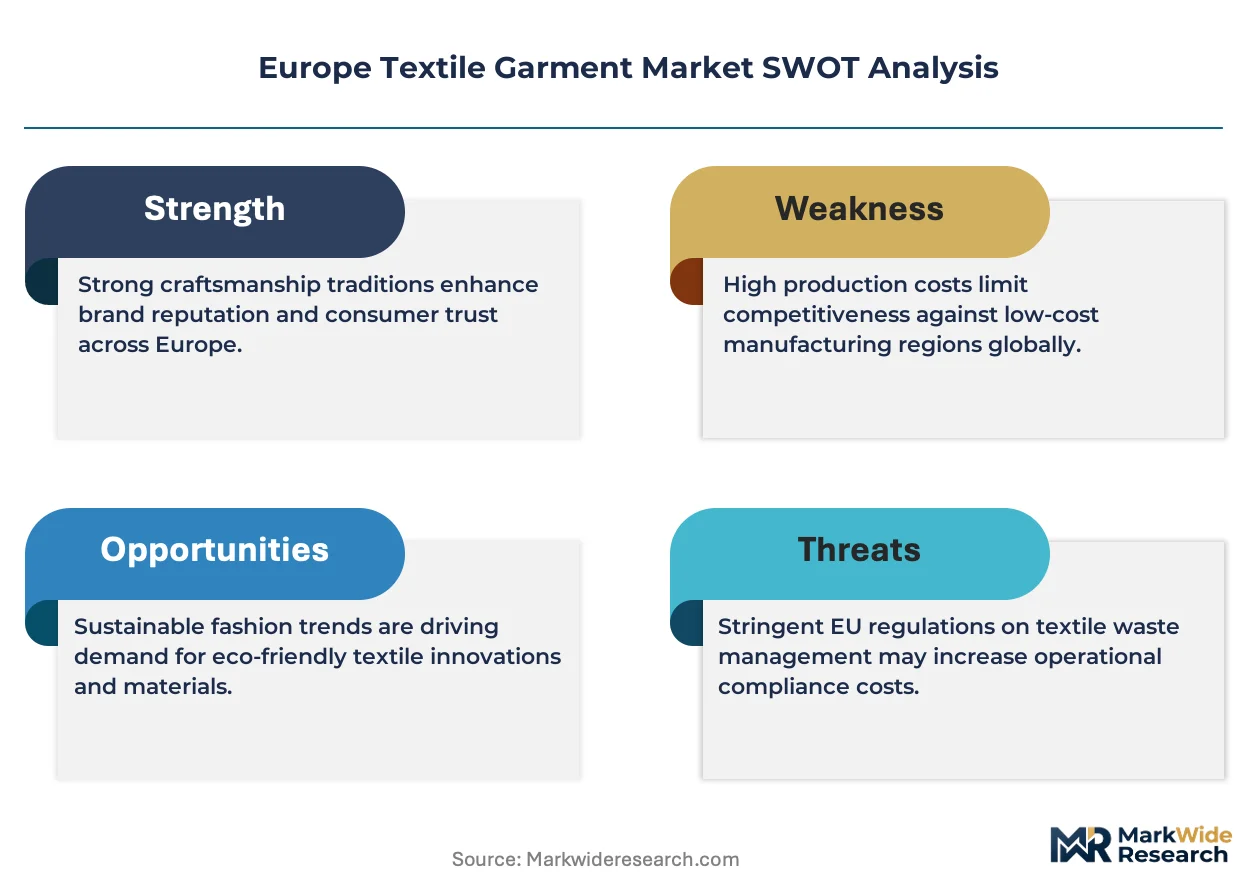
REACH chemical compliance costs and ECHA enforcement timelines for PFAS elimination constitute the dominant risk vector compressing margin structures across European textile garment tiers, simultaneously widening price spreads between certified sustainable supply chains and conventional production while forcing geographic reconfiguration toward EU-regulatory-equivalent zones.
Pricing Analysis
Certification level creates the primary spread across European textile garment pricing, with GOTS organic and OEKO-TEX Standard 100 tiers commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium artisanal, certified sustainable, and uncertified economy levels reflects material provenance and regulatory compliance investment. Cost compression in fast-fashion polyester blends is intensifying because virgin petrochemical feedstock volatility and impending EPR eco-modulated fees erode already thin margins. German corporate procurement shows lowest price sensitivity, prioritizing CSRD-compliant supply chain disclosure, while Southern European mid-tier retailers exhibit highest sensitivity to per-unit cost fluctuations.
Supply Chain Analysis
Portuguese full-package manufacturers and Polish cut-make-trim specialists hold the dominant contract-manufacturing concentration for Nordic and German brand direct sourcing. Raw material flows draw from Austrian wood-based cellulosic fiber producers, Italian regenerated nylon specialists, and Belgian technical textile suppliers. Single-source dependency on Como-region silk and wool finishing creates vulnerability during capacity constraints at heritage mill clusters. Distribution runs through vertically integrated brand e-commerce platforms, wholesale department store networks, and independent boutique channels with diverging margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal textile strategy mandates fiber-to-fiber recyclability benchmarks and extended producer responsibility frameworks, creating a regulatory inflection that disrupts incumbent cost structures while opening acquisition opportunities for circular infrastructure specialists.
For Market Incumbents: Build captive recycling infrastructure moats through mechanical and chemical recycling partnerships in France and Belgium to preempt EPR fee modulation penalties. Secure multi-year supply agreements with Lenzing AG and Aquafil S.p.A. to lock in sustainable material access before capacity constraints intensify. Invest in bio-based dye formulation R&D with Swiss chemical suppliers to maintain functional fabric certification under tightening ECHA substance restrictions.
For New Entrants and Emerging Players: Establish a beachhead in Poland-Czechia nearshoring corridors where EU regulatory compliance equivalence meets 15-20% labor cost advantages against Italian production. Target direct-to-consumer athletic apparel segments in Denmark and Sweden where sustainability transparency requirements exceed standard wholesale protocols and brand loyalty remains fluid. Pursue full-package manufacturing partnerships with Portuguese industrial zones specializing in quick-turnaround production cycles.
For Investors and Strategic Acquirers: EU-wide EPR implementation and harmonized extended producer responsibility frameworks reshape the acquisition landscape toward circular infrastructure and certified material supply assets. Focus on vertically integrated mid-cap specialists with established GOTS or EU Ecolabel certification and existing take-back program infrastructure. Monitor ECHA enforcement timeline acceleration for PFAS restrictions as the critical signal indicating reformulation partnership valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Material System Investment | ECONYL regenerated nylon integration virtualizes virgin polymer demand for swimwear and activewear brands. |
| Central European Nearshoring Expansion | Poland-Czechia manufacturing zones capture German retail volume with equivalent REACH compliance and shortened lead times. |
| Direct-to-Consumer Platform Buildout | Proprietary e-commerce enables full margin capture and real-time demand signaling from Nordic sustainability-conscious consumers. |
| Bio-Based Dye Formulation Partnership | Swiss chemical supplier collaborations maintain water-repellency certification under ECHA fluorinated finish elimination mandates. |
| Extended Producer Responsibility Infrastructure | France's AGEC law and pending EU-wide EPR create fee-modulated incentives for design-for-recycling and take-back program development. |
Research Methodology
Initial hypotheses were tested against primary input from sustainability officers at luxury fashion houses, procurement directors at German industrial workwear manufacturers, technical textile R&D leads at Belgian and Swiss suppliers, and category buyers at Nordic athletic apparel retailers, then refined through customs trade data, ECHA regulatory filings, EU Green Deal implementation documents, and SEC disclosures from listed fiber and fabric producers, with bottom-up production capacity modeling cross-validated against top-down consumption estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material certification tier, customer demographic, and distribution channel economics. CAGRs were derived from installed manufacturing capacity trajectories, regulatory compliance cost curve modeling, and substitution elasticity between virgin and recycled feedstocks. Wood-based cellulosic fiber supply expansion and mechanical recycling yield degradation curves served as textile-specific forecast inputs.
Stress conditions across petrochemical input volatility, EPR fee modulation severity, and ECHA enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and brand sustainability commitment durability. Quarterly review of ECHA substance restriction proposals and EU Green Deal textile strategy implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Uniform Market
Apparel Textiles
Denim Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Horse Riding Apparel Market