
 Japan Denim Jeans Market | 2026-2036
Japan Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Denim Jeans Market Insights
Okayama Prefecture's artisan mill network is hardening its reputation as the global epicenter of premium Japanese denim. Studio D'Artisan leverages decades of shuttle-loom expertise to sustain its position among heritage collectors. Momotaro Jeans anchors its brand identity through distinctive battle-stripe detailing and uncompromising fabric weight standards. Kaihara dominates domestic raw denim supply through vertical control over spinning, dyeing, and weaving operations.
Japan denim jeans technically comprise cotton twill fabrics woven with indigo-dyed warp threads and undyed weft, typically constructed on vintage shuttle looms producing narrow selvedge edges with characteristically irregular texture. The primary commercial purpose centers on durable, aesthetically evolving garments prized for fade patterns unique to individual wear patterns. Slim fit silhouettes command the largest volume position across domestic retail, while selvedge denim fabric technology captures the highest margin pool due to labor-intensive shuttle-loom production and limited yardage output. Stretch denim formulations are gaining traction among younger demographics seeking comfort without sacrificing visual authenticity.
METI's Sustainable Fashion Initiative and JIS standards for textile quality and labeling shape product specifications and consumer transparency requirements across the Japanese denim value chain. The national consumer affairs agency enforces strict fiber content disclosure rules that influence how mills communicate material provenance to domestic buyers. Stakeholders must monitor how evolving environmental compliance timelines and generational shifts in channel preference between specialty stores and direct-to-consumer platforms reshape competitive dynamics.
Market Dynamics
Shuttle-loom selvedge production capacity in Okayama Prefecture is tightening as artisan mills face generational workforce transitions, constraining supply of premium narrow-edge fabric while METI's carbon-reduction mandates accelerate capital requirements for smaller weaving operations.
Growth Catalysts
- METI Sustainable Fashion Initiative:Government-backed low-interest financing for cleaner indigo-dyeing processes is enabling Kojima-based mills to retrofit wastewater recovery systems without margin erosion.
- Heritage tourism circuits:Foreign visitors to Okayama's Jeans Street are converting at specialty retail, extending brand exposure to Southeast Asian and European collectors.
- Raw denim subculture:Online communities documenting fade evolution are sustaining replacement demand among Tokyo and Osaka enthusiasts who cycle multiple pairs annually.
Market Restraints
- Cotton price volatility:Import dependency on US and Australian upland cotton exposes domestic mills to currency fluctuation and climate-related harvest uncertainty.
- Shuttle-loom operator scarcity:The average age of skilled technicians in Kojima exceeds 55, with vocational pipeline gaps threatening production continuity at heritage mills.
- JIS labeling compliance costs:Fiber content verification and origin documentation requirements impose disproportionate administrative burden on small-batch artisan producers.
Strategic Opportunities
- Direct-to-consumer platforms:Specialty mills in Okayama are bypassing wholesale layers to capture full margin from overseas enthusiasts via localized e-commerce.
- Stretch-selvedge hybridization:Core-spun elastane integration into shuttle-loom construction is opening comfort-positioned product lines for younger Kanto demographics.
- Prefectural craft certification:Okayama Prefecture's geographic indication lobbying could create protected status analogous to Scotch whisky, defending price premiums against non-Japanese "Japan-style" competitors.
Industry Challenges
- Dyeing chemistry expertise gap:Natural indigo fermentation mastery is concentrated among aging craftsmen in Tokushima, with limited knowledge transfer to next-generation technicians.
- Legacy ERP integration:Family-owned mills operating on paper-based production logs face friction digitizing inventory and order management for omnichannel fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Denim Jeans Market |
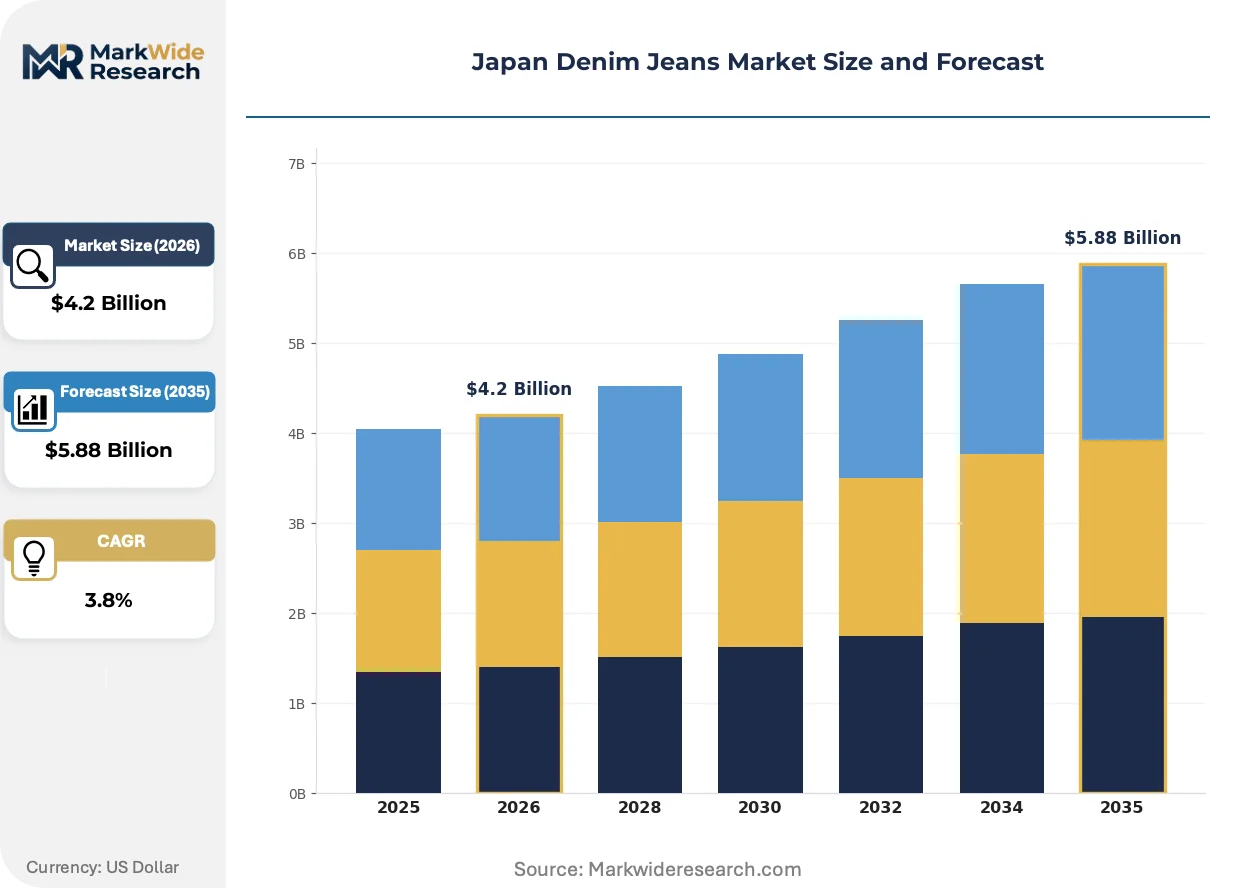
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
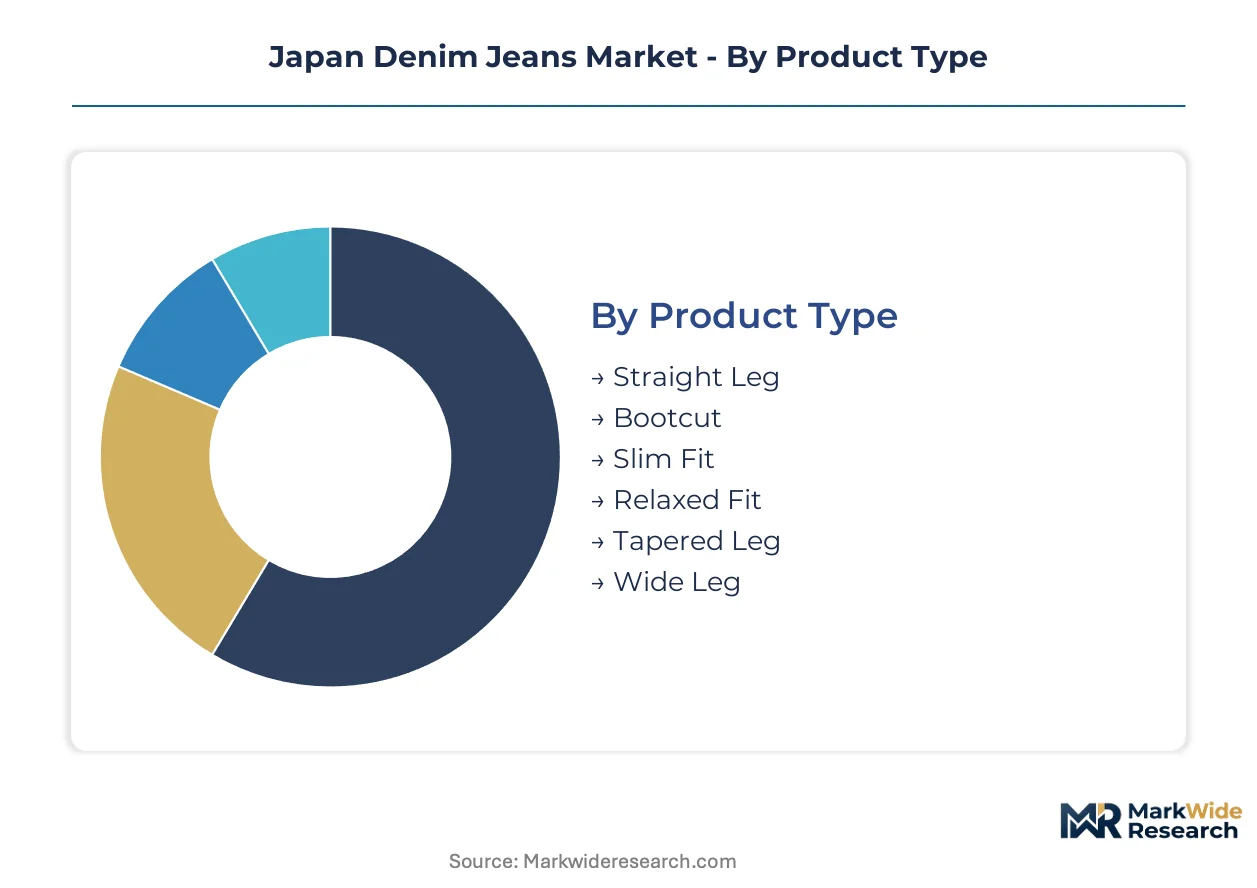
| Segmentation | Product Type: Straight Leg, Bootcut, Slim Fit, Relaxed Fit, Tapered Leg, Wide Leg Fabric Technology: Selvedge Denim, Raw Denim, Stretch Denim, Sanforized Denim, Stonewashed Denim, Bio-Washed Denim End User: Young Adults, Fashion Enthusiasts, Casual Wearers, Craft Denim Collectors, Outdoor Workers, Lifestyle Influencers Distribution Channel: Specialty Stores, Department Stores, Online Retailers, Branded Outlets, Pop-Up Shops, Wholesale Distributors |
| Companies Covered | Studio D'Artisan, The Strike Gold, Momotaro Jeans, Blue Blue Japan, Evisu, Oni Denim, Samurai Jeans, Kaihara, Iron Heart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Denim Jeans Market Trends and Innovations
Laser finishing and ozone washing systems are displacing traditional stone-wash and bleach processes, driven by water-usage restrictions and buyer preference for controlled abrasion patterns.
Robotic laser finishing equipment is integrating into Kojima district production lines, enabling programmable whisker and honeycomb pattern replication without manual sanding. Mid-tier Osaka garment processors are adopting this technology fastest, compressing sample-to-production timelines from weeks to days. The capital efficiency gain is integrating smaller batch viability, fragmenting volume concentration among heritage mills.
METI's carbon-neutral manufacturing roadmap is tightening emissions disclosure requirements for textile producers above defined revenue thresholds. Mills must document Scope 1 and 2 emissions or face exclusion from government procurement and export promotion programs. Okayama-based selvedge specialists are responding by consolidating dyehouse energy contracts and installing on-site solar generation.
Specialty retail consolidation in Tokyo's Shibuya and Harajuku districts is shifting collector purchasing toward appointment-only ateliers and brand-owned flagship experiences. Department store denim floors are contracting floor space, replaced by direct-operated stores offering repair and alteration services. This channel rotation is most visible in Kanto, where rent pressures and experiential retail expectations are highest.
Japan Denim Jeans Market Segmentation
Japanese denim manufacturers calibrate production capacity across distinct technical and aesthetic specifications. JIS labeling requirements apply differentially to selvedge versus stretch constructions, creating compliance cost asymmetries that reshape competitive positioning within each segment.
Product Type:
Slim fit and straight leg constructions dominate Kanto retail floor space, while tapered and wide leg silhouettes carry divergent JIS fiber-content verification burdens based on panel complexity and seam construction standards.
- Slim Fit:Narrow leg openings and reduced seat ease characterize this silhouette. Tokyo and Osaka young adults drive replacement cycles, with METI's sustainable fashion subsidies partially offsetting premium pricing for domestically manufactured units.
- Straight Leg:Consistent width from hip to hem accommodates varied body types with minimal pattern grading. Heritage mills in Okayama Prefecture concentrate volume output here, leveraging standardized cutting templates that reduce fabric waste and JIS documentation overhead per unit.
- Bootcut:Flared hem accommodates footwear stacking. Demand concentrates among casual wearers seeking versatility across workplace and social contexts.
- Relaxed Fit:Generous rise and thigh room prioritize comfort. Older demographics in regional cities favor this construction for extended wear cycles.
- Tapered Leg:Gradual narrowing from knee to ankle. Younger Kanto buyers seeking selvedge authenticity with contemporary styling drive adoption.
- Wide Leg:Exaggerated silhouette revival from vintage archives. Fashion enthusiasts and lifestyle influencers in Harajuku district specialty stores sustain niche demand.
Leading the category by volume: Straight Leg. Growing fastest: Tapered Leg.
Fabric Technology:
Shuttle-loom capacity constraints and dyeing chemistry requirements fragment margin structures across fabric categories, with natural indigo fermentation and core-spun elastane integration demanding distinct technical competencies.
- Selvedge Denim:Narrow self-finished edges produced on vintage shuttle looms yield characteristically irregular texture. Okayama's Kojima district mills command price premiums through limited yardage output and artisan labor intensity, though generational workforce transitions threaten supply continuity.
- Stretch Denim:Core-spun elastane integration enables comfort without visual compromise. Younger demographics across Tokyo and Osaka drive fastest expansion, with METI carbon-reduction mandates pushing mills toward cleaner elastane processing chemistries.
- Raw Denim:Unwashed, rigid fabric prized for personalized fade evolution. Craft denim collectors sustain demand through online fade documentation communities.
- Sanforized Denim:Pre-shrunk treatment stabilizes dimensions post-wash. Casual wearers prioritizing fit predictability favor this specification.
- Stonewashed Denim:Pumice abrasion creates vintage aesthetic. Water-usage restrictions are displacing traditional processing toward laser-based alternatives.
- Bio-Washed Denim:Enzyme-based softening reduces environmental load. Sustainability-positioned retailers in Shibuya district are expanding shelf allocation.
Commanding highest margins: Selvedge Denim. Expanding most quickly: Stretch Denim.
End User:
Purchasing frequency and price sensitivity diverge sharply across user psychographics, with craft collectors accepting extended lead times for bespoke construction while casual wearers prioritize immediate availability.
- Young Adults:Urban Tokyo and Osaka consumers aged 18-34 drive volume through trend-responsive purchasing. Social media fade documentation sustains engagement and replacement demand.
- Craft Denim Collectors:Connoisseurs seeking shuttle-loom provenance and natural indigo dyeing accept premium pricing for limited production runs. Appointment-only Okayama ateliers serve this segment exclusively.
- Fashion Enthusiasts:Early adopters of silhouette innovations and seasonal washes. Harajuku and Shibuya specialty retailers concentrate merchandising investment here.
- Casual Wearers:Practical buyers prioritizing durability and fit consistency. Department store denim floors retain this demographic despite channel contraction.
- Outdoor Workers:Functional durability requirements drive heavyweight fabric preferences. Regional construction and agricultural employment sustains steady baseline demand.
- Lifestyle Influencers:Content creators sourcing visually distinctive pieces for audience engagement. Brand collaboration opportunities concentrate with this segment.
Generating highest revenue per transaction: Craft Denim Collectors. Scaling fastest: Young Adults.
Distribution Channel:
Channel economics reflect rent pressures and experiential service requirements, with direct-operated formats capturing margin from repair and alteration attach rates.
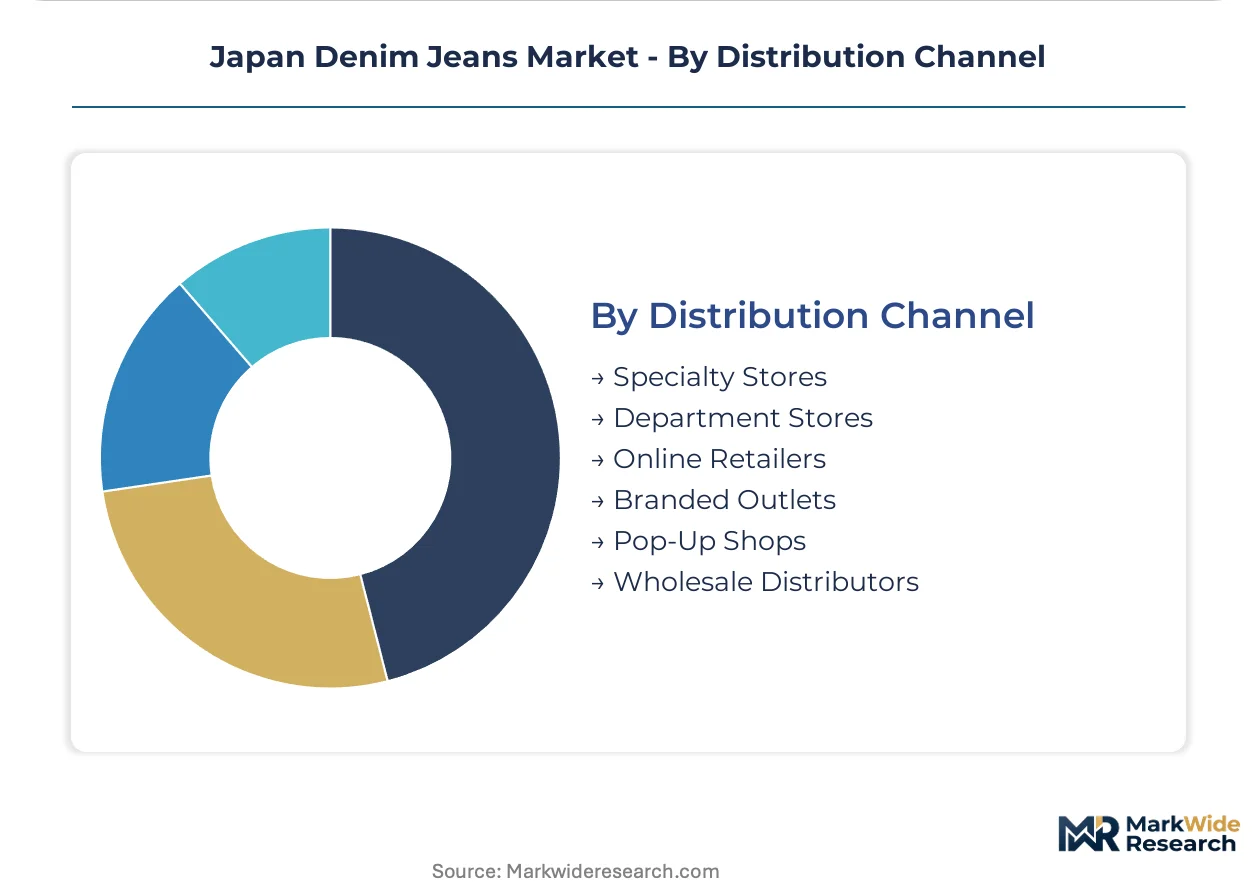
- Specialty Stores:Curated assortments with trained staff guiding selvedge selection. Okayama Jeans Street anchors heritage tourism conversion.
- Online Retailers:Direct-to-consumer platforms enable mills to bypass wholesale layers. Localized e-commerce captures overseas enthusiast demand with full margin retention.
- Branded Outlets:Flagship experiences integrate repair, alteration, and fade consultation services. Kanto rent pressures favor this format over department store concessions.
- Department Stores:Contracting floor space across Tokyo districts as experiential expectations rise. Remaining denim sections target casual wearer convenience.
- Pop-Up Shops:Temporary installations test new markets and limited collaborations. Seasonal placement in Osaka and Fukuoka extends brand reach.
- Wholesale Distributors:Traditional intermediaries facing margin compression as mills verticalize. Surviving players specialize in regional city coverage.
Highest transaction values: Branded Outlets. Gaining share fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Okayama Prefecture's Kojima district anchors Japan's denim production through its artisan mill network, while domestic demand concentrates in metropolitan corridors where heritage retail and collector culture intersect.
Kanto Region
Tokyo's Shibuya and Harajuku districts drive premium denim turnover through appointment-only ateliers and brand-owned flagships. METI's sustainable fashion subsidies partially offset rent pressures for domestic manufacturers operating direct retail. Collector communities in the capital sustain replacement demand through fade documentation and seasonal silhouette rotations.
Kansai Region
Osaka's young adult demographic accelerates stretch-selvedge adoption, balancing comfort requirements with visual authenticity preferences. Mid-tier garment processors in the region deploy robotic laser finishing fastest, compressing sample-to-production timelines. Heritage tourism circuits linking Osaka to Okayama extend brand exposure to Southeast Asian visitors.
Chubu Region
Nagoya's manufacturing base supplies technical components and dyeing chemistry to upstream denim operations. The region's industrial infrastructure supports equipment retrofitting for METI carbon-reduction compliance. Logistics connectivity positions Chubu as a distribution node for domestic wholesale and export consolidation.
Kyushu Region
Fukuoka's retail landscape hosts seasonal pop-up installations testing new market penetration for heritage brands. Younger demographics in the metropolitan area exhibit growing interest in raw denim subculture through online community engagement. Regional rent advantages attract specialty retailers expanding beyond Kanto saturation.
Tohoku Region
Sendai and surrounding cities sustain baseline demand for relaxed-fit constructions among older demographics prioritizing extended wear cycles. Department store denim floors retain stronger presence here compared to contracting Kanto equivalents. Limited heritage brand penetration creates whitespace for direct-to-consumer platform expansion.
Japan Denim Jeans Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue comfort-positioned hybridization and direct-to-consumer channel control. The vendor base stratifies across heritage shuttle-loom specialists, vertically integrated fabric suppliers, and mid-tier garment processors adopting automation. Three archetypes dominate: artisan mills leveraging geographic indication credibility, scale-driven operators consolidating dyehouse energy contracts, and digital-native brands bypassing wholesale layers. Competitive moves concentrate on stretch-selvedge R&D partnerships and prefectural craft certification lobbying.
Within the heritage artisan tier, Studio D'Artisan and Momotaro Jeans exemplify shuttle-loom positioning anchored in Okayama's Kojima district. Kaihara occupies a distinct position through vertical control over spinning, dyeing, and weaving operations. These three entities represent the spectrum from family-owned atelier craft to integrated industrial supply, each navigating METI compliance timelines and generational workforce transitions differently.
| Leading Market Players |
|---|
| Studio D'Artisan |
| The Strike Gold |
| Momotaro Jeans |
| Blue Blue Japan |
| Evisu |
| Oni Denim |
| Samurai Jeans |
| Kaihara |
| Iron Heart |
| Others |
Pricing and Supply Chain Analysis
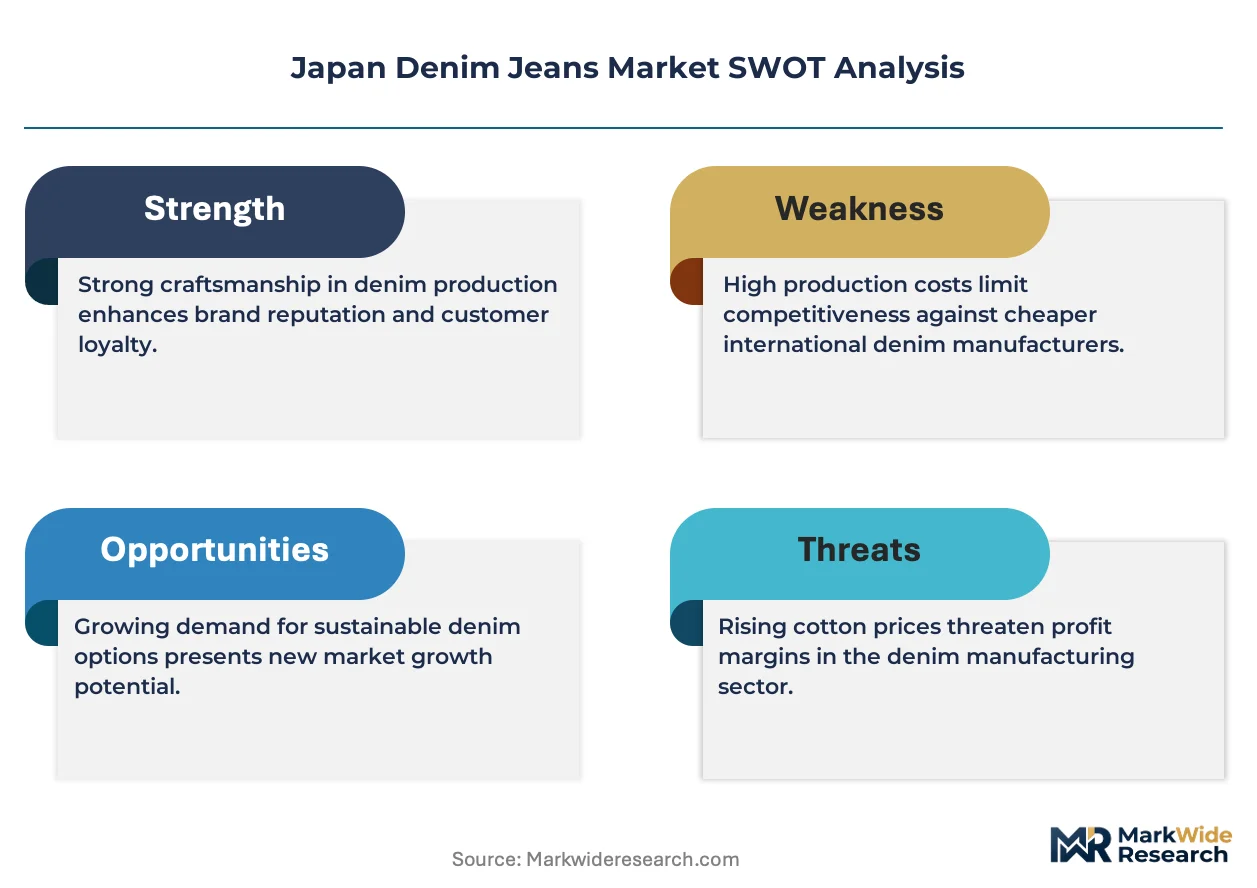
Backward integration into captive dyeing and weaving operations anchors pricing power for Okayama-based heritage mills, insulating them from commodity cotton volatility while enabling premium positioning through controlled scarcity of shuttle-loom output. This structural choice concentrates margin capture among vertically integrated operators as METI carbon-compliance costs disproportionately burden non-integrated competitors.
Pricing Analysis
Repair and alteration service bundling distinguishes branded outlet pricing from unbundled wholesale transactions, with fade consultation and lifetime mending justifying 40-60% premiums over comparable selvedge sold through department store channels. Three-tier pricing structure across artisan atelier, specialty retail, and mass-market entry points reflects certification grade and provenance documentation depth. Cost compression in mid-tier stretch-selvedge runs through elastane processing chemistry investments required by METI mandates. Casual wearers in regional Tohoku cities exhibit highest price sensitivity, while Okayama collectors accept extended lead times for bespoke natural indigo construction.
Supply Chain Analysis
Shuttle-loom operator scarcity in Kojima district constrains output expansion as technician ages exceed 55 years with minimal vocational pipeline replenishment. Raw cotton feeds from US and Australian upland suppliers, with indigo dye chemistry anchored in Tokushima fermentation traditions and core-spun elastane sourcing from domestic textile chemical specialists. Single-source vulnerability concentrates in natural indigo mastery concentrated among aging craftsmen. Distribution runs through direct-to-consumer platforms and appointment-only ateliers, bypassing wholesale layers that once intermediated overseas collector demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shuttle-loom capacity constraints in Okayama's Kojima district prop pricing premiums by capping premium fabric supply even as METI sustainable fashion subsidies expand addressable demand among younger Kanto buyers.
For Market Incumbents: Deepen repair-service attach rates at branded flagships to defend margin position against direct-to-consumer entrants capturing overseas collector demand. Secure dyeing chemistry expertise through apprenticeship pipeline investments before Tokushima indigo fermentation knowledge dissipates. Lock in long-term cotton offtake contracts to buffer currency exposure from US and Australian suppliers. For New Entrants and Emerging Players: Direct-to-consumer localization platforms offer the lowest-friction entry path, enabling full margin capture from Southeast Asian and European enthusiasts without wholesale layer compression. Target Tohoku regional cities where heritage brand penetration remains thin and department store denim floors retain stronger presence. Pursue stretch-selvedge hybridization to access comfort-positioned Kanto young adults underserved by rigid heritage constructions. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to apparel conglomerates seeking authentic craft credentials, with IPO viability limited by family-owned mill governance structures. Mid-term viability hinges on successful generational transition in Kojima technician ranks and METI compliance cost absorption. Monitor apprenticeship program graduation rates as the inflection signal for supply continuity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Stretch-Selvedge R&D Partnership | Core-spun elastane integration opens comfort-positioned lines for Kanto young adults without sacrificing shuttle-loom authenticity. |
| Direct-to-Consumer Platform Localization | Okayama mills bypass wholesale compression to capture full margin from overseas fade-documentation communities. |
| Geographic Indication Certification Lobbying | Prefectural craft protection would defend price premiums against non-Japanese "Japan-style" competitors in European markets. |
| Robotic Laser Finishing Adoption | Osaka mid-tier processors compress sample-to-production timelines from weeks to days, fragmenting volume concentration. |
| Apprenticeship Pipeline Investment | Tokushima indigo fermentation mastery transfer secures dyeing chemistry continuity threatened by aging craftsman concentration. |
Research Methodology
Independent corroboration across mill operations directors, specialty retail buyers, and METI textile policy officials underwrites the qualitative findings on supply constraints and regulatory compliance burdens. Primary fieldwork with Okayama dyehouse technicians, Kanto brand flagship managers, and Chubu equipment suppliers validated capacity utilization and automation adoption patterns. Secondary sources included JIS standard documentation, METI sustainable fashion initiative filings, customs records for cotton imports, and prefectural economic development reports. Bottom-up production capacity modeling triangulated against top-down retail turnover estimates across distribution channels.
Comparable-period anchoring to historical shuttle-loom output trends and heritage tourism visitor conversion rates established baseline assumptions across the analysis window. Segmentation modeling spanned fabric technology tiers, silhouette specifications, end-user psychographics, and regional demand clusters. CAGRs derived from production capacity constraints interacting with generational workforce transition timelines and METI carbon-reduction compliance phase-ins. Forecast inputs incorporated stretch-denim formulation adoption curves and direct-to-consumer platform penetration rates among overseas collectors.
The model holds under stable shuttle-loom operator supply and sustained METI subsidy continuity; deviation in apprenticeship graduation rates or trade policy shifts affecting cotton import costs would shift output and pricing trajectories. Forecasts reflect documented assumptions about dyeing chemistry expertise transfer and channel migration patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Rolle Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Zipper Market
Apparel Textiles
Maternity Leggings Market