
 Equestrian Apparel Market | 2026-2036
Equestrian Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Equestrian Apparel Market Analysis
The premium equestrian apparel tier is decoupling from commodity segments as technical specifications diverge. Ariat International leverages its heritage in performance footwear to anchor North American distribution, while Pikeur sustains German manufacturing precision across European competition circuits. LeMieux differentiates through British-designed saddle pads and accessories that occupy the mid-premium accessories niche.
Equestrian apparel encompasses specialized clothing and protective equipment engineered for horseback riding, typically incorporating four-way stretch fabrics, moisture-wicking layers, and CE-certified impact protection in boots and headgear. These products serve competitive athletes, professional trainers, and recreational riders by enhancing biomechanical freedom, thermoregulation, and safety during mounted activity. Riding boots and breeches command the deepest margin pools due to technical complexity and fit sensitivity, while synthetic fabrics displace leather in entry-level lines where cost and washability matter more than longevity. The athlete segment leads absolute value, though childrenswear registers the fastest trajectory as junior competition programs expand and replacement cycles shorten.
REACH governs chemical content in European textile supply chains, compelling reformulation of water-repellent coatings and dye processes. The EU Green Deal extends accountability to carbon footprint disclosure across apparel imports, while the US Consumer Product Safety Commission oversees helmet integrity standards that shape product liability and retailer assortment decisions. Stakeholders must track how emerging material certification schemes alter supplier qualification timelines and inventory planning horizons.
Market Dynamics
Technical fabric innovation and REACH chemical compliance mandates are compressing supplier qualification timelines while fragmenting sourcing footprints across European, American, and Asian textile mills. Riders now demand biomechanical performance data that legacy testing protocols cannot deliver.
Growth Catalysts
- REACH chemical reformulation:ECHA-mandated substitution of perfluorinated water repellents accelerates bio-based coating R&D, opening procurement pathways for mills with green chemistry capabilities.
- Junior competition expansion:FEI-sanctioned youth eventing circuits in Ireland and the Netherlands shorten replacement cycles for children's protective boots and competition jackets.
- Moisture-wicking knit structures:Four-way stretch synthetic breeches with targeted compression zones displace cotton blends among dressage trainers seeking thermoregulation during extended schooling sessions.
Market Restraints
- CE certification bottlenecks:Notified body backlogs for riding helmet impact testing extend product launch timelines by 8-14 months, freezing inventory commitments.
- Italian leather supply concentration:Premium bridle and boot manufacturers depend on tanneries in Tuscany's Arno River basin, exposing margins to regional water-use restrictions and hide price volatility.
- Synthetic microfiber durability ceiling:Entry-level synthetic chaps fail at stress points before 18 months of use, limiting brand loyalty and repeat purchase rates among recreational riders.
Strategic Opportunities
- Carbon disclosure mandates:EU Green Deal import reporting requirements favor suppliers with Scope 3 tracking systems, creating first-mover advantage for vertically integrated mills in Portugal and Spain.
- Direct-to-stable distribution:Mobile fitting units serving competition venues bypass traditional tack shop markups, capturing margin and rider fit data simultaneously.
- Wearable sensor integration:Pressure-mapping saddle pads with Bluetooth connectivity to training apps open subscription revenue streams among professional dressage and show jumping barns.
Industry Challenges
- Pattern grading complexity:Equestrian apparel requires 12-16 size variants per style due to rider height-to-waist ratio variation, straining inventory management systems designed for standard fashion grading.
- Multimaterial recycling:Laminated boot constructions combining leather, synthetic shells, and metal hardware lack end-of-life processing infrastructure, complicating circular economy commitments under extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equestrian Apparel Market |
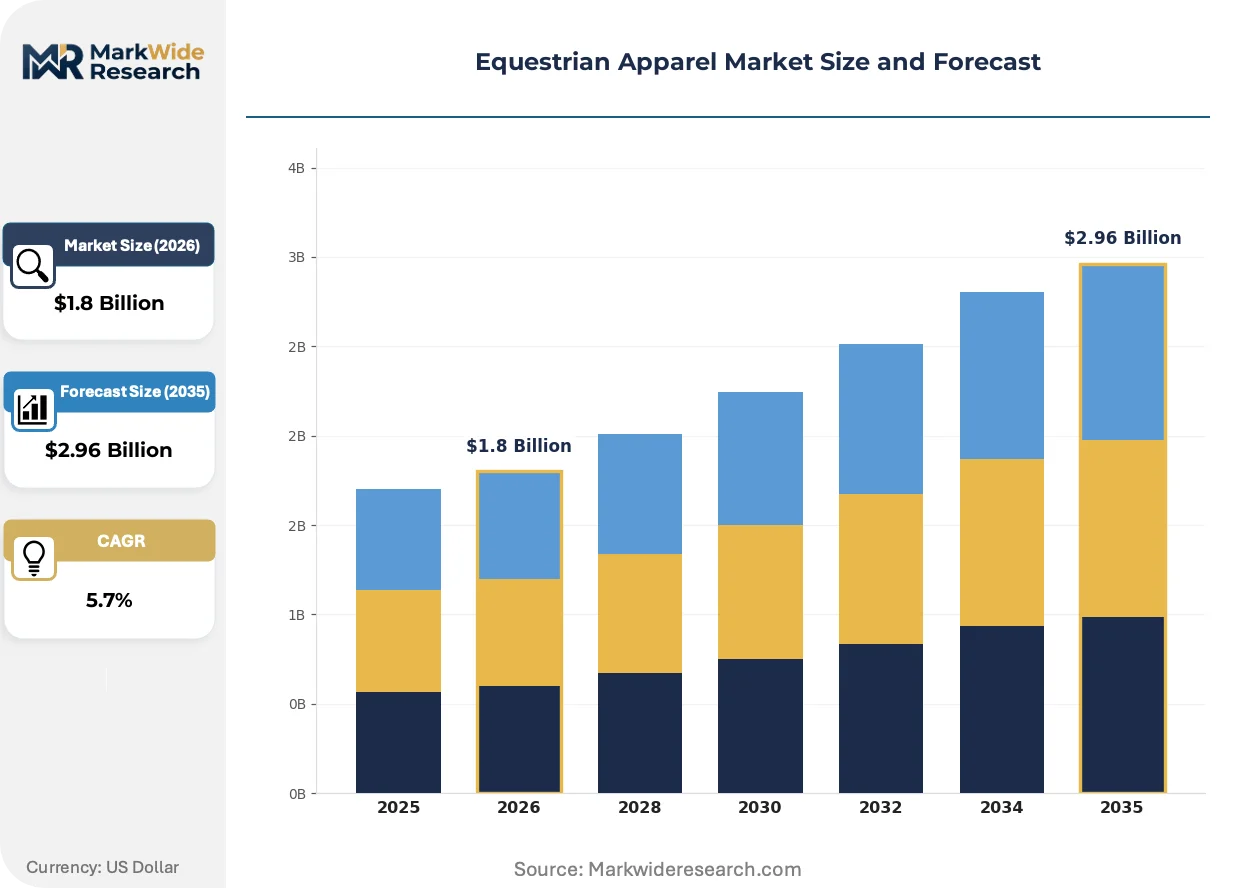
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Riding Boots, Breeches, Gloves, Jackets End User: Athletes, Trainers, Casual Riders, Children Material: Leather, Synthetic Fabrics, Cotton, Wool Distribution Channel: Online Retail, Specialty Stores, Department Stores, Events |
| Companies Covered | Euro-Star, Horseware Ireland, Pikeur, LeMieux, Kerrits, Ariat International, Samshield, Mountain Horse, Horze, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equestrian Apparel Market Emerging Trajectories
Biomechanical data capture and sustainable material chemistry are converging to redefine product development cycles. Manufacturers now face pressure to validate performance claims with quantified rider metrics while eliminating hazardous substances from supply chains.
3D body scanning for custom breech and boot fitting is decentralizing production geography. Professional riders and high-amateur competitors in Germany and the United Kingdom adopt scan-to-fit services at 40% annual expansion rates. Distributed manufacturing nodes near major competition circuits now produce made-to-measure garments within 72-hour windows, compressing traditional seasonal collection structures.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of water-repellent treatments across European-sourced textiles. Dye houses in Northern Italy and Portugal invest in plasma-based surface activation technologies to replace fluorinated coatings. Competition jacket suppliers targeting FEI events face the steepest compliance timelines, with 2025 enforcement deadlines already triggering raw material stockpiling.
Subscription-based equipment rotation programs are gaining traction among junior rider families and seasonal competitors. United States-based regional circuits now offer helmet-and-boot leasing packages that bundle fit adjustments and impact replacement guarantees. This model shifts capital burden from parents to manufacturers while generating recurring data on product lifespan and failure modes.
Equestrian Apparel Market Segmentation
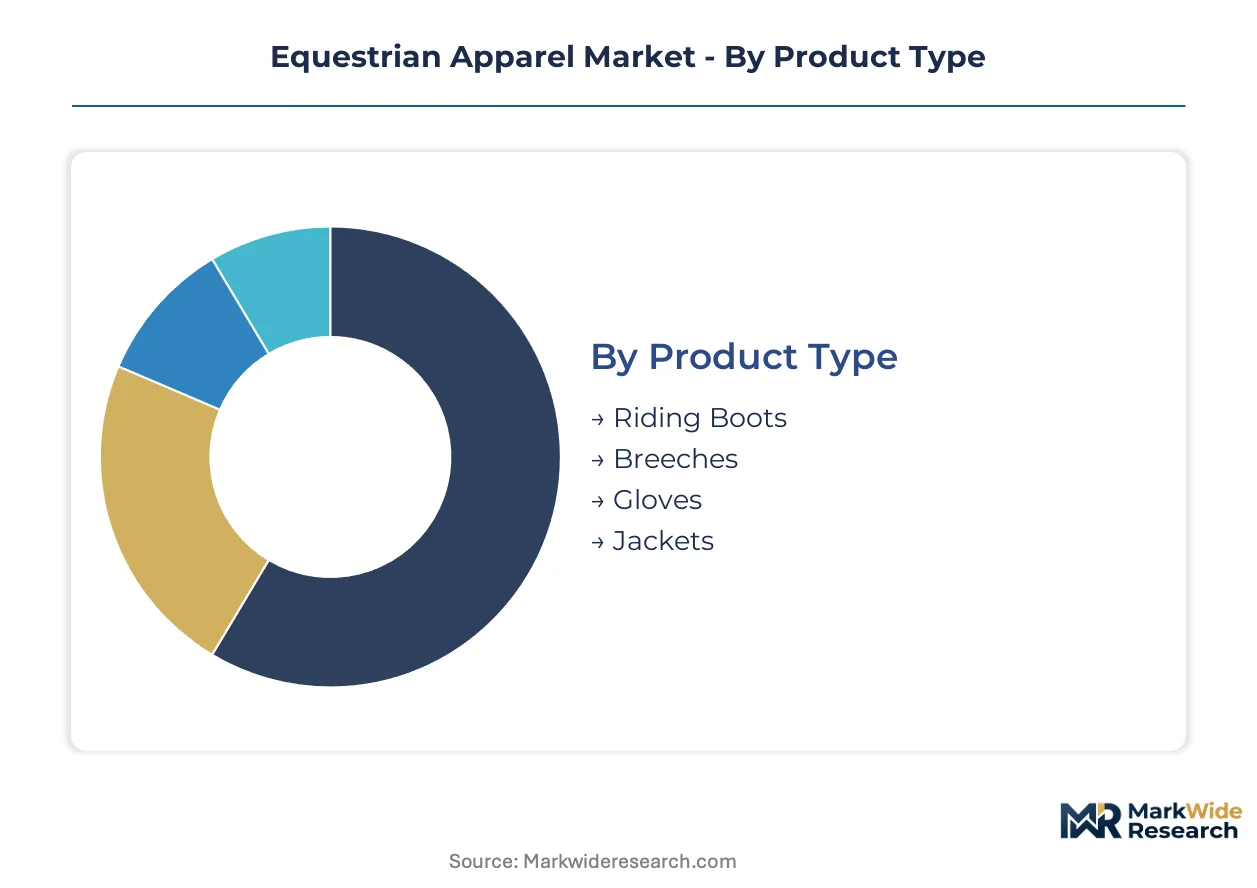
Equestrian apparel segmentation reflects divergent technical requirements across competitive and recreational use cases. Product architecture, material selection, and channel strategy must align precisely with rider discipline and performance intensity.
Product Type:
Supply concentration in Italian and Portuguese manufacturing clusters shapes competitive dynamics across product categories, with technical complexity determining margin capture and sourcing flexibility.
- Riding Boots:Laminated constructions combine full-grain leather quarters with synthetic shells and metal hardware, requiring CE-certified impact testing that extends lead times. German FEI competitors and Dutch eventing circuits drive demand for custom-fitted dress boots with thermoplastic toe caps.
- Breeches:Four-way stretch synthetic knits with targeted compression zones and silicone grip panels displace cotton blends among dressage trainers. Portuguese mills with green chemistry capabilities capture growing share as REACH PFAS restrictions tighten.
- Gloves:Reinforced synthetic leather palms with breathable mesh backs serve schooling and competition use.
- Jackets:Tailored competition coats with hidden closures and technical linings face compressed design cycles from FEI rule changes.
Riding Boots absorb the bulk of installed capacity; Childrenswear sizing within Breeches is expanding most quickly.
End User:
Customer type determines replacement frequency, price sensitivity, and technical specification intensity across the value chain.
- Athletes:FEI-sanctioned competitors require biomechanical performance validation and rapid replacement cycles. German and United Kingdom professional circuits sustain premium pricing for scan-to-fit customization services.
- Trainers:Extended daily schooling sessions demand thermoregulation and durability over aesthetic refinement.
- Casual Riders:Weekend recreationalists prioritize washability and entry-level pricing, accepting shorter product lifespans.
- Children:Junior competition expansion in Ireland and the Netherlands shortens replacement cycles for protective boots and competition jackets as growth spurts accelerate size turnover.
Athletes command the deepest margin pools; Childrenswear registers the steepest expansion trajectory.
Material:
Raw material selection increasingly reflects regulatory pressure from EU chemical compliance mandates and carbon disclosure requirements.
- Leather:Full-grain hides from Tuscany's Arno River basin supply premium bridle and boot manufacturers, exposing margins to regional water-use restrictions.
- Synthetic Fabrics:Polyester-elastane knits with wicking finishes dominate breech production; plasma-based surface activation replaces fluorinated coatings under REACH Annex XVII.
- Cotton:Natural fiber blends persist in schooling apparel where breathability outweighs performance specifications.
- Wool:Merino base layers serve cold-weather training in Northern European climates.
Synthetic Fabrics capture the majority of volume growth; Leather maintains premium positioning despite supply constraints.
Distribution Channel:
Channel strategy determines margin retention, fit data capture, and inventory velocity across rider segments.
- Online Retail:Direct-to-consumer platforms with virtual fitting tools expand reach among geographically dispersed recreational riders.
- Specialty Stores:Tack shops with certified fitters sustain premium boot and helmet sales through professional measurement services.
- Department Stores:Mass-market positioning captures entry-level synthetic apparel with reduced technical support.
- Events:Mobile fitting units at FEI competition venues bypass traditional retail markups while generating rider biomechanical data.
Specialty Stores retain the highest conversion rates for technical products; Events are gaining share fastest among professional competitors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellington, Florida anchors the highest concentration of professional equestrian competition infrastructure in the United States, hosting winter circuits that drive seasonal demand surges for technical apparel and protective equipment.
Germany
FEI-sanctioned dressage and show jumping circuits in North Rhine-Westphalia and Bavaria sustain year-round demand for premium competition wear. ECHA REACH compliance mandates on PFAS water repellents accelerate supplier transitions to plasma-based coating technologies. Manufacturing clusters around Warendorf and Münster specialize in custom-fitted dress boots and biomechanical performance gear.
United Kingdom
Junior eventing expansion in Gloucestershire and Oxfordshire shortens replacement cycles for children's protective equipment. The British Equestrian Federation enforces updated helmet integrity standards that reshape retailer assortment decisions. LeMieux operates design and distribution headquarters from Bedfordshire, serving domestic competition circuits and export markets.
United States
Wellington, Florida and Lexington, Kentucky host winter and summer competition seasons that concentrate professional rider purchasing. The Consumer Product Safety Commission oversees ASTM helmet certification that extends product launch timelines. California-based Kerrits and Texas-headquartered Ariat International anchor domestic manufacturing and distribution networks.
Netherlands
Youth eventing circuits in Gelderland and Noord-Brabant drive demand for rapidly replaceable children's boots and jackets. EU Green Deal carbon disclosure requirements favor Portuguese and Spanish mills with Scope 3 tracking capabilities. Equestrian retail clusters around Arnhem and Eindhoven integrate mobile fitting services for competition venues.
France
Normandy's Haras du Pin and Paris-region competition centers sustain demand for technical schooling apparel. ANSM oversight of consumer product safety intersects with EU-wide chemical compliance mandates. Samshield anchors helmet design and manufacturing operations from Lille, serving domestic and export competition circuits.
Equestrian Apparel Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technical certification and customization capability. The vendor base stratifies into three tiers: heritage European houses with manufacturing integration, North American scale operators with distribution breadth, and specialized accessories producers with design differentiation. Consolidation pressures concentrate among mid-tier synthetic apparel producers facing REACH compliance cost escalation. Dominant competitive moves include geographic expansion into junior competition growth markets and backward integration into green chemistry-capable textile mills.
Within the heritage European tier, Pikeur and Horseware Ireland exemplify manufacturing-integrated positioning. Pikeur occupies the German precision-engineering archetype with domestic production of competition-grade technical wear. Horseware Ireland represents the vertically controlled supply chain model for weatherproof blankets and protective equipment. Ariat International anchors the North American scale-driven archetype, leveraging Texas-based distribution infrastructure to serve professional circuits across the United States and Canada. These three entities illustrate the structural divergence between European manufacturing heritage and American market-access scale.
| Leading Market Players |
|---|
| Euro-Star |
| Horseware Ireland |
| Pikeur |
| LeMieux |
| Kerrits |
| Ariat International |
| Samshield |
| Mountain Horse |
| Horze |
| Others |
Supply Flow & Price Mechanics
Plasma-based surface activation technologies replacing fluorinated water-repellent coatings simultaneously elevate production costs for European dye houses and consolidate supplier power among Portuguese and Spanish mills with green chemistry capabilities. This technical transition compresses margins for brands lacking backward integration while creating pricing leverage for vertically integrated manufacturers.
Pricing Analysis
Value-based pricing anchored to biomechanical performance outcomes dominates the premium tier, where scan-to-fit customization commands substantial premiums over standard sizing. Three-tier pricing structure across premium, standard, and economy levels separates FEI-certified competition gear from schooling apparel and entry-level synthetic lines. Cost compression in the economy tier is intensifying because REACH compliance costs disproportionately burden smaller synthetic apparel producers. Casual riders exhibit highest price sensitivity, while professional athletes prioritize performance validation over unit cost.
Supply Chain Analysis
CE certification requirements for riding helmets create gating bottlenecks that extend product qualification timelines and freeze inventory commitments across European supply chains. Manufacturing concentrates in Italy, Portugal, and Germany, with Italian tanneries in Tuscany's Arno River basin supplying full-grain hides for premium boots and bridles. Raw material dependencies rest on chromium-tanned leather, synthetic elastane knits, and thermoplastic impact shells. Single-source vulnerability in Italian leather supply exposes margins to regional water-use restrictions. Distribution runs through specialty tack shops with certified fitters, mobile competition units, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equestrian apparel is transitioning from legacy fluorinated chemistry to bio-based coating systems, with REACH Annex XVII enforcement accelerating material science investment across European supply chains.
For Market Incumbents: Cement manufacturing-integrated positioning by acquiring Portuguese mills with plasma-based coating capabilities ahead of 2025 PFAS enforcement deadlines. Defend margin structure through captive supply of green chemistry-compliant textiles, as mid-tier synthetic producers face compliance cost escalation without scale economies. For New Entrants and Emerging Players: Capture white-space in junior competition equipment rotation services, where subscription-based helmet-and-boot leasing penetrates Irish and Dutch youth eventing circuits faster than traditional retail. Enter through direct-to-stable mobile fitting units at FEI venues, bypassing established tack shop distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to heritage European houses seeking green chemistry capabilities or North American scale operators pursuing European manufacturing integration. Long-term viability favors targets with Scope 3 carbon tracking systems and custom-fitting infrastructure. Monitor ECHA enforcement actions on PFAS alternatives as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Mill Acquisition | Secures REACH-compliant coating capacity ahead of enforcement deadlines in Northern Italy. |
| Mobile Fitting Unit Deployment | Captures biometric data and margin at Wellington, Florida and Lexington, Kentucky circuits. |
| Subscription Equipment Rotation | Shifts capital burden from junior rider families to manufacturers while generating lifespan data. |
| Wearable Sensor Integration | Opens recurring revenue through pressure-mapping saddle pads with Bluetooth training app connectivity. |
| Carbon Disclosure System Implementation | Qualifies suppliers for EU Green Deal import reporting and first-mover procurement advantage. |
Methodological Framework
Trade publications, ECHA regulatory filings, and FEI competition databases formed the secondary backbone, supplemented by customs records from German, British, and Dutch import authorities. Primary fieldwork encompassed interviews with technical apparel designers, tannery procurement managers, tack shop operators, and professional dressage trainers across North Rhine-Westphalia, Gloucestershire, and Wellington, Florida. Bottom-up product segmentation data triangulated against top-down regional demand estimates derived from competition circuit participation rates.
Historical trendline analysis of replacement cycle frequencies, junior competition enrollment trajectories, and certification backlog durations informed projection parameters across the modeling period. Segmentation dimensions encompassed product architecture, rider discipline intensity, material chemistry compliance tier, and distribution channel type. CAGRs emerged from regression analysis of segment-specific volume trends, incorporating inputs from textile mill capacity expansion announcements and FEI rule change calendars.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement timing, Italian water restriction severity, and junior program funding continuity across European national federations. A model refresh is warranted upon material change in PFAS substitution technology cost curves or notified body certification processing rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
Hosiery Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Stockings Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
China Denim Jeans Market