
 Maternity Leggings Market | 2026-2036
Maternity Leggings Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity Leggings Market Foresight
Digital knitting and seamless compression engineering is fragmenting traditional cut-and-sew production into on-demand, size-inclusive manufacturing networks. Lululemon leverages its technical fabric R&D infrastructure to extend performance attributes into maternity-specific compression lines. Beyond Yoga sustains a design-led positioning that specializes in soft modal blends for prenatal yoga practitioners. Blanqi anchors its competitive presence through medical-grade support engineering that differentiates its core product from fashion-oriented alternatives.
Maternity leggings are engineered lower-body garments constructed with elastomeric fibers, typically incorporating 15-25% spandex content to accommodate progressive abdominal expansion while maintaining graduated compression for circulatory support. Their primary commercial purpose centers on functional comfort during gestation and postpartum recovery, bridging medical utility with lifestyle apparel. Yoga and compression categories lead volume contribution due to repeat purchase frequency among fitness-oriented pregnant women, while modal fabric blends capture margin concentration through premium positioning in specialty channels. Online retail channels exhibit the fastest structural growth as algorithmic fit tools and subscription replenishment models reduce return rates.
FDA oversight of medical-grade compression claims intersects with OEKO-TEX Standard 100 textile safety protocols and state-level consumer protection statutes to shape product labeling and material disclosure requirements. The Federal Trade Commission's Green Guides further constrain how brands communicate sustainability credentials around organic cotton sourcing and recycled polyester content. Stakeholders must monitor evolving regulatory clarity on biomaterial certifications and anticipate how pending textile extended producer responsibility frameworks will reshape sourcing economics.
Market Dynamics
Digital knitting infrastructure is compressing lead times from twelve weeks to seventy-two hours, fragmenting traditional cut-and-sew production into distributed, on-demand manufacturing networks across multiple continents.
Growth Catalysts
- FDA medical-device pathway expansion:Compression leggings qualifying under Class I medical device designation unlock reimbursement channels through US private insurers and HSA-eligible retail, accelerating clinical adoption.
- Postpartum recovery protocols:Hospital discharge planners in Germany and the Netherlands now prescribe graduated compression garments, embedding maternity leggings into standard maternal care pathways.
- Seamless 3D knitting:This production technology eliminates side seams and enables zero-waste patterning, reducing material scrap rates while accommodating size ranges from XXS to 6XL in single production runs.
Market Restraints
- Elastane price volatility:Spandex feedstock derived from petroleum-based polyurethane exposes margins to crude oil fluctuations, with contract manufacturers in Taiwan and South Korea bearing input cost risk.
- Certification timeline friction:OEKO-TEX Standard 100 and GOTS organic certification cycles extend sixteen to twenty-four months, delaying product launches for emerging brands without established testing relationships.
- Substitute compression alternatives:Medical-grade compression stockings and abdominal binders prescribed through orthotic channels capture overlapping clinical use cases, particularly in France and Japan where reimbursement favors established device categories.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer platforms offering trimester-based size progression capture lifetime value through automated fit algorithms and predictive sizing based on gestational week inputs.
- Biomaterial convergence:Integration of TENCEL Lyocell with recycled ocean plastic yarns addresses dual sustainability credentials, appealing to premium buyers in Scandinavian markets with stringent environmental disclosure requirements.
- Postpartum athletic crossover:Extended sizing and compression engineering originally developed for gestational support now targets diastasis recti recovery, opening incremental revenue from the twelve-month postpartum window.
Industry Challenges
- Technical pattern engineering scarcity:Specialized knowledge in grading maternity patterns across progressive abdominal expansion curves concentrates among aging technical designers in Milan and Los Angeles, constraining brand expansion.
- Multi-certification compliance complexity:Simultaneous pursuit of OEKO-TEX, GOTS, and Bluesign approval requires redundant testing protocols, straining quality assurance resources for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternity Leggings Market |
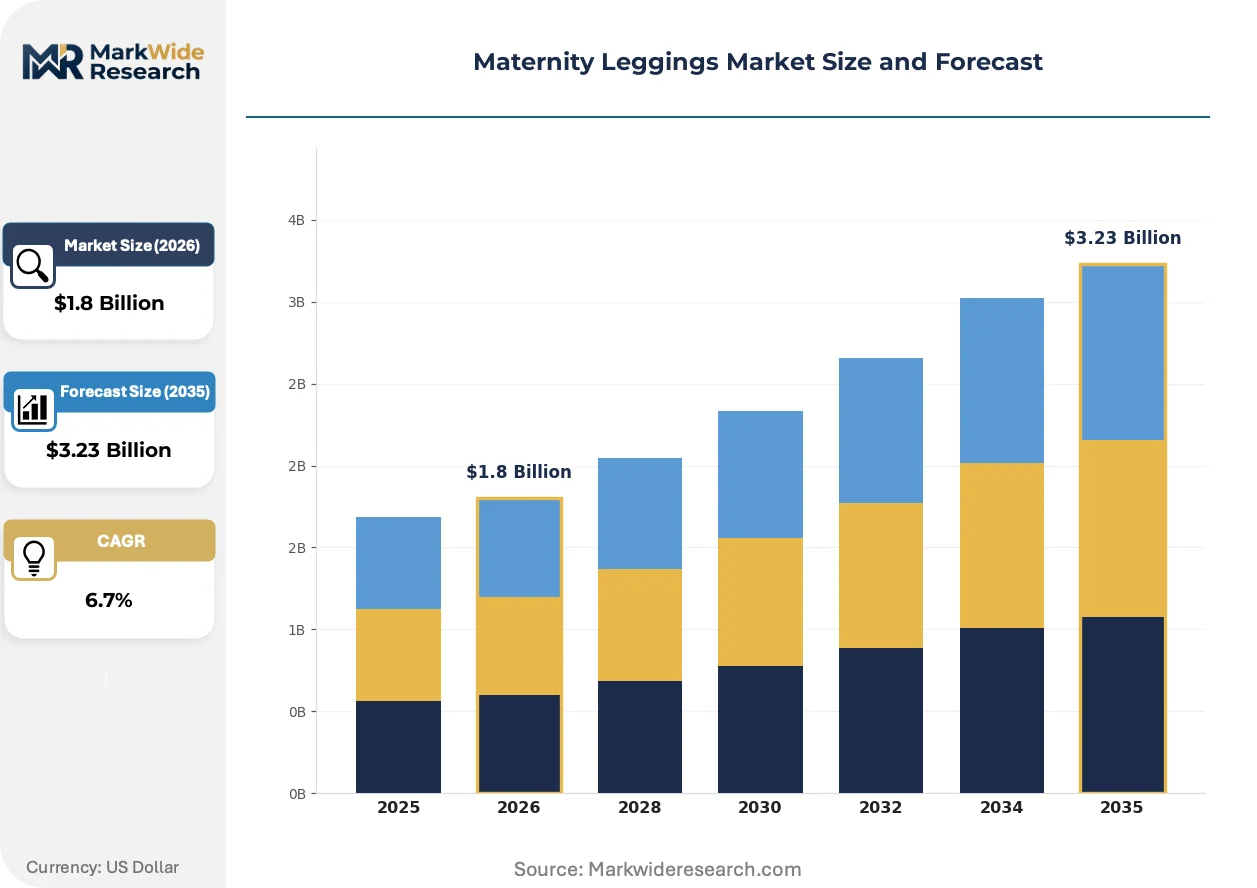
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yoga, Compression, Everyday Wear, Fashion Fabric Type: Cotton, Polyester, Spandex, Modal Retail Channel: Online, Department Stores, Specialty Shops, Outlets Customer Type: Pregnant Women, New Mothers, Fitness Enthusiasts, Casual Users |
| Companies Covered | Ingrid + Isabel, Lululemon, Beyond Yoga, Blanqi, Quince, Vitality, Isabella Oliver, Ohsurewear, Storq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity Leggings Market Shifts & Advancements
Algorithmic fit prediction and biomaterial substitution are converging to reshape how compression garments are engineered, produced, and distributed across gestational and postpartum use cases.
Seamless 3D knitting technology is digitizing pattern development and production workflows, enabling single-garment customization without minimum order quantities. Boutique maternity brands in Brooklyn and Shoreditch deploy this infrastructure to serve niche sizing demands previously excluded by mass-market grading. The technology is digitizing inventory risk management, compressing working capital requirements and enabling test-and-learn product development cycles measured in days rather than seasons.
REACH restriction proposals on microplastic release from synthetic textiles are compelling reformulation of elastomeric fiber blends across EU manufacturing footprints. The European Chemicals Agency's 2025 consultation on intentionally added microplastics threatens conventional spandex-dominant constructions, accelerating adoption of bio-based elastane alternatives. German and Dutch brands are responding fastest, restructuring supplier contracts to secure pre-certified compliant yarn stocks ahead of enforcement timelines.
Hospital procurement departments are unbundling maternity compression from general apparel tenders, creating standalone clinical garment categories with distinct technical specifications. This purchasing pattern shift elevates medical-grade engineering credentials over fashion positioning, particularly visible in NHS England supply frameworks and Kaiser Permanente system contracts. The channel disruption favors specialized manufacturers with established quality management systems over generalist apparel suppliers lacking ISO 13485 certification.
Maternity Leggings Market Segmentation
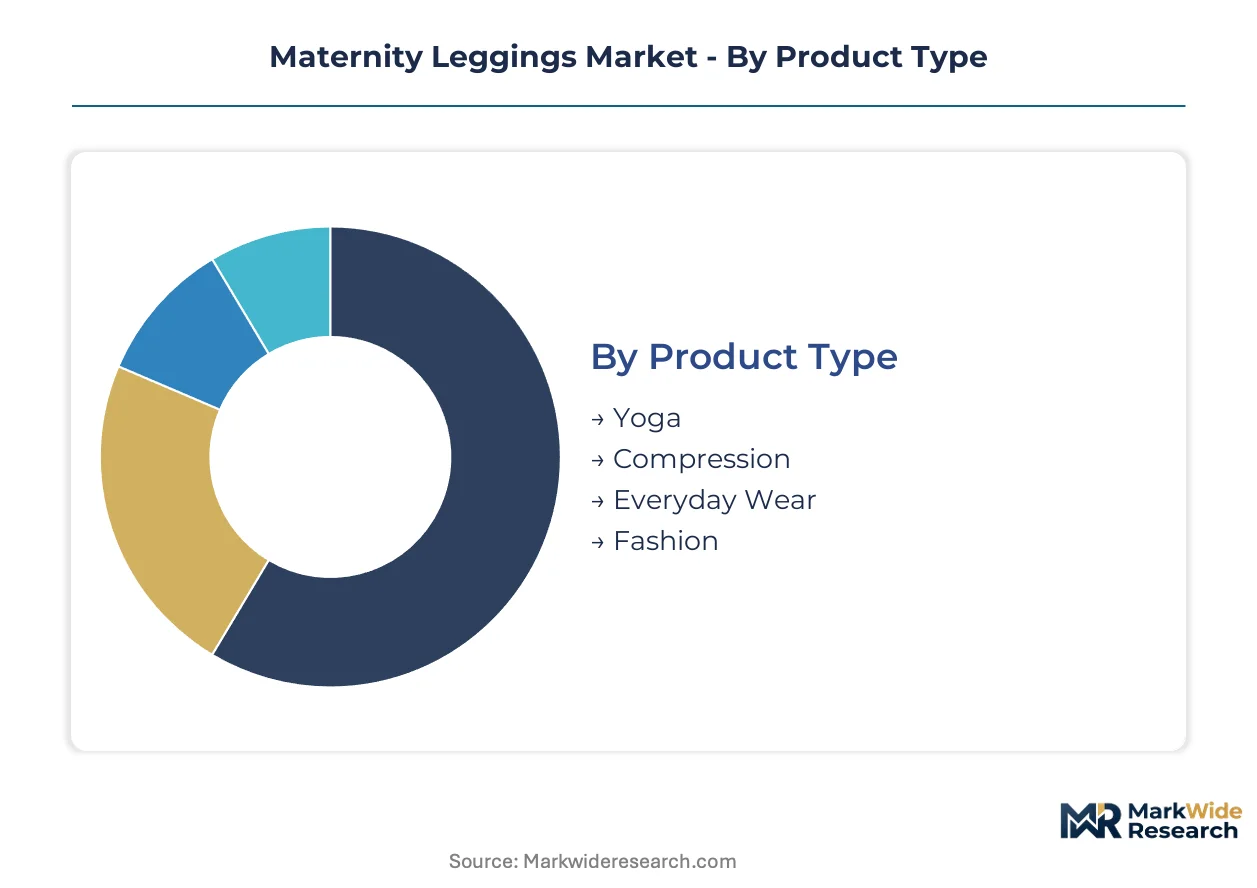
Maternity leggings segmentation reveals how technical specifications, material science, and distribution economics fragment addressable demand across gestational and postpartum use cases. Understanding these divides exposes where margin concentrates and which channels capture lifetime value through repeat purchase cycles.
Product Type:
Mature compression engineering dominates clinical and athletic applications, while emerging fashion-forward silhouettes test premium positioning in direct-to-consumer channels.
- Yoga:Constructed with four-way stretch nylon-spandex blends and gusseted crotch panels for range-of-motion retention. Demand concentrates among prenatal fitness practitioners in California and New York, where studio partnerships drive brand discovery and subscription replenishment.
- Compression:Medical-grade graduated compression (15-20 mmHg) engineered with seamless knitting for circulatory support during third-trimester edema. German hospital procurement frameworks and US HSA-eligible retail channels accelerate clinical adoption over fashion alternatives.
- Everyday Wear:Mid-rise and full-panel cotton blends prioritize all-day comfort for workplace and home environments.
- Fashion:Trend-driven prints, mesh inserts, and cropped lengths target social media-driven discovery and occasion-based purchase.
Compression handles the majority of throughput; Fashion is the fastest mover on share.
Fabric Type:
Cost tier stratification runs from commodity petrochemical inputs to certified organic and cellulosic alternatives commanding specialty retail premiums.
- Spandex:Elastomeric polyurethane fiber (15-25% content) provides essential abdominal expansion accommodation and shape retention across wash cycles. Taiwanese contract manufacturers bear crude oil price volatility risk, compressing margins for brands without forward yarn contracts.
- Modal:Beechwood-derived cellulosic fiber processed through closed-loop solvent recovery delivers superior moisture management and hand-feel. Scandinavian markets with stringent EU Green Deal disclosure requirements drive premium positioning in specialty channels.
- Cotton:Conventional and certified organic grades serve price-sensitive mass retail and sustainability-positioned specialty lines respectively.
- Polyester:Recycled PET and virgin filament yarns dominate entry-level pricing and performance moisture-wicking segments.
Cotton handles the majority of throughput; Modal is expanding most quickly in premium channels.
Retail Channel:
Volume concentration shifts from physical footprint economics to algorithmic fit prediction and subscription infrastructure.
- Online:Direct-to-consumer platforms deploy gestational-week input tools and predictive sizing to reduce return rates below industry averages. The channel captures working professional demand in the United States through Instagram and Pinterest discovery funnels.
- Specialty Shops:Curated maternity boutiques in London, Paris, and Milan provide tactile evaluation and expert fitting consultation. These outlets sustain margin concentration through exclusive brand distribution and postpartum crossover merchandising.
- Department Stores:Mass-market accessibility through national chains serves price-conscious first-trimester purchasers.
- Outlets:Off-price inventory clearance channels manage end-of-season carryover and size-run fragmentation.
Online handles the majority of throughput; Specialty Shops are gaining share fastest among premium buyers.
Customer Type:
Application context separates medical-functional need states from lifestyle and discretionary purchase occasions.
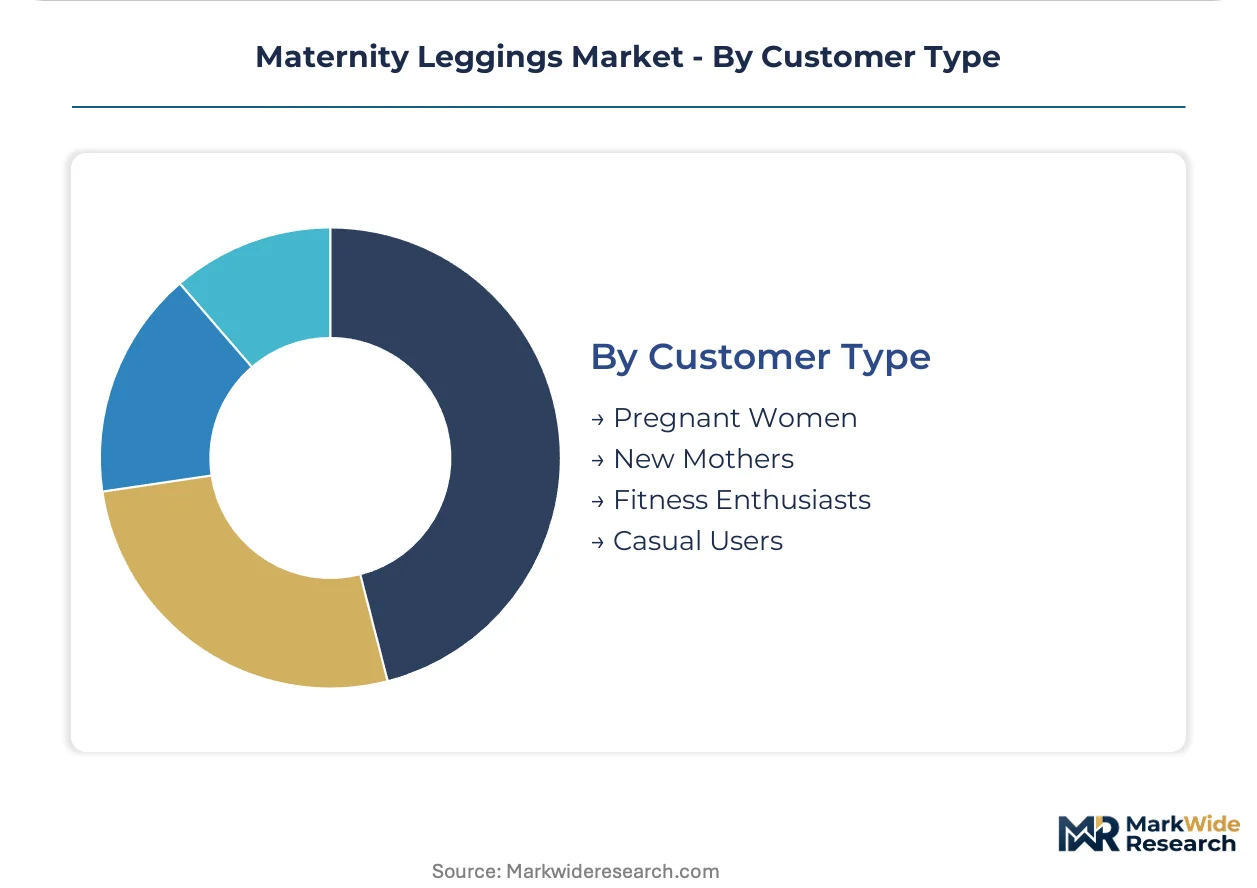
- Pregnant Women:First and second-trimester entrants drive initial category adoption with progressive sizing requirements across gestational weeks. Clinical guidelines in the Netherlands and Germany now prescribe graduated compression, embedding functional garments into standard maternal care.
- Fitness Enthusiasts:Prenatal yoga practitioners and running communities demand performance-grade moisture management and compression support. This segment exhibits highest repeat purchase frequency and brand loyalty through instructor endorsement networks.
- New Mothers:Postpartum recovery and diastasis recti support extend product utility into the twelve-month window after delivery.
- Casual Users:Occasional wear for comfort and style without specific functional requirements.
Pregnant Women handles the majority of throughput; Fitness Enthusiasts are climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese contract manufacturers export compression-grade elastomeric yarns to maternity apparel brands across the United States and Germany, establishing the primary trade-flow corridor for technical fabric inputs.
United States
Working professionals in professional services drive everyday and compression style adoption through direct-to-consumer channels and maternity-specific retailers. The FDA oversees medical-device classification for compression leggings qualifying under Class I designation, enabling HSA-eligible retail and private insurance reimbursement. Los Angeles hosts technical design studios specializing in progressive abdominal expansion pattern grading.
Germany
Hospital discharge planners prescribe graduated compression garments as standard postpartum recovery protocols, embedding maternity leggings into maternal care pathways. The EU Green Deal and REACH restriction proposals on microplastic release accelerate reformulation of elastomeric fiber blends toward bio-based alternatives. Berlin and Hamburg anchor specialized quality management systems for ISO 13485-certified clinical garment production.
Netherlands
Clinical guidelines now prescribe graduated compression for third-trimester edema and circulatory support, driving medical-grade demand through hospital procurement frameworks. ECHA consultations on intentionally added microplastics threaten conventional spandex-dominant constructions. Amsterdam-based brands restructure supplier contracts to secure pre-certified compliant yarn stocks ahead of enforcement timelines.
China
Digital knitting infrastructure compresses lead times from twelve weeks to seventy-two hours, fragmenting traditional cut-and-sew production into distributed on-demand networks. GB standards and MIIT oversight shape textile safety protocols for export-oriented manufacturing. The Yangtze River Delta concentrates seamless 3D knitting capacity serving boutique maternity brands in Brooklyn and Shoreditch.
United Kingdom
NHS England supply frameworks unbundle maternity compression from general apparel tenders, creating standalone clinical garment categories with distinct technical specifications. The Competition and Markets Authority enforces consumer protection statutes on sustainability credential communications. London and Manchester sustain curated maternity boutiques providing tactile evaluation and expert fitting consultation.
Maternity Leggings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The structure fragments between mass-market accessibility and premium medical-grade engineering credentials. Three archetypes dominate: technical performance specialists leveraging R&D infrastructure, design-led positioning specialists emphasizing soft fabric blends, and medical-grade support engineers differentiating through clinical validation. Dominant competitive moves include subscription replenishment model deployment and seamless 3D knitting technology licensing.
Within the technical performance tier, Lululemon represents channel-controlling capabilities through technical fabric R&D infrastructure extension. Among design-led specialists, Beyond Yoga occupies a position emphasizing soft modal blends for prenatal yoga practitioners. On the medical-grade vector, Blanqi exemplifies support engineering differentiation from fashion-oriented alternatives. These three companies anchor the competitive spectrum from athletic crossover through clinical validation.
| Leading Market Players |
|---|
| Ingrid + Isabel |
| Lululemon |
| Beyond Yoga |
| Blanqi |
| Quince |
| Vitality |
| Isabella Oliver |
| Ohsurewear |
| Storq |
| Others |
Supply & Pricing Matrix
Yangtze River Delta freight corridors linking Shanghai to Los Angeles and Rotterdam transmit crude oil price volatility into elastomeric yarn costs, concentrating margin pressure on Taiwanese contract manufacturers while enabling premium pricing power for brands with forward yarn commitments and certified organic positioning.
Pricing Analysis
Seamless 3D knitting technology commands a generation-ahead premium over cut-and-sew alternatives, while conventional compression lines face price erosion from commoditized spandex blends. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade FDA-registered garments from fashion-forward direct-to-consumer lines and mass-market cotton basics. Price differentiation centers on certification tier—OEKO-TEX Standard 100 and GOTS organic credentials—and vertical integration depth. Cost compression in entry-level polyester-spandex segments is intensifying because of petroleum feedstock exposure. Casual users exhibit highest price sensitivity; fitness enthusiasts and hospital procurement departments demonstrate lowest elasticity due to performance requirements and clinical protocols.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates risk calculus for elastomeric yarn sourcing, compelling brands to diversify toward South Korean and Vietnamese alternative suppliers. Manufacturing gravity centers on China's Yangtze River Delta for digital knitting infrastructure, Taiwan for spandex fiber production, and Germany for ISO 13485-certified clinical garment finishing. Raw material dependencies rest on petroleum-based polyurethane for spandex, beechwood pulp for modal, and recycled PET feedstock for sustainable polyester lines. Single-source vulnerability concentrates in Taiwanese spandex contract manufacturers. Distribution runs through direct-to-consumer platforms for premium positioning, hospital procurement frameworks for medical-grade volumes, and specialty maternity boutiques for tactile evaluation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The maternity leggings market sits in early-cycle expansion as hospital discharge protocols in Germany and the Netherlands embed graduated compression garments into standard maternal care pathways, creating institutional demand tailwinds beyond discretionary consumer purchase cycles.
For Market Incumbents: Harden technical moats through exclusive seamless 3D knitting licensing agreements and captive supply of OEKO-TEX pre-certified organic cotton yarn stocks. Deepen backward integration into Taiwanese elastomeric fiber production to offset petroleum price volatility. Prioritize ISO 13485 certification investment to capture NHS England and Kaiser Permanente hospital procurement unbundling trends before generalist apparel suppliers adapt. For New Entrants and Emerging Players: Build out algorithmic fit prediction infrastructure targeting trimester-based subscription replenishment models, where predictive sizing based on gestational week inputs reduces return rates and captures lifetime value. The most penetrable white space sits in postpartum athletic crossover segments addressing diastasis recti recovery, where existing players under-serve the twelve-month window after delivery. Launch through Instagram and Pinterest discovery funnels targeting California and New York prenatal fitness practitioners. For Investors and Strategic Acquirers: Carve-out targets emerge from generalist apparel conglomerates with dormant maternity lines lacking technical pattern engineering capabilities or certification relationships. Long-term viability hinges on whether brands can bridge medical-grade clinical validation with lifestyle apparel margins. The acquisition archetype to prioritize: specialized manufacturers with ISO 13485 quality management systems and established hospital procurement channel access. Watch FDA medical-device pathway expansion signals as the inflection indicator for reimbursement-driven volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless 3D Knitting Licensing | Enables zero-waste production and size-inclusive manufacturing from XXS to 6XL in single runs. |
| OEKO-TEX and GOTS Certification Investment | Accelerates product launch timelines by sixteen to twenty-four months for emerging brands. |
| Subscription Replenishment Model Deployment | Captures gestational-week-based size progression through automated fit algorithms in direct-to-consumer channels. |
| Hospital Procurement Framework Entry | Positions brands for NHS England and Kaiser Permanente standalone clinical garment category tenders. |
| Biomaterial Convergence R&D | Integrates TENCEL Lyocell with recycled ocean plastic yarns for Scandinavian market compliance. |
Research Methodology
A standing panel of maternity apparel technical designers, hospital procurement managers, direct-to-consumer brand operators, and OEKO-TEX certification auditors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FDA medical-device registration databases, EU ECHA REACH consultation filings, and NHS England supply framework tender documents. Bottom-up triangulation across gestational-week demand modeling and top-down cross-checks against elastomeric fiber trade flow data anchored volume estimates.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation dimensions spanning product type, fabric composition, retail channel, and customer application context. CAGRs derived from fitted growth curves incorporating working professional adoption rates, hospital prescription protocol expansion, and digital knitting capacity deployment trajectories. Industry-specific forecast inputs included spandex feedstock price elasticity coefficients and trimester-based size progression replenishment frequency data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated athletic apparel conglomerates or fast-fashion entrants with digital knitting capabilities would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Stockings Market
Apparel Textiles
Europe Textile Garment Market