
 GCC PVC Pipes Market | 2026-2036
GCC PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
GCC PVC Pipes Market Intelligence
Advanced compounding with impact-modified PVC formulations is rewriting durability benchmarks for desert-climate infrastructure across the Gulf. Napco leverages backward integration into resin production to secure feedstock cost advantages. Wavin anchors its position through specialized pressure-pipe systems engineered for high-salinity groundwater conditions. Orbia competes via technology leadership in molecularly oriented PVC, which delivers superior hoop stress performance.
PVC pipes are thermoplastic conduits manufactured from polyvinyl chloride resin blended with stabilizers, plasticizers, and impact modifiers, extruded through single-screw or twin-screw processes to specified dimensional tolerances; they transport fluids and protect electrical cabling across corrosive soil and saline water environments. Rigid pipes dominate volume shipments for buried municipal water supply networks where ring stiffness governs specification. Flexible pipes sustain faster growth in trenchless rehabilitation applications across aging districts in Dubai and Manama. Fittings capture disproportionate margin pools due to custom molding complexity and shorter production runs.
Saudi Standards, Metrology and Quality Organization (SASO) mandates compliance with Gulf Standardization Organization (GSO) pipe specifications for potable water contact. The UAE's Ministry of Energy and Infrastructure enforces pressure-rating certifications for buried drainage systems in flood-prone coastal zones. Abu Dhabi Quality and Conformity Council (QCC) testing protocols for lead-free stabilizer migration are tightening formulation requirements. Stakeholders must monitor how evolving green building codes across Kuwait and Oman will recalibrate recycled-content thresholds before committing to multi-year resin supply agreements.
Market Dynamics
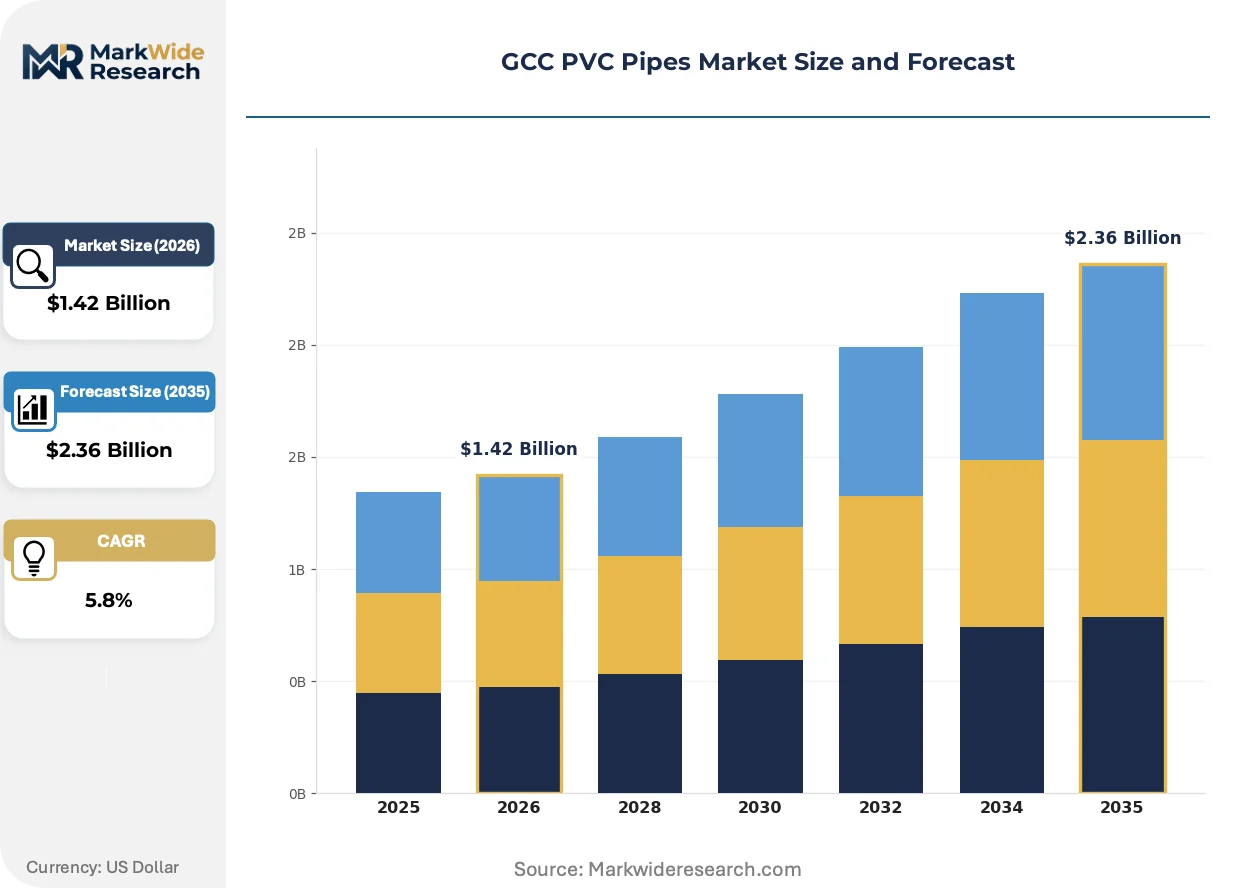
Impact-modified PVC formulations and molecular orientation technologies are compressing replacement cycles for desert-climate infrastructure, while Saudi Vision 2030 and Qatar National Vision 2030 channel capital toward pipeline networks that must withstand saline groundwater and thermal stress.
Growth Catalysts
- SASO-GSO Compliance Mandates:Saudi Standards, Metrology and Quality Organization enforcement of Gulf Standardization Organization specifications for potable water contact is disqualifying non-compliant imports and consolidating procurement toward certified domestic producers.
- Megaproject Corridor Concentration:Saudi Arabia's Riyadh-Jeddah-Red Sea development axis is generating concentrated demand for high-pressure distribution networks in arid zones with corrosive soil chemistry.
- Trenchless Rehabilitation Uptake:Flexible PVC pipe systems are capturing share in Dubai and Manama's aging district renewal programs where minimal surface disruption commands specification priority.
Market Restraints
- Resin Price Volatility:Feedstock cost swings in ethylene and chlorine derivatives compress margin predictability for extruders lacking backward integration into resin production.
- Lead-Free Stabilizer Migration:Abu Dhabi Quality and Conformity Council testing protocols are forcing formulation changes that increase compound costs and require requalification of existing product lines.
- High-Density Polyethylene Substitution:HDPE pipes are displacing PVC in select trenchless applications where flexibility and fusion welding offer installation advantages in rocky substrate conditions.
Strategic Opportunities
- Kuwait Green Building Code Alignment:Evolving recycled-content thresholds in Kuwaiti construction regulations will reward early movers with pre-qualified compound formulations before multi-year resin supply agreements lock in.
- Oman Coastal Infrastructure:Underpenetrated municipal water networks in Oman's flood-prone coastal zones present specification opportunities for pressure-rated systems with enhanced ring stiffness.
- Smart Leak Detection Integration:Convergence of PVC pressure pipes with embedded sensor networks and IoT monitoring platforms is opening premium specification tiers in Saudi Arabia's NEOM and Red Sea Project developments.
Industry Challenges
- Compound Formulation Expertise Gap:Scarce technical talent in impact-modifier blending and thermal stabilizer selection is extending product development timelines for specialized desert-climate grades.
- Multi-Jurisdiction Certification Burden:Divergent testing protocols across SASO, UAE Ministry of Energy and Infrastructure, and QCC are fragmenting compliance costs and delaying market entry for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC PVC Pipes Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Pipes, Flexible Pipes, Foam Pipes, Fittings End User: Construction, Agriculture, Oil & Gas, Infrastructure Application: Water Supply, Drainage, Irrigation, Sewage Size: 1 inch, 2 inch, 3 inch, 4 inch |
| Companies Covered | Napco, Wavin, SABIC, Borealis AG, Uponor Corporation, Aliaxis, GF Industry and Infrastructure Flow Solutions, Orbia, JM Eagle, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC PVC Pipes Market Strategic Shifts & Innovations
Material science advances and regulatory tightening are compressing traditional specification boundaries, while procurement centralization around state-backed megaprojects is privileging suppliers with demonstrated desert-climate performance records.
Molecularly oriented PVC (PVC-O) is rendering obsolete conventional unplasticized PVC in high-pressure water distribution applications. Saudi Arabia's National Water Company and UAE's Etihad Water and Electricity are specifying PVC-O for trunk mains where hoop stress performance reduces wall thickness and installation labor. This technology is rendering obsolete legacy extrusion lines incapable of biaxial orientation, consolidating production capacity toward specialized equipment holders.
Abu Dhabi Quality and Conformity Council's lead-free stabilizer migration protocols are tightening formulation requirements for all potable water contact applications. Industrial consequence includes accelerated phase-out of calcium-zinc and organotin systems in favor of calcium-organic complexes with higher raw material costs. Fittings manufacturers face disproportionate impact due to shorter production runs and custom molding complexity that amplifies reformulation economics.
Centralized procurement through Saudi Arabia's National Water Company and Qatar's Kahramaa is consolidating buyer power and compressing supplier margins. Traditional distributor networks are losing share to direct manufacturer-contractor relationships in megaproject corridors. This concentration is most visible in Riyadh and Doha where single-source framework agreements now govern multi-year pipeline supply for entire development zones.
GCC PVC Pipes Market Segmentation
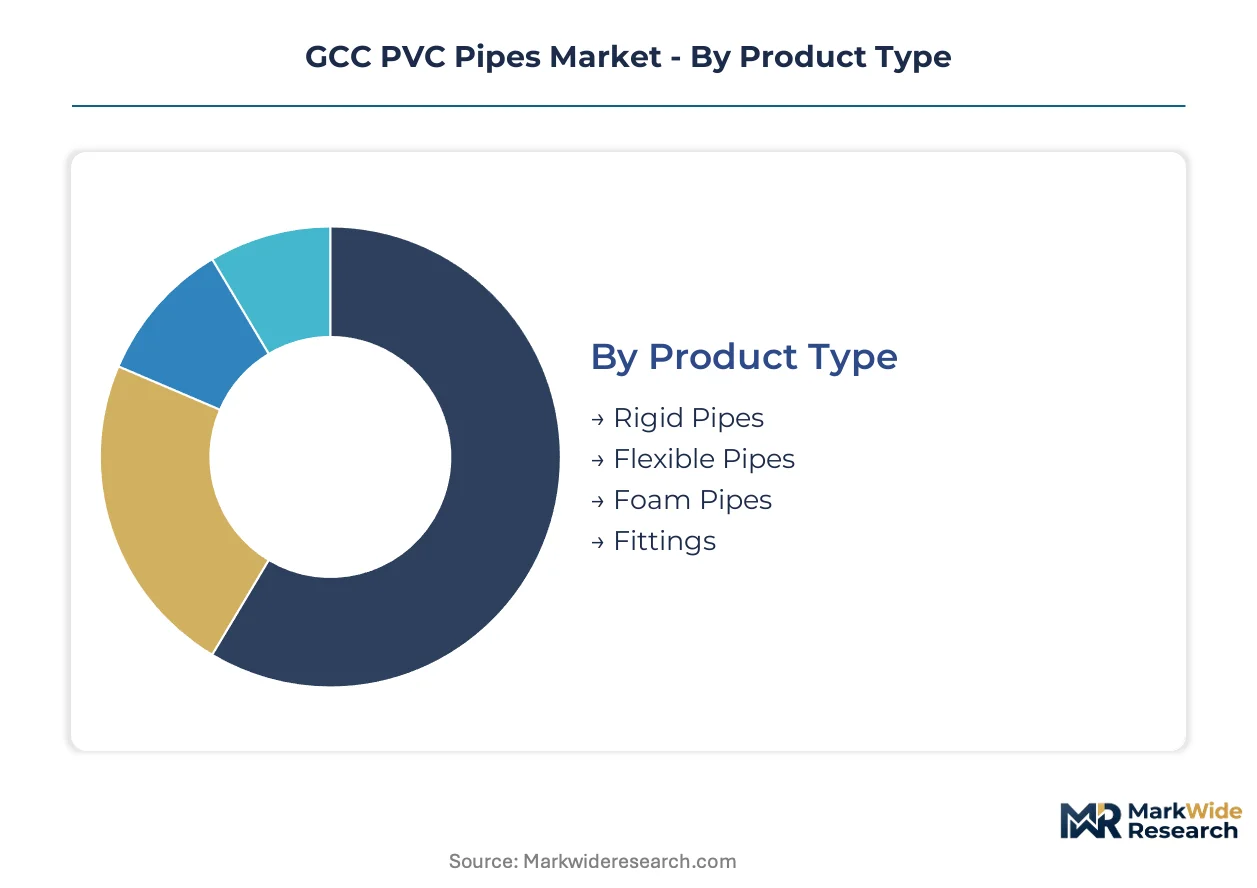
PVC pipe specification across the Gulf Cooperation Council hinges on matching material rigidity to soil chemistry, pressure ratings to groundwater salinity, and diameter to flow velocity requirements. Procurement officers in Saudi Arabia's National Water Company and Qatar's Kahramaa weight segment selection against installation labor costs and trenchless rehabilitation compatibility.
Product Type:
Replacement cycles vary sharply across product types, with rigid buried infrastructure turning over every 25-40 years while flexible trenchless systems refresh within 10-15 year windows as rehabilitation technology advances.
- Rigid Pipes:Unplasticized PVC formulations extruded to high ring stiffness specifications dominate buried municipal water networks across the Riyadh-Jeddah corridor. Saudi Vision 2030 trunk main projects specify these for corrosive soil conditions where dimensional stability governs performance.
- Flexible Pipes:Plasticized PVC compounds enable coiling and tight-radius installation without joint failure. Dubai and Manama's aging district renewal programs specify these for minimal surface disruption where trenchless technology commands priority.
- Foam Pipes:Cellular-core construction reduces weight for above-ground drainage in Oman's coastal flood zones where handling efficiency outweighs pressure rating requirements.
- Fittings:Custom-molded junctions, elbows, and reducers carry disproportionate margin pools due to shorter production runs and compound formulation complexity for lead-free stabilizer compliance.
Rigid pipes anchor the volume base while flexible pipes gain share at the steepest rate.
End User:
Cost tier stratification separates commodity-grade agricultural procurement from premium infrastructure specifications where SASO-GSO certification commands price premiums.
- Construction:Residential and commercial building contractors source standard pressure ratings for internal plumbing and storm drainage across Kuwait's green building code developments.
- Agriculture:Center-pivot and drip irrigation networks in Saudi Arabia's Qassim and Eastern Province regions specify lower-cost formulations where UV resistance outweighs pressure performance.
- Oil & Gas:Produced water handling and secondary recovery systems in Abu Dhabi's onshore fields require specialized compound grades for hydrocarbon contact resistance.
- Infrastructure:Municipal water authorities in Doha and Riyadh consolidate procurement through framework agreements for multi-year pipeline supply with embedded smart leak detection compatibility.
Infrastructure commands the premium tier while agriculture drives volume throughput.
Application:
Application selection tracks directly to fluid chemistry and pressure regime, with potable water contact triggering the strictest Abu Dhabi Quality and Conformity Council formulation requirements.
- Water Supply:Potable distribution networks across the UAE's Ministry of Energy and Infrastructure jurisdiction specify molecularly oriented PVC for reduced wall thickness and superior hoop stress performance in high-pressure trunk mains.
- Drainage:Stormwater and greywater systems in flood-prone coastal zones from Dammam to Sohar prioritize ring stiffness and joint integrity for saline groundwater exposure.
- Irrigation:Tertiary-treated wastewater distribution for landscaping and agriculture in Qatar's peri-urban zones tolerates lower compound grades where chemical resistance requirements moderate.
- Sewage:Gravity and pressure sewer mains across Bahrain's aging Manama districts specify abrasion-resistant formulations for solids handling with extended service life targets.
Water supply anchors specification value while drainage applications expand most quickly with coastal infrastructure investment.
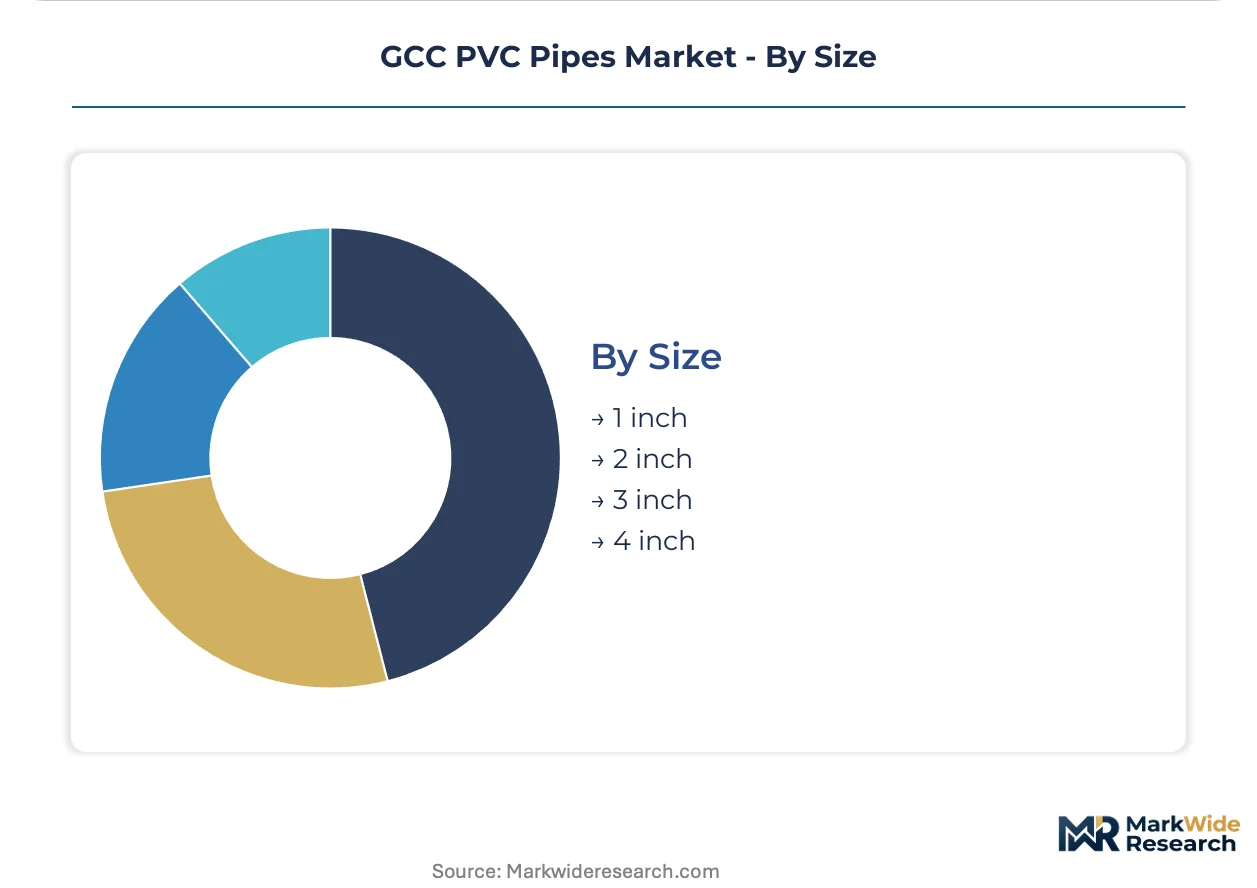
Size:
Volume concentration sits at mid-range diameters where residential and light commercial construction overlaps with small-bore municipal laterals.
- 1 inch:Internal building plumbing and residential irrigation laterals across Saudi Arabia's housing ministry projects.
- 2 inch:Commercial building risers and small-bore municipal connections in Dubai's dense urban renewal zones.
- 3 inch:Medium-pressure distribution laterals and agricultural mainlines in Qatar's expanded food security programs.
- 4 inch:Municipal service connections and commercial drainage headers where flow velocity management governs specification.
Two-inch and three-inch diameters capture the densest procurement activity while four-inch specifications climb fastest with trunk lateral expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipe shipments from Saudi Arabia's Eastern Province resin complexes supply trunk main projects across the Riyadh-Jeddah corridor and re-export to Qatar and Bahrain. The UAE's Jebel Ali hub handles compound formulations for re-export to Oman and Kuwait.
Saudi Arabia
The National Water Company consolidates procurement for Riyadh's Qiddiya and Red Sea Project developments, specifying molecularly oriented PVC for high-pressure distribution. SASO enforces GSO potable water contact standards that disqualify non-compliant imports. The Eastern Province's Jubail Industrial City hosts resin production feeding extrusion lines for megaproject corridors.
United Arab Emirates
Etihad Water and Electricity specifies reduced-wall-thickness PVC-O for saline groundwater conditions in Abu Dhabi's coastal zones. The Ministry of Energy and Infrastructure mandates pressure-rating certifications for buried drainage in flood-prone areas. Dubai's trenchless rehabilitation programs in Deira and Bur Dubai specify flexible pipe systems for minimal surface disruption.
Qatar
Kahramaa centralizes multi-year framework agreements for Doha's Lusail and Msheireb developments with embedded smart leak detection compatibility. Qatar National Vision 2030 channels capital toward pipeline networks withstand thermal stress and saline conditions. Industrial City Doha concentrates fitting production for custom junctions serving the North Field expansion's water supply infrastructure.
Kuwait
The Ministry of Public Works drives specification for South Saad Al-Abdullah City and Silk City developments under evolving green building codes. Recycled-content thresholds in construction regulations are shifting compound formulation requirements for potable water applications. Al-Zour's industrial zone hosts emerging extrusion capacity targeting infrastructure tenders.
Oman
Underpenetrated municipal networks in Sohar and Salalah's flood-prone coastal zones specify pressure-rated systems with enhanced ring stiffness. The Ministry of Housing and Urban Planning accelerates procurement for Dhofar and Al Batinah development corridors. Port of Sohar's free zone attracts compound blending operations serving cross-border projects.
GCC PVC Pipes Market Key Industry Players
On the supply side, the industry is consolidating toward producers with captive resin supply and certified compound formulation capabilities. Backward integration into ethylene derivatives separates margin-stable suppliers from extruders exposed to feedstock volatility. Two archetypes dominate: integrated petrochemical-resin-pipe conglomerates and specialized pressure-pipe system engineers. Capacity expansion in Saudi Arabia's Eastern Province and technology licensing for molecular orientation equipment represent the primary competitive vectors.
Within the integrated-resin tier, SABIC anchors regional feedstock supply while Borealis AG exemplifies European compound technology transfer into Gulf manufacturing. Among specialized system engineers, Wavin occupies a position in high-salinity groundwater applications and Orbia sits within the molecularly oriented PVC technology leadership segment. These three represent distinct strategic positions: captive raw material security, climate-specific formulation expertise, and biaxial orientation equipment mastery.
| Leading Market Players |
|---|
| Napco |
| Wavin |
| SABIC |
| Borealis AG |
| Uponor Corporation |
| Aliaxis |
| GF Industry and Infrastructure Flow Solutions |
| Orbia |
| JM Eagle |
| Others |
Cost & Logistics Intelligence
Overcapacity in Saudi Arabia's Eastern Province resin complexes is compressing feedstock margins and forcing extruders toward longer-term contract structures that lock in volume commitments before pricing power erodes further.
Pricing Analysis
Conventional unplasticized PVC, molecularly oriented PVC-O, and emerging recycled-content formulations occupy distinct pricing strata. Three-tier pricing structure across premium, standard, and economy levels separates certified potable water grades from agricultural irrigation specifications. SASO-GSO certification commands measurable premiums over uncertified imports. Cost compression in standard grades is intensifying because centralized procurement through Saudi Arabia's National Water Company and Qatar's Kahramaa extracts volume discounts. Agricultural buyers in Saudi Arabia's Qassim region exhibit highest price sensitivity, while infrastructure authorities in Abu Dhabi's coastal zones prioritize performance over unit cost.
Supply Chain Analysis
Ethylene and chlorine derivatives anchor the upstream, with resin production concentrating in Saudi Arabia, the UAE, and Qatar. Feedstock supply draws from Jubail Industrial City's petrochemical complexes and Ruwais refining corridors. Single-source vulnerability persists for molecular orientation equipment, where European and Asian machinery suppliers control biaxial extrusion technology. Distribution runs through manufacturer-direct frameworks to megaproject contractors, bypassing traditional distributor networks in Riyadh and Doha corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-density polyethylene substitution in trenchless applications threatens PVC's installed base, requiring incumbents to articulate clear performance differentiation in saline groundwater conditions.
For Market Incumbents: Build formulation expertise moats around impact-modified compounds for desert-climate durability. Secure backward integration into resin production to isolate margin from ethylene volatility. Invest in PVC-O capacity before equipment lead times extend. Defend against HDPE encroachment by emphasizing ring stiffness performance in corrosive soil chemistry.
For New Entrants and Emerging Players: Establish a beachhead in Oman's underpenetrated coastal infrastructure segment where pressure-rated system demand outstrips certified supply. Target Kuwait's evolving green building code compliance window before recycled-content thresholds lock in incumbent formulations. Pursue direct contracting relationships with Oman Ministry of Housing and Urban Planning tenders.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across molecular orientation equipment installations, favoring scaled producers over fragmented extrusion operators. Five-to-ten year viability hinges on captive resin supply and multi-jurisdiction certification capabilities. Acquisition targets should demonstrate SASO, QCC, and UAE Ministry of Energy compliance portfolios. Monitor centralized procurement contract awards to Saudi National Water Company as inflection signal for supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive ethylene supply from Jubail complexes insulates margin from feedstock volatility. |
| PVC-O Capacity Expansion | Biaxial orientation equipment mastery secures specification in Saudi trunk main projects. |
| Lead-Free Stabilizer Reformulation | Abu Dhabi QCC compliance opens premium potable water contact applications. |
| Smart Leak Detection Integration | Embedded sensor compatibility commands specification in NEOM and Red Sea developments. |
| Kuwait Green Building Code Alignment | Pre-qualified recycled-content compounds capture regulatory shift before supply agreements lock. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with resin procurement directors, extrusion plant managers, municipal water authority engineers, and distribution channel partners; and secondary validation through SASO technical regulations, UAE Ministry of Energy infrastructure standards, GSO harmonized specifications, customs trade data for PVC resin imports, and project tender databases for megaproject corridors. Bottom-up shipment estimates from individual extrusion lines were triangulated against top-down demand projections from national water company capital expenditure disclosures.
Forecast inputs encompassed product type segmentation across rigid, flexible, and molecularly oriented grades; end-user stratification between infrastructure, construction, agriculture, and oil and gas applications; and diameter-based sizing tiers. CAGRs were derived from regression analysis of historical shipment volumes against announced project pipelines across the projection horizon. Industry-specific inputs included thermal stress coefficients for desert-climate performance and saline groundwater corrosion indices.
Macroeconomic conditions sit as an overlay; deviation in oil-linked ethylene pricing, construction labor availability, or sovereign project funding timelines would shift the trajectory. Forecasts reflect documented assumptions regarding SASO enforcement consistency and megaproject execution schedules. Cross-checking against National Water Company annual procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Global Hydraulic Thermoplastic Hose and Couplings Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
China Industrial Hoses Market