
 Magnesium Stearate Market | 2026-2036
Magnesium Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Stearate Market Outlook
Continuous manufacturing technology is reshaping pharmaceutical excipient procurement, as direct compression and hot-melt extrusion methods demand tighter particle-size distribution and batch-to-batch consistency from lubricant suppliers. Baerlocher GmbH leverages backward integration into stearic acid feedstock to secure supply continuity across European pharma clients. Peter Greven GmbH & Co. KG anchors its position through specialized magnesium stearate grades tailored to high-shear blending environments. Valtris Specialty Chemicals competes on geographic reach, operating production assets across multiple North American sites to reduce logistics risk for just-in-time buyers.
Magnesium stearate is a metallic salt of stearic acid, typically containing 4-5% magnesium content with a bulk density of 0.15-0.30 g/cm³, synthesized through saponification of fats or direct reaction of magnesium oxide with stearic acid, serving primarily as a lubricant and flow agent in solid-dose manufacturing. Pharmaceutical Grade dominates value capture due to USP-NF and EP compliance burdens that limit supplier qualification, while Food Grade applications in salt and seasoning anticaking represent a mature volume channel with thinner margins. Tablet Manufacturing as an application concentrates demand among the top twenty global generic drug producers, who account for disproportionate excipient procurement volumes.
FDA's ICH Q3D elemental impurity guidelines and EMA's updated excipient risk assessment frameworks jointly elevate analytical testing costs, filtering smaller compounders from qualified supplier lists. India's CDSCO mandates excipient import registration with local stability data, creating regulatory friction for foreign manufacturers while advantaging domestic producers like Nimbasia Stabilizers. REACH registration deadlines for fatty acid derivatives in Europe add compliance layering that favors established registrants over new market entrants. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP and JP standards, as divergence in heavy metal limits or specific surface area specifications could force dual-sourcing strategies or dedicated regional production lines.
Market Dynamics
Continuous manufacturing adoption in pharmaceutical tablet production is compressing batch sizes and tightening particle-size specifications for lubricant suppliers, forcing capital retooling across magnesium stearate production networks.
Growth Catalysts
- Direct Compression Expansion:High-speed tablet presses at generic drug facilities in India demand magnesium stearate with sub-50 micron particle distribution, pulling volume toward specialized grades.
- FDA ICH Q3D Implementation:Elemental impurity testing mandates are filtering unqualified suppliers, concentrating procurement among certified manufacturers with validated analytical protocols.
- India CDSCO Localization Push:Domestic excipient registration requirements with local stability data are redirecting import demand toward Indian producers with in-country manufacturing assets.
Market Restraints
- Palm Oil Feedstock Volatility:Stearic acid precursor costs fluctuate with Malaysian and Indonesian palm oil output cycles, squeezing margin predictability for non-integrated compounders.
- European REACH Registration Burden:Fatty acid derivative compliance deadlines favor established registrants with dedicated regulatory affairs teams, blocking smaller Asian exporters from EU market access.
- Alternative Lubricant Substitution:Sodium stearyl fumarate and glycerol behenate are displacing magnesium stearate in moisture-sensitive formulations, constraining volume in high-humidity climates.
Strategic Opportunities
- Brazil ANVISA Pre-Qualification Gap:Few magnesium stearate suppliers hold active pharmaceutical ingredient excipient certification for Latin America's largest generic drug market.
- Hot-Melt Extrusion Convergence:Combination with twin-screw processing equipment opens formulation services bundling lubricant supply with process development for specialty dosage forms.
- EU Green Deal Bio-Based Mandates:Renewable carbon content thresholds for pharmaceutical excipients create premium positioning for vegetable-derived stearic acid grades versus tallow-based alternatives.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent heavy metal limits between USP, EP and JP standards force dual inventory management and regional production line segregation.
- Continuous Manufacturing Integration:Real-time release testing protocols require lubricant suppliers to align batch records with pharmaceutical clients' process analytical technology systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Stearate Market |
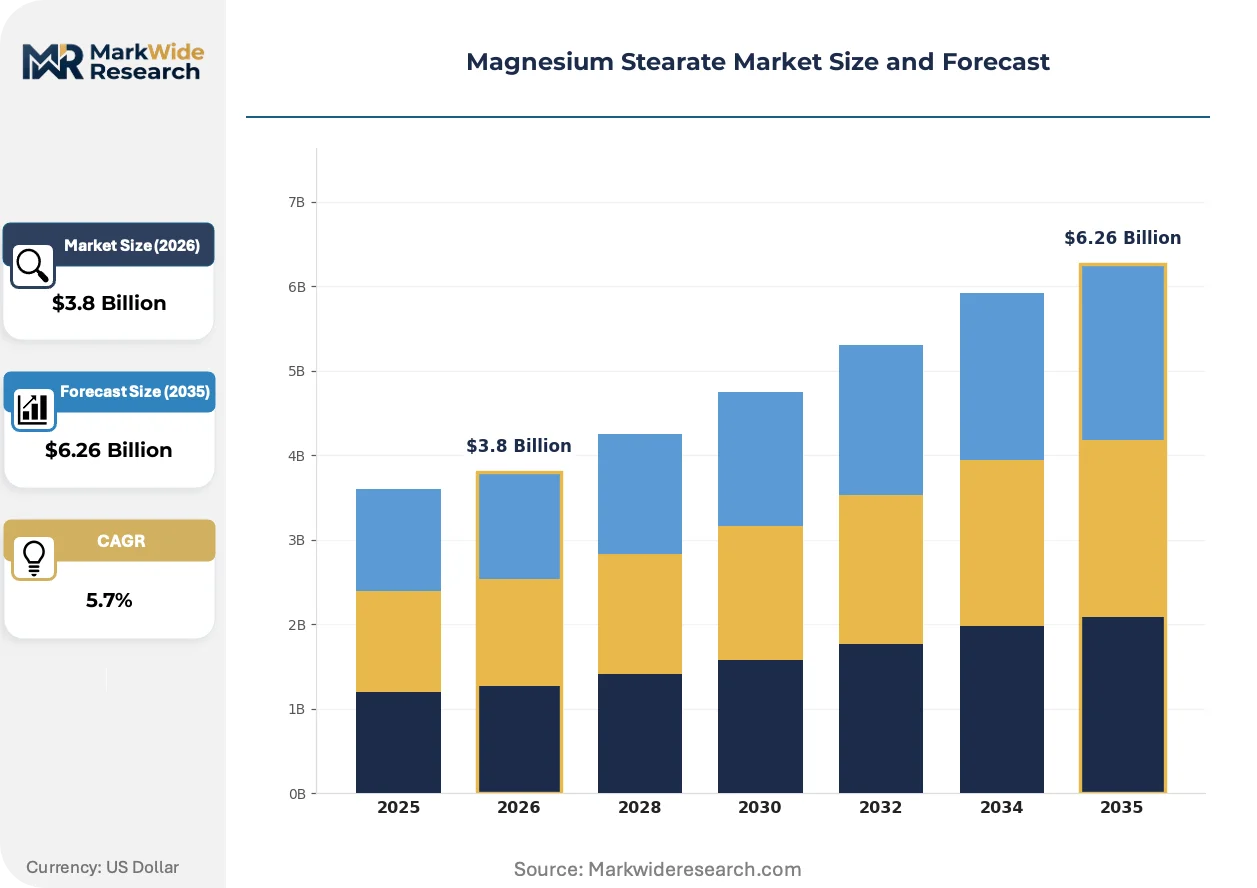
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade End User: Pharmaceuticals, Food & Beverage, Personal Care, Plastics Application: Tablet Manufacturing, Food Fortification, Coating Agent, Anticaking Agent Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Baerlocher GmbH, Peter Greven GmbH & Co. KG, Valtris Specialty Chemicals, Faci S.p.A, Nimbasia Stabilizers, Struktol Company of America LLC, Mallinckrodt Pharmaceuticals, PMC Biogenix, James M. Brown Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Stearate Market Strategic Shifts
Process analytical technology and real-time particle characterization are redefining quality assurance protocols, compressing traditional batch release timelines while elevating supplier technical service requirements.
Granular magnesium stearate with controlled surface area specifications is migrating from conventional batch blending toward continuous direct compression lines at European generic manufacturers. Pfizer and Novartis contract manufacturing sites in Germany and Ireland now specify surface area ranges of 3-7 m²/g for high-shear environments. This migration from loose bulk density grades is compressing supplier qualification cycles and favoring producers with in-line laser diffraction capabilities.
EMA's updated excipient risk assessment framework now mandates supply chain transparency documentation for all new drug applications, effective across EU member states. The industrial consequence is a documentation burden that favors incumbent suppliers with decade-long audit histories over emerging Asian competitors. Oral solid dosage form filings from Indian and Chinese drug sponsors face extended review timelines where magnesium stearate traceability gaps trigger deficiency letters.
Consolidated procurement at top-twenty generic drug producers is compressing supplier rosters from multi-source models toward single-source partnerships with technical service attachments. Purchasing departments at Teva, Viatris and Sandoz now bundle lubricant supply with formulation troubleshooting support, displacing spot-buy arrangements. This concentration is most visible in India, where domestic API producers like Aurobindo and Dr. Reddy's have halved their qualified magnesium stearate vendor lists since 2022.
Magnesium Stearate Market Segmentation
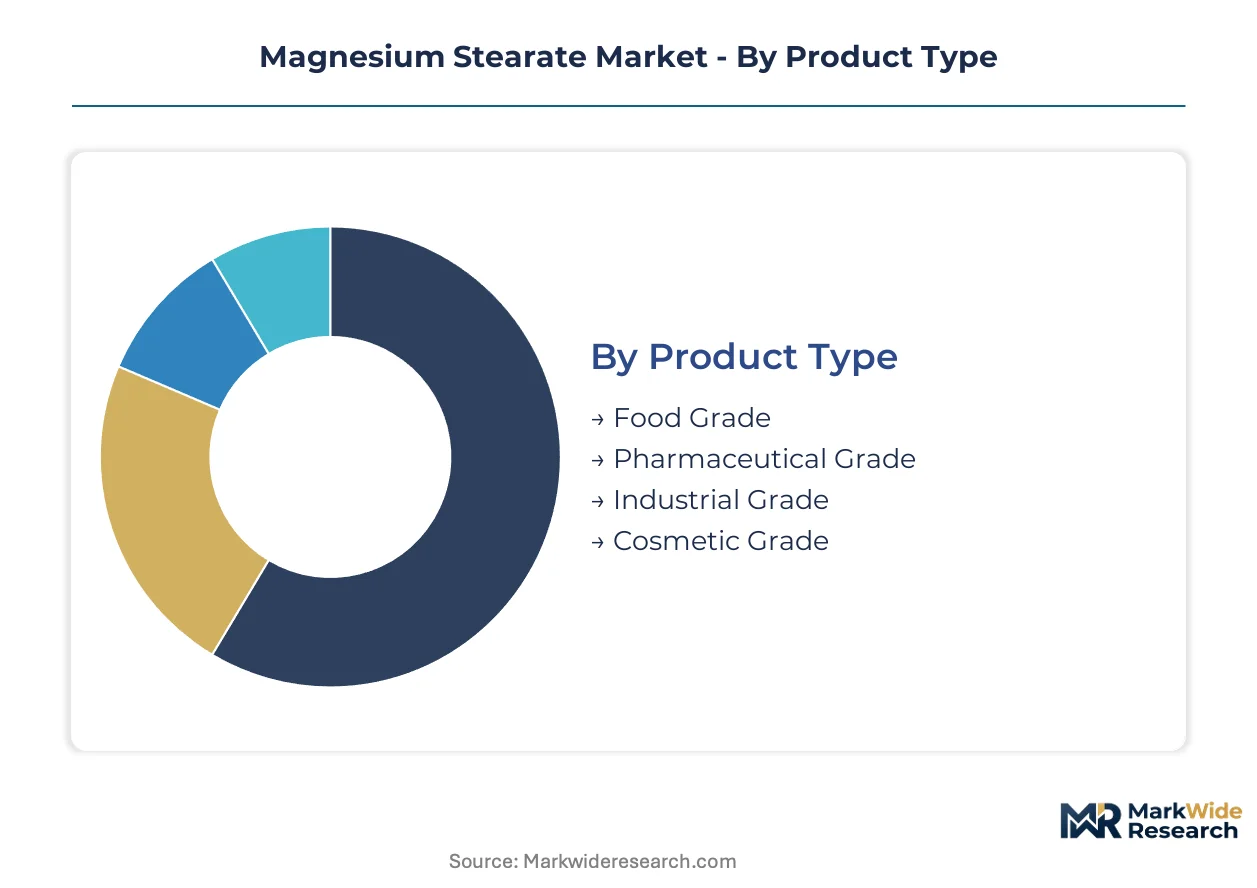
Magnesium stearate specifications diverge sharply across end-use contexts, with pharmaceutical purity requirements creating insurmountable qualification barriers for commodity producers. Segmentation clarity enables buyers to match grade specifications with process tolerances while suppliers optimize production assets against margin profiles.
Product Type:
Mature pharmaceutical specifications coexist with emerging sustainability-driven grades as feedstock provenance gains regulatory weight across European and North American procurement offices.
- Pharmaceutical Grade:USP-NF and EP compliance mandates metallic content below 20 ppm lead and 3 ppm arsenic, with specific surface area controlled to 3-7 m²/g for high-shear tablet presses. CDSCO registration requirements in India concentrate procurement among domestic producers with validated stability data, filtering import competition.
- Food Grade:FSSAI and FDA food additive specifications govern anticaking applications in salt and seasoning blends, where bulk density of 0.15-0.25 g/cm³ ensures uniform dispersion. Margin compression is severe as commodity compounders compete on volume tenders from multinational food processors.
- Industrial Grade:Lubricant and release agent applications in polymer processing tolerate higher moisture content and broader particle-size distribution. Demand tracks automotive and construction plastics output cycles with minimal regulatory overlay.
- Cosmetic Grade:INCI-listed variants for pressed powder formulations require micronized particle distribution below 10 microns and heavy metal thresholds stricter than industrial grades but below pharmaceutical benchmarks.
Pharmaceutical Grade retains volume leadership; Cosmetic Grade holds the steepest expansion curve as clean beauty formulations displace talc-based alternatives.
End User:
Customer concentration patterns split between consolidated pharmaceutical procurement and fragmented food service channels, dictating entirely different sales force structures and technical support investments.
- Pharmaceuticals:Direct compression and hot-melt extrusion methods at Teva, Viatris and Sandoz manufacturing sites specify sub-50 micron particle distribution with batch-to-batch consistency validated through laser diffraction protocols. ICH Q3D elemental impurity testing has halved qualified vendor lists since implementation.
- Food & Beverage:Salt anticaking represents a mature volume channel with specification commoditization, where procurement favors long-term supply contracts over technical differentiation. Seasoning blend manufacturers in India and Brazil drive regional volume concentration.
- Personal Care:Pressed powder and emulsion stabilization applications demand cosmetic-grade certification with heavy metal documentation for EU and ASEAN cosmetic directive compliance.
- Plastics:PVC and polyolefin processing uses magnesium stearate as internal and external lubricant, with demand tied to construction and packaging polymer output.
Pharmaceuticals dominates value capture; Personal Care is expanding most quickly as pressed powder formulations gain share in Southeast Asian markets.
Application:
Process technology migration from batch to continuous manufacturing is fragmenting application requirements, with real-time release testing protocols forcing supplier technical service attachments.
- Tablet Manufacturing:Lubricant function reduces ejection force and die wall friction in solid-dose production, with concentration typically 0.25-1.0% w/w. High-speed presses at Indian generic facilities demand specialized grades for high-shear blending environments.
- Anticaking Agent:Salt and seasoning applications exploit magnesium stearate's hydrophobic surface properties to prevent moisture-induced clumping, with usage rates of 0.5-2.0% by weight.
- Coating Agent:Film-forming applications in nutritional supplements and confectionery require specific viscosity grades with controlled particle morphology.
- Food Fortification:Micronutrient encapsulation uses magnesium stearate as processing aid in vitamin and mineral premix manufacturing, with regulatory status varying across national food additive frameworks.
Tablet Manufacturing retains volume leadership; Coating Agent shows the steepest expansion trajectory as functional confectionery segments proliferate.
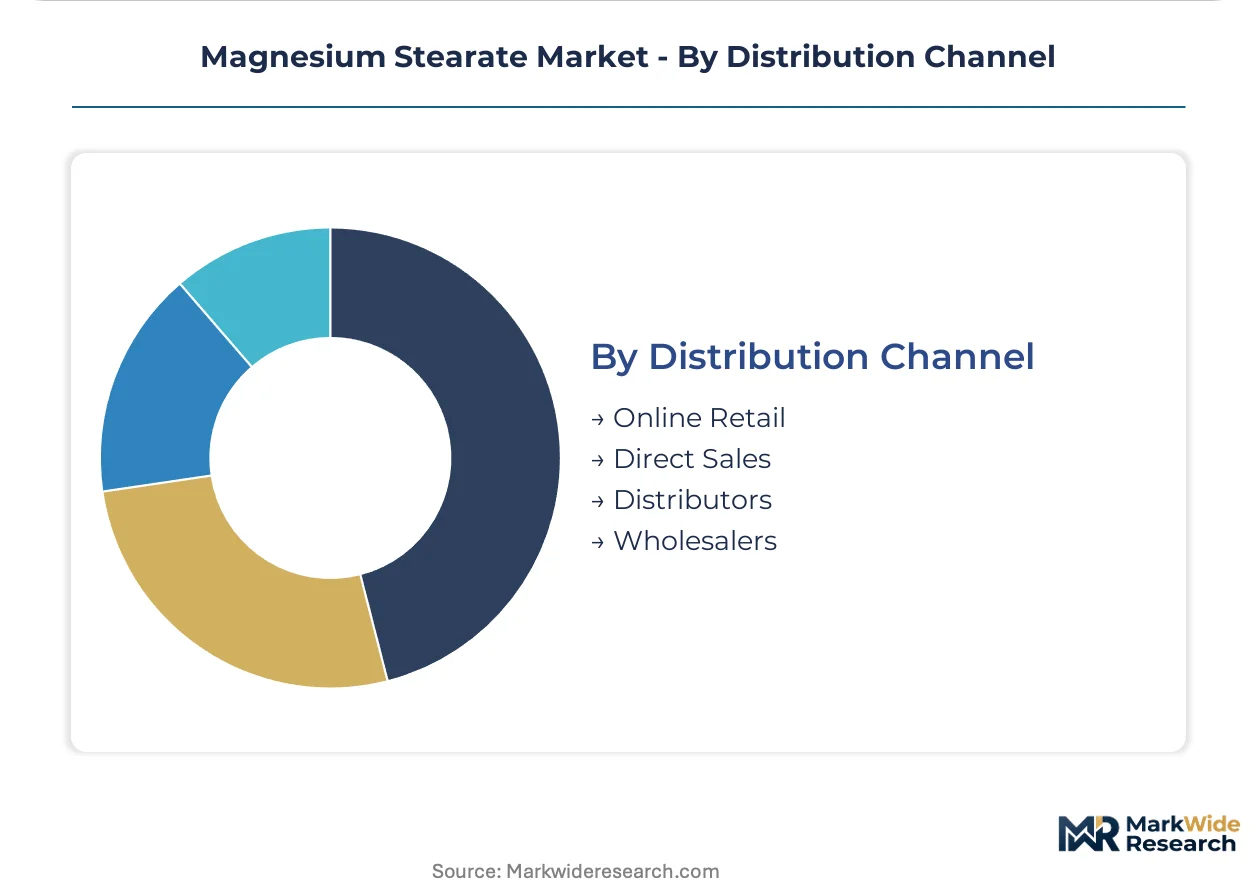
Distribution Channel:
Channel economics reflect customer scale concentration, with direct sales capturing technical grade premiums and distributor networks serving fragmented regional accounts.
- Direct Sales:Pharmaceutical and multinational food manufacturers procure through qualified supplier agreements with embedded technical service and audit documentation. EMA excipient risk assessment frameworks mandate supply chain transparency that favors direct relationships.
- Distributors:Regional chemical distributors serve mid-tier compounders and specialty manufacturers with inventory pooling and smaller minimum order quantities.
- Wholesalers:Bulk commodity grades for industrial applications move through established chemical wholesale networks with price transparency and limited technical support.
- Online Retail:E-commerce platforms capture small-laboratory and research-scale demand, with limited penetration in validated pharmaceutical supply chains due to qualification requirements.
Direct Sales commands value concentration; Online Retail is gaining share fastest among research-scale and clean beauty formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward regional self-sufficiency as pharmaceutical manufacturers reduce supply chain exposure. Countries with integrated stearic acid feedstock and domestic excipient registration systems are capturing procurement shifts from import-dependent markets.
United States
FDA's ICH Q3D elemental impurity guidelines are filtering supplier qualification lists toward domestic compounders with validated analytical protocols. The agency's emphasis on supply chain documentation favors established registrants over new import entrants. New Jersey and Pennsylvania host concentrated generic drug manufacturing clusters where Teva and Viatris facilities specify sub-50 micron particle distribution grades.
Germany
EMA's updated excipient risk assessment framework mandates transparency documentation that advantages decade-long audit histories. REACH registration deadlines for fatty acid derivatives create compliance layering favoring established European producers. The Rhine-Ruhr industrial corridor anchors magnesium stearate production assets serving Pfizer and Novartis contract manufacturing sites with surface area specifications of 3-7 m²/g.
India
CDSCO mandates excipient import registration with local stability data, redirecting demand toward domestic producers with in-country manufacturing assets. The country's API production expansion drives disproportionate excipient procurement volumes among top-twenty global generic drug producers. Hyderabad and Ahmedabad clusters concentrate formulation facilities where Aurobindo and Dr. Reddy's have halved qualified vendor lists since 2022.
China
NMPA alignment with ICH Q3D standards is elevating analytical testing requirements for export-oriented manufacturers. Domestic pharmaceutical production growth is absorbing capacity previously directed toward international markets. The Yangtze River Delta hosts chemical processing hubs where stearic acid derivative production tracks palm oil feedstock import cycles.
Brazil
ANVISA pre-qualification gaps in pharmaceutical-grade excipient certification create entry barriers for foreign suppliers. Local generic drug manufacturing expansion is pulling regional procurement toward qualified import channels. São Paulo state concentrates formulation facilities where domestic salt and seasoning anticaking demand provides parallel volume channels.
Magnesium Stearate Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: integrated feedstock producers, specialized pharmaceutical-grade compounders, and regional commodity suppliers. Tier-one players control stearic acid sourcing through backward integration into palm and tallow derivatives. Tier-two specialists compete on pharmacopeial compliance and batch-to-batch consistency. Tier-three regional actors serve industrial and food-grade applications with thinner margins. Dominant competitive moves include geographic expansion through production asset replication and portfolio diversification into adjacent metallic stearates.
Within the integrated feedstock tier, Baerlocher GmbH and Peter Greven GmbH & Co. KG exemplify European producers leveraging backward integration into stearic acid supply. Valtris Specialty Chemicals occupies a position among North American multi-site operators reducing logistics risk for just-in-time pharmaceutical buyers. These three entities represent distinct archetypes: the German integrated chemical group, the family-owned specialty compounder, and the geographically distributed industrial chemicals platform.
| Leading Market Players |
|---|
| Baerlocher GmbH |
| Peter Greven GmbH & Co. KG |
| Valtris Specialty Chemicals |
| Faci S.p.A |
| Nimbasia Stabilizers |
| Struktol Company of America LLC |
| Mallinckrodt Pharmaceuticals |
| PMC Biogenix |
| James M. Brown Ltd |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam-Frankfurt logistics corridor shapes magnesium stearate cost dynamics across European pharmaceutical supply chains, concentrating pricing power among backward-integrated producers while downstream buyers face tiered premiums tied to certification grade and particle-size specifications.
Pricing Analysis
Industrial OEM buyers anchor commodity-grade pricing at thin margins, while pharmaceutical procurement stratifies across premium, standard, and economy tiers. USP-NF and EP compliance burdens drive 40-60% price premiums over food-grade equivalents, with sub-50 micron particle distribution commanding additional technical service fees. Cost compression in industrial applications stems from palm oil feedstock volatility squeezing non-integrated compounders. Generic drug manufacturers exhibit highest price sensitivity, whereas innovator pharma tolerates premiums for batch-to-batch consistency validated through laser diffraction protocols.
Supply Chain Analysis
Contract manufacturing concentration at Pfizer and Novartis facilities in Germany and Ireland pulls specialized magnesium stearate grades toward European production hubs. Supply concentrates in Germany, India, and the United States, with stearic acid feedstock drawing from Malaysian and Indonesian palm oil cycles. Magnesium oxide, hydrogenated fats, and tallow derivatives constitute critical input dependencies. Single-source vulnerability persists for pharmaceutical-grade certification holders, as FDA ICH Q3D and EMA excipient risk assessment frameworks filter qualified supplier lists. Distribution runs through direct sales agreements with embedded technical service for pharmaceutical accounts, while regional chemical distributors serve fragmented industrial and food-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnesium stearate demand tracks pharmaceutical production cycles, with generic drug manufacturing expansion in India signaling cyclical recovery momentum through API output growth.
For Market Incumbents: Pre-empt sodium stearyl fumarate substitution in moisture-sensitive formulations by securing hot-melt extrusion partnerships with twin-screw equipment manufacturers. Deepen backward integration into stearic acid feedstock to defend margin position against palm oil price volatility, while accelerating pharmacopeial harmonization investments to reduce dual-inventory burdens from divergent USP-EP-JP standards.
For New Entrants and Emerging Players: Build out ANVISA pre-qualification capabilities for Brazil's underpenetrated pharmaceutical-grade excipient market, where few certified suppliers hold active status. Target cosmetic-grade micronized variants below 10 microns for Southeast Asian clean beauty formulators displacing talc-based alternatives, leveraging e-commerce channels to bypass established distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with neglected pharmaceutical-grade excipient divisions lacking dedicated regulatory affairs teams. Long-term viability rests on continuous manufacturing alignment and real-time release testing protocol integration. Monitor CDSCO registration acceleration rates among domestic Indian producers as inflection indicator for import substitution momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stearic Acid Feedstock | Baerlocher GmbH secures supply continuity across European pharma clients through captive Malaysian palm derivative sourcing. |
| Pharmaceutical-Grade Certification Investment | CDSCO registration with local stability data redirects Indian procurement toward domestic producers like Nimbasia Stabilizers. |
| Hot-Melt Extrusion Process Development Services | Specialized magnesium stearate grades bundled with twin-screw expertise open formulation services revenue at Pfizer contract sites. |
| Geographic Production Asset Replication | Valtris Specialty Chemicals operates multiple North American sites to reduce logistics risk for just-in-time pharmaceutical buyers. |
| EU Green Deal Bio-Based Transition | Vegetable-derived stearic acid grades command premium positioning over tallow-based alternatives under renewable carbon thresholds. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with plant managers at magnesium stearate production facilities, procurement leads at generic drug manufacturers, distribution channel partners in European chemical networks, and technical R&D directors overseeing direct compression formulations; alongside secondary validation through customs and trade data, FDA drug master file submissions, EMA excipient qualification databases, and SEC filings from publicly traded chemical conglomerates. Bottom-up volume estimates from grade-specific production capacities were triangulated against top-down pharmaceutical excipient consumption models.
Forecast inputs span pharmaceutical grade, food grade, industrial grade, and cosmetic grade tiers across tablet manufacturing, anticaking, coating, and food fortification applications, with end-use segmentation by pharmaceuticals, food and beverage, personal care, and plastics industries. CAGRs were derived from regression analysis against API production indices, continuous manufacturing adoption curves, and regulatory implementation timelines. Palm oil price volatility, pharmacopeial harmonization progress, and CDSCO registration velocity served as industry-specific forecast modifiers across the projection horizon.
Stress conditions across Malaysian palm oil supply disruptions, REACH registration deadline accelerations, and ICH Q3D enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding generic drug manufacturing expansion rates and continuous manufacturing technology diffusion. Quarterly review of CDSCO import registration volumes, EMA deficiency letter issuance rates for traceability gaps, and high-shear tablet press installation counts at Indian formulation facilities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Enzyme Stabilizer Market
Additives
Guanylic Acid Market
Additives
Tamarind Gum Derivatives Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Potting Mix Additives Market
Additives
Glycol Acetate Market
Additives
Cetane Improver Additives Market
Additives
Canada Anti-Caking Market
Additives
Global Synthetic Tackifier Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Additives for Floor Coatings Market
Additives
Packaging Coating Additives Market
Additives
Metal Deactivators Market
Additives
Feed Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Lecithin and Phospholipids Market