
 Water-Saving Cleaning Chemical Systems for Professional Use Market | 2026-2036
Water-Saving Cleaning Chemical Systems for Professional Use Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Saving Cleaning Chemical Systems for Professional Use Market Insights
The EU Green Deal's water-efficiency targets for commercial cleaning operations is pivoting procurement specifications across European facility networks. Ecolab leverages its integrated dispensing platform to capture recurring service contracts in hospitality and healthcare verticals. Diversey anchors its position through concentrated chemistry paired with IoT-enabled dilution control. Alfred Kärcher SE & Co. KG dominates mobile high-pressure cleaning applications where water recovery systems command premium positioning.
Water-saving cleaning chemical systems for professional use combine surfactant packages, chelating agents, and rinse aids engineered for reduced water volume per cleaning cycle, typically requiring dilution ratios of 1:128 to 1:512 for concentrated formats. These formulations serve commercial and industrial end users seeking to minimize effluent discharge while maintaining sanitation compliance. Concentrates command the largest revenue share due to freight and packaging cost advantages, though automated dispensing deployment is expanding fastest as labor costs rise and dilution accuracy becomes a compliance variable. Cold water systems lead in energy-sensitive segments, while hot water systems retain share in food processing and grease-intensive applications where thermal activation accelerates soil removal.
The EPA's Safer Choice standard and REACH restrictions on nonylphenol ethoxylates in Europe constrain surfactant selection, pushing formulators toward bio-based alternatives that maintain performance at lower use concentrations. Japan's METI guidelines on industrial water recycling and China's GB standards for commercial cleaning effluent add compliance layers for multinational suppliers. Facility managers and chemical procurement officers must weigh total water cost against reformulation timelines as regulatory thresholds tighten without grandfathering existing product registrations.
Market Dynamics
Facility managers across commercial laundries and food processing plants face mounting municipal water discharge fees while EPA Safer Choice and REACH surfactant toxicity thresholds tighten simultaneously. This dual pressure is compressing reformulation timelines and forcing procurement officers to recalculate total water cost equations against compliance risk.
Growth Catalysts
- EPA Safer Choice Program:The tightening allowable surfactant toxicity thresholds in the United States are accelerating bio-based formulation R&D among professional cleaning chemical suppliers serving institutional buyers.
- Commercial Laundries:Water-intensive textile service operations in Germany and Japan are retrofitting facilities with low-rinse chemistry to cut municipal discharge tariffs and meet corporate sustainability targets.
- Concentrated Chemistry:Dilution ratios of 1:128 to 1:512 are absorbing freight and packaging cost advantages that improve margin structures for distributors serving fragmented facility management networks.
Market Restraints
- Bio-based Surfactant Input Costs:Agricultural feedstock volatility for plant-derived surfactants constrains margin predictability for formulators shifting away from petroleum-based chemistry.
- REACH Registration Burden:The European Chemicals Agency's nonylphenol ethoxylate restrictions create multi-year reformulation timelines that freeze product portfolios during transition periods.
- Automated Dispensing Capex:IoT-enabled dilution control systems require upfront hardware investment that small and mid-sized cleaning contractors defer during uncertain demand cycles.
Strategic Opportunities
- China GB Standards:The country's commercial cleaning effluent regulations are creating compliance-driven upgrade cycles for multinational suppliers with pre-certified low-water formulations.
- IoT-Dispensing Convergence:Connected dilution hardware paired with concentrated chemistry enables recurring revenue service contracts that displace spot chemical purchases.
- Cold Water Segments:Energy-sensitive hospitality and healthcare facilities in Australia and South Korea are adopting ambient-temperature cleaning systems that reduce thermal activation requirements.
Industry Challenges
- Formulation Chemistry Expertise:The shortage of surfactant chemists capable of balancing bio-based performance with low-rinse efficacy is extending product development cycles for mid-tier suppliers.
- Legacy Equipment Compatibility:Existing high-pressure and steam-based cleaning infrastructure in food processing plants requires retrofitting or parallel system installation to accommodate new chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Saving Cleaning Chemical Systems for Professional Use Market |
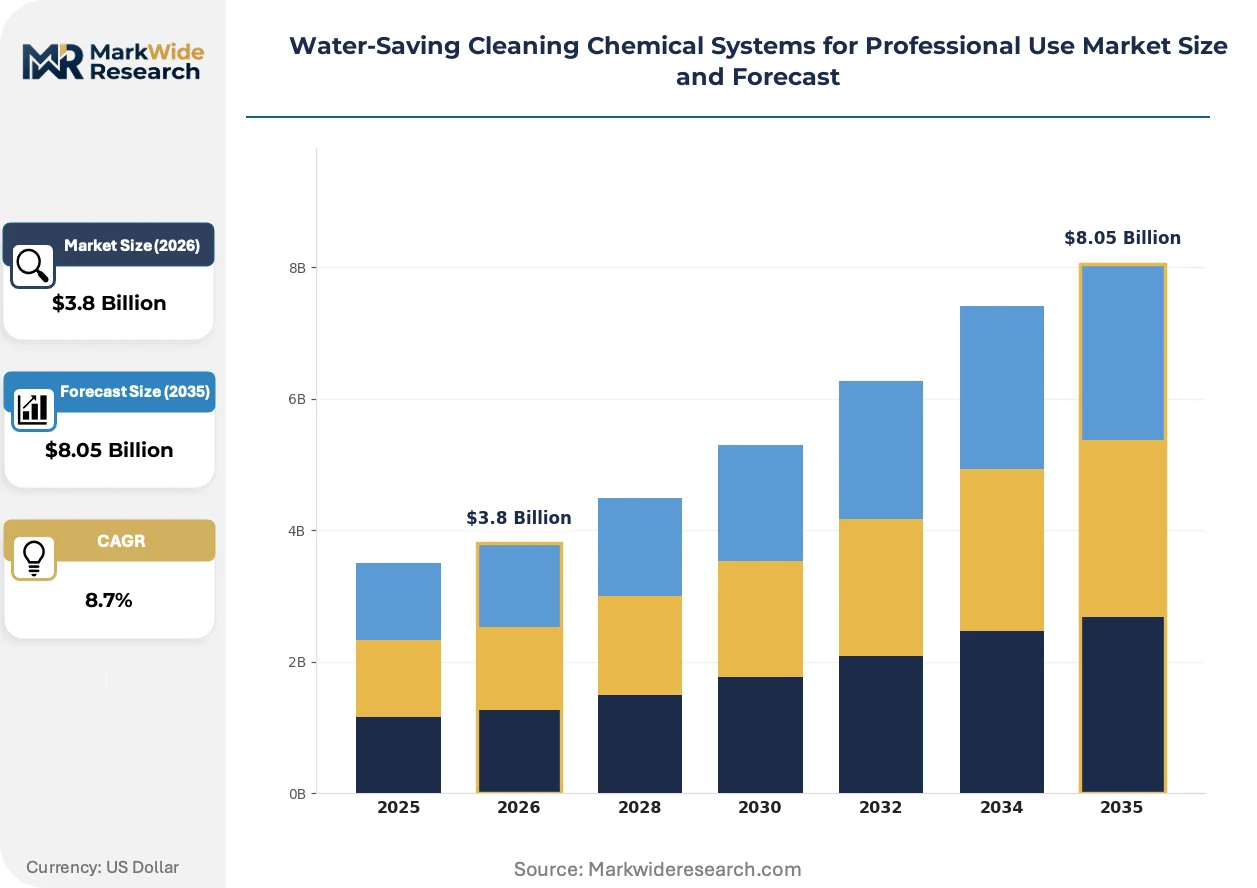
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Ready-to-Use, Powder Formulations, Gel Solutions, Foam Cleaners Application: Food Processing, Hospitality Services, Automotive Maintenance, Industrial Fabric Care, Public Facility Sanitation End User: Janitorial Services, Commercial Laundries, Facility Management, Vehicle Fleet Operators, Waste Treatment Facilities Deployment: Cold Water Systems, Hot Water Systems, High-Pressure Equipment, Automated Dispensing, Manual Application |
| Companies Covered | Ecolab, Diversey, SC Johnson Professional, Alfred Kärcher SE & Co. KG, 3M, Solenis, Zep, Betco, Spartan Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Saving Cleaning Chemical Systems for Professional Use Market Trends and Innovations
Water recovery and closed-loop filtration hardware is converging with concentrated chemical formulations to create integrated cleaning systems that treat water as a managed resource rather than disposable input. This redefinition of the value chain is compressing traditional distinctions between chemical suppliers and equipment manufacturers.
Enzymatic cold-water detergents are absorbing share from hot water formulations in grease-intensive applications where thermal activation was previously considered mandatory. Food processing plants in the Netherlands and Belgium are piloting ambient-temperature systems that maintain sanitation compliance while eliminating boiler fuel costs. The structural consequence is absorbing capital allocation away from steam infrastructure toward chemical activation technology.
REACH restrictions on nonylphenol ethoxylates are forcing European formulators toward bio-based surfactant packages that maintain performance at lower use concentrations. The industrial consequence is extended product registration timelines as suppliers validate new chemistries through ECHA compliance pathways. Professional laundries in France and Italy are most affected, responding by consolidating supplier relationships to secure reformulation support.
Facility management networks are consolidating chemical procurement through integrated dispensing platforms that bundle hardware, chemistry, and service into multi-year contracts. The spot-purchase distributor channel serving small commercial cleaners is being disrupted by vendor-managed inventory systems with telemetry-based replenishment. This pattern is most visible in North American hospital and hotel chains where procurement officers prioritize compliance documentation over unit chemistry costs.
Water-Saving Cleaning Chemical Systems for Professional Use Market Segmentation
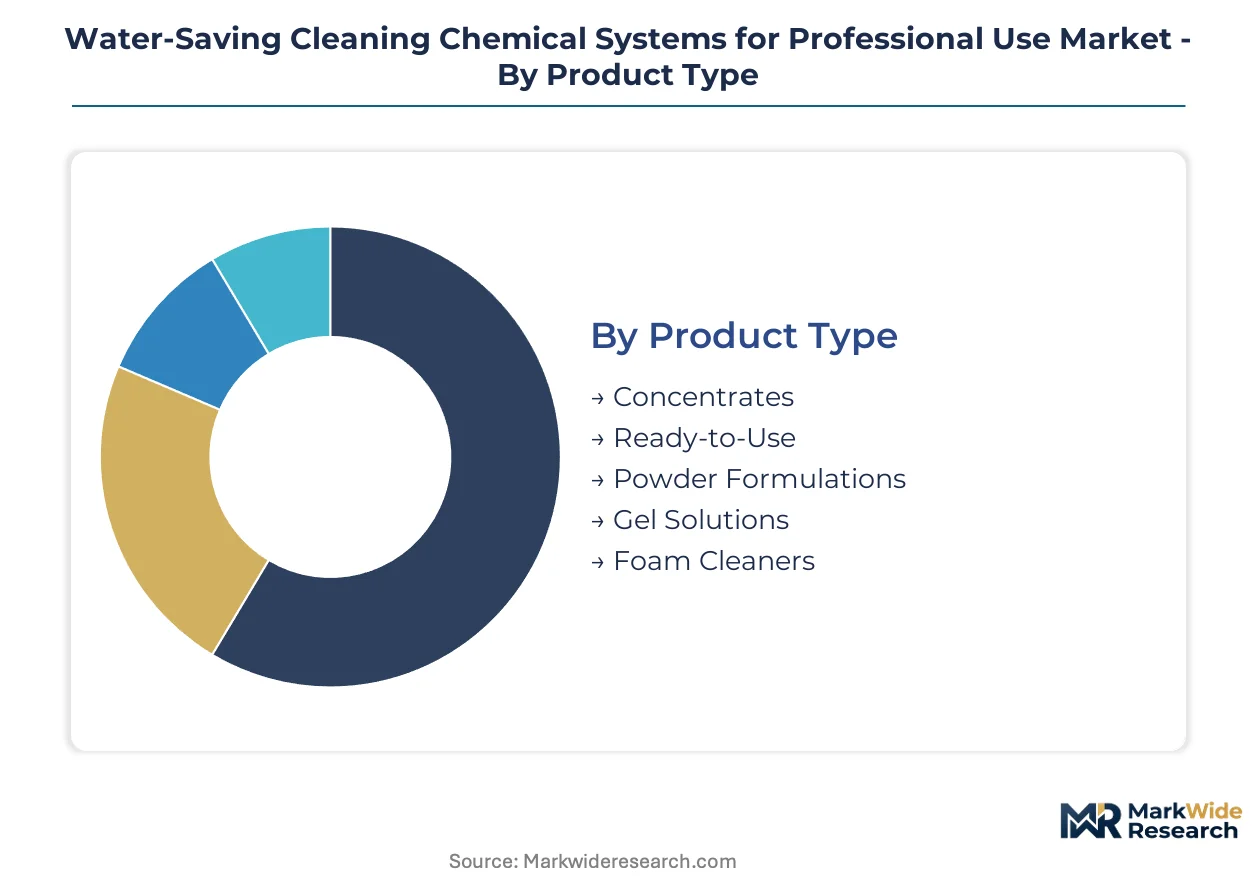
Segmentation in water-saving cleaning chemical systems reveals where capital deployment, regulatory compliance, and operational complexity intersect. Procurement officers and facility managers navigate these categories to optimize total water cost against reformulation risk and equipment compatibility constraints.
Product Type:
Capital intensity varies sharply across formulation formats, with automated dispensing infrastructure and concentrated chemistry requiring the heaviest upfront investment while manual-application formats minimize entry barriers.
- Concentrates:Surfactant packages engineered for dilution ratios of 1:128 to 1:512, reducing freight and packaging expenditures. Demand concentrates in North American facility management networks where distributors prioritize margin structures serving fragmented commercial laundries and hospitality chains.
- Ready-to-Use:Pre-diluted formulations eliminating on-site mixing errors and compliance documentation burdens. Smaller janitorial contractors and emergency response cleaning operations absorb this format where labor training constraints outweigh per-unit chemistry premiums.
- Powder Formulations:Lightweight shipping profiles suit remote mining camps and offshore platforms with irregular supply chains.
- Gel Solutions:Controlled-release chemistry adheres to vertical surfaces in food processing sanitation protocols.
- Foam Cleaners:Extended contact time chemistry for automotive undercarriage and heavy equipment degreasing.
Most installed capacity flows through Concentrates. Expansion is steepest in Automated Dispensing convergence with concentrated formats.
Application:
Water discharge tariff structures and sanitation compliance thresholds create divergent margin profiles across end-use environments, with food processing bearing the steepest regulatory burden.
- Food Processing:Thermal activation chemistry for grease-intensive sanitation combined with effluent monitoring under EPA and EU F-Gas adjacent protocols. Plants in Germany and Japan retrofitting with low-rinse formulations to cut municipal discharge costs.
- Hospitality Services:Ambient-temperature systems for linen and surface cleaning where energy costs dominate operational calculus. Australian and South Korean hotel chains absorb cold-water enzymatic detergents to eliminate boiler fuel expenditure.
- Automotive Maintenance:High-pressure water recovery systems for fleet washing and detailing operations.
- Industrial Fabric Care:Commercial laundries in France and Italy consolidating supplier relationships amid REACH reformulation timelines.
- Public Facility Sanitation:Transit systems and municipal buildings with standardized procurement specifications.
Food Processing commands the highest compliance-driven pricing. Hospitality Services is gaining share fastest as energy-sensitive facilities abandon thermal activation.
End User:
Customer scale and procurement sophistication determine whether spot chemical purchases or integrated service contracts dominate the relationship structure.
- Janitorial Services:Fragmented contractor base deferring IoT-enabled dispensing hardware during demand uncertainty.
- Commercial Laundries:Water-intensive textile operations consolidating supplier ties to secure reformulation support under tightening surfactant toxicity thresholds.
- Facility Management:Integrated dispensing platforms capturing multi-year service contracts in hospital and hotel chains where compliance documentation outweighs unit chemistry costs.
- Vehicle Fleet Operators:Mobile cleaning infrastructure with water recovery system premiums in regulated jurisdictions.
- Waste Treatment Facilities:Closed-loop filtration chemistry treating water as managed resource rather than disposable input.
Facility Management channels the most contract value. Commercial Laundries is expanding most quickly as water tariffs escalate.
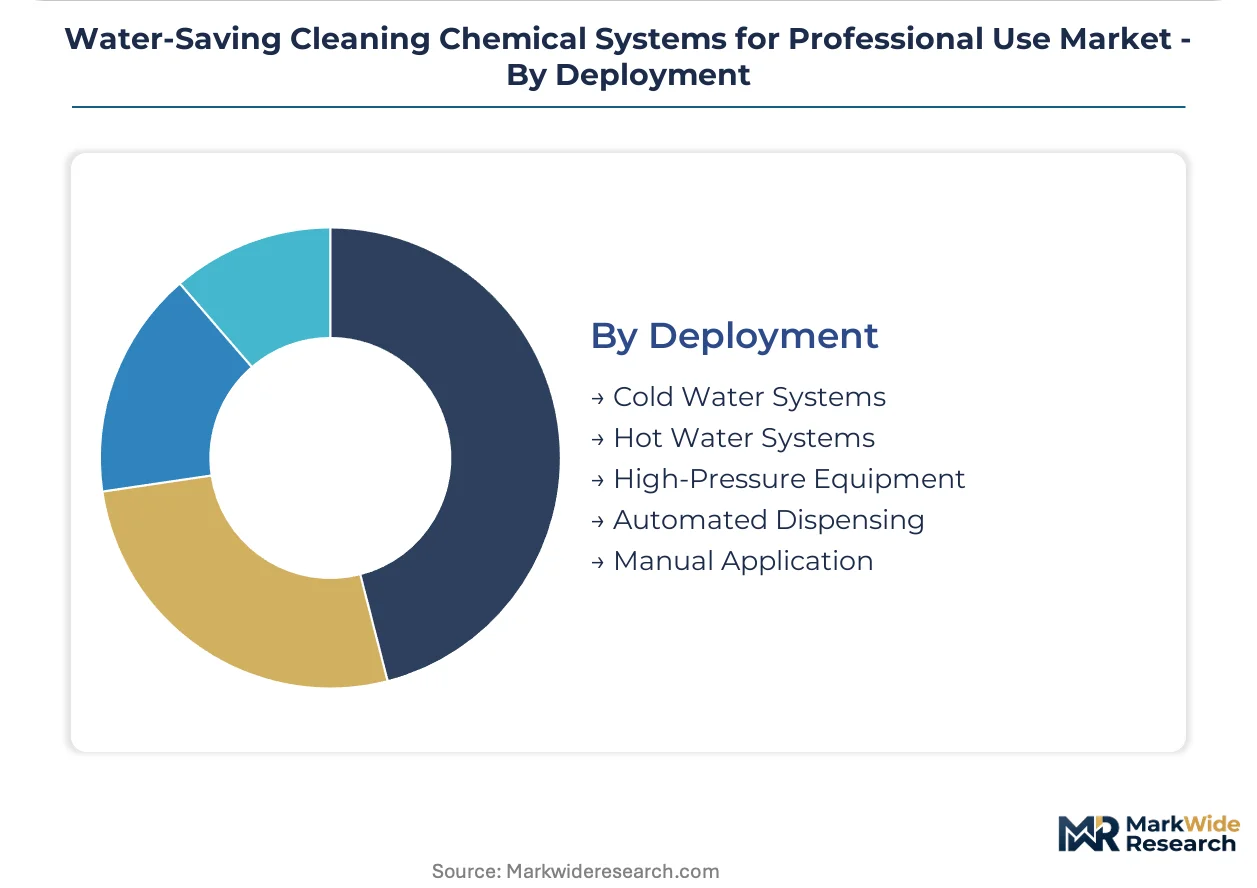
Deployment:
Equipment-software-chemistry bundling is restructuring competitive boundaries between chemical suppliers and hardware manufacturers.
- Cold Water Systems:Enzymatic detergents maintaining sanitation compliance without thermal activation. Netherlands and Belgium food plants piloting ambient-temperature protocols.
- Hot Water Systems:Retained share in grease-intensive applications where thermal acceleration remains mandatory despite boiler fuel costs.
- High-Pressure Equipment:Mobile cleaning with water recovery commanding premium positioning in automotive and industrial maintenance.
- Automated Dispensing:IoT-enabled dilution control enabling vendor-managed inventory with telemetry-based replenishment.
- Manual Application:Lowest capital threshold for small contractors with basic compliance requirements.
Hot Water Systems retains the largest installed base. Automated Dispensing is climbing the fastest as labor costs rise and dilution accuracy becomes a compliance variable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surfactant chemists and formulation specialists cluster in Germany, Japan, and the United States, anchoring the technical workforce that enables low-rinse chemistry development. These talent concentrations shape where water-saving cleaning systems achieve regulatory certification fastest.
United States
Commercial laundries in Chicago and Los Angeles absorb concentrated formulations to cut municipal discharge tariffs. The EPA's Safer Choice program tightens allowable surfactant toxicity thresholds, accelerating bio-based R&D. Facility management networks in Texas and Florida retrofit properties with automated dispensing platforms.
Germany
Food processing plants in Bavaria and North Rhine-Westphalia pilot ambient-temperature enzymatic systems. REACH restrictions on nonylphenol ethoxylates force multi-year reformulation timelines through ECHA pathways. Industrial laundries around Frankfurt consolidate supplier relationships to secure compliance support.
Japan
Textile service operations in Osaka and Tokyo retrofit facilities with low-rinse chemistry to meet corporate sustainability targets. METI guidelines on industrial water recycling add compliance layers for multinational suppliers. Hospitality chains in Fukuoka absorb cold-water detergents to eliminate boiler fuel expenditure.
China
Commercial cleaning operators in Shanghai and Beijing face GB standards for effluent discharge driving upgrade cycles. The country's national environmental regulator enforces tightening thresholds on surfactant loads in wastewater. Multinational suppliers with pre-certified formulations capture procurement contracts in Yangtze River Delta manufacturing zones.
Netherlands
Food processing plants in Rotterdam and Eindhoven pilot closed-loop filtration systems that treat water as managed resource. The EU Green Deal's water-efficiency targets pivot procurement specifications across facility networks. Enzymatic cold-water detergents absorb capital allocation away from steam infrastructure toward chemical activation technology.
Water-Saving Cleaning Chemical Systems for Professional Use Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and hardware boundaries. Integrated dispensing platforms require upfront hardware investment that chemical specialists avoid, creating tiered competitive positions. Three archetypes dominate: full-system bundlers combining chemistry with IoT-enabled equipment, concentrate specialists optimizing freight and packaging economics, and regional formulators serving fragmented janitorial contractors. M&A activity concentrates on dispensing technology acquisitions, while strategic partnerships link chemical suppliers with water recovery equipment fabricators.
Among integrated-system bundlers, Ecolab and Diversey exemplify the service-contract archetype that displaces spot chemical purchases through multi-year agreements. Alfred Kärcher SE & Co. KG anchors the mobile equipment segment where water recovery systems command premium positioning. These three occupy positions spanning hospitality, healthcare, and industrial maintenance verticals without overlapping core competencies.
| Leading Market Players |
|---|
| Ecolab |
| Diversey |
| SC Johnson Professional |
| Alfred Kärcher SE & Co. KG |
| 3M |
| Solenis |
| Zep |
| Betco |
| Spartan Chemical |
| Others |
Pricing and Supply Chain Analysis
Facility management consolidation across North American hospital and hotel chains is compressing procurement timelines and forcing chemical suppliers to absorb hardware costs into multi-year service contracts, reshaping margin structures away from transactional spot sales toward bundled recurring revenue models.
Pricing Analysis
The bundled-versus-unbundled service split separates integrated dispensing platforms from standalone chemical sales. Pricing stratifies across premium certified tiers, standard compliance-grade formulations, and economy manual-application products, with differentiation driven by EPA Safer Choice certification status and telemetry-enabled service bundling. Cost compression in economy tiers is intensifying because agricultural feedstock volatility for bio-based surfactants constrains formulator margins. Small janitorial contractors exhibit the highest price sensitivity, while facility management networks prioritize compliance documentation over unit chemistry costs.
Supply Chain Analysis
Reverse-logistics flows for IoT-enabled dispensing hardware create refurbishment and redeployment channels that extend equipment lifecycles and reduce capital barriers for mid-tier cleaning contractors. Manufacturing concentrates in Germany, Japan, and the United States where surfactant chemist talent clusters anchor formulation development. The supply chain draws from palm-derived feedstocks, petroleum-based intermediates, and chelating agent precursors with exposure to agricultural commodity volatility. Single-source vulnerability runs through concentrated surfactant packages where REACH reformulation timelines freeze product portfolios. Distribution runs through integrated service contracts displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where successive tightening of EPA Safer Choice thresholds and REACH surfactant restrictions creates recurring upgrade demand that locks in multi-year service relationships.
For Market Incumbents: Anticipate margin compression from bio-based feedstock volatility by securing long-term agricultural supply agreements and accelerating captive production of enzymatic cold-water formulations. Vertical integration into IoT dispensing hardware manufacturing defends against equipment-specialist encroachment. Prioritize certification investment ahead of EU Green Deal water-efficiency enforcement timelines.
For New Entrants and Emerging Players: Fragmented janitorial contractors in secondary US metropolitan markets represent an underserved buyer archetype deferred by incumbents focused on enterprise facility management networks. Cold water system retrofits in Australian hospitality chains offer the most penetrable application segment. A dispensing-hardware-as-a-service go-to-market angle bypasses capital barriers that stall smaller contractor adoption.
For Investors and Strategic Acquirers: Asymmetric upside sits with automated dispensing technology specialists possessing telemetry platforms that can layer chemical subscription revenue atop hardware installation bases. The five-to-ten year viability window favors suppliers with pre-certified formulations across multiple regulatory jurisdictions. Acquisition targets should demonstrate installed base scale in hospital and hotel chains. Monitor ECHA reformulation approval velocity as an inflection indicator for European market access competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Surfactant Production | Captive supply of plant-derived feedstocks insulates margin structures from agricultural commodity volatility affecting European formulators. |
| IoT Dispensing Platform Deployment | Telemetry-enabled dilution control locks in recurring revenue contracts with facility management networks in Texas and Florida. |
| REACH Pre-certification Investment | Early ECHA compliance for nonylphenol ethoxylate alternatives secures procurement relationships with German industrial laundries. |
| Cold Water Enzymatic Formulation Launch | Ambient-temperature chemistry captures energy-cost-sensitive hospitality chains in South Korea and Australia abandoning boiler infrastructure. |
| Joint Venture with Water Recovery Equipment Fabricators | Integrated closed-loop filtration systems address Netherlands food processing pilots treating water as managed resource. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facility management procurement officers, chemical formulator R&D directors, commercial laundry operations managers, and IoT dispensing hardware engineers with secondary validation against EPA Safer Choice certification databases, ECHA REACH registration filings, customs trade data for surfactant imports, and ACC industry reports. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Segment-weighting approaches modeled deployment mode, formulation concentration tier, end-use application intensity, and regional regulatory cluster across the projection horizon. CAGRs derived from installed base expansion rates, replacement cycle acceleration, and pricing trajectory assumptions for bundled service contracts. Forecast inputs incorporated municipal water tariff escalation schedules and bio-based surfactant cost curves.
Underlying measurement precision varies by segment; automated dispensing and food processing applications carry tighter precision than fragmented janitorial services where contractor survey response is sparse. Forecasts reflect documented assumptions on regulatory enforcement timing and feedstock cost normalization. Practitioners should monitor ECHA reformulation approval queues and METI water recycling guideline updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market