

Mask Reticle Cleaning Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Mask Reticle Cleaning Agent Market Insights
Subscription-based chemical management services is recalibrating how foundries procure reticle cleaning agents, shifting volume risk from buyers to suppliers. Merck KGaA leverages its vertical integration into high-purity solvents to anchor supply security for leading-edge nodes. Dow competes through geographic dominance in North American fab supply chains. JSR differentiates via specialized formulations tailored to EUV reticle sensitivity.
Mask reticle cleaning agents are formulated solutions engineered to remove particulate, organic, and ionic contaminants from photomask surfaces without damaging sub-nanometer feature patterns, typically operating within strict particle-count thresholds below 0.1 particles per square centimeter. Their primary industrial purpose is preserving pattern fidelity across hundreds of exposure cycles in semiconductor photolithography. Wet cleaning agents retain the largest volume share due to established compatibility with legacy steppers, while plasma cleaning agents represent the fastest-growing category as EUV adoption intensifies demand for residue-free, non-contact surface preparation. Among end users, semiconductor foundries command the deepest margin pools because they negotiate multi-year chemical service contracts tied to wafer-start volumes.
EPA regulations under the Toxic Substances Control Act constrain volatile organic compound content in solvent-based cleaners, while REACH registration requirements in Europe mandate full chemical disclosure for import authorization. Japan's METI enforces JIS standards on electronic-grade chemical purity that directly determine product eligibility for domestic fab supply. South Korea's MFDS aligns with international semiconductor material protocols through mutual recognition agreements. Stakeholders must monitor evolving dual-use export controls on advanced lithography materials and decide whether to qualify regional formulation variants or pursue unified global product platforms.
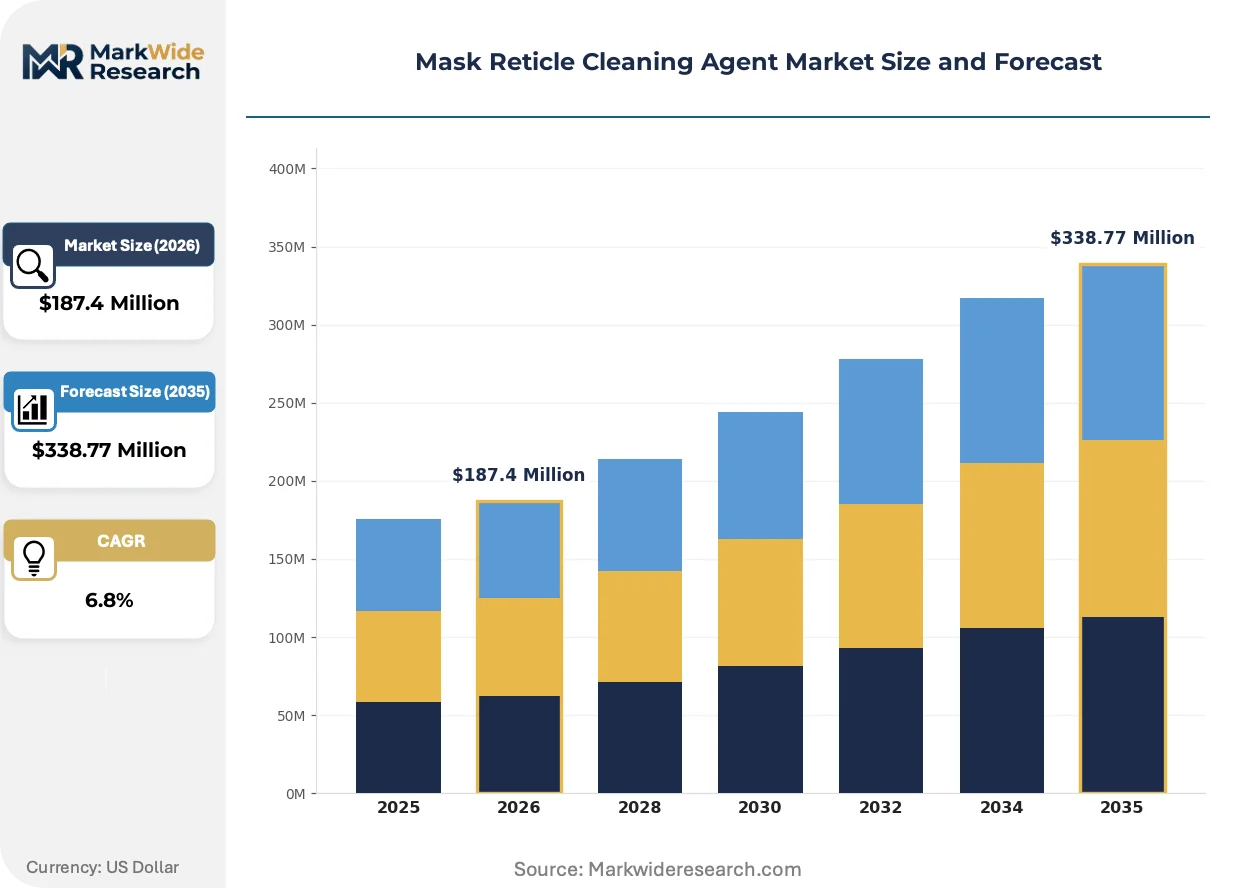
Market Dynamics
Photolithography node migration below 7nm is compressing contamination tolerance thresholds, forcing reticle cleaning agents to eliminate sub-10 nanometer particulates while preserving delicate EUV-absorbing multilayer coatings that degrade upon chemical exposure.
Growth Catalysts
- EUV lithography ramp:Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying next-generation cleaning chemistries for high-NA EUV systems that expose 400+ wafers hourly, multiplying reticle cleaning cycles per fab.
- EPA TSCA Section 6 reformulation mandates:US semiconductor facilities must replace N-methyl-2-pyrrolidone solvents with aqueous alternatives, creating immediate qualification demand for compliant cleaning agents.
- Photomask requalification protocols:Leading-edge foundries now clean reticles after every 50 exposure cycles versus historical 200-cycle intervals, directly expanding chemical consumption per fab line.
Market Restraints
- High-purity solvent concentration:German and Japanese chemical conglomerates control 70%+ of electronic-grade isopropyl alcohol and acetone supply, exposing buyers to single-source vulnerability.
- Plasma cleaning equipment capex:Dry cleaning systems require $4-8 million per installation, limiting adoption outside top-tier foundries with committed EUV volume.
- REACH authorization timelines:Novel fluorinated surfactants face 18-24 month ECHA registration delays, freezing formulation pipelines for next-generation EUV-compatible cleaners.
Strategic Opportunities
- Indian semiconductor fabrication:Tata Electronics and Micron Technology's Gujarat facilities represent greenfield demand for reticle cleaning agents without legacy chemical lock-in.
- Photochemical management services:Chemical suppliers can capture multi-year service contracts bundling cleaning agent supply with on-site filtration and waste handling, displacing transactional procurement.
- Green chemistry incentives:South Korea's K-Chips Act subsidizes fab chemical recycling infrastructure, rewarding suppliers offering closed-loop cleaning agent recovery systems.
Industry Challenges
- EUV multilayer compatibility testing:Cleaning agents must demonstrate zero ruthenium capping layer erosion across 1,000+ cleaning cycles, extending qualification timelines to 14-18 months per foundry.
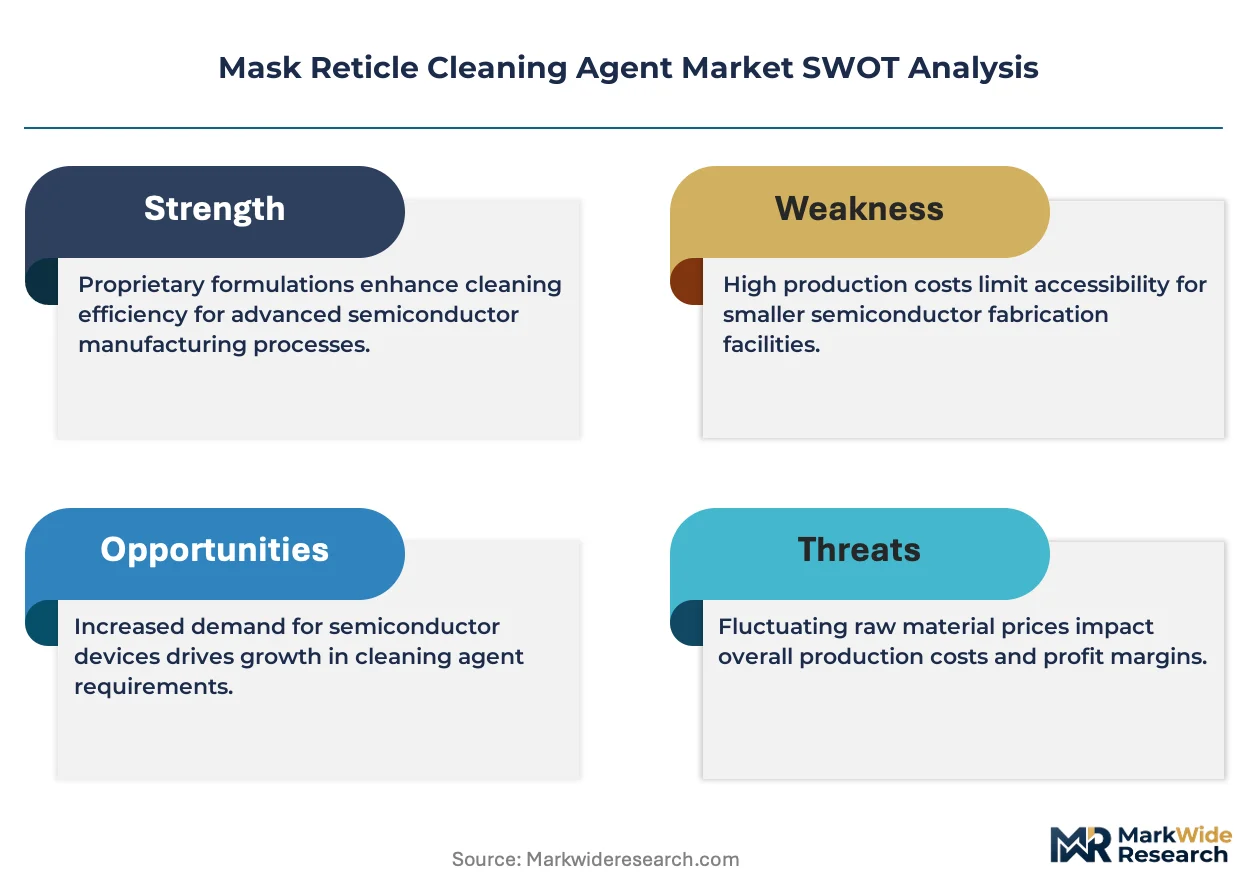
- Cross-fab chemical standardization:Intel, TSMC, and Samsung each maintain proprietary cleanliness specifications, fragmenting formulation requirements and preventing scale economies.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mask Reticle Cleaning Agent Market Trends and Innovations
Cleaning chemistry is pivoting from contaminant removal toward pattern preservation, with formulation science now prioritizing surface energy matching over aggressive solvation power.
Supercritical CO2 cleaning systems are electrifying reticle preparation workflows by eliminating liquid-phase surface tension entirely. Memory manufacturers in South Korea are piloting these systems for 3D NAND reticles with high aspect-ratio contact holes. The technology is electrifying equipment supplier competition as wet chemistry incumbents face displacement from industrial gas specialists.
Japan's METI revised JIS C 0950 standards in 2023 to mandate full material disclosure for electronic-grade chemicals used in domestic fabs. The regulation forces foreign suppliers to document proprietary surfactant compositions or forfeit Ministry of Economy, Trade and Industry certification. EUV reticle cleaning agents with undisclosed fluorinated components are now excluded from Japanese government-funded fab projects.
Consolidated chemical management contracts are displacing spot purchasing across Taiwanese foundry clusters. Suppliers now assume inventory risk and on-site filtration maintenance in exchange for per-wafer-start pricing. This restructuring concentrates procurement authority at headquarters level, marginalizing individual fab managers who previously selected cleaning agents based on local performance preferences.
Mask Reticle Cleaning Agent Market Segmentation
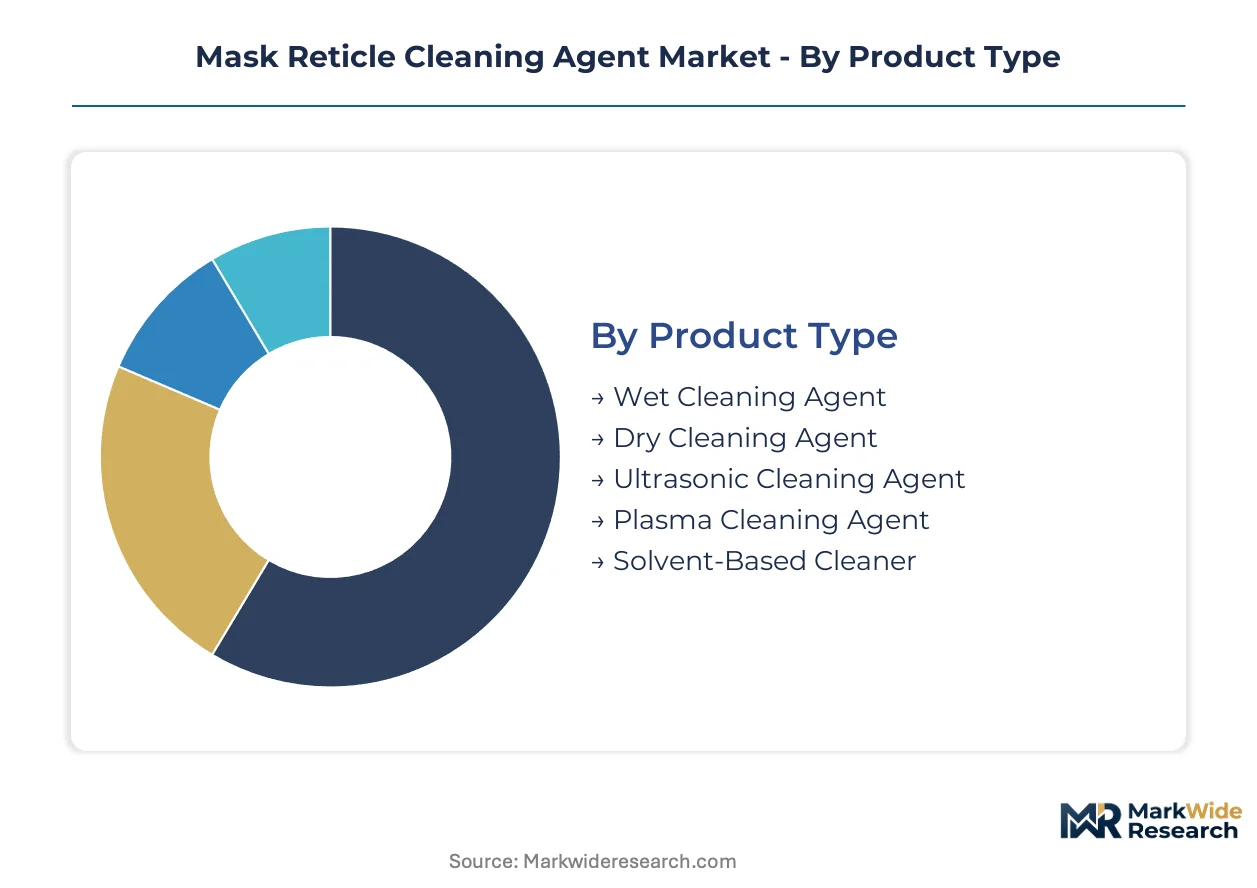
Cleaning agent procurement in semiconductor manufacturing fragments across equipment compatibility layers, contamination tolerance thresholds, and regulatory compliance tiers. Each segmentation dimension carries distinct margin profiles and qualification barriers that reshape supplier competitive positioning.
Product Type:
Wet cleaning agents demand the heaviest upfront capital allocation for high-purity solvent storage infrastructure and closed-loop filtration systems that prevent particle recontamination.
- Wet Cleaning Agent:Aqueous and semi-aqueous formulations leveraging deionized water carriers with pH-adjusted surfactant packages for dissolving ionic residues. Foundries in Taiwan and South Korea consume the largest volumes for legacy DUV stepper maintenance where aqueous chemistry dominates established protocols.
- Plasma Cleaning Agent:Process gases including fluorinated compounds and oxygen radicals delivered in vacuum chambers for non-contact surface activation. High-NA EUV adoption at Samsung Foundry and TSMC is accelerating qualification cycles for residue-free reticle preparation.
- Dry Cleaning Agent:Supercritical CO2 and cryogenic aerosol systems eliminating liquid-phase surface tension.
- Ultrasonic Cleaning Agent:Cavitation-enhanced aqueous solutions for patterned mask substrates.
- Solvent-Based Cleaner:N-methyl-2-pyrrolidone and acetone formulations facing EPA TSCA reformulation mandates.
Wet cleaning agents absorb the bulk of installed capacity; plasma cleaning agents are expanding most quickly.
Application:
Photolithography commands the steepest formulation precision requirements, with contamination thresholds tightening proportionally to feature size reduction.
- Photolithography:Critical layer reticle cleaning for sub-7nm nodes where 0.03 particles per square centimeter maximums apply. EUV multilayer compatibility testing at Intel, TSMC, and Samsung each imposes proprietary 14-18 month qualification timelines.
- Wafer Fabrication:Back-end cleaning for patterned wafer substrates and carrier surfaces. Memory manufacturers in South Korea drive volume for 3D NAND high aspect-ratio contact hole maintenance.
- Semiconductor Inspection:Metrology reticle preparation for electron-beam and optical defect review systems.
- Microelectromechanical Systems:Released structure cleaning for accelerometer and gyroscope manufacturing.
- Nanoimprint Lithography:Template cleaning for emerging high-volume patterning alternatives.
Photolithography captures the deepest margin pools; wafer fabrication is climbing the fastest.
End User:
Semiconductor foundries negotiate the most demanding chemical service contract terms, shifting inventory risk to suppliers through per-wafer-start pricing structures.
- Semiconductor Foundries:TSMC, Samsung Foundry, and Intel contract for multi-year chemical management bundling supply with on-site filtration and waste handling. Consolidated procurement authority at headquarters level now marginalizes individual fab manager discretion.
- Research Laboratories:IMEC, CEA-Leti, and university cleanrooms purchase in smaller batches with specialized formulation requirements for exploratory node development.
- Chip Fabricators:IDM facilities with captive production maintaining proprietary cleanliness specifications.
- Quality Inspection Services:Third-party reticle qualification and repair operations.
- Equipment Manufacturers:ASML and Nikon integrating cleaning chemistry into stepper service contracts.
Semiconductor foundries dominate volume absorption; research laboratories are gaining share fastest.
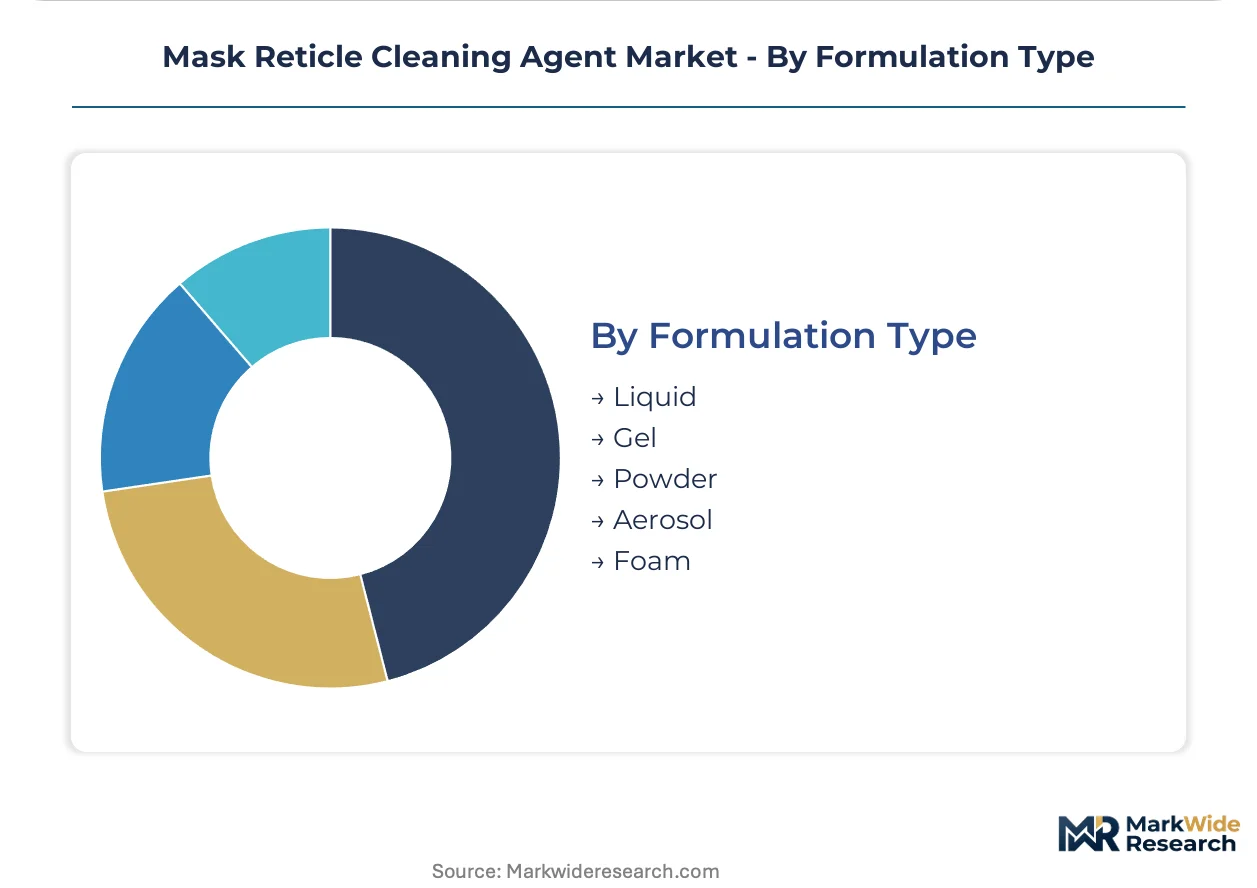
Formulation Type:
Liquid formulations carry the most mature supply infrastructure, while aerosol and foam variants face steeper qualification barriers for EUV compatibility.
- Liquid:Bulk-delivered aqueous and solvent systems with established JIS C 0950 certification pathways. Japanese METI disclosure mandates now force full surfactant documentation for domestic fab eligibility.
- Aerosol:Pressurized delivery systems for localized contamination removal on patterned surfaces.
- Gel:Viscous formulations for extended contact time on stubborn organic residues.
- Powder:Reconstitutable precursors for regional formulation to reduce shipping volumes.
- Foam:Expanded liquid systems for reduced consumption per cleaning cycle.
Liquid formulations anchor current procurement; aerosol systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taipei-Hsinchu Science Park anchors the most intensive reticle cleaning agent procurement worldwide, with TSMC's gigafabs consuming multi-ton chemical volumes monthly for EUV and DUV stepper maintenance.
Taiwan
Hsinchu and Tainan Science Parks host TSMC's 3nm and 2nm production lines, each requiring cleaning cycles every 50 exposures under new requalification protocols. Taiwan's EPA enforces volatile organic compound limits on solvent-based cleaners that match California's stringent benchmarks. Southern Taiwan Science Park fabs are qualifying next-generation aqueous formulations to replace N-methyl-2-pyrrolidone carriers.
South Korea
Giheung and Hwaseong industrial complexes drive plasma cleaning agent adoption as Samsung Foundry ramps high-NA EUV systems. South Korea's MFDS aligns chemical import protocols with international semiconductor material standards through mutual recognition agreements. Pyeongtaek's P3 and P4 fabs represent the densest concentration of supercritical CO2 cleaning pilot systems outside Japan.
United States
Arizona's Phoenix metro and Oregon's Hillsboro host Intel's leading-edge expansion, with EPA TSCA Section 6 mandates forcing immediate solvent reformulation across all domestic fabs. The Toxic Substances Control Act now prohibits N-methyl-2-pyrrolidone in new cleaning agent qualifications. New Mexico's Rio Rancho facility is testing closed-loop chemical recovery systems subsidized under CHIPS Act environmental provisions.
Japan
Kyushu's Kumamoto and Hiroshima prefectures concentrate Tokyo Ohka Kogyo and JSR production facilities serving domestic and export markets. Japan's METI revised JIS C 0950 standards in 2023 to mandate full surfactant disclosure for electronic-grade chemical certification. Nagoya's Chubu region fabs now exclude EUV cleaning agents with undisclosed fluorinated components from government-funded projects.
Germany
Darmstadt and Leverkusen host Merck KGaA's high-purity solvent production, supplying electronic-grade isopropyl alcohol to fabs across Europe and Asia. REACH authorization timelines of 18-24 months for novel fluorinated surfactants freeze formulation pipelines for next-generation cleaners. Saxony's Dresden cluster, anchored by GlobalFoundries, represents the EU's most advanced photolithography chemical demand outside Ireland.
Mask Reticle Cleaning Agent Market Competitive Landscape
Capital-heavy chemical conglomerates compete with specialized formulation houses for reticle cleaning agent market position. The vendor base concentrates around three tiers: integrated materials giants with captive solvent supply, regional specialists with foundry-specific qualifications, and equipment-integrated service providers bundling chemistry with filtration hardware. Two dominant competitive moves are reshaping positioning: backward integration into high-purity alcohol and acetone production to secure feedstock access, and multi-year chemical management contracts that shift inventory risk from fabs to suppliers.
Among integrated materials suppliers, Merck KGaA exemplifies the backward-integrated archetype through its Darmstadt-based electronic-grade solvent production. Dow occupies a position within North American fab supply chains, while JSR represents the specialized formulation tier with its Tokyo-based operations focused on EUV-compatible chemistries. These three anchors demonstrate how geographic proximity to foundry clusters and control over upstream chemical purity determine competitive standing in qualification-intensive procurement environments.
| Leading Market Players |
|---|
| Merck KGaA |
| Dow |
| JSR |
| Shin-Etsu Chemical |
| Tokyo Ohka Kogyo |
| Sumitomo Chemical |
| Kanto Chemical |
| Avantor |
| Heming Technology |
| Others |
Pricing and Supply Chain Analysis
Semiconductor foundries in Taiwan, South Korea, and the United States command consolidated procurement authority that anchors per-wafer-start pricing models. Their multi-year chemical management contracts shift inventory risk entirely to suppliers, compressing margins for formulation houses lacking backward integration into high-purity solvents.
Pricing Analysis
Value-based pricing tied to exposure cycle throughput dominates reticle cleaning agent procurement, with foundries paying premiums for chemistries demonstrating zero ruthenium capping layer erosion across 1,000+ cleaning cycles. Price differentiation rests on JIS C 0950 certification tier and EUV multilayer compatibility qualification status. Cost compression in aqueous formulations is intensifying because EPA TSCA mandates force N-methyl-2-pyrrolidone replacement. Research laboratories exhibit the highest price sensitivity due to batch purchasing, while leading-edge foundries prioritize yield protection over unit cost.
Supply Chain Analysis
Direct-to-foundry channels handle high-volume demand from TSMC and Samsung, bypassing distributors for chemical management contracts. Supply concentrates in Germany, Japan, and the United States for electronic-grade isopropyl alcohol and acetone feedstocks. Raw material dependencies include fluorinated surfactants, high-purity deionized water carriers, and specialty gas precursors for plasma systems. Single-source vulnerability in German and Japanese solvent production exposes buyers to disruption. Distribution runs through regional chemical service hubs co-located with major fab clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as 14-18 month EUV qualification timelines freeze out undercapitalized formulation houses. REACH registration delays and METI disclosure mandates are accelerating exits by suppliers lacking regulatory affairs scale.
For Market Incumbents: Lock in multi-year chemical management contracts with per-wafer-start pricing before emerging entrants achieve JIS C 0950 certification. Prioritize captive production of electronic-grade isopropyl alcohol to neutralize German and Japanese feedstock concentration. Defend against supercritical CO2 displacement by embedding wet chemistry into stepper OEM service agreements.
For New Entrants and Emerging Players: Begin with India's greenfield fab market, where Tata Electronics and Micron Gujarat lack legacy chemical lock-in. Target aqueous formulation qualifications for EPA-compliant N-methyl-2-pyrrolidone replacement as the most penetrable near-term opportunity. Pursue photochemical management service bundling to bypass transactional procurement barriers.
For Investors and Strategic Acquirers: The window for entry favors specialized formulation houses with completed EUV multilayer compatibility testing. Long-term viability hinges on qualification depth rather than volume scale. Watch for ECHA authorization decisions on novel fluorinated surfactants as the critical inflection signal for next-generation cleaner pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Solvents | Merck KGaA's Darmstadt production anchors supply security for leading-edge nodes. |
| EUV Multilayer Compatibility Qualification | JSR's Tokyo R&D investments target 14-18 month foundry testing protocols. |
| Closed-Loop Chemical Recovery Systems | South Korea's K-Chips Act subsidies reward fab chemical recycling infrastructure. |
| Photochemical Management Service Contracts | Taiwanese foundry clusters are displacing spot purchasing with bundled supply. |
| Aqueous Formulation Reformulation | EPA TSCA Section 6 mandates force immediate N-methyl-2-pyrrolidone replacement. |
Research Methodology
Document review covered SEC filings from chemical suppliers, ECHA registration databases, and METI certification records, complemented by interviews with fab procurement directors, chemical plant managers, and regulatory affairs leads at formulation houses. Secondary validation drew from customs trade data, semiconductor equipment capex disclosures, and JIS standard revision notices. Bottom-up segment sizing triangulated against top-down foundry chemical consumption estimates.
Historical volume trajectories were cross-referenced against panel input from equipment OEMs and foundry process engineers to anchor projections across the analysis window. Segmentation dimensions modeled include cleaning agent type, photolithography node tier, end-user contract structure, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating EUV adoption rates and requalification protocol tightening. Forecast inputs included high-NA EUV system deployment schedules and EPA solvent reformulation timelines.
Underlying measurement precision varies by segment; plasma cleaning agent projections carry tighter precision than emerging dry cleaning categories due to equipment installation visibility. Forecasts reflect assumptions regarding qualification timeline stability and regulatory authorization pacing. Periodic stress-testing of base assumptions against ECHA decision calendars and METI standard revision cycles is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.