
 Low-Foaming Detergent Market | 2026-2036
Low-Foaming Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Foaming Detergent Market Foresight
Buyer concentration among industrial laundries and food-processing facilities is hardening as large contract cleaners consolidate purchasing volumes. BASF SE leverages its integrated surfactant chemistry portfolio to supply multinational detergent brands with tailored low-foam alkoxylates. Stepan Company anchors North American manufacturing through backward integration into fatty alcohol feedstocks. Clariant AG differentiates via specialty additives that suppress foam in high-temperature wash cycles.
Low-foaming detergent refers to surfactant formulations engineered with cloud-point-controlled nonionic ethoxylates or silicone defoamers to maintain cleaning efficacy while generating minimal stable foam, typically achieving foam heights below 50 mm in standard Ross-Miles tests. These formulations serve automated industrial cleaning systems where excessive foam triggers pump cavitation, sensor errors, and rinse-cycle inefficiencies. Liquid concentrates lead among product types due to their compatibility with precision dosing equipment in commercial dishwashers and tunnel washers. Industrial cleaning applications command the deepest margin pools as facility managers prioritize throughput reliability over per-unit chemistry cost. Pods and tablets remain niche but occupy growing shelf space in premium household segments where consumers associate unit-dose convenience with controlled dissolution profiles.
EPA Safer Choice certification and REACH Annex XVII restrictions on alkylphenol ethoxylates shape surfactant selection across the United States and European Union, compelling suppliers to validate biodegradability and aquatic toxicity profiles. FDA food-contact notifications govern detergent residues on processing equipment in U.S. dairy and beverage plants, adding compliance layers beyond general cleaning chemistry. ISO 14001 environmental management systems increasingly serve as procurement filters for multinational hospitality chains auditing supplier sustainability credentials. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulators in Germany and the United States scrutinize fluorosurfactant alternatives that historically delivered premium foam control.
Market Dynamics
REACH Annex XVII restrictions on alkylphenol ethoxylates and EPA Safer Choice certification requirements are forcing simultaneous surfactant reformulation across European and North American supply chains, compressing formulation windows while elevating R&D spend for compliant low-foam alkoxylates.
Growth Catalysts
- High-efficiency machine penetration:Industrial laundries in Germany and the United States are retrofitting tunnel washers and continuous batch washers that demand precisely controlled foam profiles to prevent pump cavitation and sensor malfunction.
- REACH compliance deadlines:ECHA's phased restrictions on nonylphenol ethoxylates are accelerating supplier migration toward fatty alcohol ethoxylates with superior biodegradability credentials.
- Food processing automation:Dairy and beverage plants in Wisconsin and Bavaria are installing clean-in-place systems that specify low-foaming chemistries to maintain throughput reliability.
Market Restraints
- Palm kernel oil price volatility:Fatty alcohol feedstock costs fluctuate with Malaysian and Indonesian palm oil harvest cycles, squeezing margin stability for ethoxylate producers.
- Specialty surfactant supply concentration:Cloud-point-controlled nonionic production clusters in Germany and the Netherlands create geographic vulnerability for North American formulators.
- Fluorosurfactant regulatory scrutiny:German and U.S. regulators are examining per- and polyfluoroalkyl substance alternatives that historically delivered premium foam suppression, chilling adoption of next-generation defoamers.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO-regulated sterile processing facilities in Hyderabad and Bangalore are adopting automated parts washers that specify low-foam chemistries for validated cleaning protocols.
- EU Green Deal procurement incentives:Public hospital systems in France and Italy are embedding ISO 14001 environmental credentials into detergent tender requirements, favoring biodegradable formulations.
- Silicone-polyether hybrid defoamers:Convergence of organosilicon chemistry with precision alkoxylation is enabling temperature-stable foam control across wider pH ranges.
Industry Challenges
- Surfactant toxicology expertise scarcity:Formulators struggle to recruit chemists proficient in aquatic toxicity modeling and biodegradability validation required for EPA Safer Choice dossiers.
- Legacy dosing equipment incompatibility:Older commercial dishwashers in U.S. hospitality chains require mechanical retrofits to handle viscous liquid concentrates without dilution system recalibration.
- Multi-jurisdiction notification timelines:FDA food-contact notifications for processing equipment residues run parallel to EPA registrations, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Foaming Detergent Market |
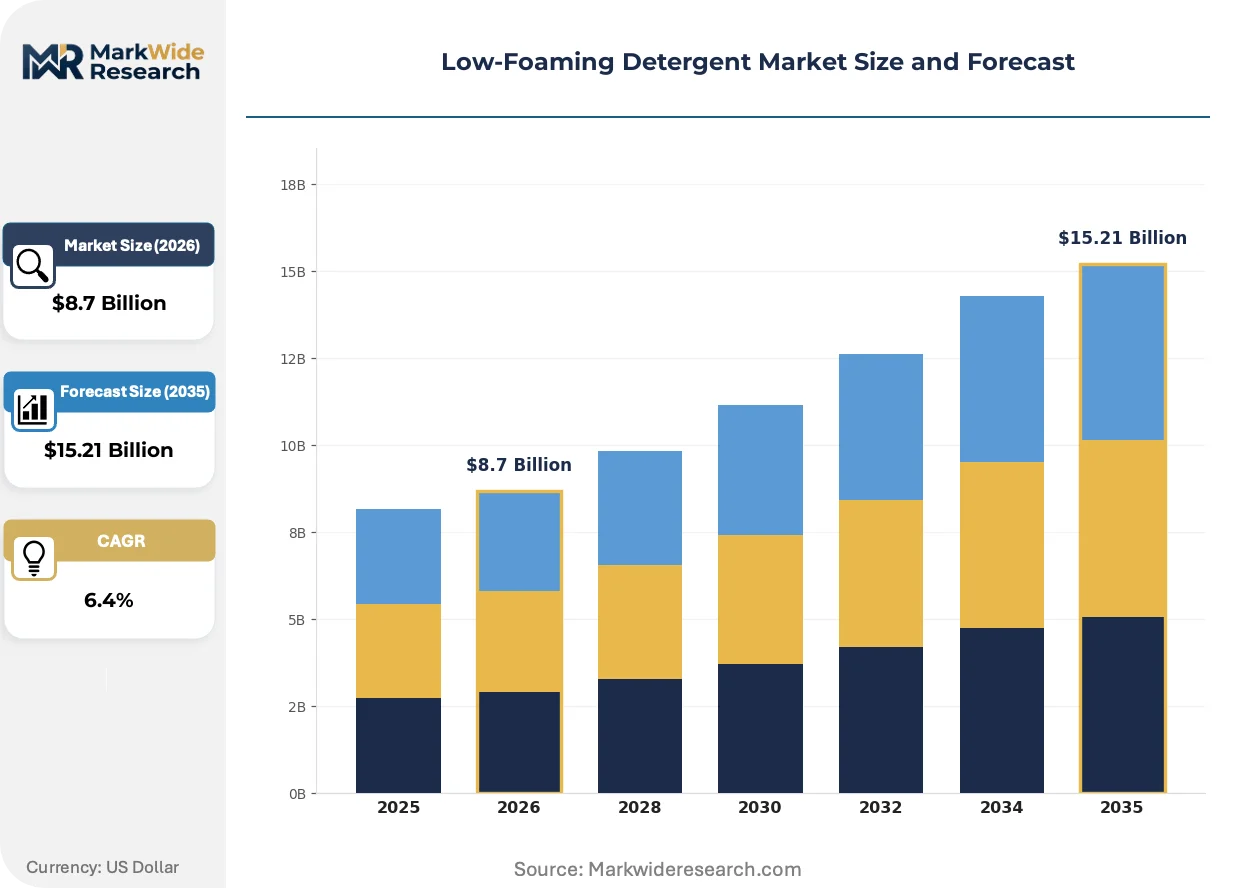
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Pods, Tablets Application: Industrial Cleaning, Household Use, Auto Detailing, Hospitality End User: Manufacturers, Consumers, Retailers, Service Providers Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Croda International Plc, Clariant AG, BASF SE, Akzo Nobel N.V., Galaxy Surfactants, Stepan Company, Solvay S.A., Kao Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Foaming Detergent Market Shifts & Advancements
Precision dosing infrastructure and cloud-point engineering are converging to reshape how low-foaming chemistries are specified, procured, and validated across industrial cleaning workflows.
Cloud-point-controlled ethoxylates derived from narrow-cut fatty alcohols are automating foam suppression in high-temperature wash cycles. Food processing facilities in the Netherlands and Denmark are specifying these materials for clean-in-place systems operating above 60°C. The technology is automating specification processes previously managed through trial-and-error defoamer addition.
EPA Safer Choice certification and ECHA REACH restrictions are jointly elevating biodegradability thresholds for surfactant chemistries. Formulators must now validate ready biodegradability and aquatic toxicity profiles before commercial launch. Industrial laundries in the United States are prioritizing certified products to meet corporate sustainability mandates.
Unit-dose packaging formats are capturing premium household segments as consumers associate pod and tablet convenience with controlled dissolution profiles. Retailers in Germany and the United Kingdom are expanding shelf space for these formats. The shift is most visible in urban markets where storage constraints and precision dosing preferences align.
Low-Foaming Detergent Market Segmentation
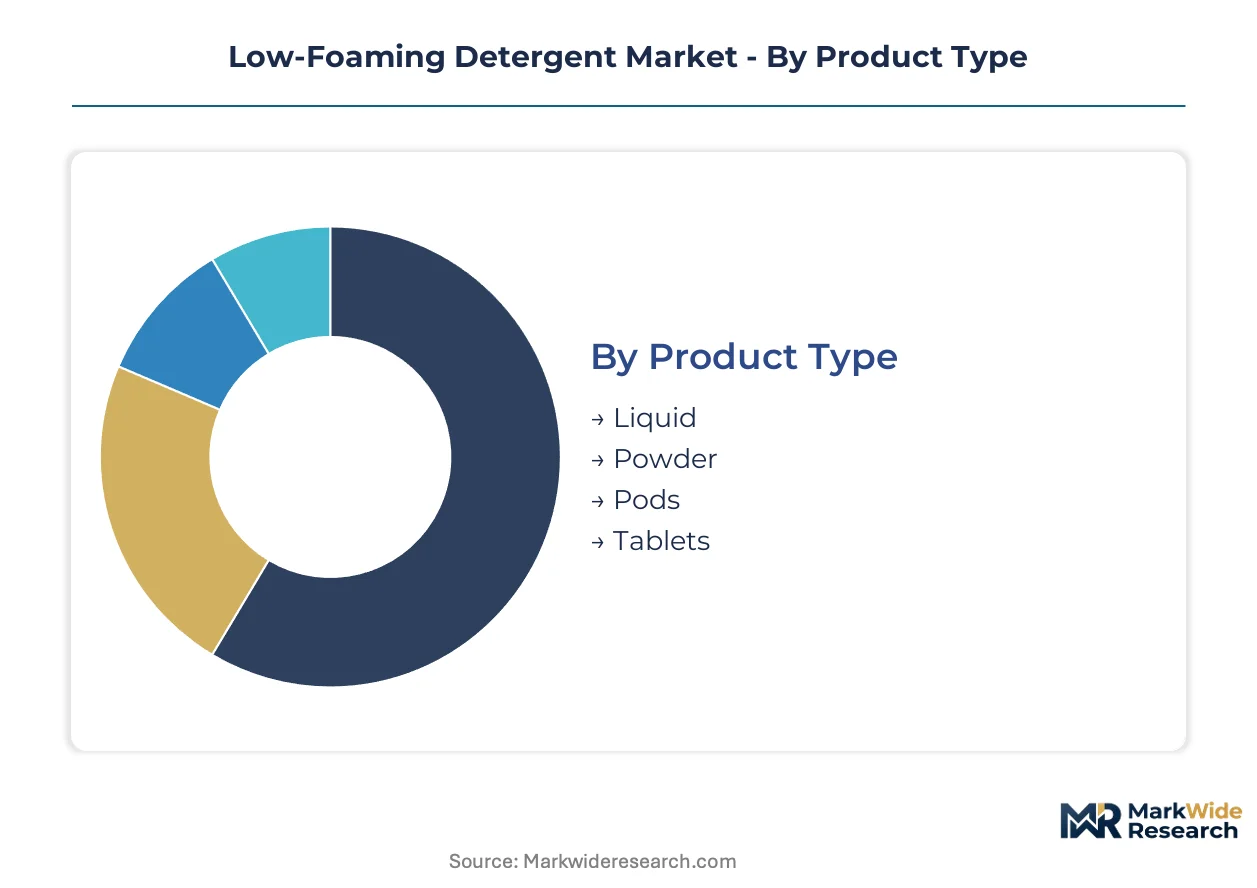
Segmentation in low-foaming detergents reflects divergent compliance burdens and performance specifications across industrial and consumer channels. Formulators must navigate distinct certification pathways for food-contact applications versus household retail, with each segment imposing unique surfactant selection constraints.
Product Type:
EPA Safer Choice certification applies universally across all formats, yet liquid concentrates face additional FDA food-contact notification requirements when destined for dairy and beverage processing equipment. Powder formulations trigger REACH Annex XVII scrutiny on dust exposure and biodegradability validation.
- Liquid:Viscous concentrates engineered with cloud-point-controlled ethoxylates for precision dosing in tunnel washers and clean-in-place systems. Industrial laundries in Germany specify these for automated dispensing equipment, though older U.S. hospitality dishwashers require mechanical retrofits to handle higher viscosities without dilution recalibration.
- Powder:Spray-dried granules incorporating silicone defoamers and builders for high-temperature wash cycles. Powder sits at the top of the volume ranking, with pods climbing the fastest.
- Pods:Water-soluble film encapsulating unit-dose surfactant blends, capturing premium household segments in German and British urban markets where storage constraints align with convenience preferences.
- Tablets:Compressed solid blocks with controlled dissolution profiles for commercial dishwashers, requiring validated disintegration rates to prevent residue on food-contact surfaces.
Pods are expanding most quickly in premium retail channels, while liquid retains dominance in industrial procurement.
Application:
Cost tier stratification separates industrial specifications—where throughput reliability commands premium chemistry spend—from household segments where per-unit price sensitivity dominates.
- Industrial Cleaning:Clean-in-place systems in Wisconsin dairy plants and Bavarian beverage facilities specify low-foam alkoxylates with validated residue limits under FDA and EFSA frameworks. This segment captures the deepest margin pools as facility managers prioritize uptime over per-kilogram surfactant cost.
- Household Use:Standard formulations for domestic laundry and surface cleaning, distributed primarily through supermarket and online channels in the United States and Germany.
- Auto Detailing:pH-neutral formulations with controlled foam for automated car wash tunnels, requiring compatibility with water reclamation systems under EPA effluent guidelines.
- Hospitality:Commercial dishwashing chemistries for hotel and restaurant chains, with multinational operators auditing ISO 14001 credentials through procurement filters.
Industrial cleaning commands the steepest pricing premium, while hospitality shows the fastest volume gain as contract cleaners consolidate purchasing.
End User:
Customer type determines whether procurement flows through centralized tender processes or fragmented retail selection, shaping formulation complexity and margin structure.
- Manufacturers:Food processing and pharmaceutical facilities in Hyderabad and Bangalore specifying validated cleaning protocols under CDSCO regulations for sterile equipment.
- Consumers:Individual purchasers selecting unit-dose convenience formats through online and supermarket channels, with minimal technical specification involvement.
- Retailers:Supermarket and hospitality procurement managers embedding sustainability credentials into supplier scorecards, particularly in French and Italian public hospital systems.
- Service Providers:Contract cleaners consolidating volumes across industrial laundry and facility maintenance accounts, driving backward integration demands on surfactant suppliers.
Service providers are consolidating share fastest, while manufacturers retain the most stringent technical requirements.
Distribution Channel:
Supply concentration in cloud-point ethoxylate production—clustering in Germany and the Netherlands—creates geographic vulnerability for North American formulators dependent on imported specialty surfactants.
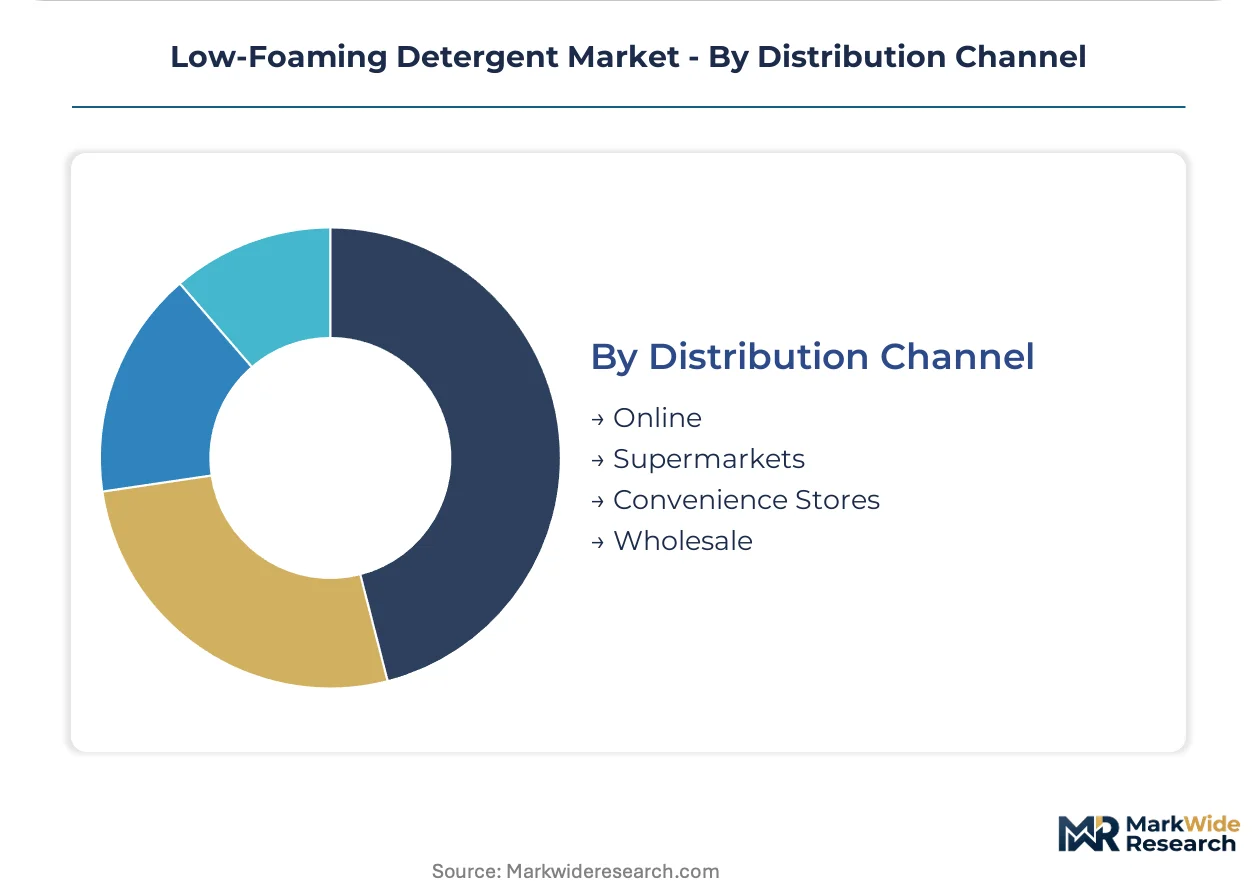
- Online:Direct-to-consumer and B2B platforms capturing urban household segments and small industrial accounts, with subscription models for liquid concentrate replenishment.
- Supermarkets:Mass retail placement for powder and pod formats, with shelf space expansion for unit-dose products in German and British markets.
- Convenience Stores:Emergency and travel-size liquid sachets, limited to standard formulations without specialized low-foam engineering.
- Wholesale:Bulk liquid and powder supply to industrial laundries, food processors, and contract cleaners, with tanker delivery and dosing equipment leasing bundles.
Wholesale channels move the largest absolute volumes, with online posting the sharpest trajectory upward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized surfactant chemists cluster in Germany's industrial Rhine corridor and the Netherlands' Rotterdam-Antwerp chemical belt, anchoring European formulation expertise. North American technical talent concentrates in New Jersey's specialty chemicals corridor and Illinois' cleaning products hub.
Germany
Industrial laundries in North Rhine-Westphalia and Bavaria drive demand for cloud-point-controlled ethoxylates compatible with tunnel washer automation. ECHA REACH Annex XVII restrictions on alkylphenol ethoxylates compel formulators to validate fatty alcohol alternatives. BASF SE's Ludwigshafen complex supplies multinational detergent brands with tailored low-foam alkoxylates for food processing and healthcare applications.
United States
Dairy processors in Wisconsin and beverage facilities in California specify low-foaming chemistries for clean-in-place systems under FDA food-contact notification requirements. EPA Safer Choice certification tightens surfactant selection criteria, elevating R&D spend for biodegradable formulations. Stepan Company anchors North American manufacturing through backward integration into fatty alcohol feedstocks from Illinois operations.
India
Pharmaceutical manufacturers in Hyderabad and Bangalore adopt automated parts washers requiring validated low-foam protocols under CDSCO sterile processing regulations. Contract cleaners in Maharashtra consolidate purchasing volumes across industrial laundry accounts. Galaxy Surfactants supplies regional formulators with specialty alkoxylates engineered for high-temperature foam suppression.
Netherlands
Food processing facilities in the Rotterdam port cluster specify cloud-point ethoxylates for clean-in-place systems operating above 60°C. EU Green Deal procurement incentives embed ISO 14001 credentials into detergent tender requirements for public hospital systems. Specialty surfactant production concentrates near Antwerp, creating supply vulnerability for North American formulators dependent on imported materials.
Japan
Precision manufacturing facilities in Osaka and Nagoya demand low-foam chemistries for automated component cleaning under METI industrial standards. Kao Corporation leverages domestic alkoxylation capacity to serve regional electronics and automotive parts washers. Formulators must validate biodegradability profiles under stricter local environmental guidelines than baseline OECD protocols.
Low-Foaming Detergent Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where integrated chemical majors supply commodity alkoxylates while specialty houses deliver performance additives. The vendor base separates into three strategic archetypes: multinational integrated suppliers with captive surfactant chemistry, regional formulators with dosing equipment bundling capabilities, and specialty additive houses focused on temperature-stable defoamers. Competitive moves concentrate on backward integration into fatty alcohol feedstocks and geographic expansion through toll manufacturing partnerships.
Among European integrated suppliers, BASF SE and Evonik Industries AG exemplify the diversified conglomerate archetype with broad surfactant portfolios spanning multiple industrial cleaning verticals. Clariant AG occupies a position within the specialty additive tier, representing focused expertise in foam suppression technologies for high-temperature wash cycles. Stepan Company anchors the North American manufacturing landscape, demonstrating how regional players compete through feedstock integration and proximity to industrial laundry clusters.
| Leading Market Players |
|---|
| Croda International Plc |
| Clariant AG |
| BASF SE |
| Akzo Nobel N.V. |
| Galaxy Surfactants |
| Stepan Company |
| Solvay S.A. |
| Kao Corporation |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Industrial laundry consolidators and multinational hospitality procurement groups concentrate purchasing volumes, anchoring contract-based long-term offtake pricing that rewards volume scale and ISO 14001 certification tiers over spot-market flexibility.
Pricing Analysis
Bundled service contracts dominate industrial channels, pairing liquid concentrate supply with leased dosing equipment and technical support, while unbundled transactional sales persist in fragmented hospitality accounts. Three-tier pricing structure across premium, standard, and economy levels separates EPA Safer Choice-certified formulations from REACH-compliant mid-tier products and uncertified economy blends. Pricing pressure stems from palm kernel oil feedstock volatility squeezing ethoxylate producers. Household consumers show highest price sensitivity, while food processing facilities prioritize throughput reliability over per-kilogram chemistry cost.
Supply Chain Analysis
Regional distribution centers in Germany's Rhine corridor and the Netherlands' Rotterdam-Antwerp belt anchor hub-and-spoke patterns serving European formulators, with Illinois-based facilities covering North American industrial laundries. Specialty alkoxylate production concentrates in Germany, the Netherlands, and the United States, drawing from Malaysian and Indonesian palm kernel oil and narrow-cut fatty alcohol feedstocks. Single-source vulnerability in cloud-point-controlled ethoxylates creates geographic risk for North American formulators. Distribution runs through wholesale tanker delivery with equipment leasing bundles for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-certified tiers as REACH and EPA compliance costs filter out commodity competitors, while backward integration into fatty alcohol feedstock anchors cost-down potential for integrated suppliers.
For Market Incumbents: Lock in supply security through captive fatty alcohol production or long-term offtake agreements with Malaysian and Indonesian feedstock processors. Defend against specialty additive houses by embedding silicone-polyether hybrid defoamers into integrated alkoxylate portfolios. Prioritize EPA Safer Choice certification investment to capture procurement filters at multinational hospitality chains. For New Entrants and Emerging Players: Launch via direct-to-industrial online platforms targeting small pharmaceutical manufacturers in Hyderabad and Bangalore requiring CDSCO-validated cleaning protocols. White-space exists in toll manufacturing partnerships for North American formulators seeking geographic supply diversification. Focus initial penetration on silicone defoamer concentrates for high-temperature clean-in-place systems. For Investors and Strategic Acquirers: Specialty chemical conglomerates with surfactant portfolios are the most active acquirers in this space, seeking cloud-point engineering capabilities and EPA Safer Choice dossier libraries. Five-to-ten-year viability hinges on defluorination exposure management and biodegradability validation infrastructure. Watch ECHA phased restriction timelines as inflection signals for alkoxylate substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Feedstocks | Stepan Company's Illinois operations demonstrate margin stability against palm oil price swings. |
| EPA Safer Choice Certification Investment | Industrial laundries in Wisconsin prioritize certified products for corporate sustainability mandates. |
| Silicone-Polyether Hybrid Defoamer Development | Clariant AG leverages temperature-stable foam control for food processing above 60°C. |
| Toll Manufacturing Partnership Expansion | North American formulators reduce geographic vulnerability to German and Dutch supply concentration. |
| Direct-to-Industrial Online Platform Launch | Small pharmaceutical accounts in India bypass traditional wholesale channel constraints. |
Research Methodology
Coverage spans Germany, the United States, India, the Netherlands, and Japan, with primary inputs from each market gathered through interviews with plant managers at industrial laundries, procurement leads at food processing facilities, technical R&D directors at surfactant suppliers, and channel partners in wholesale distribution. Secondary validation drew from ECHA REACH restriction documents, EPA Safer Choice certified product listings, FDA food-contact notification databases, and customs trade data on fatty alcohol imports. Bottom-up volume builds triangulated against top-down market sizing across product type and application segments.
Granularity-level modeling operated at the country-application-product type intersection, with separate projections for liquid concentrates, powders, pods, and tablets across industrial cleaning, household use, auto detailing, and hospitality end-uses. CAGRs were derived from trend extrapolation of high-efficiency machine penetration rates and regulatory compliance deadline impacts. Forecast inputs included tunnel washer installation data from German and U.S. industrial laundry associations and CDSCO sterile processing facility expansion plans in Indian pharmaceutical clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden palm kernel oil supply disruptions or accelerated PFAS restriction timelines. Outputs reflect documented assumptions on regulatory phase-in schedules and feedstock price normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market