
 Drain Opener Chemicals Market | 2026-2036
Drain Opener Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Drain Opener Chemicals Market Analytics
Commercial kitchen operations is decoupling from residential maintenance as the primary volume driver for alkaline drain opener formulations. Reckitt Benckiser Group leverages its retail shelf presence across multiple continents to sustain brand recognition in consumer channels. Procter & Gamble anchors its position through concentrated liquid technologies that reduce packaging weight and shipping costs. Henkel competes in European professional cleaning segments with specialized enzymatic products targeting hospitality grease traps.
Drain opener chemicals comprise caustic, acidic, enzymatic, and surfactant-based formulations designed to dissolve or disperse organic blockages, mineral deposits, and grease accumulations in plumbing systems, typically operating within pH extremes or catalytic degradation pathways. Sodium hydroxide-based products dominate industrial applications due to aggressive saponification of fats and oils, while enzymatic segments capture margin pools in environmentally sensitive institutional contracts where discharge permits restrict chemical oxygen demand loads. Liquid formulations lead residential channels for consumer convenience, though gel variants are gaining traction in commercial maintenance programs for their cling time on vertical pipe surfaces.
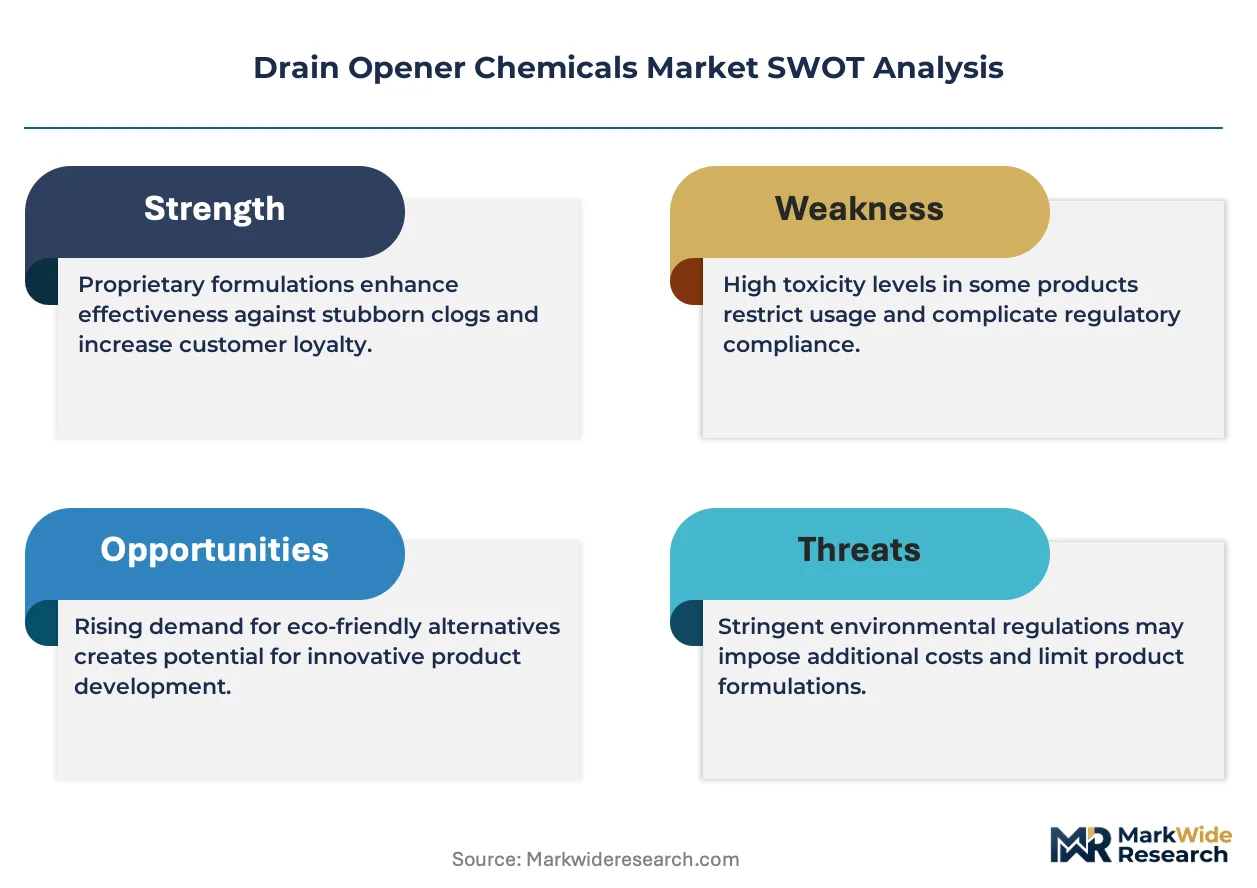
The EPA regulates drain opener chemicals under FIFRA and TSCA, requiring hazard communication and disposal compliance that elevates formulation costs for sulfuric acid products. REACH registration in Europe restricts corrosive active ingredients, pushing manufacturers toward surfactant and biological alternatives with lower aquatic toxicity profiles. OSHA workplace exposure limits further constrain industrial-use product concentration levels. Stakeholders must monitor evolving state-level plumbing code amendments and municipal pretreatment standards that increasingly prohibit high-pH discharges from commercial facilities.
Market Dynamics
Municipal wastewater infrastructure upgrades across North America and Europe are redirecting procurement toward enzymatic formulations, while REACH and EPA Safer Choice restrictions compress the addressable market for corrosive alkaline products.
Growth Catalysts
- EPA Safer Choice Program:Federal procurement preferences for low-toxicity formulations accelerate surfactant-based product development in institutional channels.
- Commercial kitchen density:Foodservice grease trap maintenance requirements in the United States sustain alkaline drain opener volume in professional segments.
- Enzymatic catalysis:Biological degradation pathways capture margin pools in environmentally sensitive contracts where discharge permits restrict chemical oxygen demand loads.
Market Restraints
- Sulfuric acid feedstock volatility:Sulfur-based industrial chemical supply concentration in China creates input cost instability for acidic formulation manufacturers.
- REACH registration burden:European corrosive active ingredient restrictions elevate compliance costs and compress product portfolios for sulfuric acid-based offerings.
- Caustic soda supply chain:Sodium hydroxide production concentration in chlor-alkali clusters exposes formulators to energy-price transmission effects.
Strategic Opportunities
- United States municipal pretreatment standards:State-level plumbing code amendments increasingly prohibit high-pH commercial discharges, creating demand for neutral-pH biological alternatives.
- E-commerce direct fulfillment:Concentrated liquid technologies reduce shipping weights and enable last-mile delivery models bypassing traditional retail shelf competition.
- Hospitality sector contracts:Specialized enzymatic products targeting European professional cleaning segments offer recurring revenue structures.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant-biological hybrid systems remains concentrated among legacy industrial cleaning R&D functions.
- OSHA exposure limit compliance:Workplace safety documentation requirements for high-pH industrial products extend certification timelines and elevate liability insurance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drain Opener Chemicals Market |
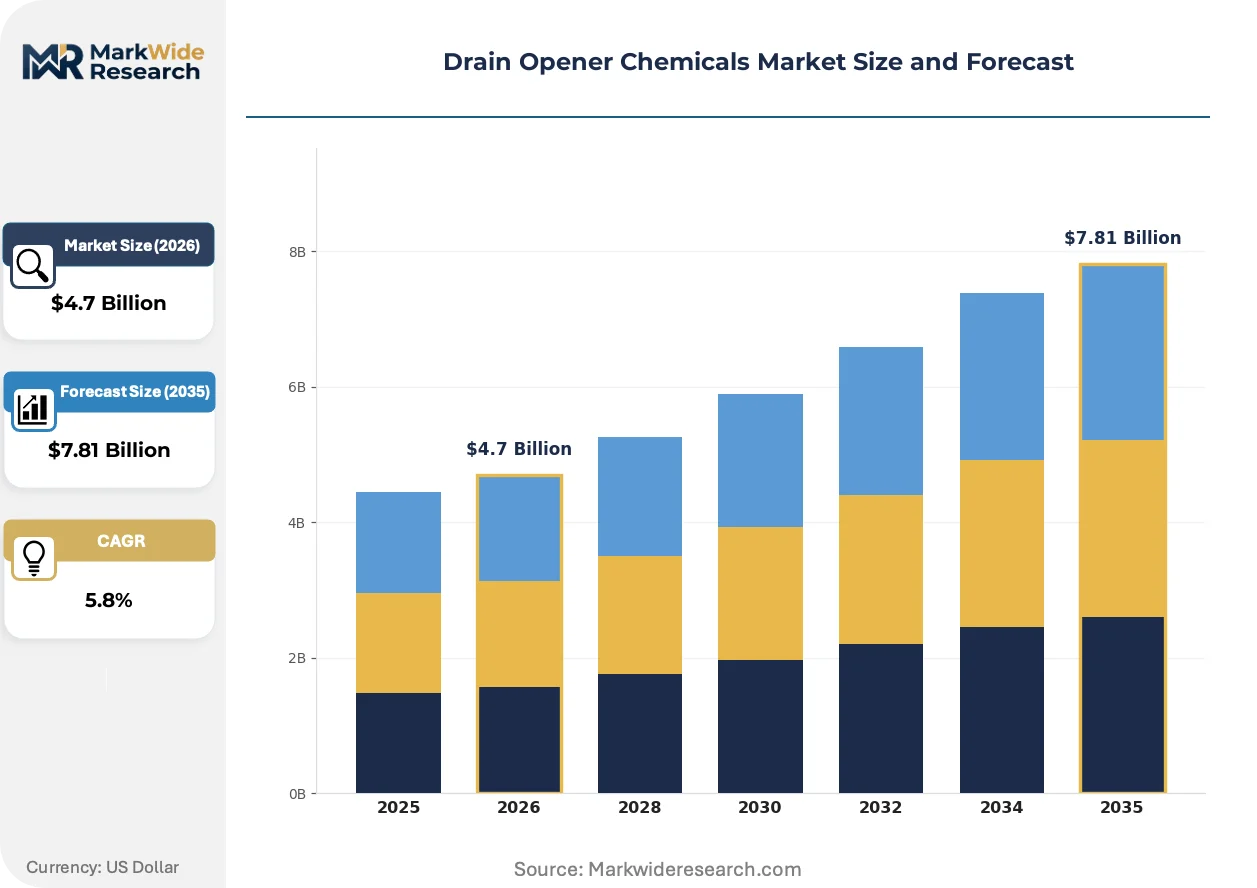
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Gel, Granular Active Ingredient: Sodium Hydroxide, sulphuric Acid, Enzymatic, Surfactants Application: Residential Use, Commercial Use, Industrial Use, Institutional Use Packaging Type: Bottles, Tubs, Pouches, Cans |
| Companies Covered | Reckitt Benckiser Group, 3X Chemistry, Procter & Gamble, Camco Manufacturing, Ridgid, S.C. Johnson & Son, The Clorox Company, Thetford Corporation, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drain Opener Chemicals Market Evolving Landscape
Formulation chemistry is pivoting from aggressive pH extremes toward catalytic and surfactant-based mechanisms that satisfy tightening discharge regulations without sacrificing clearing efficacy.
Enzymatic drain opener technology is consolidating market position in institutional procurement channels. These formulations deploy lipase, protease, and cellulase enzymes to degrade organic blockages through biocatalytic pathways rather than chemical dissolution. Municipal wastewater authorities in Germany and the Netherlands now specify enzymatic products for commercial kitchen pretreatment systems. The technology is consolidating margin pools previously captured by caustic soda manufacturers in environmentally sensitive contract segments.
REACH restrictions on corrosive substances are compressing the viable formulation space for traditional drain opener chemistry. ECHA registration requirements for sulfuric acid and sodium hydroxide at high concentrations have triggered portfolio rationalization among European manufacturers. Professional cleaning segments in France and Belgium are accelerating adoption of surfactant-based alternatives with lower aquatic toxicity profiles.
Facility maintenance managers are unbundling chemical supply from equipment service contracts in commercial kitchen operations. Independent procurement of enzymatic maintenance doses replaces bundled offerings from grease trap servicing firms. This pattern concentrates in the United States, where restaurant chain operators centralize purchasing decisions and negotiate direct supply agreements with chemical manufacturers.
Drain Opener Chemicals Market Segmentation
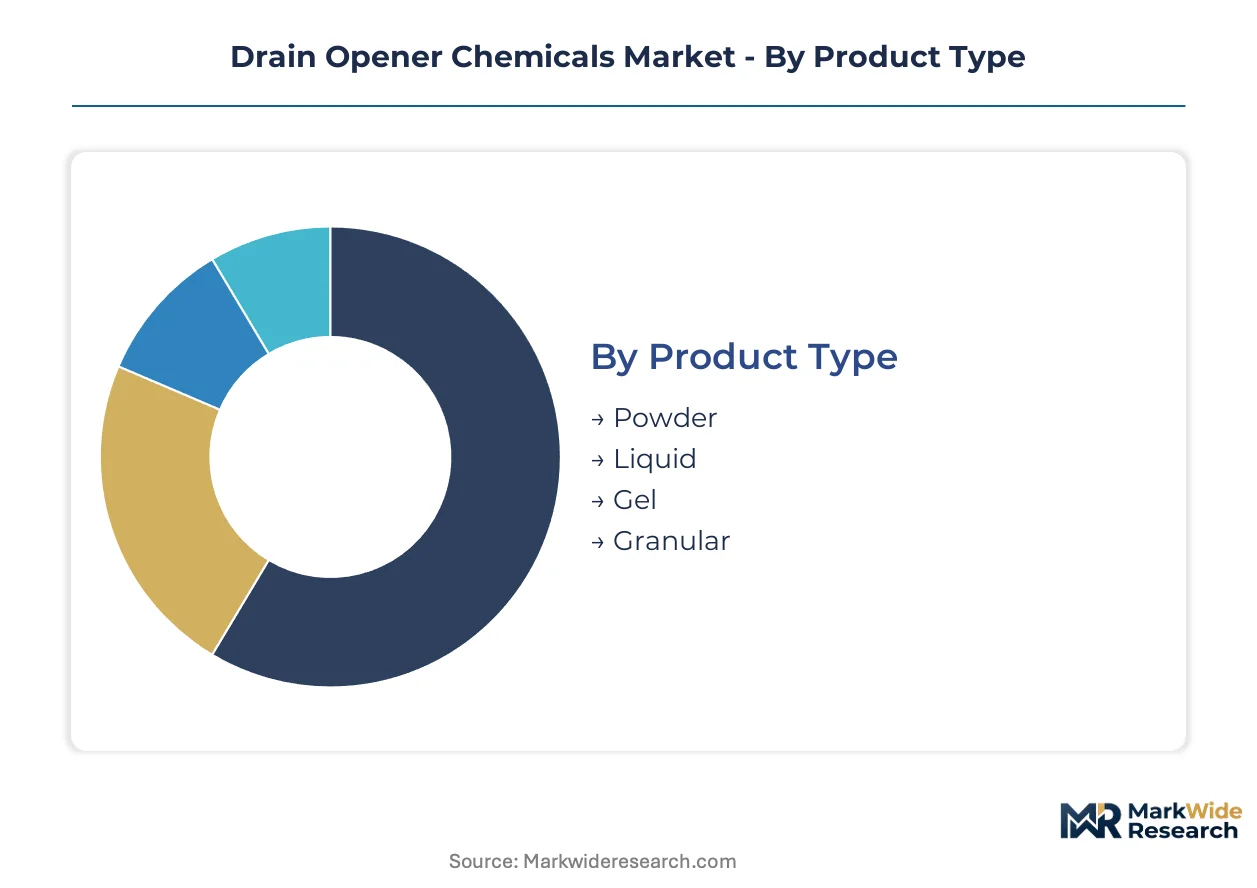
Drain opener chemical purchasing patterns diverge sharply between retail convenience buyers and professional maintenance contractors. Formulation chemistry, physical state, and packaging format each dictate distinct margin structures and regulatory exposure across end-use channels.
Product Type:
Liquid and gel formats command premium shelf positioning while powder and granular variants dominate volume procurement in institutional contracts.
- Liquid:Concentrated aqueous formulations enable precise dosing and reduced packaging mass for e-commerce fulfillment. Residential consumers in the United States favor liquid products for immediate clog response in kitchen and bathroom drains.
- Gel:Thickened rheology extends cling time on vertical pipe surfaces, improving contact duration with grease accumulations. Commercial kitchen maintenance programs specify gel products for scheduled grease trap dosing protocols.
- Powder:Dry alkali blends offer cost-efficient bulk procurement for industrial facilities managing high-frequency drain maintenance.
- Granular:Coarse particle size reduces dusting hazards during handling and dissolves gradually in standing water applications.
Today's leader: Liquid. Tomorrow's challenger: Gel.
Active Ingredient:
Chemical oxygen demand restrictions and workplace safety limits are fragmenting procurement across corrosive, biological, and surfactant-based mechanisms.
- Sodium Hydroxide:Caustic soda formulations deliver aggressive saponification of fat and oil blockages through high-pH chemistry. Foodservice operations in the United States sustain volume demand despite municipal pretreatment constraints on alkaline discharge.
- Enzymatic:Lipase and protease catalysis degrades organic matter without pH extremes, satisfying EPA Safer Choice criteria for federal procurement. German and Dutch wastewater authorities specify enzymatic products for commercial kitchen pretreatment systems.
- Sulphuric Acid:Strong acid chemistry targets mineral deposits and hair accumulations in residential drain applications.
- Surfactants:Amphiphile-based formulations disperse grease through micelle formation rather than chemical degradation, aligning with REACH aquatic toxicity restrictions.
Current procurement favors Sodium Hydroxide for efficacy; regulatory pressure elevates Enzymatic as the steepest expansion trajectory.
Application:
Commercial kitchen density and aging residential plumbing stock sustain divergent demand profiles across consumer and professional channels.
- Residential Use:Emergency clog response drives impulse purchasing through retail and e-commerce channels. United States homeowners generate recurring demand for convenient liquid formulations.
- Commercial Use:Scheduled maintenance protocols in foodservice operations require specialized grease-dissolving chemistry. Restaurant chain operators centralize procurement decisions and negotiate direct supply agreements.
- Industrial Use:Manufacturing facilities specify high-concentration caustic products for process drain maintenance.
- Institutional Use:Schools, hospitals, and municipal facilities prioritize enzymatic and surfactant formulations to comply with discharge permit restrictions.
Commercial Use anchors professional segment revenue; Institutional Use is gaining share fastest under regulatory pressure.
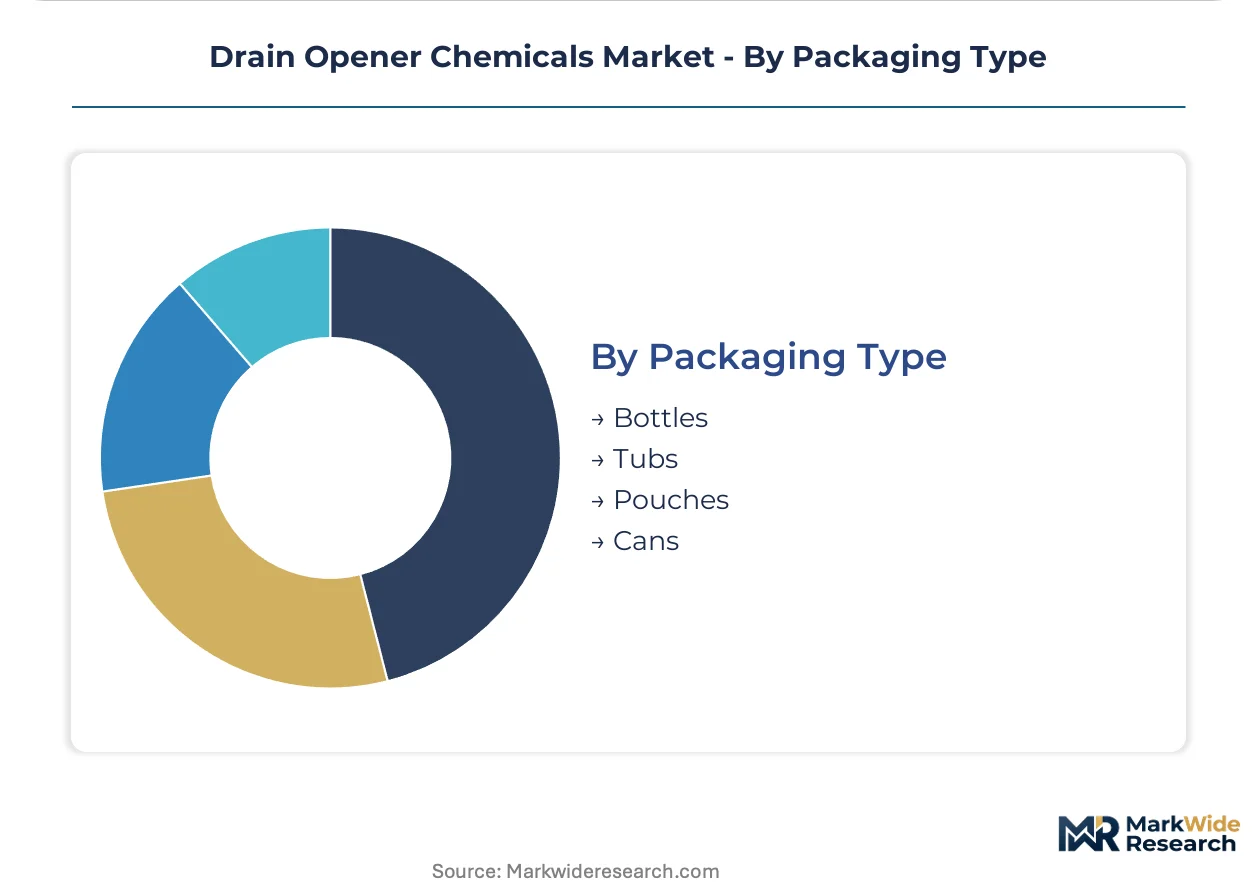
Packaging Type:
Shipping economics and storage constraints determine format selection across retail, professional, and industrial procurement channels.
- Bottles:Molded polyethylene containers dominate residential retail shelves with ergonomic handling and child-resistant closure options.
- Tubs:Wide-mouth rigid packaging facilitates scoop-based dosing for powder and granular products in commercial maintenance settings.
- Pouches:Flexible film formats reduce shipping cube and material cost for concentrated liquid refill applications.
- Cans:Aerosol or pressurized metal containers serve specialized foaming applications in industrial drain maintenance.
Bottles retain consumer channel dominance; Pouches represent the most disruptive format for direct fulfillment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as REACH compliance costs in Europe push formulation R&D toward jurisdictions with streamlined chemical notification regimes. Production capacity for enzymatic alternatives is concentrating in the United States and Germany where EPA Safer Choice and EU Green Deal procurement incentives offset higher labor costs.
United States
Aging residential plumbing stock and commercial kitchen density sustain alkaline drain opener volume leadership. EPA Safer Choice program preferences accelerate federal procurement of surfactant-based formulations. Chicago and Houston industrial corridors host concentrated blending operations serving foodservice maintenance contracts.
Germany
Municipal wastewater authorities in Bavaria and North Rhine-Westphalia specify enzymatic products for commercial kitchen pretreatment systems. ECHA registration requirements for corrosive actives compress portfolios for sulfuric acid-based offerings. Frankfurt-Rhine-Main chemical cluster houses specialized R&D for biological degradation pathways.
Netherlands
Rotterdam port logistics enable bulk caustic soda import for European formulation networks. REACH aquatic toxicity restrictions elevate surfactant adoption in professional cleaning segments. Eindhoven-Brabant region concentrates enzymatic product development for hospitality grease trap applications.
China
Domestic chlor-alkali capacity supplies sodium hydroxide feedstock for industrial drain maintenance formulations. GB standards and MEE discharge regulations constrain high-pH product distribution in coastal provinces. Yangtze River Delta chemical parks manufacture sulfur-based intermediates for acidic formulations.
France
ANSM workplace safety documentation extends certification timelines for high-pH industrial products. Île-de-France hospitality sector contracts drive enzymatic maintenance dose procurement. Lyon chemical engineering cluster develops surfactant-biological hybrid systems for institutional discharge compliance.
Drain Opener Chemicals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consumer channels consolidating around household names while professional procurement fragments across regional formulators. The vendor base separates into three strategic archetypes: multinational FMCG conglomerates with retail shelf dominance, mid-scale chemical specialists serving institutional maintenance contracts, and private-label manufacturers capturing price-sensitive volume. Competitive moves concentrate on portfolio diversification toward enzymatic alternatives and geographic expansion through direct e-commerce fulfillment models.
Within the multinational tier, Reckitt Benckiser Group, Procter & Gamble, and Henkel occupy positions defined by retail distribution depth and concentrated liquid technology platforms. Reckitt Benckiser Group exemplifies the branded specialist archetype through multi-continental shelf presence. Procter & Gamble anchors scale-driven manufacturing efficiency for shipping-weight reduction. Henkel represents European professional segment specialization with hospitality-focused enzymatic positioning.
| Leading Market Players |
|---|
| Reckitt Benckiser Group |
| 3X Chemistry |
| Procter & Gamble |
| Camco Manufacturing |
| Ridgid |
| S.C. Johnson & Son |
| The Clorox Company |
| Thetford Corporation |
| Henkel |
| Others |
Value Network & Pricing Analysis
Caustic soda futures pricing on the US Gulf Coast chlor-alkali benchmark cascades through three distinct procurement tiers, with bulk industrial contracts absorbing volatility while retail shelf prices adjust quarterly to cover polyethylene packaging and freight cost pass-through.
Pricing Analysis
Distributor margin compression in institutional channels separates enzymatic premium formulations from commodity alkaline alternatives. Three-tier pricing structure across premium enzymatic, standard surfactant, and economy caustic levels reflects EPA Safer Choice certification status and volume commitment scale. Pricing pressure stems from REACH registration cost recovery in European sulfuric acid portfolios. Foodservice maintenance contractors exhibit lowest price sensitivity due to bundled grease trap service economics, while residential retail buyers shift aggressively toward private-label alternatives.
Supply Chain Analysis
Empty polyethylene bottle returns from commercial foodservice accounts feed regional reconditioning networks that reduce virgin resin procurement for institutional refill programs. Chlor-alkali production clusters in the United States, Germany, and China supply sodium hydroxide feedstock for alkaline formulation networks. Sulfur-based intermediates for acidic products draw from Yangtze River Delta chemical parks. Single-source vulnerability concentrates in Chinese sulfuric acid feedstock concentration. Distribution runs through regional chemical distributors serving professional cleaning segments and mass-market retailers for consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation R&D arbitrage between EPA Safer Choice procurement incentives in the United States and REACH compliance burdens in Europe creates geographic cost differentials favoring North American enzymatic production scale-up.
For Market Incumbents: Anticipate margin erosion in high-pH alkaline portfolios as municipal pretreatment standards tighten across US metropolitan areas. Consolidate backward integration into chlor-alkali capacity in Texas and Louisiana to secure caustic soda feedstock cost stability. Accelerate EPA Safer Choice certification pipelines for surfactant-based alternatives before state-level plumbing code amendments proliferate.
For New Entrants and Emerging Players: Capture unbundled procurement opportunities in US restaurant chain centralized purchasing, where independent enzymatic maintenance dose agreements replace bundled grease trap servicing contracts. Target hospitality sector direct supply relationships in Germany and the Netherlands where municipal wastewater authorities specify biological pretreatment systems. Lead with e-commerce pouch-format concentrated liquids to bypass retail shelf slotting fees.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale enzymatic specialists possessing existing EPA Safer Choice formulations and established foodservice distributor relationships. Five-to-ten year viability hinges on regulatory trajectory rather than technology displacement. Monitor ECHA substance restriction proposals for sulfuric acid concentration thresholds as the critical inflection signal for portfolio reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Captive sodium hydroxide supply insulates Reckitt Benckiser and Henkel from energy-price transmission effects in Gulf Coast production clusters. |
| EPA Safer Choice Certification Pipeline | Federal procurement preferences accelerate institutional channel access for Procter & Gamble's concentrated liquid enzymatic platforms. |
| Direct E-Commerce Fulfillment Infrastructure | Pouch-format concentrated liquids enable S.C. Johnson to bypass mass-market retailer slotting fees and capture last-mile margin. |
| Joint Venture with Municipal Wastewater Authorities | Preferred supplier status in Dutch and German commercial kitchen pretreatment systems locks in recurring enzymatic dose revenue streams. |
| Surfactant-Biological Hybrid R&D Consortium | Lyon and Frankfurt-Rhine-Main chemical engineering clusters develop next-generation formulations satisfying REACH aquatic toxicity restrictions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at chlor-alkali production facilities, procurement leads at foodservice chain operators, distribution channel partners in professional cleaning segments, and technical R&D directors at enzymatic formulation specialists. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic sector reports, SEC 10-K filings, and EPA Safer Choice product registry databases. Bottom-up volume modeling across formulation chemistry tiers triangulated against top-down market sizing from trade association production statistics.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand patterns and post-regulatory-shift adjustment trajectories across the modeling period. Segmentation dimensions spanned active ingredient chemistry, physical formulation state, packaging format, end-use application intensity, and regional regulatory cluster. CAGRs emerged from weighted average growth across these segments informed by chlor-alkali capacity expansion announcements, REACH substance restriction timelines, and municipal pretreatment standard adoption curves.
Underlying measurement precision varies by segment; institutional procurement data carries tighter precision than fragmented residential retail channel estimates. Forecasts reflect documented assumptions regarding regulatory implementation pacing and feedstock cost pass-through elasticity. Practitioners should monitor ECHA corrosive substance restriction proposals and state-level plumbing code amendment activity for early signals of portfolio reallocation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market