
 Bleaching Chemicals Market | 2026-2036
Bleaching Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Bleaching Chemicals Market Analysis
Hydrogen peroxide is decoupling bleaching economics from chlorine dependency in pulp processing. BASF SE leverages its integrated peroxide chain across European and North American supply nodes. Kemira anchors Nordic paper mill contracts through on-site generation partnerships. Solvay differentiates via specialized grades for textile pretreatment in Mediterranean markets.
Bleaching chemicals are oxidizing agents formulated to remove color, degrade lignin, or sanitize surfaces, with hydrogen peroxide typically supplied at 35-70% concentration for industrial applications and stabilized against decomposition. The pulp and paper application commands the largest volume share as mills substitute chlorine dioxide and elemental chlorine to meet effluent toxicity limits. Hydrogen peroxide product types capture the fastest expansion trajectory, driven by effluent regulation and fiber yield optimization. Food-grade formulations represent a concentrated margin pool, with pharmaceutical and laboratory grades requiring GMP and pharmacopeia compliance that limits supplier entry.
EPA cluster rules and REACH restrictions on absorbable organic halogens are reshaping product qualification requirements for mill operators. BIS certification mandates in India and FDA food-contact notifications in the United States create divergent compliance pathways that favor multi-certification producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
EPA cluster rules and REACH absorbable organic halogen limits are forcing pulp mills to retire elemental chlorine systems, redirecting capital toward hydrogen peroxide infrastructure and on-site generation partnerships.
Growth Catalysts
- REACH phase-out mandates:European paper mills face binding deadlines to eliminate chlorinated bleaching sequences, accelerating hydrogen peroxide qualification programs.
- India BIS certification pipeline:Domestic textile hubs and export-oriented paper complexes in Gujarat and Tamil Nadu require certified industrial grades, concentrating demand growth.
- Peroxide stabilization chemistry:Advances in chelating additive packages extend shelf life for tropical supply chains, unlocking new distribution economics.
Market Restraints
- Anthracene derivative input volatility:Hydrogen peroxide production depends on quinone process intermediates whose pricing tracks energy and solvent markets.
- Specialized tanker fleet concentration:Bulk 70% concentration transport requires stainless steel vessels with explosion-proof specifications, limiting carrier options.
- Food-contact notification timelines:FDA clearance for new peroxide grades in packaging applications extends 18-24 months, freezing formulation innovation.
Strategic Opportunities
- Pharmaceutical-grade peroxide white space:GMP-compliant production for aseptic filling lines remains underserved outside European and North American supply nodes.
- EU Green Deal industrial transition incentives:Carbon border adjustment mechanisms favor low-emission peroxide production methods in import-competing regions.
- On-site generation partnerships:Electrolytic peroxide units at mill gates eliminate transport costs and concentration degradation risks for remote pulp facilities.
Industry Challenges
- Process safety engineering talent scarcity:Concentrated peroxide handling requires specialized hazard analysis competencies that outpace vocational training pipelines.
- Multi-jurisdiction certification synchronization:Mills supplying both FDA-notified and BIS-certified grades face divergent audit timelines and documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleaching Chemicals Market |
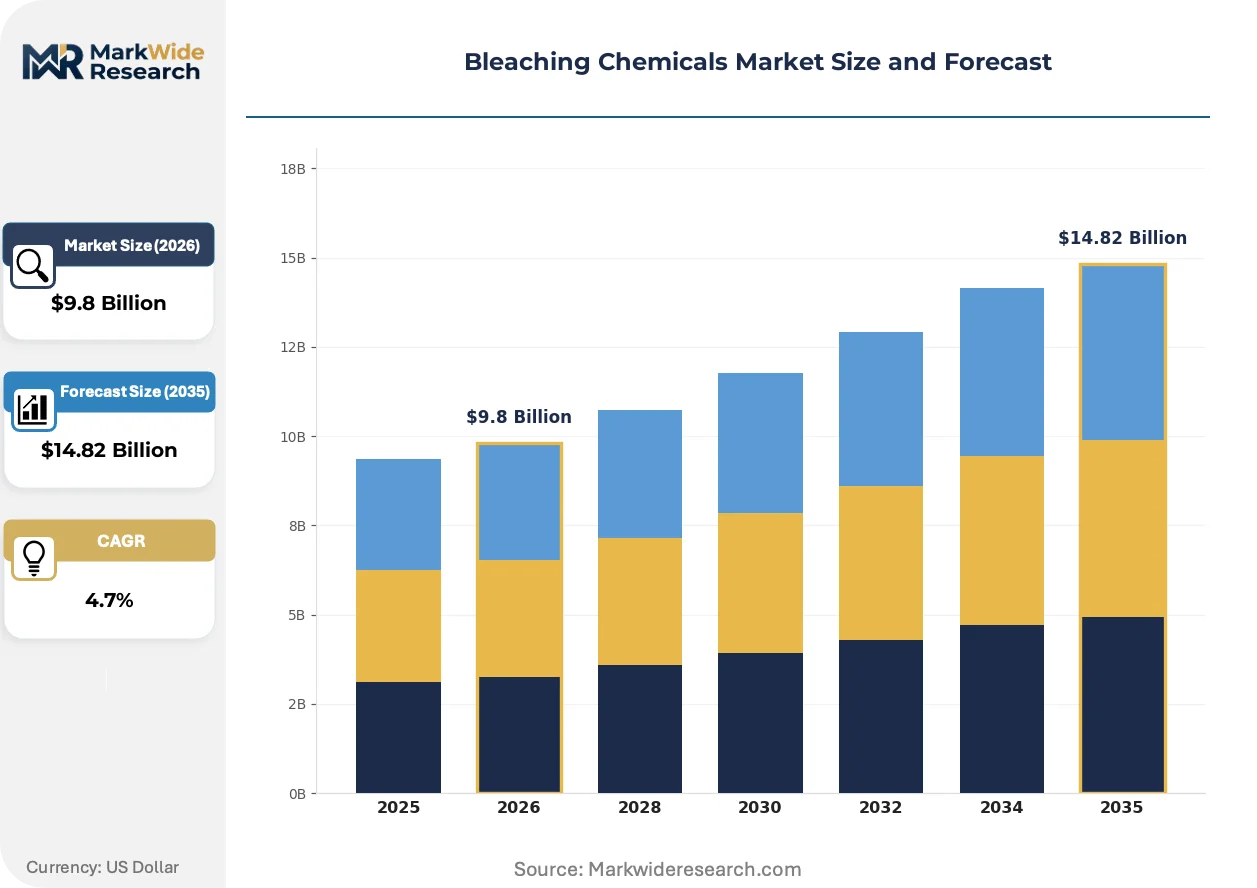
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.82 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorine, Hydrogen Peroxide, Sodium Hypochlorite, Sodium Perborate Application: Pulp & Paper, Textile, Water Treatment, Food & Beverages Grade: Industrial, Food, Pharmaceutical, Laboratory Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | BASF SE, Evonik Industries, Solvay, Kemira, Nouryon, Akzo Nobel, Arkema Group, Aditya Birla Chemicals, Mitsubishi Gas Chemical Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleaching Chemicals Market Emerging Trajectories
Peroxide bleaching sequences are displacing legacy chlorine chemistry through integrated process design, regulatory compliance automation, and concentrated formulation logistics.
Membrane electrolysis for on-site peroxide generation is unifying distributed production with consumption points. Nordic pulp mills deploy skid-mounted units producing 3-8% concentration directly at bleach plants, eliminating bulk transport and storage hazards. This technology is unifying supply security with effluent compliance in regions with sparse chemical distribution infrastructure.
EPA cluster rule updates and REACH restricted substance list expansions are tightening absorbable organic halogen limits for pulp effluents. Mills in the US Southeast and Baltic states face simultaneous pressure to certify chlorine-free sequences while maintaining fiber yield targets. Specialty peroxide grades with enhanced lignin selectivity are capturing qualification contracts in these regulated markets.
Textile pretreatment houses in India are consolidating chemical procurement through mill-direct arrangements rather than distributor networks. Large integrated dyeing operations in Surat and Tiruppur negotiate annual hydrogen peroxide supply contracts with volume-indexed pricing. This channel compression is visible where buyer scale justifies dedicated tankage and technical service support.
Bleaching Chemicals Market Segmentation
Segmentation in bleaching chemicals reveals how regulatory pressure and end-use specifications fragment supply requirements. Mills upgrading from chlorine sequences face distinct qualification pathways compared to food processors or pharmaceutical compounders.
Product Type:
Replacement cycles for elemental chlorine systems are accelerating qualification timelines for peroxide-based alternatives across mill engineering departments.
- Hydrogen Peroxide:Supplied at 35-70% concentration with stabilized formulations against decomposition, this oxidizer dominates new bleach plant installations. Pulp mills in Finland and the US Southeast are retiring chlorine dioxide generators for peroxide sequences under tightening EPA cluster rule enforcement.
- Chlorine:Elemental chlorine gas persists in legacy installations requiring capital-intensive decommissioning. Indian paper complexes in Tamil Nadu still operate chlor-alkali integrated mills where BIS effluent standards permit controlled discharge, though qualification pressure mounts.
- Sodium Hypochlorite:Dilute aqueous solution serves municipal water treatment and textile finishing where controlled oxidation suffices.
- Sodium Perborate:Powdered peroxygen finds niche demand in detergent compounding and specialty textile bleaching.
Hydrogen peroxide sits at the top of the volume ranking, with hydrogen peroxide climbing the fastest as mills execute chlorine phase-out timelines.
Application:
Cost tier differentiation separates commodity pulp processing from certified food-contact and pharmaceutical applications.
- Pulp & Paper:Kraft and mechanical pulp bleaching commands the largest volume consumption as mills substitute chlorine dioxide sequences. Nordic producers deploy membrane electrolysis units at mill gates to eliminate transport hazards for remote facilities.
- Textile:Pretreatment houses in Surat and Tiruppur negotiate direct supply contracts for scouring and bleaching cotton substrates. BIS-certified industrial grades serve export-oriented dyeing operations facing downstream brand audit requirements.
- Water Treatment:Municipal disinfection applications favor sodium hypochlorite for residual maintenance in distribution systems.
- Food & Beverages:Food-grade peroxide formulations require FDA notification or EFSA compliance for packaging sterilization and aseptic filling lines.
Pulp & Paper captures the dominant share by volume, with Food & Beverages expanding most quickly on aseptic packaging qualification demand.
Grade:
Margin structure stratifies sharply across certification tiers, with pharmaceutical and food grades commanding multiples over industrial specifications.
- Industrial:Standard specifications for pulp bleaching and textile processing carry baseline certification requirements. BIS marking in India and EPA registration in the United States create divergent documentation burdens for multi-destination suppliers.
- Food:Formulations require FDA food-contact notifications or EFSA safety assessments for packaging sterilization. Clearance timelines extend 18-24 months, freezing formulation innovation cycles for new entrants.
- Pharmaceutical:GMP-compliant production for aseptic filling lines demands pharmacopeia conformance that limits supplier entry outside established European and North American nodes.
- Laboratory:Analytical-grade specifications serve research and quality control applications with concentrated purity requirements.
Industrial grade dominates current volume, with Pharmaceutical grade gaining share fastest on biologics manufacturing expansion.
Form:
Supply concentration in bulk liquid distribution shapes procurement economics for high-volume mill customers.
- Liquid:Bulk tanker delivery of 35-70% hydrogen peroxide requires stainless steel vessels with explosion-proof specifications. Concentrated formulations reduce transport costs but limit carrier options to specialized fleets.
- Powder:Sodium perborate and stabilized percarbonate serve detergent compounders and textile operations lacking bulk liquid infrastructure.
- Granular:Controlled-release formulations find application in swimming pool sanitation and agricultural processing.
- Tablet:Solid dose formats serve remote water treatment and emergency sanitation kits where transport weight constraints apply.
Liquid form leads by volume, with Tablet formulations showing steepest expansion trajectory in decentralized sanitation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish pulp clusters anchor peroxide demand as Nordic mills retire chlorine sequences under REACH absorbable organic halogen limits.
United States
Southeastern kraft mills drive hydrogen peroxide qualification programs under EPA cluster rule enforcement. The EPA mandates binding effluent toxicity reductions for pulp facilities in Georgia and Alabama. Integrated bleach plants in the Savannah River corridor are converting chlorine dioxide generators to peroxide sequences.
Germany
Integrated chemical producers supply stabilized peroxide grades to Central European paper complexes. REACH restrictions on chlorinated organics force Rhineland mills to certify elemental chlorine-free sequences. BASF SE leverages its Ludwigshafen production node for just-in-time delivery to Nordic customers.
India
Textile pretreatment houses in Surat and Tiruppur negotiate direct supply contracts for BIS-certified industrial grades. The Bureau of Indian Standards mandates marking requirements for export-oriented dyeing operations. Gujarat chemical complexes are expanding peroxide storage infrastructure to serve consolidated buyer procurement.
China
Mechanical pulp producers in Shandong and Jiangsu provinces deploy membrane electrolysis units at mill gates. National dual carbon goals pressure coastal mills to eliminate chlor-alkali integrated bleaching. Yangtze River Delta paper clusters are qualifying low-emission peroxide sequences for European export compliance.
Finland
Nordic pulp mills anchor on-site generation partnerships with electrolytic peroxide producers. EU Green Deal industrial transition incentives favor carbon-efficient bleaching chemistry in Baltic Sea catchment areas. Kemira secures multi-year contracts through skid-mounted units producing 3-8% concentration directly at bleach plants.
Bleaching Chemicals Market Vendor Landscape
Global majors compete with regional champions across certification tiers and supply chain integration depth. The vendor base stratifies between multi-certification producers serving FDA and BIS pathways simultaneously, and single-jurisdiction specialists capturing local mill relationships. Three archetypes dominate: integrated chemical conglomerates with captive peroxide chains, regional champions anchoring Nordic or Indian mill contracts, and on-site generation technology licensors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with electrolytic unit deployment reshaping distribution economics for remote facilities.
Within the integrated chemical conglomerate tier, BASF SE and Solvay exemplify multi-node supply architectures spanning European and Mediterranean markets. Kemira occupies a distinctive position anchoring Nordic paper mill relationships through on-site generation partnerships. Among Asia-Pacific specialists, Mitsubishi Gas Chemical Company, Inc. and Aditya Birla Chemicals represent regional production gravity centers serving domestic textile and pulp demand clusters.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries |
| Solvay |
| Kemira |
| Nouryon |
| Akzo Nobel |
| Arkema Group |
| Aditya Birla Chemicals |
| Mitsubishi Gas Chemical Company, Inc. |
| Others |
Supply Flow & Price Mechanics
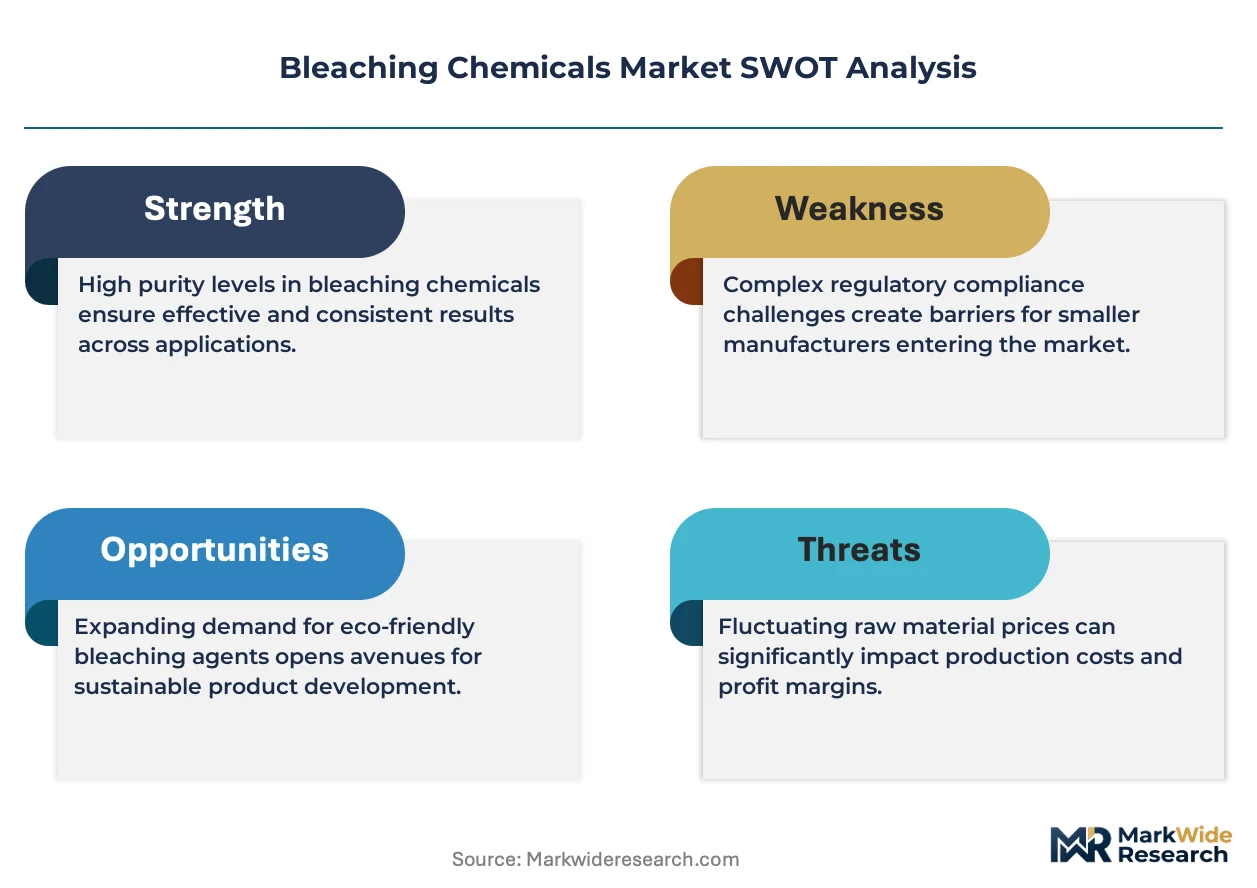
Anthracene derivative pricing volatility cascades through hydrogen peroxide production economics, compressing margins at industrial-grade tiers while pharmaceutical and food-grade certifications sustain premium capture against raw material headwinds.
Pricing Analysis
Input-cost pass-through from quinone process intermediates dominates hydrogen peroxide pricing, with energy and solvent market movements transmitting directly to mill-gate contracts. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates margin pools by certification burden, with FDA-notified and BIS-certified grades commanding sustained premiums. Cost compression in industrial specifications is intensifying as textile pretreatment houses in Surat and Tiruppur consolidate procurement through mill-direct annual contracts. Small-scale dyeing operations lacking dedicated tankage exhibit highest price sensitivity, while integrated pulp complexes with on-site generation partnerships lock in cost stability.
Supply Chain Analysis
Hydrogen peroxide supply rests on German, Belgian, and Finnish production nodes where integrated chemical conglomerates operate captive peroxide chains. The supply chain draws from anthracene derivative feedstocks, specialized stainless steel tanker fleets, and chelating additive packages for tropical stabilization. Single-source vulnerability concentrates in explosion-proof bulk transport capacity, where 70% concentration requirements limit carrier options to qualified specialized fleets. Distribution runs through direct mill-gate delivery for large pulp complexes, with distributor networks serving fragmented textile pretreatment houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bleaching chemicals constitute a late-cycle quality story as pulp mills and textile processors pivot from commodity chlorine chemistry toward certified peroxide specifications that command durable margin premiums.
For Market Incumbents: Deploy on-site generation partnerships as the anchor lever for account retention, converting remote Nordic and Southeast US mills to electrolytic units that eliminate transport costs and lock out competitors. BASF SE and Kemira demonstrate this model through skid-mounted 3-8% concentration units at Finnish bleach plants. Backward integration into anthracene derivative supply buffers margin pressure from energy-linked input volatility. Reinforce multi-certification capabilities across FDA, BIS, and REACH pathways to capture divergent regulatory demand without duplicate qualification costs. For New Entrants and Emerging Players: Pharmaceutical-grade peroxide production for aseptic filling lines represents the most penetrable white-space target, with GMP-compliant capacity concentrated outside European and North American nodes. India's domestic biologics manufacturing expansion creates qualification demand that incumbent supply chains underserve. Target BIS-certified industrial grades for Gujarat and Tamil Nadu textile hubs through mill-direct technical service relationships rather than distributor channel competition. A go-to-market angle anchored in peroxide stabilization chemistry for tropical supply chains unlocks shelf-life differentiation in high-humidity distribution environments. For Investors and Strategic Acquirers: Asymmetric upside sits with electrolytic on-site generation technology licensors and regional peroxide specialists holding BIS certification pipelines. Long-term viability favors assets positioned at the intersection of REACH chlorine phase-out mandates and EU Green Deal industrial transition incentives. Acquisition target archetype: mid-cap European or Indian producers with multi-certification infrastructure and established mill-gate delivery relationships. Watch FDA food-contact notification backlog clearance rates as inflection indicator for formulation innovation cycle resumption.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Partnership | Electrolytic units at Finnish and US Southeast mill gates eliminate transport hazards and secure multi-year supply contracts. |
| Multi-Certification Investment | Simultaneous FDA, BIS, and REACH qualification captures pulp and textile demand across divergent regulatory jurisdictions. |
| Backward Integration | Captive anthracene derivative supply insulates margin structures from energy-linked quinone process input volatility. |
| Pharmaceutical-Grade Capacity Buildout | GMP-compliant production for aseptic filling lines addresses biologics manufacturing expansion in underserved supply nodes. |
| Tropical Stabilization R&D | Chelating additive packages extending shelf life unlock distribution economics for high-humidity textile hub supply chains. |
Methodological Framework
Direct dialogue with pulp mill engineering directors, textile pretreatment procurement leads, hydrogen peroxide plant managers, and BIS certification auditors grounded qualitative findings in operational reality. Secondary validation drew from EPA cluster rule enforcement records, REACH restricted substance list updates, BIS marking requirement circulars, and SEC filings of integrated chemical producers. Bottom-up segmentation modeling triangulated against top-down trade flow analysis across the analysis window.
Market size and growth trajectory outputs reflect econometric modeling across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from regression analysis of historical qualification timelines, regulatory phase-out schedules, and capacity expansion announcements. Forecast inputs incorporated chlorine sequence retirement capital expenditure patterns, membrane electrolysis unit deployment rates, and pharmaceutical aseptic filling line investment pipelines.
Inputs from EPA enforcement databases and BIS certification registries were available through the study window; gaps in private mill-gate contract pricing introduce uncertainty bands around industrial-grade volume assumptions. Forecasts reflect documented regulatory timelines and announced capacity investments, with revision triggers including REACH absorbable organic halogen limit acceleration, FDA food-contact notification processing rate shifts, and anthracene derivative supply disruptions. A small set of named triggers—electrolytic unit cost curves, dual carbon goal enforcement in China, and Indian PLI scheme chemical sector extensions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Water-Saving Cleaning Chemical Systems for Professional Use Market