
 Charcoal-Infused Food Market | 2026-2036
Charcoal-Infused Food Market Size, Share, and Industry Trends Forecast 2026-2036
Charcoal-Infused Food Market Analysis
The FDA's interim stance on activated charcoal in food and beverage applications is repositioning the cost-of-entry calculus for domestic manufacturers. IHALO KRUNCH INC leverages its specialty snack focus to sustain premium shelf placement in urban retail corridors. Morgenstern's anchors its competitive profile through artisanal ice cream formulations that differentiate on visual intensity and flavor layering.
Charcoal-infused food denotes edible products incorporating carbonized organic matter, typically activated charcoal with surface areas exceeding 500 m²/g, to achieve distinctive pigmentation, textural modification, or perceived detoxification benefits. The ingredient type dimension shows activated charcoal commanding the deepest margin pools due to processing complexity, while bamboo charcoal competes on sustainability credentials and supply accessibility. Application through food service channels leads volume absorption as restaurants exploit theatrical plating value, though retail packaging is accelerating fastest behind convenience-oriented consumer migration.
The FDA, EFSA, and FSSAI collectively govern permissible charcoal particle specifications, with the FDA's GRAS ambiguity creating divergent compliance pathways that either accelerate or stall product registration depending on jurisdiction. The EU's novel food classification under EFSA review further fragments market access timelines for activated charcoal imports. Stakeholders must monitor regulatory harmonization momentum between these bodies to time portfolio expansion and avoid stranded formulation investments.
Market Dynamics
Regulatory ambiguity surrounding activated charcoal's food-grade status is fragmenting compliance pathways and forcing manufacturers to maintain parallel formulation portfolios across jurisdictions. This structural friction elevates working capital requirements and compresses margin predictability for new entrants.
Growth Catalysts
- Social media visual culture:Platforms like Instagram and TikTok reward high-contrast food photography, driving boutique bakeries and specialty coffee operators to adopt jet-black formulations for shareable menu items.
- EFSA novel food review timeline:The European Food Safety Authority's ongoing classification process is creating first-mover advantages for brands that secured early regulatory clarity in member states with permissive interim stances.
- Activated carbon surface engineering:Advanced activation techniques producing 800-1,500 m²/g specific surface areas enable lower dosage requirements, reducing aftertaste complaints that previously limited recipe integration.
Market Restraints
- Coconut shell feedstock volatility:Activated charcoal production depends on coconut shell charcoal imports from Southeast Asian suppliers, where weather disruptions and export quota fluctuations create input cost instability.
- FDA GRAS indeterminacy:The United States Food and Drug Administration has declined to affirm activated charcoal as Generally Recognized as Safe, forcing domestic manufacturers to pursue costly food additive petitions or self-determine compliance risk.
- Pharmaceutical interference concerns:Medical literature documenting activated charcoal's adsorption of oral medications has prompted liability-averse retailers to limit shelf placement in pharmacy-adjacent grocery formats.
Strategic Opportunities
- India FSSAI clearance pathway:India's Food Safety and Standards Authority maintains explicit provisions for charcoal use in traditional preparations, offering a regulatory template for standardized industrial-scale products.
- Direct-to-consumer subscription models:Specialty snack brands are bypassing conventional retail slotting fees through curated monthly boxes targeting wellness-oriented millennials.
- Clean-label convergence:Pairing activated charcoal with organic certification and plastic-neutral packaging addresses dual consumer priorities, commanding price premiums in urban coastal markets.
Industry Challenges
- Formulation stability expertise:Maintaining pigment intensity across freeze-thaw cycles and pH variations requires food science capabilities scarce outside established ingredient houses.
- Multi-jurisdiction label compliance:Divergent maximum permitted levels across FDA, EFSA, and FSSAI regimes force SKUs with country-specific packaging, inflating inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charcoal-Infused Food Market |
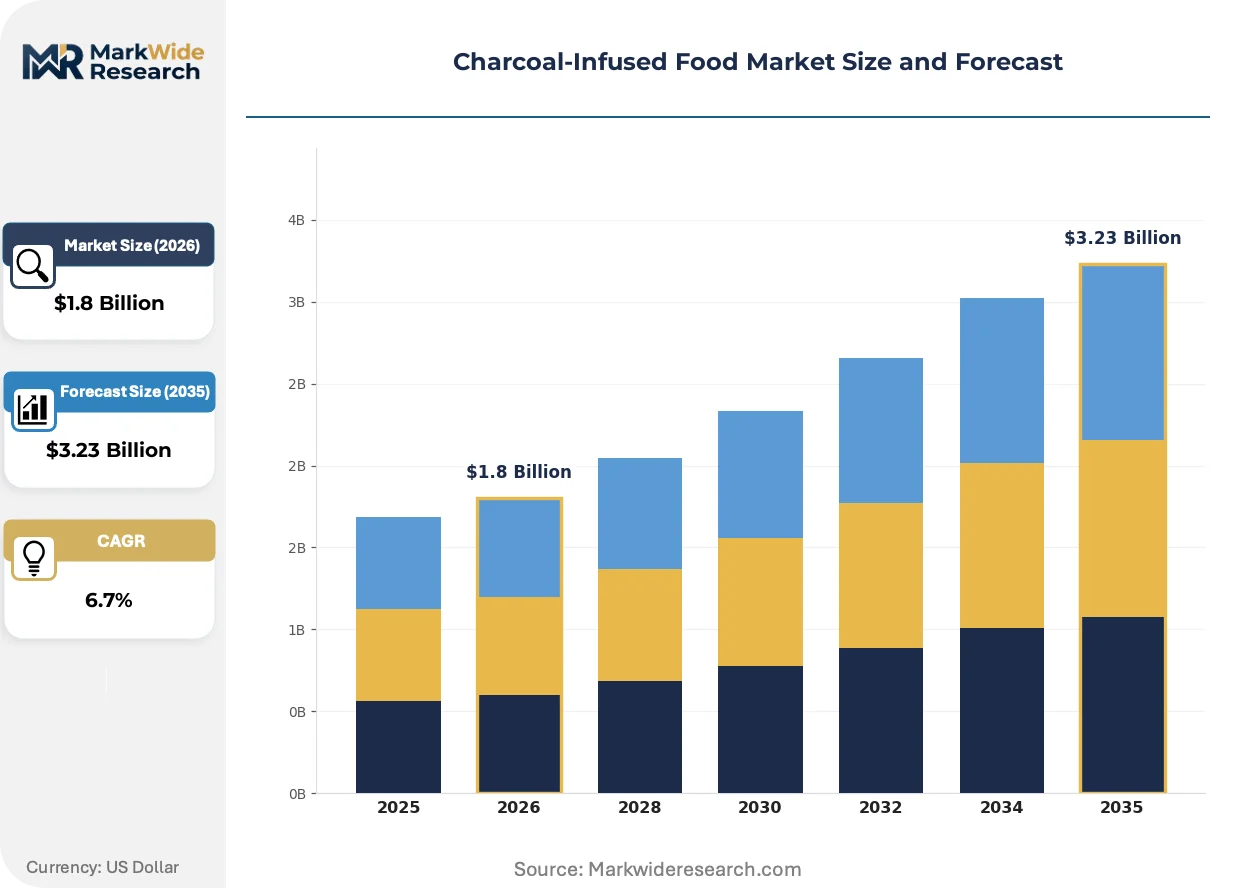
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Desserts, Condiments Application: Food Service, Retail, Home Cooking, Culinary Innovation Ingredient Type: Activated Charcoal, Bamboo Charcoal, Coconut Shell Charcoal, Vegetable Charcoal Target Audience: Health Conscious Consumers, Gourmet Food Enthusiasts, Restaurants, Foodies |
| Companies Covered | The Loop, The Nolen, IHALO KRUNCH INC, Morgenstern's, Ashley Sue's Baked Goods, The Good Sort, Macaroon, Ritzcarlton, Chocolate Pi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charcoal-Infused Food Market Emerging Trajectories
Visual-first food culture is compressing product development cycles, forcing manufacturers to prioritize photogenic innovation over incremental flavor refinement. This shift rewards rapid formulation iteration and direct consumer feedback loops.
Micro-encapsulation technology is unifying pigment delivery with flavor masking in charcoal-infused applications. Beverage manufacturers in California and New York are adopting spray-dried charcoal particles coated with maltodextrin to prevent sedimentation and bitter off-notes. This convergence is collapsing the traditional trade-off between visual impact and palatability that previously constrained category expansion.
REACH authorization requirements for certain carbon black variants are pressuring European suppliers to document supply chain purity. The European Chemicals Agency's substance evaluation process is extending lead times for imported activated charcoal, compelling regional formulators to qualify alternative biomass sources. Food service operators in Germany and France are responding by emphasizing bamboo-derived charcoal with established sustainability credentials.
Wellness-oriented consumers are scrutinizing detoxification claims with greater skepticism, compressing the window for pseudoscientific marketing. Specialty retailers in Los Angeles and Miami are shifting shelf positioning from supplement-adjacent to gourmet ingredient sections, reframing charcoal as a culinary aesthetic rather than a functional additive. This recategorization is most visible in independent grocery formats with educated buyer demographics.
Charcoal-Infused Food Market Segmentation
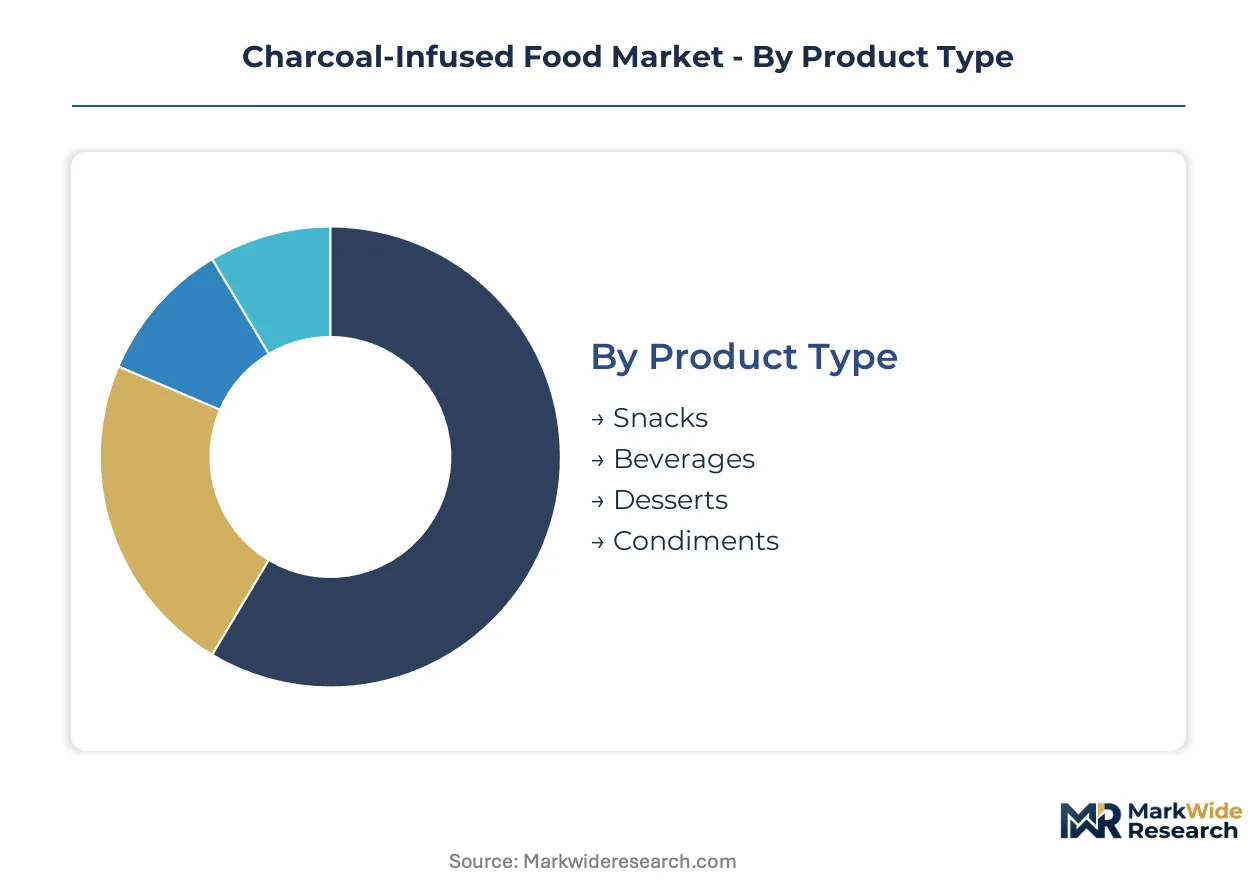
Segmentation in charcoal-infused food tracks how deeply the ingredient penetrates product architecture—from surface decoration to core formulation. Manufacturers optimize production lines differently for each tier, with standalone applications demanding precise dosage control and embedded systems requiring stability across processing conditions.
Product Type:
Integration depth varies sharply: snacks and beverages embed charcoal throughout the matrix, while desserts and condiments often deploy it as a surface or layer accent.
- Snacks:Extruded and puffed formats incorporate activated charcoal at 0.5-2% by weight to achieve uniform jet-black coloring without structural compromise. Specialty retailers in Los Angeles and New York stock these in premium positionings near checkout, driven by Instagram-friendly packaging and shareable unboxing moments.
- Beverages:Ready-to-drink lattes, lemonades, and detox waters suspend micro-encapsulated charcoal to prevent sedimentation and bitter aftertaste. California-based coffee chains lead adoption, using visual contrast against white cup interiors to drive social media tagging.
- Desserts:Ice creams, macarons, and pastries deploy charcoal as a visual anchor in layered compositions.
- Condiments:Mayonnaise, hot sauces, and finishing salts use charcoal for dramatic plating accents in high-end dining.
Snacks lead volumes today; beverages are gaining share fastest.
Application:
Cost tier separation is pronounced: food service absorbs premium-priced theatrical applications, while retail and home cooking compete on unit economics and convenience.
- Food Service:Restaurants and cafes exploit charcoal's photogenic properties for menu differentiation, with plating labor cost absorbed into premium pricing. Miami's boutique hotel restaurants and New York's tasting-menu venues deploy it in course-progression narratives.
- Retail:Packaged goods face shelf-space constraints and label compliance complexity across FDA, EFSA, and FSSAI jurisdictions.
- Home Cooking:Direct-to-consumer charcoal powders and capsules target wellness-oriented millennials through subscription boxes.
- Culinary Innovation:R&D kitchens and food tech incubators experiment with charcoal in 3D-printed foods and cellular agriculture scaffolds.
Food Service commands margin pools; Retail is expanding most quickly.
Ingredient Type:
Supply concentration and processing sophistication create steep margin ladders, with activated charcoal at the top and vegetable charcoal competing on locality.
- Activated Charcoal:Steam-activated coconut shell or wood carbon achieves 800-1,500 m²/g surface area, enabling low-dose pigmentation and adsorption claims. FDA GRAS ambiguity elevates compliance costs for domestic manufacturers, concentrating supply among established ingredient houses with petition expertise.
- Bamboo Charcoal:Japanese and Chinese suppliers leverage rapid-growth feedstock for sustainability credentials and REACH-aligned European access.
- Coconut Shell Charcoal:Southeast Asian supply chains face weather volatility and export quota fluctuations.
- Vegetable Charcoal:Traditional European preparations use grape vine or oak char for regional authenticity claims.
Activated Charcoal dominates value capture; Bamboo Charcoal shows steepest expansion trajectory.
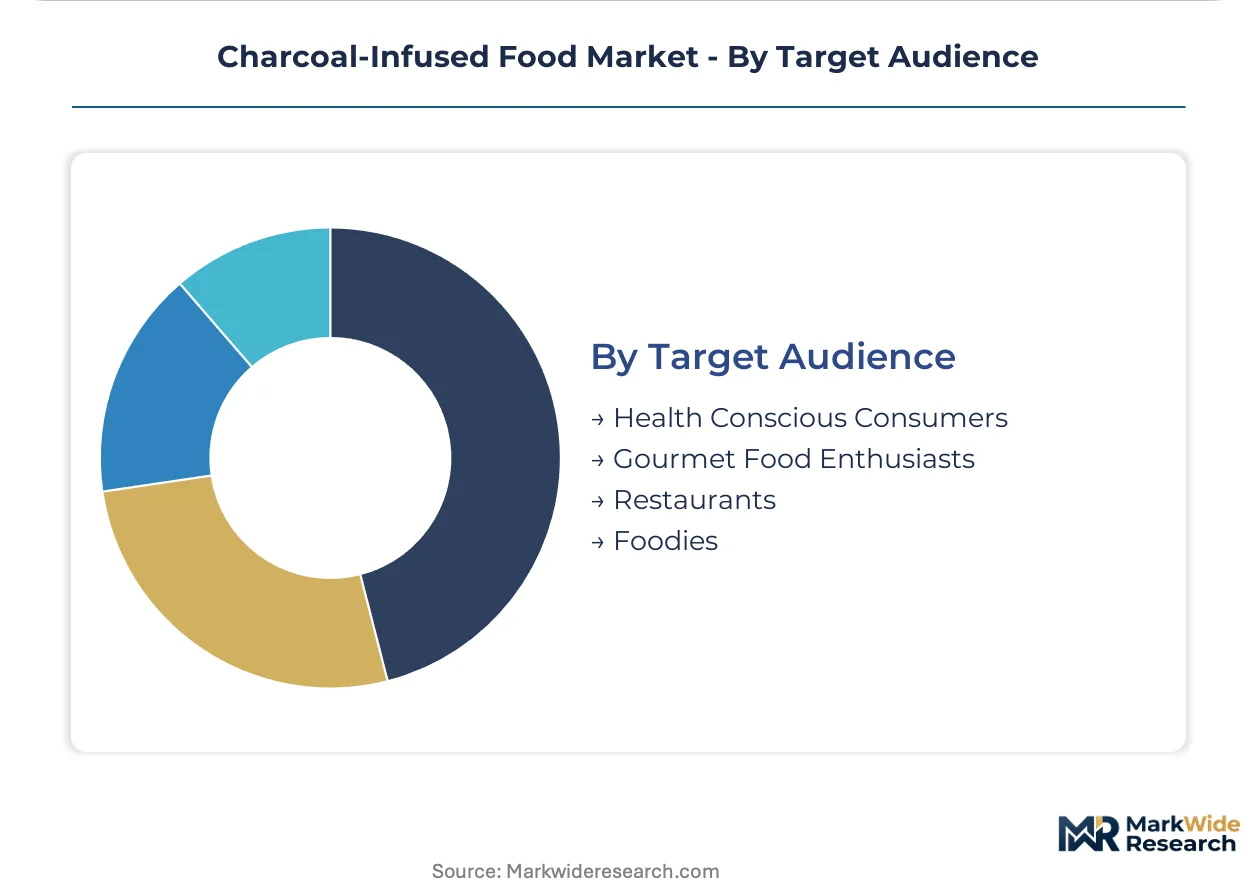
Target Audience:
Customer sophistication determines messaging architecture: health claims require regulatory caution, while aesthetic positioning faces lower compliance burden.
- Health Conscious Consumers:This segment scrutinizes detoxification claims with mounting skepticism, prompting liability-averse retailers to shift charcoal products from supplement-adjacent to gourmet ingredient sections.
- Gourmet Food Enthusiasts:Visual-first buyers prioritize plating drama and flavor layering over functional benefits.
- Restaurants:Menu developers seek theatrical differentiation for social media virality.
- Foodies:Early adopters drive trial in coastal urban markets before trends diffuse inland.
Restaurants anchor current demand; Gourmet Food Enthusiasts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty coffee roasters and boutique bakery talent clusters in Los Angeles, New York, and Miami anchor North American demand generation. European food technologists in Germany and the Netherlands drive micro-encapsulation innovation. Asian suppliers in Indonesia and the Philippines control coconut shell feedstock flows.
United States
Instagram-driven visual culture powers specialty coffee chain adoption in Los Angeles and New York. The FDA's GRAS ambiguity forces domestic manufacturers toward costly food additive petitions. Miami's boutique hotel restaurants deploy charcoal in theatrical tasting-menu progressions.
Germany
REACH authorization requirements pressure suppliers to document supply chain purity. EFSA's novel food classification creates first-mover advantages for early regulatory clarity. Berlin's independent grocery formats recategorize charcoal from supplement-adjacent to gourmet sections.
Netherlands
Sustainability-conscious consumers favor bamboo charcoal with established credentials. ECHA substance evaluation extends lead times for imported activated charcoal. Amsterdam's food service operators emphasize REACH-aligned biomass sourcing in menu narratives.
Indonesia
Coconut shell charcoal exports face weather disruption and quota fluctuation risks. The national export regulator manages feedstock allocation for activated carbon production. Sulawesi and Sumatra supply chains experience seasonal volatility affecting global input costs.
India
FSSAI maintains explicit provisions for charcoal in traditional preparations offering regulatory templates. Domestic manufacturers leverage this clarity for standardized industrial-scale products. Mumbai and Delhi specialty retailers target wellness-oriented millennials through curated subscription models.
Charcoal-Infused Food Market Vendor Landscape
The competitive structure tilts toward specialty snack and artisanal dessert specialists rather than diversified food conglomerates. Player density concentrates in urban coastal markets with visual-first food cultures. Three archetypes dominate: micro-encapsulation technology licensors, direct-to-consumer subscription brands, and theatrical food service operators. Capacity expansion and portfolio diversification represent the dominant competitive moves as firms navigate multi-jurisdiction label compliance costs.
Among North American specialists, IHALO KRUNCH INC exemplifies the specialty snack archetype through premium shelf placement strategies, while Morgenstern's occupies a position within artisanal ice cream formulation. The Loop and The Nolen represent the food service theatricality segment, anchoring competitive profiles through visual intensity and flavor layering rather than functional positioning.
| Leading Market Players |
|---|
| The Loop |
| The Nolen |
| IHALO KRUNCH INC |
| Morgenstern's |
| Ashley Sue's Baked Goods |
| The Good Sort |
| Macaroon |
| Ritzcarlton |
| Chocolate Pi |
| Others |
Supply Flow & Price Mechanics
Food service procurement mandates for REACH-aligned activated charcoal and FDA-compliant labeling are forcing manufacturers to maintain parallel formulation portfolios, elevating working capital requirements and compressing margin predictability across certification tiers.
Pricing Analysis
Ingredient-plus-service bundling dominates food service channels where theatrical plating consultation accompanies bulk charcoal supply, while unbundled commodity pricing prevails in direct-to-consumer retail. Three-tier pricing structure across premium, standard, and economy levels separates activated charcoal with 1,500 m²/g surface area from bamboo alternatives and conventional vegetable grades. Cost compression in economy tiers is intensifying because coconut shell feedstock volatility from Indonesian suppliers feeds through to spot pricing. Boutique bakeries and specialty coffee chains show lowest price sensitivity, while mass-market retailers demand volume discounts that erode supplier margins.
Supply Chain Analysis
Dual-sourcing requirements from European food service operators mandate qualification of both Southeast Asian coconut shell and East Asian bamboo charcoal suppliers, extending vendor onboarding timelines. Supply concentrates in Indonesia, the Philippines, and Japan, with raw material flows drawing from coconut shell agriculture, rapid-growth bamboo plantations, and traditional oak char operations. Single-source vulnerability runs through Sulawesi export corridors where weather disruption and quota fluctuations create input instability. Distribution runs through specialty ingredient houses in Los Angeles, New York, and Amsterdam before reaching food service operators and retail packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in charcoal-infused food rests on micro-encapsulation technology cost curves flattening and premium-tier adoption shifting from coastal urban enclaves toward inland specialty retail.
For Market Incumbents: To counter EFSA novel food classification delays fragmenting European market access, deepen backward integration into coconut shell carbonization operations in Sulawesi and Sumatra to secure feedstock priority. Accelerate FDA food additive petition expertise accumulation to convert GRAS ambiguity into competitor moats. For New Entrants and Emerging Players: Wellness-oriented millennials in secondary Indian cities represent an underserved buyer archetype with FSSAI regulatory clarity already established. Direct-to-consumer subscription boxes targeting Mumbai and Delhi households offer the most penetrable entry vector, with clean-label organic certification as the distinguishing go-to-market anchor. For Investors and Strategic Acquirers: Asymmetric upside sits with micro-encapsulation technology licensors possessing formulation stability expertise across freeze-thaw cycles and pH variations. Long-term viability over a decade-long window favors acquisition targets with multi-jurisdiction label compliance infrastructure already amortized. The signal to watch is FDA GRAS affirmation momentum as inflection indicator for domestic manufacturing capacity deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Operations | Captive coconut shell supply from Sulawesi insulates margin from Indonesian export quota volatility. |
| Micro-Encapsulation Technology Licensing | Spray-dried charcoal particles with maltodextrin coating unlock beverage applications previously constrained by sedimentation. |
| Multi-Jurisdiction Label Compliance Investment | Parallel FDA, EFSA, and FSSAI registration capability accelerates geographic portfolio expansion without reformulation delays. |
| Direct-to-Consumer Subscription Launch | Curated monthly boxes bypass conventional retail slotting fees while capturing wellness-oriented millennial lifetime value. |
| Sustainability Repositioning | Bamboo charcoal with REACH-aligned credentials commands price premiums in Amsterdam and Berlin food service channels. |
Methodological Framework
Coverage spans the United States, Germany, the Netherlands, Indonesia, and India, with primary inputs from each market combining interviews with specialty food formulators, regulatory affairs consultants at ingredient houses, category buyers at Los Angeles and New York retailers, and supply chain managers at Southeast Asian carbonization operations. Secondary validation draws from FDA GRAS notices, EFSA novel food applications, FSSAI traditional food provisions, Indonesian export regulator quota disclosures, and trade flow customs data. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to cross-validate segment sizing.
Rate-of-change decomposition across the analysis window separated volume growth from price-mix effects, with CAGRs derived from year-over-year progression analysis rather than endpoint averaging. Segmentation dimensions modeled include ingredient type, application channel, and target audience sophistication tier. Forecast inputs incorporated social media engagement velocity indices for visual food content and regulatory harmonization momentum between FDA, EFSA, and FSSAI regimes.
Underlying measurement precision varies by segment; food service channel estimates carry tighter precision than emerging home cooking applications due to disclosed procurement volumes at named restaurant groups. Forecasts reflect assumptions about EFSA novel food classification timelines and FDA GRAS petition resolution pathways. Deviation in coconut shell feedstock export quotas or REACH authorization requirements for carbon black variants would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Food Thickening Agents Market