
 Emulsion Stabilizer for Beverages Market | 2026-2036
Emulsion Stabilizer for Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsion Stabilizer for Beverages Market Analytics
Plant-derived hydrocolloids is consolidating share from synthetic stabilizers as beverage brands reformulate for label simplicity. Cargill Incorporated leverages its North American agricultural supply base to secure guar and locust bean bean feedstock. Ingredion Incorporated anchors its position through modified starch innovation for dairy-alternative beverages. Kerry Group plc competes on integrated flavor-stabilizer systems that reduce client formulation complexity.
Emulsion stabilizer for beverages denotes hydrocolloid, starch, or surfactant systems that reduce interfacial tension between immiscible liquid phases, typically achieving particle sizes below one micron for shelf-stable optical clarity. These systems prevent creaming, flocculation, and coalescence in products ranging from flavored waters to protein-fortified drinks. Natural emulsifiers command premium positioning as beverage manufacturers face consumer pressure for recognizable ingredient decks. Modified starches retain volume leadership in cost-sensitive soft drink applications where process tolerance and heat stability outweigh clean-label demands. Gums represent the fastest-expanding category in nutritional supplements, where high-protein loadings demand robust viscosity control and suspension capacity.
The FDA maintains GRAS notification requirements for novel stabilizer submissions, while the EPA oversees processing effluent standards that affect hydrocolloid extraction economics. EFSA evaluations under EU regulation shape acceptance timelines for new botanical emulsifiers seeking cross-border formulation use. Stakeholders must monitor evolving disclosure thresholds under CSRD-aligned corporate reporting, as supply chain traceability becomes inseparable from market access.
Market Dynamics
Clean-label formulation mandates from the EU Green Deal and F-Gas Regulation are compressing synthetic stabilizer demand while accelerating botanical hydrocolloid procurement across beverage manufacturing clusters.
Growth Catalysts
- EU Green Deal additive disclosure:Mandatory transparency thresholds push beverage brands toward plant-derived stabilizers with recognizable ingredient decks.
- Protein-fortified beverage expansion:Nutritional supplement manufacturers require high-viscosity gum systems to suspend heavy protein loadings without sedimentation.
- Hamburg-Munich formulation clustering:Germany's beverage R&D concentration creates specialized ingredient demand that pulls advanced emulsion systems through regional supply chains.
Market Restraints
- Guar gum price volatility:Weather-dependent Indian harvests create input cost instability that compresses margin predictability for hydrocolloid-dependent formulators.
- GRAS notification timelines:FDA review cycles for novel botanical emulsifiers extend market entry lead times beyond typical product development windows.
- Modified starch substitution ceiling:Cost-sensitive soft drink applications resist premium natural alternatives despite clean-label pressure, locking volume in legacy systems.
Strategic Opportunities
- Dairy-alternative beverage white space:Oat and pea protein drink manufacturers seek integrated stabilizer-emulsifier systems that deliver mouthfeel parity with conventional dairy.
- CSRD-aligned traceability premiums:Supply chain disclosure mandates create pricing power for stabilizer suppliers with verified agricultural sourcing documentation.
- Functional water expansion:Vitamin and mineral fortification in clear beverages demands sub-micron emulsion stability without turbidity or ringing.
Industry Challenges
- EFSA novel food evaluation timelines:Cross-border acceptance delays for new botanical emulsifiers fragment formulation standardization across EU member states.
- Extraction effluent compliance:EPA processing discharge standards raise capital requirements for hydrocolloid purification infrastructure.
- Flavor-stabilizer integration complexity:Beverage manufacturers struggle to reconcile clean-label stabilizer performance with existing flavor system compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsion Stabilizer for Beverages Market |
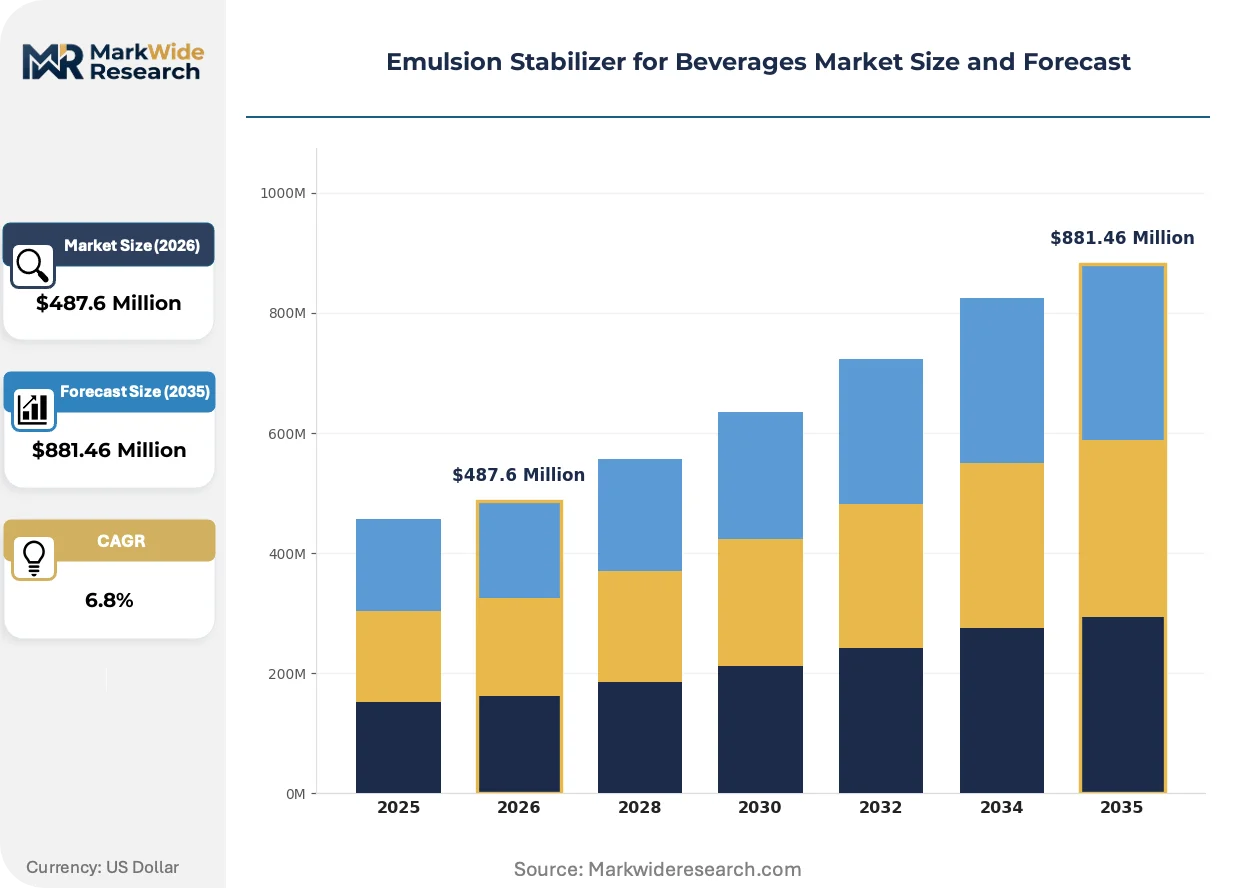
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Emulsifiers, Synthetic Emulsifiers, Modified Starches, Gums Application: Dairy Products, Alcoholic Beverages, Soft Drinks, Nutritional Supplements End User: Beverage Manufacturers, Food Industry, Retail Outlets, Online Stores Distribution Channel: Direct Sales, Wholesalers, E-commerce, Specialty Stores |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Kerry Group plc, Archer Daniels Midland Company, CP Kelco, DuPont de Nemours, DSM-Firmenich, Palsgaard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsion Stabilizer for Beverages Market Evolving Landscape
Formulation science is pivoting from single-function hydrocolloids toward multifunctional systems that simultaneously deliver stability, texture, and label simplicity.
Enzymatically modified starches is overtaking conventional chemical modifications in premium beverage applications. These biocatalytic processes produce clean-label texturants that beverage brands position as "natural" without sacrificing process tolerance. Mid-tier functional drink manufacturers in Germany and France are adopting enzymatic starches at accelerating rates, compressing demand for legacy modified starches in the premium tier.
REACH substance restriction expansions are forcing reformulation cycles across European beverage manufacturing. The regulation's evolving candidate list now captures several legacy emulsifier chemistries previously grandfathered into widespread use. Dairy-alternative producers face the steepest compliance burden, as many established oat milk formulations rely on surfactants now under regulatory scrutiny.
Direct supplier relationships are displacing distributor-mediated ingredient procurement among large beverage manufacturers. Volume buyers now contract directly with Cargill and Ingredion agricultural networks to secure guar and locust bean bean supply visibility. This channel shift concentrates in North American and German markets where procurement functions have built sufficient technical capability to evaluate stabilizer performance specifications internally.
Emulsion Stabilizer for Beverages Market Segmentation
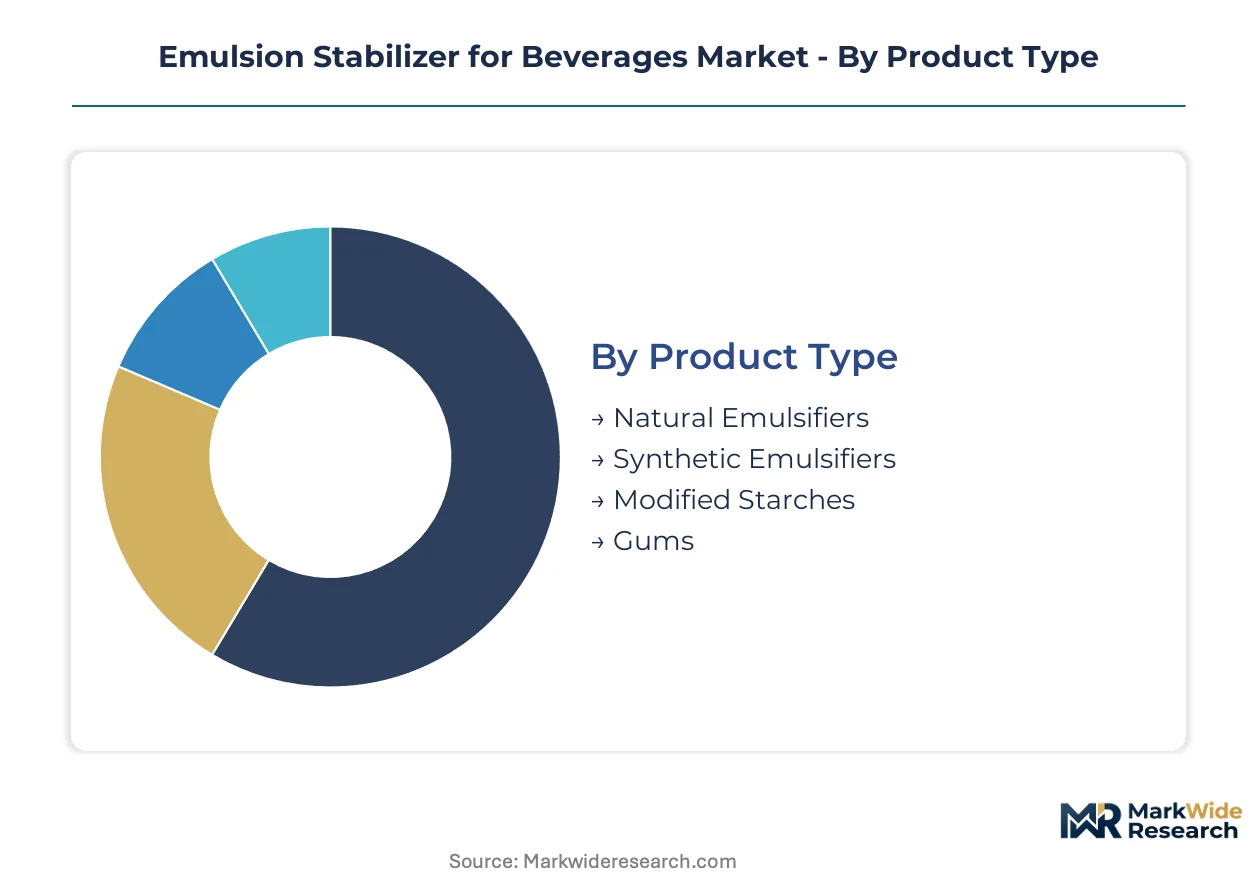
Beverage formulators select stabilizers through a hierarchy of performance thresholds, label requirements, and process economics that vary sharply across product categories. Procurement decisions in this market hinge on protein load tolerance, heat stability, and clean-label positioning rather than price alone.
Product Type:
Cost tier determines adoption velocity, with premium natural systems commanding formulation slots in functional beverages while legacy synthetics retain volume in mass-market soft drinks.
- Natural Emulsifiers:Plant-derived hydrocolloids including guar, locust bean, and acacia gums deliver sub-micron particle stability without synthetic chemical modification. Protein-fortified beverage manufacturers in Germany specify these systems to meet EU Green Deal disclosure mandates while maintaining suspension capacity for heavy nutritional loadings.
- Gums:High-viscosity botanical extracts enable robust emulsion stability in nutritional supplements where sedimentation resistance outweighs unit cost sensitivity. Hamburg and Munich formulation clusters source specialized gum blends for oat and pea protein drinks seeking dairy-comparable mouthfeel.
- Modified Starches:Cost-optimized texturants dominate soft drink applications where heat stability and process tolerance exceed clean-label priorities.
- Synthetic Emulsifiers:Legacy surfactant systems face contracting demand under REACH substance restrictions and F-Gas Regulation transparency requirements.
Modified starches lead on scale; gums lead on momentum.
Application:
Protein fortification intensity separates segments, with high-load nutritional products demanding specialized viscosity control that clear beverages and alcohol can bypass.
- Nutritional Supplements:Vitamin and mineral fortification in protein-dense formats requires gum-based stabilizers to prevent creaming and ringing through extended shelf life. German functional beverage producers specify these systems for meal replacement and sports nutrition lines subject to EFSA novel food evaluations.
- Dairy Products:Conventional milk and cream applications utilize modified starches for cost-efficient fat stabilization, though enzymatically processed alternatives are gaining share in premium tiers.
- Soft Drinks:Flavored waters and carbonated beverages prioritize optical clarity and heat stability over label simplicity, locking volume in legacy starch systems.
- Alcoholic Beverages:Spirit and ready-to-drink cocktail formulations demand alcohol-tolerant emulsifiers with flavor compatibility and freeze-thaw resistance.
Soft drinks dominate volume throughput; nutritional supplements are climbing the fastest.
End User:
Technical capability gaps separate direct procurement from distributor-mediated purchasing, with large manufacturers internalizing stabilizer specification while smaller players rely on external formulation support.
- Beverage Manufacturers:Volume buyers with in-house R&D functions contract directly with agricultural suppliers for guar and locust bean feedstock visibility, particularly in North American and German markets.
- Food Industry:Cross-category ingredient purchasers seek multi-functional stabilizers compatible with both beverage and solid food applications.
- Retail Outlets:Private-label beverage programs depend on co-manufacturer stabilizer selections with limited direct procurement influence.
- Online Stores:Direct-to-consumer functional drink brands prioritize label-friendly stabilizers for premium positioning in digital channels.
Beverage manufacturers anchor procurement scale; online stores are expanding most quickly.
Distribution Channel:
Supply chain configuration determines pricing power and technical service access, with direct relationships concentrating among buyers capable of internal performance validation.
- Direct Sales:Large beverage manufacturers bypass distributors to secure volume commitments and agricultural traceability documentation required under CSRD-aligned corporate reporting.
- E-commerce:Digital procurement platforms enable mid-tier functional drink producers to access specialized stabilizer blends without minimum order constraints.
- Wholesalers:Regional distributors serve smaller beverage manufacturers lacking technical capability to evaluate stabilizer specifications independently.
- Specialty Stores:Ingredient boutiques cater to craft beverage producers seeking novel botanical emulsifiers with premium positioning potential.
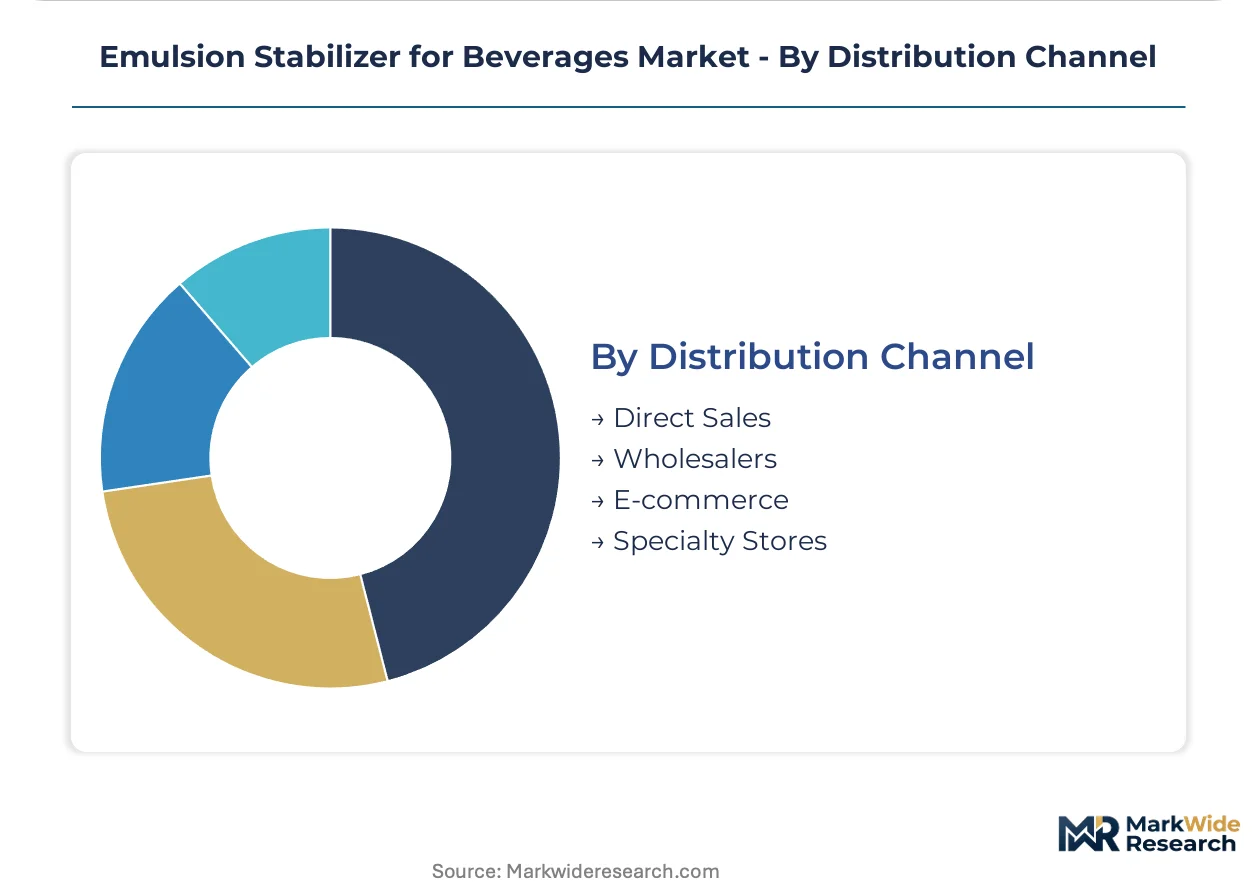
Direct sales command the largest transaction values; e-commerce channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg-Munich beverage formulation clusters anchor European demand for advanced emulsion stabilizers. Procurement patterns concentrate in Germany's technical ingredient corridors. Regulatory pressure from Brussels reshapes sourcing decisions across multiple jurisdictions.
Germany
Meal replacement and sports nutrition manufacturers specify high-viscosity gum systems for protein suspension. EFSA novel food evaluations under EU regulation shape acceptance timelines for botanical emulsifiers. Hamburg and Munich R&D clusters pull specialized stabilizer blends through regional supply chains for oat and pea protein applications.
United States
Volume buyers internalize stabilizer procurement through direct agricultural supplier contracts. FDA GRAS notification requirements extend market entry lead times for novel hydrocolloids. North American beverage manufacturers leverage Cargill's agricultural network for guar and locust bean feedstock visibility.
France
Premium functional water producers adopt enzymatically modified starches for clean-label positioning. REACH substance restrictions force reformulation cycles away from legacy surfactant chemistries. Paris and Lyon formulation centers drive demand for integrated flavor-stabilizer systems.
India
Weather-dependent guar gum harvests create input cost volatility for hydrocolloid-dependent formulators. FSSAI additive disclosure standards align with tightening international transparency mandates. Gujarat processing clusters face capital requirements from EPA-modeled effluent discharge standards for extraction infrastructure.
United Kingdom
Dairy-alternative beverage startups seek mouthfeel parity with conventional milk through specialized emulsifier blends. CSRD-aligned corporate reporting creates pricing power for suppliers with verified agricultural sourcing documentation. London functional drink manufacturers contract directly with ingredient networks for supply chain traceability.
Emulsion Stabilizer for Beverages Market Competitive Landscape
Global majors compete with regional champions across agricultural sourcing and formulation integration capabilities. The supplier base organizes around three strategic tiers: agricultural processors with captive feedstock, specialized hydrocolloid refiners, and integrated flavor-stabilizer system providers. Consolidation pressure concentrates among mid-tier players lacking vertical supply control. Dominant competitive moves include backward integration into agricultural networks and technology licensing for enzymatic modification processes.
Within the agricultural-processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven sourcing archetypes with North American supply base control. Ingredion Incorporated occupies a position bridging modified starch innovation with dairy-alternative beverage applications. Kerry Group plc anchors the integrated-systems vector through combined flavor and stabilizer offerings that reduce client formulation complexity.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Kerry Group plc |
| Archer Daniels Midland Company |
| CP Kelco |
| DuPont de Nemours |
| DSM-Firmenich |
| Palsgaard |
| Others |
Value Network & Pricing Analysis
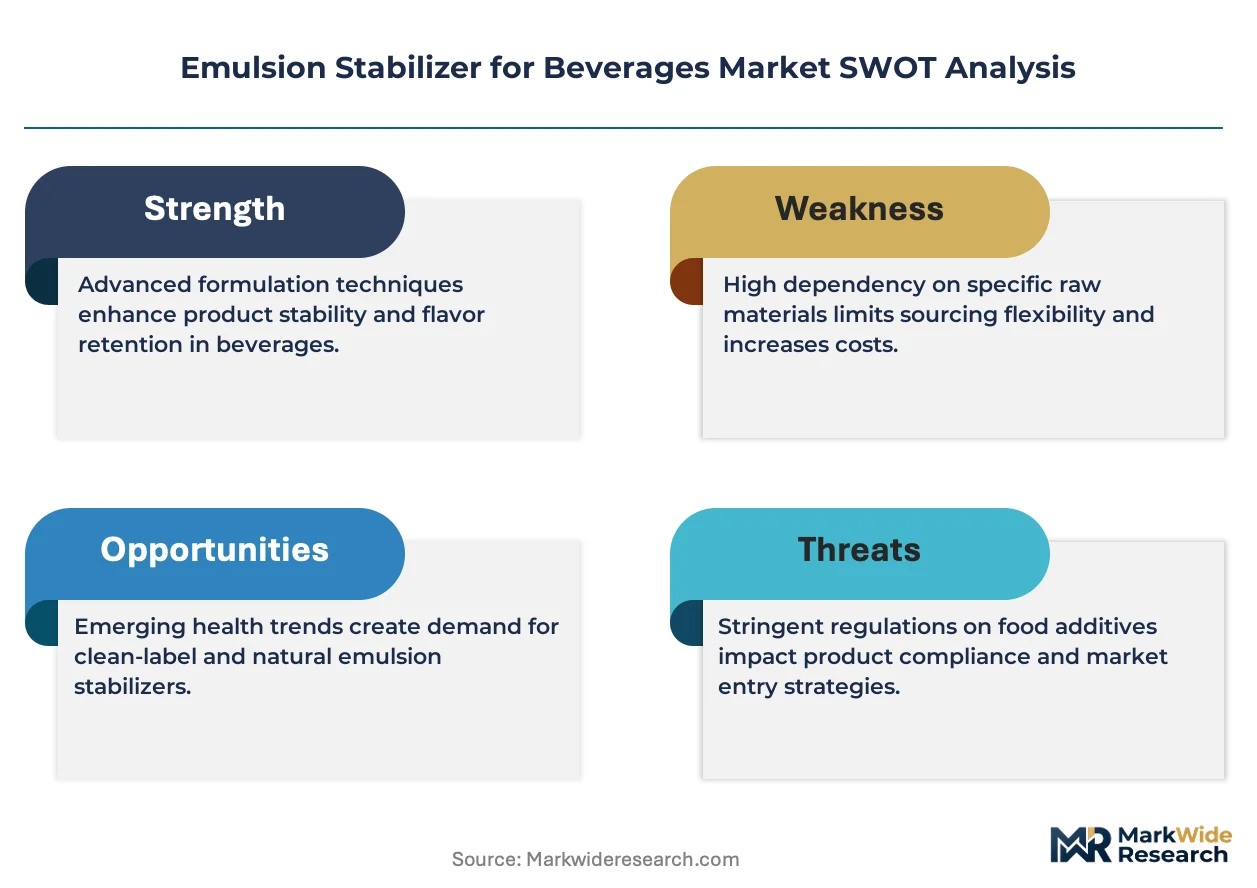
Clean-label certification divergence between enzymatically modified starches and legacy chemically modified alternatives manifests in both margin capture and agricultural sourcing configurations, with premium-tier buyers paying traceability premiums while commodity soft drink manufacturers lock in long-term modified starch contracts.
Pricing Analysis
Input-cost pass-through from weather-dependent Indian guar harvests destabilizes hydrocolloid pricing predictability for beverage formulators. Three-tier pricing structure across premium natural emulsifiers, mid-grade enzymatic starches, and economy modified starches anchors the market, with EU Green Deal disclosure mandates widening spreads between certified botanical and synthetic alternatives. Cost compression in premium natural tiers is intensifying as Hamburg-Munich formulation clusters consolidate procurement volumes. Mid-tier functional drink manufacturers exhibit highest price sensitivity, while protein-fortified nutritional supplement producers prioritize suspension performance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from large beverage manufacturers mandate qualified supply from both Indian guar processing clusters and North American locust bean extraction facilities. Geographic supply concentration centers on India, the United States, and Germany for hydrocolloid refinement and formulation integration. Raw material dependencies rest on monsoon-sensitive guar bean harvests, enzymatic processing biocatalysts, and modified starch feedstock corn. Single-source vulnerability from Gujarat processing concentration creates disruption exposure. Distribution runs through direct agricultural contracts for volume buyers and specialty ingredient distributors for craft beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on enzymatic processing cost curves flattening as biocatalyst efficiency improves, enabling premium-tier positioning without the agricultural volatility of botanical hydrocolloids.
For Market Incumbents: Deepen backward integration into North American locust bean agricultural networks to secure supply visibility against Indian guar price volatility. Expand enzymatic modification capacity in German technical corridors to capture clean-label demand from Hamburg-Munich formulation clusters before REACH restrictions accelerate synthetic emulsifier phase-out. For New Entrants and Emerging Players: E-commerce procurement platforms offer the lowest barrier to mid-tier functional drink manufacturers seeking specialized stabilizer blends without volume commitments. Target dairy-alternative beverage white space in France and the United Kingdom where mouthfeel parity demands create formulation service opportunities. Lead with integrated flavor-stabilizer technical support to differentiate from commodity hydrocolloid suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier stabilizer refiners lack captive agricultural supply or enzymatic modification technology licensing. Long-term viability favors suppliers with verified CSRD-aligned traceability documentation and direct relationships with German beverage R&D clusters. Watch EFSA novel food evaluation timelines as the inflection signal for botanical emulsifier market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Capacity Expansion | Captures clean-label positioning under REACH substance restriction timelines. |
| Direct Agricultural Supply Contracts | Secures guar and locust bean feedstock visibility for CSRD-aligned corporate reporting. |
| Integrated Flavor-Stabilizer System Development | Reduces client formulation complexity for dairy-alternative beverage manufacturers. |
| Novel Botanical Emulsifier GRAS Submission | Accelerates FDA market entry timelines for protein-fortified applications. |
| Regional Formulation Technical Centers | Anchors customer relationships in Hamburg-Munich beverage R&D clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with beverage formulation directors, hydrocolloid procurement leads, enzymatic processing R&D heads, and regulatory affairs specialists at EFSA-aligned consultancies with secondary validation from FDA GRAS notification databases, EFSA novel food evaluation registers, EU customs trade data, and SEC filings from agricultural processors. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Segment-weighting approaches modeled emulsion stabilizer demand across product type tiers, application intensity levels, and end-user procurement capabilities, with additional dimensioning by regional regulatory cluster alignment. CAGRs were derived from growth driver elasticity modeling applied to baseline procurement volumes. Forecast inputs incorporated enzymatic starch adoption curves and protein-fortified beverage expansion rates without year-specific anchoring.
The model assumes a particular technology adoption path; alternative pathways for biocatalytic modification scale-up would alter the outlook. Forecasts reflect assumptions around REACH enforcement intensity and F-Gas Regulation disclosure threshold evolution. Deviation in Indian monsoon patterns or EFSA evaluation acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Water Enhancer Market