
 Asia-Pacific Food Stabilizers Market | 2026-2036
Asia-Pacific Food Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Stabilizers Market Outlook
Plant-based dairy alternatives is repositioning demand profiles across the Asia-Pacific food stabilizers landscape. Cargill Incorporated leverages its regional supply chain footprint to serve Indonesian and Thai beverage formulators. Kerry Group plc anchors its position through specialized texture systems for ambient yogurt drinks. Palsgaard A/S competes on emulsifier technology leadership in palm oil reduction applications.
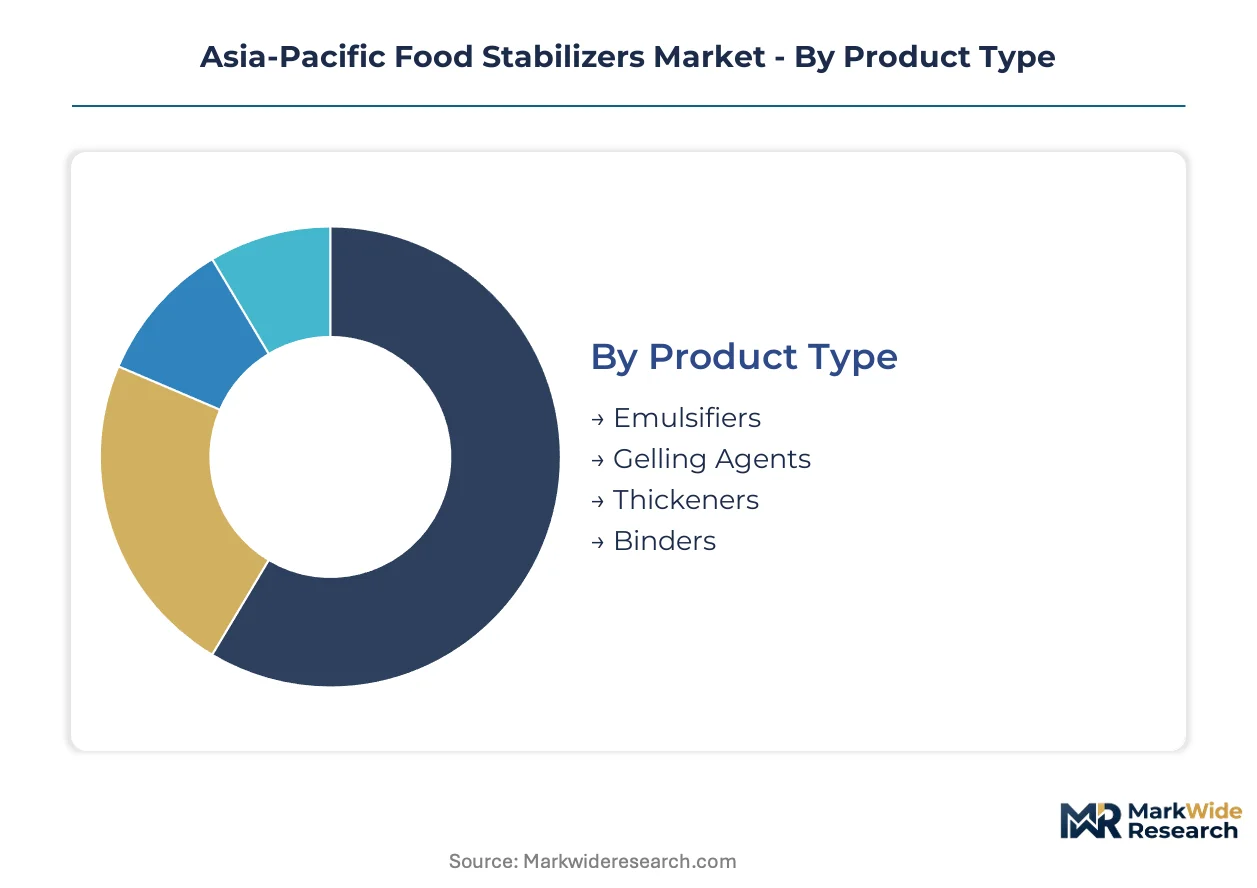
Food stabilizers encompass hydrocolloids, proteins, and emulsifiers that control water mobility, prevent syneresis, and maintain rheological consistency in processed foods. Manufacturers typically deploy carrageenan, pectin, or modified starch at concentrations between 0.1% and 2.0% by weight to achieve target viscosity and shelf stability. Thickeners command the largest product type share due to their ubiquity in sauces and dairy applications, while gelling agents expand fastest in confectionery and plant-based desserts where texture replication poses formulation challenges. Binders gain traction in meat analog applications as Asian food manufacturers respond to flexitarian dietary shifts.
FSSAI in India enforces additive maximum usage levels and mandatory declaration thresholds that directly influence stabilizer selection and dosage rates. Japan's MHLW and South Korea's MFDS maintain positive-list systems for food additives that create compliance barriers for novel hydrocolloid entrants. Australia's FSANZ coordinates with Codex Alimentarius standards to align regional trade requirements. Stakeholders must monitor evolving clean-label definitions across these jurisdictions to anticipate reformulation cycles and certification investments.
Market Dynamics
Clean-label reformulation mandates across Southeast Asia are forcing dairy and beverage manufacturers to replace synthetic stabilizers with hydrocolloid alternatives, compressing formulation cycles and tightening supplier qualification timelines.
Growth Catalysts
- Indonesia's processed dairy expansion:Domestic yogurt and flavored milk production capacity additions are pulling carrageenan and pectin volumes. Local beverage formulators prioritize texture consistency in ambient distribution conditions.
- FSSAI labeling mandates:India's tightened additive declaration thresholds push manufacturers toward single-ingredient stabilizers with recognizable names. Reformulation activity concentrates in sauces and ready-to-eat meals.
- Enzymatic modification:Novel processing techniques reduce hydrocolloid dosage requirements while maintaining viscosity targets. Thai and Vietnamese manufacturers adopt these systems to manage input costs.
Market Restraints
- Seaweed supply volatility:Carrageenan feedstock availability fluctuates with Philippine and Indonesian harvest cycles. Price instability propagates through dairy formulation supply chains.
- Positive-list barriers:Japan's MHLW and South Korea's MFDS additive approval systems delay novel hydrocolloid market entry. Registration timelines extend 18-36 months for new entrants.
- Clean-label cost premiums:Natural stabilizer alternatives command 15-40% price spreads over synthetic equivalents. Budget dairy processors in emerging markets face margin compression.
Strategic Opportunities
- Vietnam's underpenetrated beverage sector:Plant-based milk alternatives remain nascent. Early stabilizer positioning captures formulation partnerships with domestic soy and oat milk launches.
- MFDS fast-track pathways:South Korea's streamlined review for clean-label ingredients accelerates pectin and gellan gum approvals. Timeline advantages attract regional R&D investment.
- Direct-to-manufacturer channels:Bypassing traditional distributor networks reduces technical service lag. Australian and New Zealand ingredient suppliers pilot this model in Southeast Asia.
Industry Challenges
- Formulation chemist scarcity:Hydrocolloid synergy optimization requires specialized expertise. Southeast Asian technical talent pools lag demand from expanding dairy portfolios.
- Dual certification burdens:Exporters to Australia and Japan must satisfy both FSANZ and MHLW requirements simultaneously. Documentation and testing costs accumulate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Stabilizers Market |
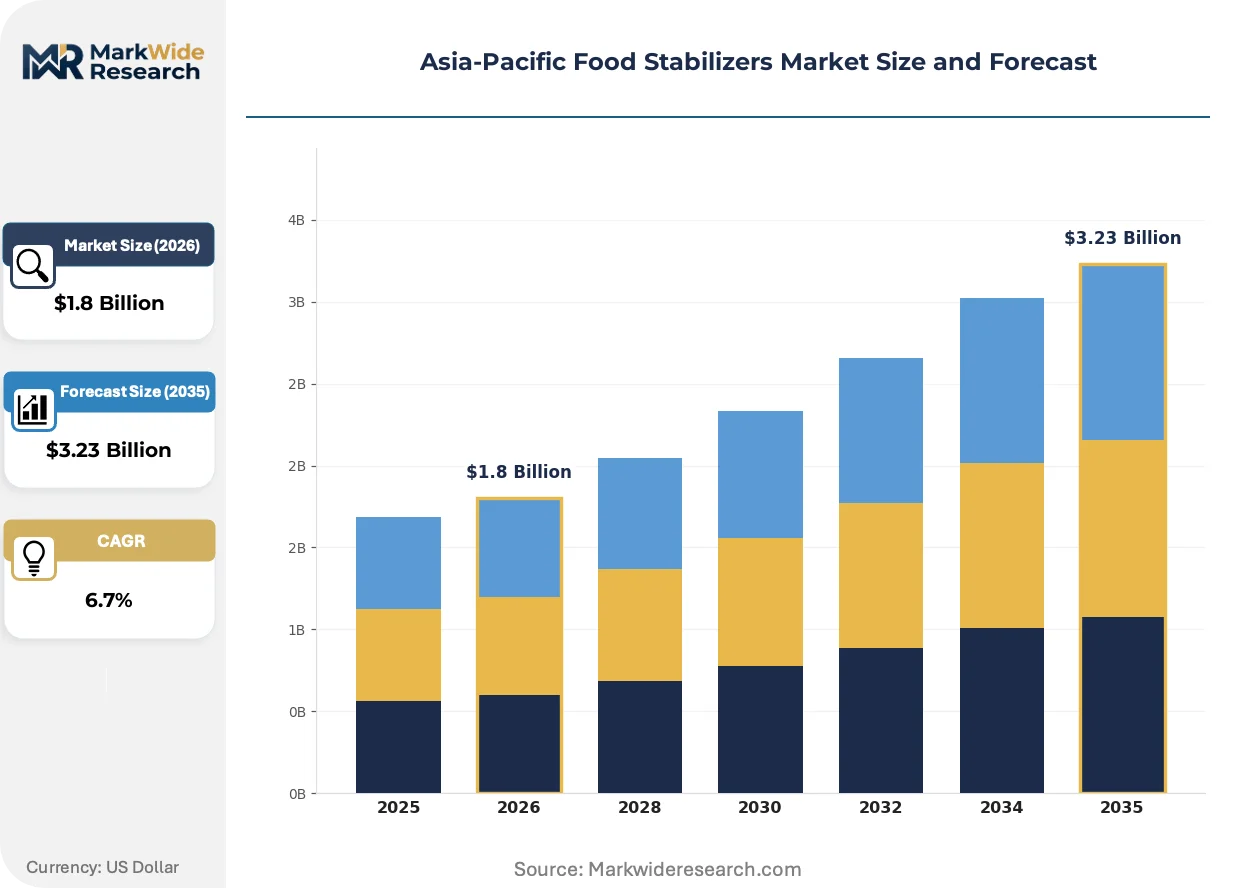
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Gelling Agents, Thickeners, Binders Application: Dairy Products, Confectionery, Bakery, Sauces End User: Food Manufacturers, Restaurants, Retailers, Food Service Providers Distribution Channel: Online Stores, Hypermarkets, Supermarkets, Specialty Stores |
| Companies Covered | Archer Daniels Midland Company, Palsgaard A/S, Cargill Incorporated, CP Kelco, Ashland Global Holdings Inc, Ingredion Incorporated, DuPont de Nemours Inc, Kerry Group plc, Tate & Lyle PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Stabilizers Market Strategic Shifts
Biotechnology-derived stabilizers and precision fermentation processes are reconfiguring raw material sourcing strategies. Manufacturers now face technology selection decisions that lock in supply chain architectures for decade-long horizons.
Fermentation-produced hydrocolloids is expanding into traditional seaweed-dependent applications. Startups and established suppliers in Singapore and South Korea are scaling xanthan and gellan gum alternatives through microbial platforms. Dairy formulators in Thailand are piloting these materials at commercial volumes, reducing exposure to marine harvest variability while meeting clean-label declarations.
FSANZ alignment with Codex Alimentarius standards is streamlining cross-border additive approvals. Australian regulators coordinate ingredient safety assessments with New Zealand and ASEAN counterparts, reducing redundant testing burdens. Indonesian and Malaysian exporters gain accelerated market access for modified starch and cellulose derivatives into Australian processed food channels.
Ingredient specification consolidation is compressing supplier bases. Large dairy and beverage manufacturers in India and Indonesia are reducing approved vendor lists from 15-20 to 5-8 core partners. Technical service integration and volume pricing leverage drive this behavior, favoring stabilizer suppliers with regional manufacturing footprints over pure trading operations.
Asia-Pacific Food Stabilizers Market Segmentation
Food stabilizer procurement patterns diverge sharply across buyer categories in Asia-Pacific. Technical specifications, regulatory compliance burdens, and supply chain reliability requirements create distinct purchasing behaviors that suppliers must address through tailored positioning.
Product Type:
Formulation chemists select stabilizer classes based on target viscosity, thermal stability, and clean-label compatibility requirements.
- Thickeners:Hydrocolloid systems including modified starch, xanthan gum, and cellulose derivatives build viscosity in sauces and ambient dairy beverages. Indonesian yogurt manufacturers prioritize these for shelf-stable texture under tropical distribution conditions.
- Emulsifiers:Lecithin, mono- and diglycerides, and polyglycerol esters maintain fat-water dispersion stability. Thai and Vietnamese plant-based milk formulators drive demand for palm oil reduction-compatible systems.
- Gelling Agents:Carrageenan, pectin, and gellan gum create structured textures in desserts and confectionery.
- Binders:Protein isolates and modified starches hold moisture and maintain integrity in processed meat and meat analog applications.
Thickeners lead volumes today; gelling agents are gaining share fastest.
Application:
End-use sectors impose distinct performance thresholds around thermal processing, acid stability, and shelf-life extension.
- Dairy Products:Flavored milk, yogurt, and ice cream applications demand acid-stable hydrocolloids that prevent protein aggregation and syneresis. India's FSSAI labeling mandates push manufacturers toward pectin and carrageenan with recognizable ingredient declarations.
- Sauces:Ketchup, dressings, and cooking sauces require shear-thinning rheology for pourability and cling. Japanese manufacturers specify low-particle modified starches for transparent finished products.
- Confectionery:Gummies, jellies, and aerated candies utilize gelling agents for texture control and sugar replacement compatibility.
- Bakery:Bread, cakes, and pastries incorporate stabilizers for crumb softness and moisture retention during distribution.
Dairy applications anchor current demand; sauce reformulation shows the steepest expansion trajectory.
End User:
Scale and technical capability determine whether buyers source commodity hydrocolloids or invest in customized texture systems.
- Food Manufacturers:Large-scale processors operate direct supplier relationships with technical service integration. Indonesian dairy multinationals qualify vendors through 12-18 month validation protocols.
- Food Service Providers:Industrial kitchens and catering operations prioritize cost-optimized stabilizer blends with simplified handling requirements.
- Restaurants:Chain operators specify stabilizers for consistency across outlet networks, particularly in beverage and dessert applications.
- Retailers:Private-label food producers source through distributor channels with limited technical support.
Food manufacturers command the largest procurement volumes; food service providers are expanding purchases most rapidly.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic coverage needs.
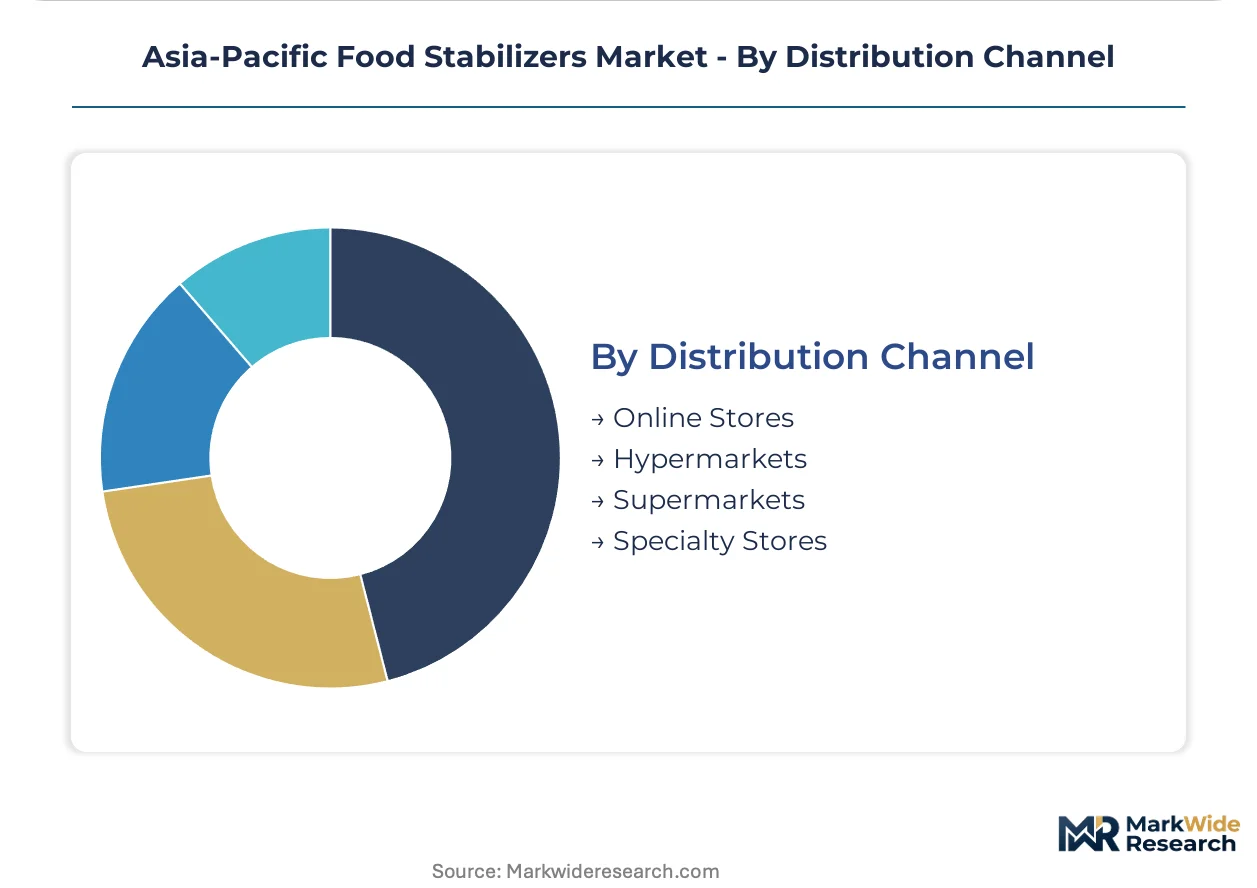
- Specialty Stores:Ingredient distributors serving small-to-mid manufacturers offer technical consultation and custom blending. Australian and New Zealand suppliers pilot direct-to-manufacturer models here.
- Supermarkets:Mass-market retail channels supply standard-grade hydrocolloids to household and small commercial buyers.
- Hypermarkets:Large-format retailers aggregate volume purchasing for regional food processors.
- Online Stores:Digital procurement platforms serve remote buyers and specialty ingredient seekers with limited local distributor access.
Specialty stores dominate professional-grade transactions; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints across Asia-Pacific as manufacturers relocate formulation activities to jurisdictions with streamlined additive approval pathways. Cost-of-compliance gaps between national regulators create migration incentives for stabilizer-dependent dairy and beverage processors.
Indonesia
Domestic yogurt and flavored milk capacity expansions are accelerating carrageenan and pectin procurement from local distributors. The country's national food safety agency maintains additive positive lists that align with Codex Alimentarius standards, reducing dual-certification burdens for exporters. Jakarta and Surabaya industrial zones host the largest concentration of beverage formulators prioritizing ambient-stable texture systems.
India
FSSAI tightened additive labeling thresholds are pushing sauce and ready-to-eat meal manufacturers toward single-ingredient hydrocolloids with consumer-recognizable names. The regulator's maximum usage level enforcement directly influences stabilizer dosage rates in processed dairy applications. Maharashtra and Gujarat dairy clusters are driving pectin reformulation activity as multinationals adapt portfolios to comply with declaration mandates.
Thailand
Enzymatic modification technologies are reducing hydrocolloid input costs for beverage manufacturers seeking viscosity optimization at lower dosage rates. The country's national food and drug administration maintains streamlined approval pathways for novel processing aids. Bangkok-based dairy processors are piloting fermentation-derived stabilizers at commercial scale to hedge against seaweed supply volatility.
South Korea
MFDS fast-track review pathways for clean-label ingredients are attracting regional R&D investment in pectin and gellan gum applications. The regulator's streamlined additive approval system offers timeline advantages over neighboring jurisdictions. Seoul-Incheon biotech corridors host startups scaling microbial fermentation platforms for xanthan gum alternatives.
Australia
FSANZ alignment with Codex Alimentarius standards is accelerating Indonesian and Malaysian modified starch exports into Australian processed food channels. The regulator's coordination with New Zealand and ASEAN counterparts reduces redundant safety testing burdens. Sydney and Melbourne food manufacturing hubs are consolidating approved vendor lists from 15-20 to 5-8 core stabilizer suppliers.
Asia-Pacific Food Stabilizers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding dairy sector procurement while regional blenders serve mid-tier sauce formulators. Market structure tilts toward consolidation at the top tier, where technical service integration and volume pricing leverage favor suppliers with captive manufacturing footprints. Three archetypes dominate: fermentation-technology pioneers, seaweed-dependent heritage processors, and enzymatic-modification specialists. Competitive dynamics center on backward integration into raw material sourcing and direct-to-manufacturer channel development bypassing traditional distributor networks.
Within the multinational tier, Cargill Incorporated and Kerry Group plc exemplify divergent strategic positions. Cargill leverages its regional supply chain footprint to anchor relationships with Indonesian and Thai beverage formulators requiring ambient distribution stability. Kerry Group plc occupies a position emphasizing specialized texture systems for ambient yogurt drinks. Palsgaard A/S represents the emulsifier-technology archetype competing on palm oil reduction applications. These three companies collectively illustrate how technical service depth and geographic manufacturing presence determine vendor qualification success in Southeast Asia's expanding dairy portfolios.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Palsgaard A/S |
| Cargill Incorporated |
| CP Kelco |
| Ashland Global Holdings Inc |
| Ingredion Incorporated |
| DuPont de Nemours Inc |
| Kerry Group plc |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Formulation chemist scarcity in Southeast Asian technical talent pools widens labor-cost differentials between regional hubs, compressing pricing-tier spreads as Jakarta and Bangkok processors absorb premium wages for hydrocolloid synergy expertise while Vietnamese entrants exploit lower technical-service overhead.
Pricing Analysis
Distributor margin layers in Indonesian and Thai stabilizer markets typically capture 12-18 percentage points between manufacturer gate and food-processor dock, though direct-to-manufacturer channels piloted by Australian and New Zealand suppliers are compressing these spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with FSSAI-compliant single-ingredient hydrocolloids commanding top-tier positioning. Pricing pressure stems from clean-label cost premiums propagating through dairy formulation supply chains as budget processors face margin compression. Small-scale sauce manufacturers in emerging markets exhibit highest price sensitivity, while multinational yogurt producers prioritize technical service integration over unit economics.
Supply Chain Analysis
Freight cost volatility across the Strait of Malacca and South China Sea shipping lanes propagates through carrageenan and pectin procurement networks, with Jakarta-Surabaya industrial zones and Bangkok-based dairy processors bearing disproportionate exposure to container rate fluctuations. Raw material sourcing draws from Philippine and Indonesian seaweed harvests, Thai tapioca starch feedstocks, and Australian wheat-derived modified starches. Single-source vulnerability concentrates in carrageenan feedstock availability tied to marine harvest cycles. Distribution runs through specialty ingredient distributors serving qualified vendor lists, though direct-to-manufacturer pilots are fragmenting traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific food stabilizers market functions as a stable compounder anchored by irreversible clean-label reformulation mandates across Southeast Asian dairy and beverage portfolios, with regulatory tightening in India and Indonesia ensuring sustained replacement demand for synthetic-to-natural stabilizer transitions.
For Market Incumbents: Hedge against seaweed supply volatility through fermentation-technology partnerships or captive sourcing agreements with Philippine and Indonesian harvest cooperatives. Prioritize backward integration into enzymatic modification capabilities to defend margin position as Thai and Vietnamese manufacturers adopt dosage-reduction processing systems. Lock in technical service integration with consolidating dairy multinationals reducing approved vendor lists from 15-20 to 5-8 core partners.
For New Entrants and Emerging Players: Fermentation-derived hydrocolloid platforms offer a technology-first wedge into Vietnam's underpenetrated plant-based milk sector, where soy and oat milk launches lack established stabilizer partnerships. Target South Korea's MFDS fast-track pathway for clean-label ingredient approvals to accelerate market entry timelines relative to Japan's MHLW positive-list barriers. Pursue direct-to-manufacturer channel development bypassing traditional distributor networks to capture technical service premiums.
For Investors and Strategic Acquirers: Regional dairy multinationals are the most active acquirer in this space, seeking texture-system capabilities to internalize formulation expertise. Five-to-ten year viability rests on regulatory arbitrage opportunities as manufacturers relocate to jurisdictions with streamlined additive approval pathways. Monitor MFDS and FSANZ alignment initiatives as inflection indicators for cross-border certification cost compression and accelerated regional trade integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Technology Adoption | Thai beverage manufacturers reduce hydrocolloid dosage requirements while maintaining viscosity targets under tropical distribution conditions. |
| Fermentation Platform Scale-Up | Singapore and South Korean startups displace seaweed-dependent supply chains through microbial xanthan and gellan gum alternatives. |
| Direct-to-Manufacturer Channel Development | Australian and New Zealand suppliers bypass traditional distributor networks to compress technical service lag in Southeast Asian markets. |
| MFDS Fast-Track Regulatory Investment | Clean-label ingredient developers exploit South Korea's streamlined review timelines versus Japan's 18-36 month positive-list barriers. |
| Technical Service Integration Consolidation | Stabilizer suppliers with regional manufacturing footprints capture volume pricing leverage as Indonesian dairy multinationals reduce approved vendor lists. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation chemists at Indonesian and Thai dairy processors, procurement leads at Indian sauce manufacturers, regulatory affairs specialists navigating FSSAI and MFDS frameworks, and distribution channel partners across Australian specialty ingredient networks. Secondary validation drew from FSSAI additive usage directives, MFDS and MHLW positive-list publications, Codex Alimentarius standards documentation, and ASEAN trade harmonization records. Bottom-up volume estimates from individual application segments triangulated against top-down market sizing from regional production capacity assessments.
Comparable-period anchoring aligned the projection horizon against historical stabilizer consumption patterns through the clean-label transition cycle, with segmentation modeling across product type, application, end-user scale, and distribution channel dimensions. CAGRs derived from regression analysis of regulatory enforcement intensity, dairy capacity expansion timelines, and enzymatic modification adoption curves. Industry-specific inputs incorporated seaweed harvest variability indices and fermentation-platform commercialization trajectories from Singapore and South Korean biotech corridors.
The model holds under sustained regulatory tightening trajectories and stable marine harvest conditions; deviation in Philippine seaweed supply shocks or MFDS approval timeline extensions would shift volume and value trajectories. Forecasts reflect assumptions around clean-label definition convergence across FSSAI, FSANZ, and ASEAN harmonization initiatives. Stakeholders should weight assumptions against their own operating context and supply chain exposure to carrageenan feedstock volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market