
 Flour Improvers Market | 2026-2036
Flour Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Flour Improvers Market Foresight
Enzyme formulation expertise is unwinding supply constraints across the flour improvers sector as specialized biochemists remain scarce in European and North American production hubs. Puratos Group leverages its vertically integrated enzyme research to dominate premium improver supply for artisan bakery chains. Lesaffre Group anchors global fermentation science capabilities that extend into specialized dough conditioner portfolios for industrial bakers. Corbion competes through microbial fermentation platforms that differentiate its clean-label oxidant alternatives from petrochemical-derived competitors.
Flour improvers comprise functional additives and processing aids that modify dough rheology, gas retention, and finished crumb structure through enzymatic, oxidative, or emulsifying action, typically dosed at 0.1% to 2.0% of flour weight depending on protein content and desired end-product characteristics. Their primary purpose is to standardize flour performance across variable wheat harvests and reduce production inconsistency in high-speed baking operations. Enzyme-based improvers now lead product type demand as amylase and xylanase blends replace chemical oxidants in clean-label formulations, while emulsifiers sustain margin pools through premium positioning in frozen dough applications. Bread applications occupy the largest application share, though pizza dough segments are accelerating fastest behind foodservice expansion and frozen crust demand.
FDA food additive regulations and the USDA organic certification framework govern improver composition and label claims in the United States, while EFSA and EU Green Deal sustainability targets are tightening scrutiny on synthetic additive portfolios across European markets. These regulatory pressures are forcing reformulation investments toward enzyme and fermented solutions that satisfy both safety thresholds and consumer transparency expectations. Stakeholders must monitor evolving clean-label definitions and regional enforcement divergence to align R&D pipelines with compliance trajectories that will determine market access over the forecast horizon.
Market Dynamics
Enzyme-based formulation is compressing chemical oxidant demand across flour improver portfolios as clean-label mandates from the EU Green Deal and FDA disclosure rules force rapid reformulation cycles. This biochemical pivot concentrates margin capture among specialists with captive fermentation science capabilities.
Growth Catalysts
- EU Green Deal additive disclosure:Tightening transparency requirements for synthetic inputs are accelerating enzyme-based improver substitution in German and French industrial baking clusters.
- Artisan bakery clean-label positioning:Premium bread producers across North America are specifying amylase-xylanase blends to differentiate finished products in competitive retail channels.
- Frozen pizza dough expansion:Foodservice chains are standardizing specialized emulsifier systems to maintain crust performance through freeze-thaw cycles.
Market Restraints
- Specialized biochemist scarcity:European and North American production hubs face persistent talent gaps in enzyme formulation and fermentation optimization.
- Wheat protein volatility:Variable harvest quality across major grain belts forces unpredictable improver dosing adjustments that complicate production planning.
- Petrochemical oxidant legacy infrastructure:Existing chemical processing assets create sunk-cost friction against enzyme system conversion.
Strategic Opportunities
- India organized retail baking:Rapid modern trade expansion in Mumbai and Delhi creates first-mover positioning for clean-label improver portfolios.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates reward transparent ingredient sourcing that enzyme fermentation platforms can document.
- Gluten-free enzyme systems:Novel protease and transglutaminase combinations address structural deficits in alternative flour matrices.
Industry Challenges
- Fermentation scale-up timelines:Microbial production capacity expansion requires 18-24 month commissioning cycles that lag demand inflections.
- Cross-border label harmonization:Divergent FDA and EFSA enzyme classification frameworks complicate unified product portfolio development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flour Improvers Market |
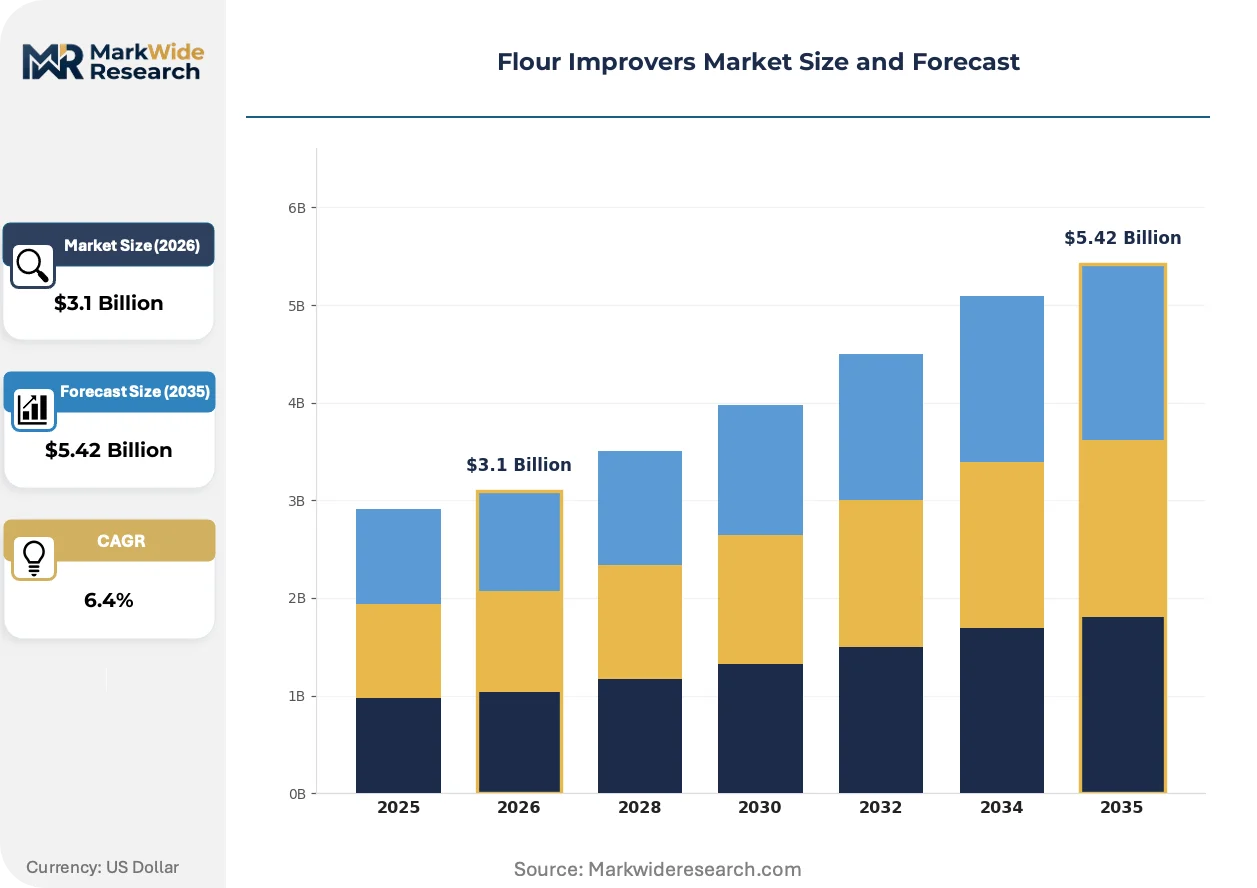
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Emulsifiers, Oxidants, Reducing Agents, Dough Conditioners Application: Bread, Biscuits, Cakes, Pasta, Pizza Dough Packaging Type: Bulk Bags, Sachets, Powder Packs, Liquid Containers, Tubs End User Industry: Bakeries, Foodservice Providers, Frozen Foods Manufacturers, Confectioners, Snack Producers |
| Companies Covered | Puratos Group, Lesaffre Group, AB Mauri, Corbion, Bakels Worldwide, DSM, Archer Daniels Midland Company, Associated British Foods, Group Soufflet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flour Improvers Market Shifts & Advancements
Bioprocessing platforms are compressing development cycles for functional ingredients while regulatory transparency mandates reshape competitive differentiation. Three interconnected developments are determining technology adoption trajectories.
Precision fermentation for oxidant alternatives is miniaturizing production footprints and enabling distributed manufacturing models that reduce transport costs for temperature-sensitive enzyme concentrates. Artisan bakery cooperatives in Denmark and the Netherlands are piloting regional bioreactor installations that shorten supply chains. This distributed architecture is compressing lead times from weeks to days for specialized dough conditioners.
EFSA is tightening enzyme allergen labeling thresholds that force reformulation of multi-enzyme blends to reduce protein carryover from production strains. Industrial bakers in Germany and Italy are demanding segregated production lines to prevent cross-contamination liabilities. The regulatory friction is accelerating investment in GRAS self-determination pathways for novel microbial strains.
Direct supplier relationships are displacing traditional distribution intermediaries as large bakery groups consolidate procurement through centralized technical buying teams. This channel compression is most pronounced in France and the UK where industrial baking concentration has created dedicated ingredient sourcing functions. Technical service integration is becoming the primary vendor selection criterion over commodity pricing.
Flour Improvers Market Segmentation
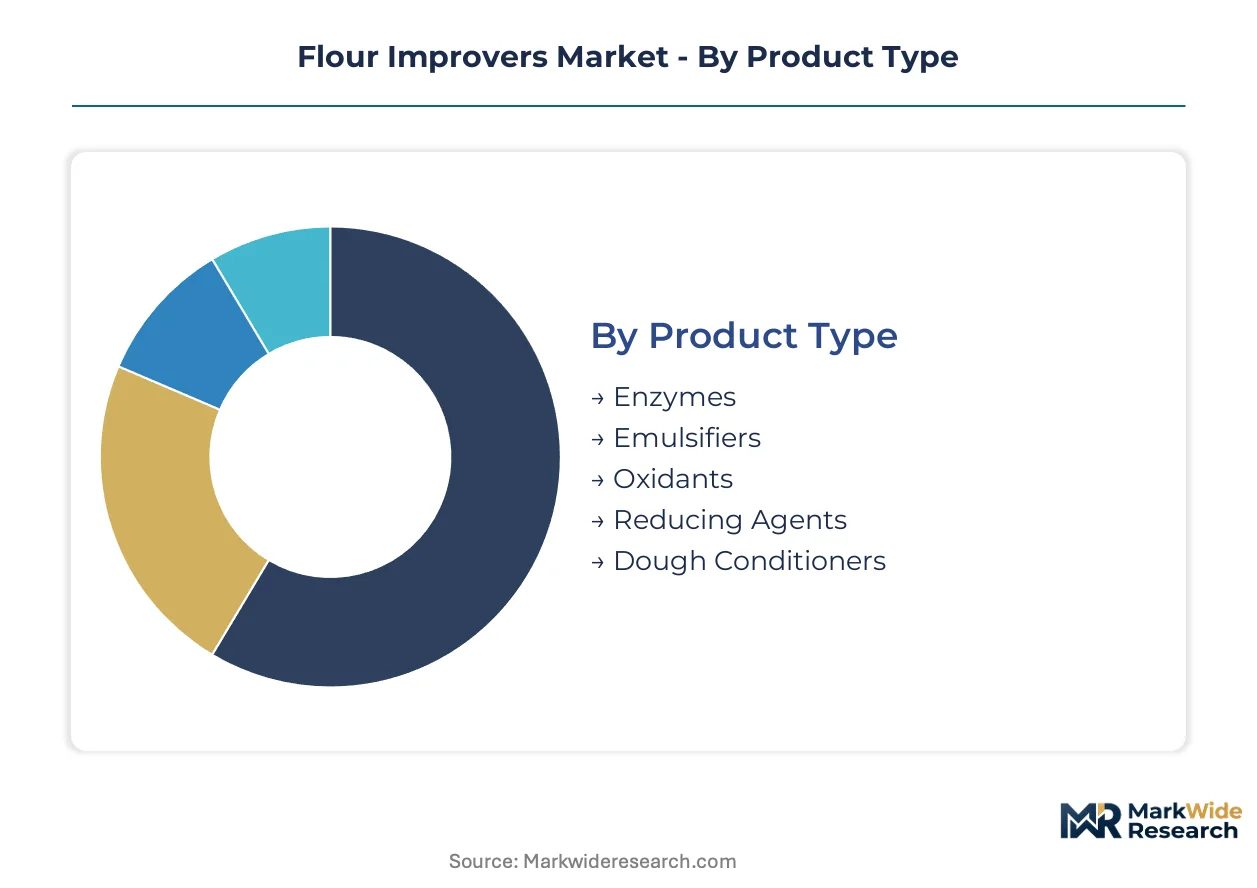
Segmentation in flour improvers determines formulation strategy, dosing precision, and regulatory compliance pathways. Manufacturers align R&D investments with segment-specific performance thresholds and clean-label positioning requirements.
Product Type:
Enzyme-based segments face the strongest substitution pressure from microbial fermentation platforms displacing petrochemical-derived alternatives.
- Enzymes:Amylase, xylanase, and lipase blends modify dough rheology through targeted protein and carbohydrate hydrolysis. Artisan bakeries in Germany specify these systems to meet EU Green Deal transparency mandates while maintaining volume yield.
- Emulsifiers:DATEM, SSL, and lecithin derivatives stabilize gas retention and extend shelf life in frozen applications. Frozen pizza manufacturers in the United States concentrate procurement here to ensure crust integrity through distribution cold chains.
- Oxidants:Azodicarbonamide and potassium bromate alternatives address legacy processing needs.
- Reducing Agents:L-cysteine and sodium metabisulfite relax dough for sheeted products.
- Dough Conditioners:Composite blends combine multiple functional categories for standardized performance.
Enzymes anchor the volume base while emulsifiers gain share at the steepest rate.
Application:
Cost tier stratification separates commodity bread improvers from premium positioning in specialized dough formats.
- Bread:Pan bread and artisan loaf applications consume the largest improver volumes, with dosing rates calibrated to protein content and desired crumb structure. Industrial bakeries in France standardize on enzyme-oxidant blends for consistent line speeds.
- Pizza Dough:Foodservice chains and frozen crust manufacturers drive specialized emulsifier demand for freeze-thaw stability. Quick-service expansion in the United States accelerates specification of high-performance conditioners.
- Biscuits:Cracker and cookie applications require low-protein flour compensation.
- Cakes:High-ratio formulations depend on chlorinated flour alternatives.
- Pasta:Durum wheat standardization demands targeted enzyme systems.
Bread applications dominate current procurement volumes while pizza dough climbs the fastest.
Packaging Type:
Customer type determines format selection, with industrial buyers favoring bulk configurations and artisan operators requiring precision dosing units.
- Bulk Bags:500kg to 1000kg flexible intermediate bulk containers serve industrial milling and large bakery operations. Facilities around Hamburg and Munich standardize on this format for enzyme concentrate reception.
- Sachets:Pre-measured unit doses enable consistent small-batch performance. Artisan cooperatives in Denmark specify sachet formats to eliminate weighing errors in distributed production.
- Powder Packs:Intermediate sizing for mid-scale bakeries.
- Liquid Containers:Pump-dispensed emulsifier systems for automated dosing lines.
- Tubs:Scoopable formats for bench-scale testing and development kitchens.
Bulk bags capture the largest volume flows while sachets expand most quickly through artisan channel penetration.
End User Industry:
Supply concentration among frozen food manufacturers creates margin pressure distinct from fragmented artisan bakery procurement patterns.
- Bakeries:Industrial, artisan, and in-store operations constitute the primary demand channel, with formulation requirements varying by scale and product mix. German industrial clusters drive bulk enzyme procurement for standardized output.
- Frozen Foods Manufacturers:Pizza crust, par-baked bread, and dough ball producers specify emulsifier-heavy systems for extended frozen shelf life. North American foodservice supply chains concentrate volume here.
- Foodservice Providers:Central commissaries and contract baking operations.
- Confectioners:Specialized applications in wafer and sponge cake production.
- Snack Producers:Extruded and sheeted snack dough conditioning requirements.
Bakeries anchor the volume base while frozen foods manufacturers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA disclosure mandates anchor European regulatory gravity, while FDA organic frameworks and FSSAI modernization programs shape procurement patterns across North American and South Asian industrial baking clusters respectively.
United States
Foodservice chains and frozen pizza manufacturers drive specialized emulsifier procurement for extended shelf-life applications. FDA disclosure rules and USDA organic certification frameworks govern clean-label improver composition and marketing claims. Industrial baking concentration around Chicago and Minneapolis-St. Paul standardizes bulk enzyme concentrate reception through dedicated technical buying teams.
Germany
Artisan bakery cooperatives and industrial milling clusters scale amylase-xylanase blends to meet EU Green Deal transparency targets. EFSA enzyme allergen labeling thresholds force reformulation of multi-enzyme blends to reduce protein carryover risks. Munich and Hamburg anchor the continent's densest concentration of dough conditioner procurement, with facilities standardizing on 500kg to 1000kg flexible intermediate bulk containers.
India
Rapid modern trade expansion in Mumbai and Delhi creates first-mover positioning for clean-label improver portfolios targeting organized retail baking. FSSAI additive disclosure modernization and PLI scheme incentives for food processing infrastructure accelerate specification of enzyme-based systems. Maharashtra and Gujarat industrial corridors concentrate mid-scale bakery equipment investment that pairs with precision-dosing sachet formats.
France
Premium bread producers specify amylase-xylanase blends to differentiate finished products in competitive retail channels. EU Green Deal sustainable food system targets tighten scrutiny on synthetic additive portfolios, forcing reformulation investments. Île-de-France and Auvergne-Rhône-Alpes host centralized technical buying teams that displace traditional distribution intermediaries through direct supplier relationships.
Netherlands
Artisan bakery cooperatives pilot regional bioreactor installations that shorten supply chains for temperature-sensitive enzyme concentrates. REACH chemical registration requirements and CSRD supply chain disclosure mandates reward transparent ingredient sourcing. Randstad region precision fermentation facilities miniaturize production footprints and enable distributed manufacturing models that compress lead times from weeks to days.
Flour Improvers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the flour improvers sector, with fermentation science capabilities determining margin capture. The upper tier concentrates enzyme research and microbial production platforms that supply standardized performance to industrial baking clusters. Specialist competitors occupy niches in clean-label oxidant alternatives and frozen dough emulsifier systems. M&A activity targets captive fermentation assets, while capacity expansion focuses on microbial strain development and regional bioreactor commissioning.
Among integrated fermentation specialists, Puratos Group, Lesaffre Group, and Corbion occupy positions that exemplify the vertical-tier structure. Puratos represents the enzyme formulation archetype with vertically integrated research capabilities. Lesaffre anchors global fermentation science positioning that extends into specialized dough conditioner portfolios. Corbion sits within the microbial fermentation platform tier that differentiates clean-label oxidant alternatives from petrochemical-derived competitors.
| Leading Market Players |
|---|
| Puratos Group |
| Lesaffre Group |
| AB Mauri |
| Corbion |
| Bakels Worldwide |
| DSM |
| Archer Daniels Midland Company |
| Associated British Foods |
| Group Soufflet |
| Others |
Supply & Pricing Matrix
Enzyme-based improver substitution for petrochemical oxidants simultaneously redistributes production geography toward fermentation science clusters and compresses pricing power in legacy chemical supply tiers. This biochemical pivot concentrates margin capture among specialists with captive microbial platforms while eroding commodity premiums for synthetic additive portfolios.
Pricing Analysis
Long-term offtake contracts dominate procurement between industrial baking clusters and integrated fermentation specialists, with spot purchasing confined to small-scale artisan operators facing supply insecurity. Three-tier pricing structure across premium enzyme concentrates, standard emulsifier blends, and economy chemical oxidants reflects certification grade and volume scale differentiation. Cost compression in economy tiers intensifies because European and North American chemical oxidant producers confront stranded asset risk from EU Green Deal disclosure mandates. Frozen food manufacturers exhibit the least price sensitivity due to freeze-thaw performance requirements, while mid-scale bakeries in emerging markets drive hardest bargaining on unit dosing economics.
Supply Chain Analysis
Belgium and the Netherlands anchor precision fermentation capacity for temperature-sensitive enzyme concentrates, while Germany and France host compounding operations for standardized dough conditioner blends. Microbial strain banks, carbohydrate feedstocks, and specialized filtration membranes constitute critical input dependencies. Single-source vulnerability concentrates in proprietary strain collections held by integrated specialists, creating acquisition-driven supply continuity risk. Distribution runs through direct technical service relationships that displace traditional ingredient distributors in concentrated industrial baking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where fermentation science capabilities function as interoperable infrastructure across multiple clean-label ingredient categories, with enzyme improver expertise transferring directly to adjacent oxidant alternative development.
For Market Incumbents: Compound fermentation science advantages through backward integration into carbohydrate feedstock processing and regional bioreactor commissioning in proximity to German and North American industrial baking clusters. Patent-protected strain development and CSRD-compliant supply chain documentation serve as defensive moats against specialty chemical entrants pivoting from eroding oxidant markets. Capacity addition in Randstad precision fermentation facilities captures distributed manufacturing economics that compress competitor lead times. For New Entrants and Emerging Players: Anchor in India's organized retail baking expansion across Mumbai and Delhi, where FSSAI modernization creates regulatory parity for clean-label enzyme systems against legacy chemical portfolios. Mid-scale bakery equipment investment corridors in Maharashtra and Gujarat pair naturally with sachet-format precision dosing, the most penetrable entry configuration before industrial scale-up. Technical service partnerships with European fermentation specialists accelerate regulatory dossier compilation without captive R&D infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical platforms holding stranded oxidant production capacity and seeking enzyme fermentation repositioning. Long-term viability over a multi-year horizon hinges on successful strain development pipeline conversion and EFSA allergen labeling compliance trajectory. Monitor EU Green Deal enforcement variance across member states as the critical signal distinguishing regulatory-leader markets from lagging jurisdictions where synthetic additive runway persists.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Regional bioreactor installations in Randstad and Denmark shorten enzyme concentrate lead times from weeks to days. |
| Backward Integration into Feedstock Processing | Captive carbohydrate supply secures strain productivity against agricultural commodity volatility in major grain belts. |
| CSRD-Compliant Supply Chain Documentation | Transparent fermentation sourcing satisfies EU corporate sustainability reporting mandates for industrial bakery procurement teams. |
| Direct Technical Service Relationships | Channel compression displaces traditional distributors as French and UK bakery groups consolidate through centralized buying functions. |
| GRAS Self-Determination Pathway Investment | Novel microbial strain regulatory clearance accelerates multi-enzyme blend reformulation ahead of EFSA allergen threshold tightening. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA enzyme classification frameworks, EU Green Deal implementation guidance, and FSSAI additive disclosure modernization protocols. Plant managers at German industrial milling clusters, procurement leads at North American frozen pizza manufacturers, technical R&D directors at fermentation specialists, and channel partners in French bakery supply chains contributed operational perspective. Customs data on enzyme concentrate trade flows, SEC filings from integrated ingredient platforms, and Cefic chemical industry reports provided secondary validation. Bottom-up segment sizing triangulates against top-down market reconstruction from production capacity and consumption intensity benchmarks.
Segmentation dimensions modeled span product type, application, packaging configuration, and end-user industry scale across the projection horizon. Enzyme, emulsifier, oxidant, and composite conditioner categories intersect with bread, pizza dough, biscuit, cake, and pasta applications. Industrial, artisan, and frozen food manufacturer end-user tiers calibrate dosing rate assumptions and procurement pattern differentiation. CAGRs derive from volume trajectory analysis against protein content standardization requirements and clean-label substitution elasticity.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and enzyme biochemist availability assumptions; material deviation in regulatory timeline or talent pipeline would warrant model refresh. Wheat protein volatility, cross-border label harmonization friction, and fermentation scale-up commissioning cycles constitute specific revision triggers. Recalibration cycles align with material shifts in EFSA enzyme allergen thresholds and CSRD supply chain disclosure implementation depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Food Raising Agents Market