
 Automotive Robotics Market | 2026-2036
Automotive Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Robotics Market Intelligence
EU Green Deal carbon-border adjustments is repositioning the cost structure for European automotive robot procurement. ABB Group leverages its Swiss-German engineering footprint to dominate arc-welding robot supply for EV chassis production. FANUC Corporation sustains unmatched servo-motor manufacturing scale from its Yamanashi facilities, anchoring Japanese OEM supply chains. KUKA AG competes through deep integration with German automotive engineering standards and Mercedes-Benz Group assembly line specifications.
Automotive robotics encompasses programmable multi-axis manipulators, autonomous mobile platforms, and sensor-guided cobot systems operating with repeatability tolerances below 0.1 millimeter for precision assembly, welding, and surface-finishing operations in vehicle manufacturing. Robotic arms and automated guided vehicles command the largest installed base across OEM final-assembly floors, while collaborative robots represent the fastest-expanding category as Tier-1 suppliers retool for mixed-model battery-electric production. Machine vision and AI integration technologies concentrate margin pools where real-time defect detection and adaptive path planning reduce rework rates and unplanned downtime.
FDA device-quality standards influence collaborative robot safety certification for human-robot interaction zones in North American plants, while REACH chemical-compliance rules govern robot coating and lubricant specifications across EU member states. Japan's METI subsidizes next-generation robot R&D through its Society 5.0 framework, directly shaping Kawasaki Heavy Industries and Yaskawa Electric Corporation product roadmaps. Stakeholders must monitor how ISO 10218 safety standard revisions and emerging EU AI Act risk classifications for autonomous manufacturing systems will reshape procurement criteria and vendor qualification timelines.
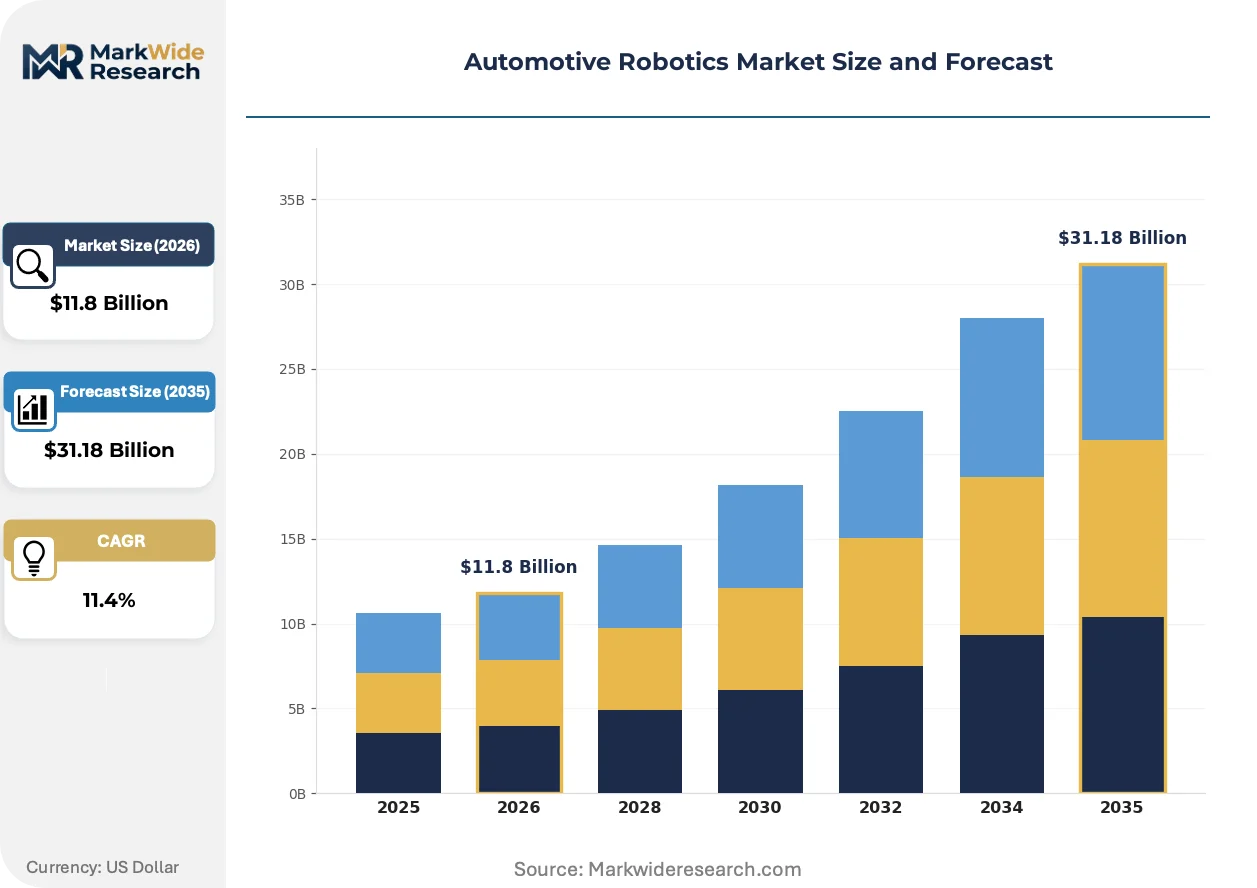
Market Dynamics
EU Green Deal carbon-border adjustments are forcing European OEMs to retool assembly lines with precision robotics capable of sub-0.1-millimeter repeatability for EV battery pack welding and chassis bonding operations.
Growth Catalysts
- EU Green Deal compliance mandates:German and French automakers must cut manufacturing emissions per unit by 2030, driving automated arc-welding robot deployment for lightweight aluminum chassis construction.
- Machine vision convergence:AI-powered defect detection systems reduce rework rates in battery module assembly, justifying capital expenditure through unplanned downtime reduction.
- South Korean EV platform retooling:Hyundai Motor Group and Kia Corporation are converting existing internal-combustion engine lines to dedicated battery-electric vehicle production, requiring full robot redeployment.
Market Restraints
- Servo motor supply concentration:Yamanashi Prefecture in Japan produces the majority of high-precision servo motors, creating single-source vulnerability for multi-axis robot arm production.
- REACH chemical compliance costs:Robot lubricant and coating reformulation to eliminate restricted substances adds 12-18 months to EU market entry timelines for new robot models.
- Legacy system integration friction:Existing programmable logic controllers from 1990s-era automotive lines lack Ethernet/IP compatibility with modern collaborative robot safety systems.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Production-linked incentive programs for advanced automotive cells and battery packs are attracting robot vendors to establish local assembly facilities.
- Autonomous mobile robot fleet expansion:Unmanned guided vehicles for just-in-time component delivery between Tier-1 supplier parks and OEM final-assembly floors remain underdeployed outside Germany and Japan.
- ISO 10218-2 safety standard revision:Updated collaborative robot speed and separation monitoring requirements will trigger replacement cycles for pre-2020 installed cobot systems.
Industry Challenges
- Multi-axis kinematics programming shortage:Automotive plants lack sufficient technicians trained in robot path optimization for mixed-model battery-electric and plug-in hybrid production.
- Functional safety certification timelines:TÜV SÜD and SGS verification of safety-rated monitored stop functions delays new cobot model launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Robotics Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $31.18 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ART, Collaborative Robots, Robotic Arms, Automated Guided Vehicles Application: Assembly, Welding, Painting, Material Handling End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: AI Integration, IoT Connectivity, Machine Vision, Force Feedback |
| Companies Covered | ABB Group, FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Denso Corporation, Kawasaki Heavy Industries, Comau S.p.A., Nachi-Fujikoshi Corporation, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Robotics Market Strategic Shifts & Innovations
Digital twin simulation and edge-computing sensor fusion are compressing robot commissioning timelines from months to weeks, while regulatory pressure on manufacturing emissions accelerates automation intensity per vehicle produced.
Force-torque sensing and adaptive impedance control are integrating into collaborative robot end-effectors for battery cell stacking operations. Tier-1 suppliers in South Korea and China are adopting these systems for cylindrical cell-to-module assembly. The technology is integrating human-robot interaction safety with precision placement tolerances below 50 micrometers, eliminating dedicated hard-automation cells for low-volume EV variants.
EU AI Act risk classification for autonomous manufacturing systems is mandating conformity assessment procedures for self-learning robot path planners. Industrial consequence includes mandatory human oversight protocols and audit trail documentation for adaptive welding parameter adjustments. Battery pack assembly lines in Germany and Sweden face the most immediate compliance deadlines, with Mercedes-Benz Group and Volvo Car AB already restructuring vendor qualification checklists.
Automotive OEMs are consolidating robot procurement under single-source framework agreements with multi-year service attachments, displacing transactional equipment purchases. Tier-1 suppliers in Japan and Germany now negotiate outcome-based throughput guarantees rather than capital expenditure ownership. This shift is most visible in electric drivetrain component manufacturing, where Aisin Corporation and Bosch GmbH have transferred robot fleet management to vendor-operated models with uptime penalties.
Automotive Robotics Market Segmentation
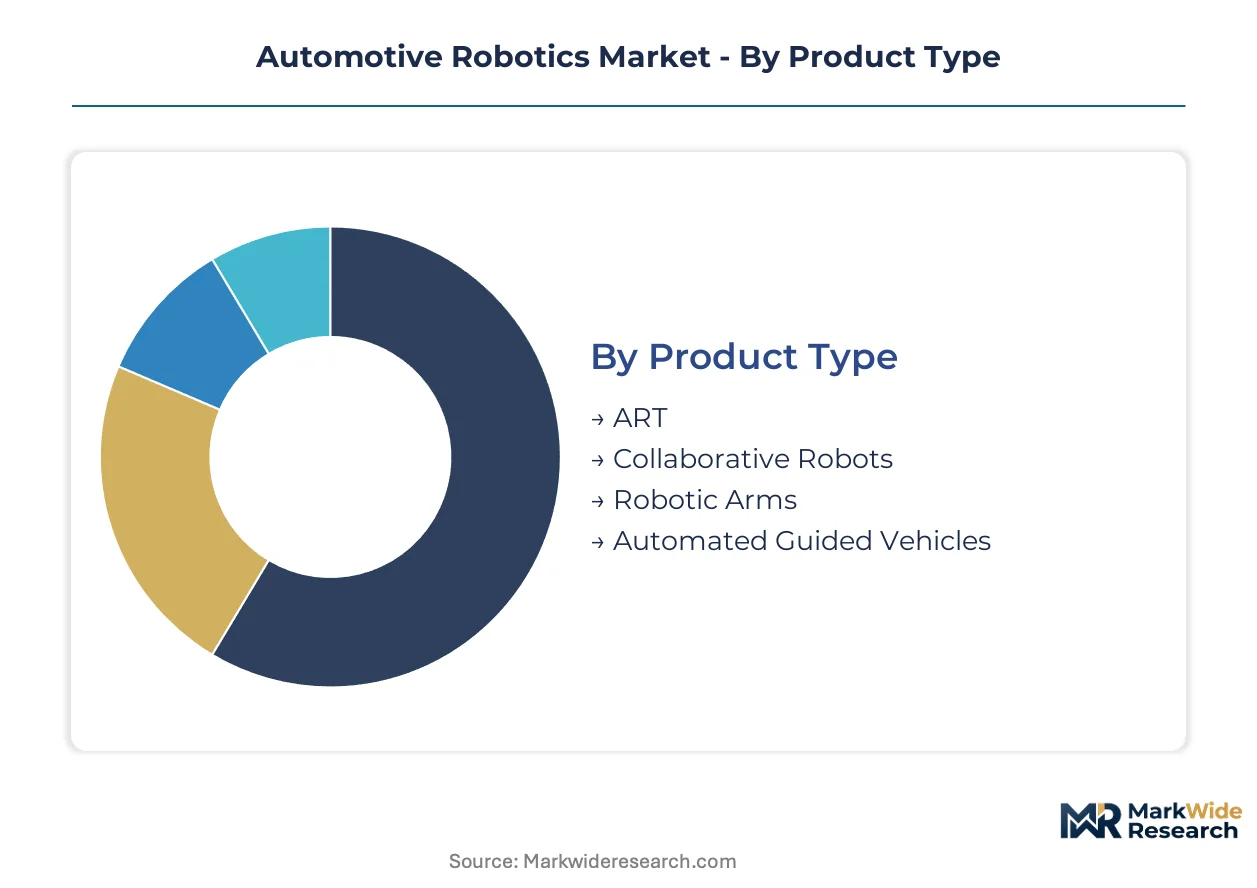
Automotive robotics segmentation reveals how precision requirements and human-robot interaction demands split procurement strategies across vehicle manufacturing stages. Battery-electric platform retooling is compressing traditional category boundaries as EV assembly lines demand hybrid automation architectures.
Product Type:
Standardized multi-axis platforms dominate high-volume chassis welding, while configurable cobot systems address mixed-model battery pack assembly where production runs shift weekly.
- ART:Adaptive robotic technology platforms integrate force-torque sensing with real-time path correction for aluminum-intensive EV body-in-white construction. German OEMs deploy ART systems for carbon-fiber reinforced plastic bonding operations where thermal expansion tolerances demand sub-0.05-millimeter compensation.
- Collaborative Robots:Force-limited articulated arms with ISO 10218-2 certified safety-rated monitored stop functions enable human-robot collaboration in battery module stacking. Tier-1 suppliers in South Korea are redeploying these systems for cylindrical cell-to-module assembly where production lots change every 48 hours.
- Robotic Arms:Six-axis servo-motor driven manipulators with 0.1-millimeter repeatability specifications handle arc-welding and spot-welding operations across final-assembly floors.
- Automated Guided Vehicles:Laser-guided and vision-guided mobile platforms transport powertrain components between supplier parks and OEM lines in just-in-time configurations.
Leading the category by volume: Robotic Arms. Growing fastest: Collaborative Robots.
Application:
Process automation intensity varies by body shop versus paint shop versus final assembly, with welding commanding the highest robot density per square meter of manufacturing footprint.
- Assembly:Precision component mating for electric drivetrain integration, including motor-stator insertion and inverter mounting, requires adaptive compliance control. Battery pack assembly lines in China combine robotic fastening with automated torque verification for high-voltage safety compliance.
- Welding:Arc and resistance welding of aluminum extrusions and high-strength steel dominates EV chassis construction. EU Green Deal emissions mandates are accelerating aluminum adoption, which demands pulsed MIG welding robots with adaptive wire feed control.
- Painting:Electrostatic spray application with atomizer robots achieves transfer efficiency above 85 percent for waterborne basecoats and clearcoats.
- Material Handling:Palletizing, depalletizing, and sequencing of stamped body panels and powertrain castings employs vacuum-gripper and magnetic-gripper end-effector configurations.
Welding captures the largest installed base. Assembly exhibits the steepest expansion trajectory as battery-electric platform complexity multiplies component count per vehicle.
End User:
Capital deployment cycles diverge between integrated OEM manufacturing and outsourced Tier-1 component supply, with fleet ownership models emerging as a structural alternative to direct procurement.
- OEMs:Original equipment manufacturers operate captive robot fleets across body shops, paint shops, and final assembly halls. Mercedes-Benz Group and Volvo Car AB are restructuring vendor qualification checklists to incorporate EU AI Act conformity assessment for autonomous welding parameter adjustment systems.
- Tier-1 Suppliers:Aisin Corporation and Bosch GmbH have transferred robot fleet management to vendor-operated models with uptime penalties in electric drivetrain component manufacturing.
- Aftermarket Providers:Refurbishment and remanufacturing operations for collision repair and powertrain rebuilding employ lower-precision robotic cells.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders deploy flexible automation for low-volume production runs.
OEMs retain dominant procurement volume. Tier-1 Suppliers are gaining share fastest through outcome-based service contracting.
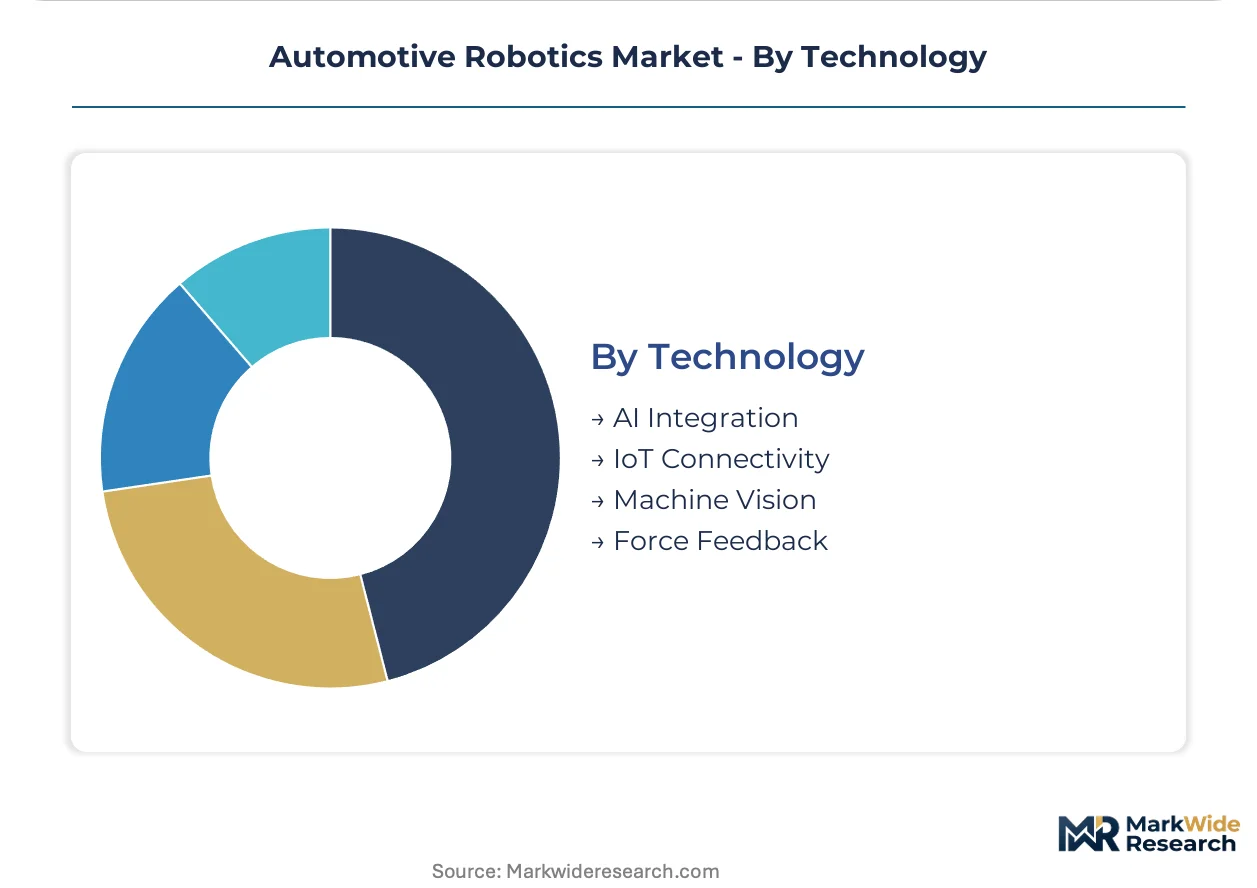
Technology:
Margin concentration follows sensor fusion complexity, with vision-guidance and AI-adaptive systems commanding premium positioning over baseline motion-control platforms.
- AI Integration:Self-learning path planners with weld seam tracking and adaptive parameter adjustment face EU AI Act risk classification mandates requiring audit trail documentation and human oversight protocols in German and Swedish battery pack assembly lines.
- Machine Vision:2D and 3D camera systems with real-time defect detection reduce rework rates in battery module assembly. Hyundai Motor Group lines in South Korea combine vision-guided robots with automated go/no-go quality gates.
- IoT Connectivity:Ethernet/IP and OPC-UA protocols enable predictive maintenance and overall equipment effectiveness monitoring across distributed robot fleets.
- Force Feedback:Torque sensors and impedance control algorithms enable delicate insertion operations for battery cell stacking and connector mating.
Machine Vision leads technology attachment rates. AI Integration is climbing the fastest as regulatory frameworks formalize deployment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China, Germany, South Korea, and the United States concentrate automotive robot deployment through targeted tax incentives and subsidized industrial land. These zones attract OEM final-assembly investments and Tier-1 supplier co-location. Manufacturing clusters within each zone drive procurement intensity for precision welding and battery assembly systems.
China
Yangtze River Delta automotive corridors demand collaborative robots for mixed-model EV battery pack assembly where production lots shift weekly. MIIT dual carbon goals mandate manufacturing emissions reductions that accelerate aluminum chassis welding automation. Shanghai and Suzhou industrial parks host BYD and NIO facilities deploying adaptive robotic technology for carbon-fiber reinforced plastic bonding operations.
Germany
Bavarian and Baden-Württemberg OEM facilities require sub-0.1-millimeter repeatability robots for EU Green Deal compliance on lightweight aluminum chassis construction. REACH chemical regulations force 12-18 month lubricant reformulation cycles that delay new robot model launches. Stuttgart and Munich manufacturing belts anchor Mercedes-Benz Group and BMW AG assembly lines where vendor qualification checklists now incorporate EU AI Act conformity assessment.
United States
Southeastern automotive corridors in Tennessee and South Carolina retool for electric drivetrain production requiring precision motor-stator insertion robots. FDA device-quality standards influence collaborative robot safety certification for human-robot interaction zones. Detroit and Austin industrial clusters concentrate battery-electric vehicle platform investments from Ford Motor Company and Tesla Inc.
Japan
Yamanashi Prefecture servo-motor manufacturing creates single-source supply vulnerability for multi-axis robot arm production serving Toyota Motor Corporation and Honda Motor Co. METI Society 5.0 framework subsidizes next-generation robot R&D through targeted innovation grants. Nagoya and Tokyo Bay industrial zones concentrate FANUC Corporation and Yaskawa Electric Corporation headquarters with captive component fabrication.
South Korea
Busan-Ulsan manufacturing belts convert internal-combustion engine lines to dedicated battery-electric vehicle production requiring full robot redeployment. MFDS-equivalent industrial safety standards govern collaborative robot speed and separation monitoring in Hyundai Motor Group facilities. Gwangju-Honam supplier parks deploy autonomous mobile vehicles for just-in-time component delivery between Tier-1 facilities and OEM final-assembly floors.
Automotive Robotics Market Key Industry Players
German producers anchor one tier; Japanese specialists hold precision servo-motor manufacturing scale. The vendor base concentrates around integrated motion-control platforms and safety-certified collaborative systems. Three archetypes dominate: full-line automation integrators, component-specialist suppliers, and fleet-management service operators. Competitive moves center on backward integration into servo-motor production and geographic expansion through subsidized manufacturing zones.
Within the full-line integrator tier, ABB Group and FANUC Corporation occupy positions defined by captive engineering footprints across Swiss-German and Yamanashi manufacturing belts. KUKA AG exemplifies the European engineering-standards archetype through its Baden-Württemberg headquarters structure. These three entities represent the concentration of arc-welding and spot-welding robot supply for EV chassis production globally.
| Leading Market Players |
|---|
| ABB Group |
| FANUC Corporation |
| KUKA AG |
| Yaskawa Electric Corporation |
| Denso Corporation |
| Kawasaki Heavy Industries |
| Comau S.p.A. |
| Nachi-Fujikoshi Corporation |
| Seiko Epson Corporation |
| Others |
Cost & Logistics Intelligence
Adaptive robotic technology platforms with force-torque sensing capabilities are compressing commissioning timelines and simultaneously concentrating procurement power among OEMs capable of absorbing upfront capital outlays. This production-method transition reshapes cost economics by rewarding scale buyers while squeezing mid-tier suppliers unable to match throughput guarantees.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to collaborative robot orders from Tier-1 suppliers facing EU AI Act compliance deadlines in Germany and Sweden. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10218-2 certified systems with full safety documentation from uncertified alternatives. Pricing pressure stems from Japanese servo-motor supply concentration that limits vendor bargaining leverage. Tier-1 suppliers exhibit highest price sensitivity due to outcome-based contracting models with uptime penalties, while Mercedes-Benz Group and BMW AG absorb premiums for customized arc-welding configurations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Mercedes-Benz Group and Hyundai Motor Group, while distributor networks serve aftermarket refurbishment operations. Component fabrication concentrates in Japan's Yamanashi Prefecture for servo motors, Germany's Baden-Württemberg for precision gearboxes, and China's Yangtze River Delta for controller electronics. Supply chains rest on rare-earth magnet dependencies for motor torque density and specialized optical sensor imports for machine vision systems. Single-source vulnerability in Yamanashi servo-motor production creates structural risk for multi-axis robot arm availability. Distribution runs through ABB Group and FANUC Corporation direct sales forces for major OEM accounts, with regional integrators covering Tier-1 supplier parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive robotics sector functions as a vertical-integration race where captive servo-motor production and safety-certification capabilities determine vendor survival. Players are pursuing backward integration into precision motion-control component manufacturing to escape supply bottlenecks.
For Market Incumbents: Cement market position through captive Yamanashi-region servo-motor supply agreements or in-house torque-motor production investments. Prioritize TÜV SÜD and SGS pre-certification of safety-rated monitored stop functions to compress new model launch timelines against emerging Chinese competitors. Defensive consolidation must address outcome-based service contracting erosion from Aisin Corporation and Bosch GmbH vendor-operated fleet models. For New Entrants and Emerging Players: Begin with autonomous mobile robot fleet management for just-in-time component delivery between Tier-1 supplier parks and OEM final-assembly floors in India and Southeast Asia. Target India's PLI scheme manufacturing zones where local assembly requirements create procurement preference for domestically sourced automation. Penetrate through predictive maintenance software attachments that retrofit legacy 1990s-era programmable logic controller installations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by industrial automation conglomerates seeking safety-certification capabilities and automotive OEM qualification relationships. Five-to-ten year viability hinges on EU AI Act conformity assessment infrastructure and ISO 10218-2 revision compliance timing. Target acquisition archetypes include force-torque sensor specialists and adaptive welding software developers. Monitor TÜV SÜD certification queue lengths as inflection indicator for vendor qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motor Production | Captive Yamanashi-scale manufacturing insulates against single-source supply vulnerability for multi-axis robot arms. |
| EU AI Act Conformity Assessment Pre-Certification | TÜV SÜD and SGS documentation accelerates Mercedes-Benz Group and Volvo Car AB vendor qualification timelines. |
| Outcome-Based Service Contracting Expansion | Uptime penalty structures transfer fleet management risk from Aisin Corporation to robot vendors. |
| Force-Torque Sensor End-Effector Development | Sub-50-micrometer battery cell stacking precision eliminates dedicated hard-automation cells for low-volume EV variants. |
| India PLI Scheme Local Assembly Facilities | Domestic production qualification unlocks advanced automotive cell and battery pack procurement from BYD and NIO supply chains. |
Research Approach
Document review covered vehicle production databases, IHS Markit registration data, SEC filings from listed automation vendors, and EU regulatory filings, complemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket service heads, and plant engineers at German and South Korean facilities. Bottom-up triangulation validated against top-down market sizing from customs and trade data produced convergent estimates across the analysis window.
Historical shipment data cross-referenced against expert panel input on EU Green Deal compliance timelines and EV platform retooling cycles anchored the analytical framework. Segmentation dimensions modeled include robot product type, manufacturing application stage, end-user procurement archetype, and regional production cluster. CAGRs derived from installed base growth rates and replacement cycle acceleration through ISO 10218-2 revision deadlines. Industry-specific inputs incorporated METI Society 5.0 subsidy disbursement patterns and India PLI scheme manufacturing incentive uptake.
Underlying measurement precision varies by segment; robotic arms and established welding applications carry tighter precision than emerging collaborative robot and AI-integration categories. Forecasts reflect assumptions on EU AI Act implementation timing and REACH chemical compliance cycle durations. Practitioners should monitor TÜV SÜD certification queue lengths, Yamanashi servo-motor allocation announcements, and India PLI scheme beneficiary lists for early signals of supply constraint or demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Palletizing Robots Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market