
 Fifth-Party Logistics Market | 2026-2036
Fifth-Party Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Fifth-Party Logistics Market Analysis
Enterprise-grade orchestration is bifurcating the Fifth-Party Logistics landscape into premium platform providers and commodity freight brokers. DHL Supply Chain leverages its proprietary control-tower architecture to anchor complex pharmaceutical and automotive networks across Europe. Kuehne + Nagel sustains competitive positioning through deep specialization in perishable logistics and seafreight integration. C.H. Robinson differentiates via its digital freight-matching platform, which dominates North American truckload procurement at scale.
Fifth-party logistics denotes supply chain orchestration where a single entity designs, manages, and optimizes entire logistics networks across multiple third- and fourth-party providers, typically employing API-first integration layers and real-time visibility dashboards to synchronize inventory, transportation, and fulfillment decisions. The primary commercial purpose centers on reducing total landed cost while improving service-level consistency for shippers lacking internal network-design expertise. Cloud-based deployment models are capturing disproportionate investment as manufacturers demand elastic compute for demand-sensing algorithms without capital-intensive infrastructure commitments. Transportation services retain the largest revenue share within service-type segmentation, though inventory management modules are expanding fastest as retailers adopt AI-driven safety-stock optimization. E-commerce customer types are pulling 5PL providers toward micro-fulfillment configurations and returns-loop integration.
The EU Green Deal and its delegated acts on transport emissions reporting are compelling 5PL operators to embed carbon-accounting APIs directly into routing engines, reshaping platform procurement criteria for large shippers. Germany's KBA enforces strict driver-hours compliance that 5PL networks must algorithmically optimize across subcontractor fleets to avoid liability exposure. REACH chemical-handling documentation requirements further complicate European cross-border orchestration, favoring providers with integrated customs and hazardous-materials workflows. Stakeholders must evaluate whether their current 5PL partnerships possess embedded regulatory-adaptation capabilities or merely outsource compliance risk without structural integration.
Market Dynamics
API-first orchestration platforms are compressing coordination costs across multi-tier supplier networks, enabling real-time inventory synchronization that legacy EDI systems cannot match. This structural shift rewards providers with embedded data-science capabilities over traditional freight brokers.
Growth Catalysts
- EU Green Deal emissions mandates:Delegated acts on transport reporting compel shippers to procure 5PL platforms with embedded carbon-accounting APIs, accelerating replacement of spreadsheet-based tracking.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution across fragmented European supplier bases demands orchestrators capable of real-time deviation alerts and contingency rerouting.
- AI-driven safety-stock optimization:Retailers deploying machine learning for demand sensing require elastic cloud compute that 5PL platforms provision without capital-intensive warehouse management system upgrades.
Market Restraints
- Subcontractor fleet fragmentation:Dense networks of small European trucking operators create liability exposure under Germany's KBA driver-hours enforcement, requiring costly algorithmic compliance layers.
- REACH documentation complexity:Chemical-handling workflows for cross-border EU movements demand integrated customs and hazardous-materials capabilities that commodity brokers lack.
- Legacy system integration costs:Proprietary shipper ERP architectures resist standard API protocols, extending implementation timelines and inflating professional services margins.
Strategic Opportunities
- Micro-fulfillment network design:E-commerce pull toward urban last-mile densification creates white space for 5PL providers configuring dark-store synchronization across tiered inventory pools.
- Returns-loop integration:Reverse logistics orchestration for apparel and electronics retailers remains underserved, with specialized providers capturing premium pricing for closed-loop visibility.
- CSRD-aligned disclosure services:Corporate Sustainability Reporting Directive scope expansion positions 5PL platforms as embedded data aggregators for Scope 3 transport emissions verification.
Industry Challenges
- Data-science talent scarcity:Demand-sensing algorithm development requires hybrid supply chain and machine-learning expertise that European labor markets undersupply.
- Interoperability standardization delays:Competing visibility protocols among platform providers fragment API ecosystems, forcing costly adapter development for multi-client deployments.
- Cybersecurity certification timelines:ISO 27001 and TISAX audits for automotive and pharmaceutical data handling extend sales cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fifth-Party Logistics Market |
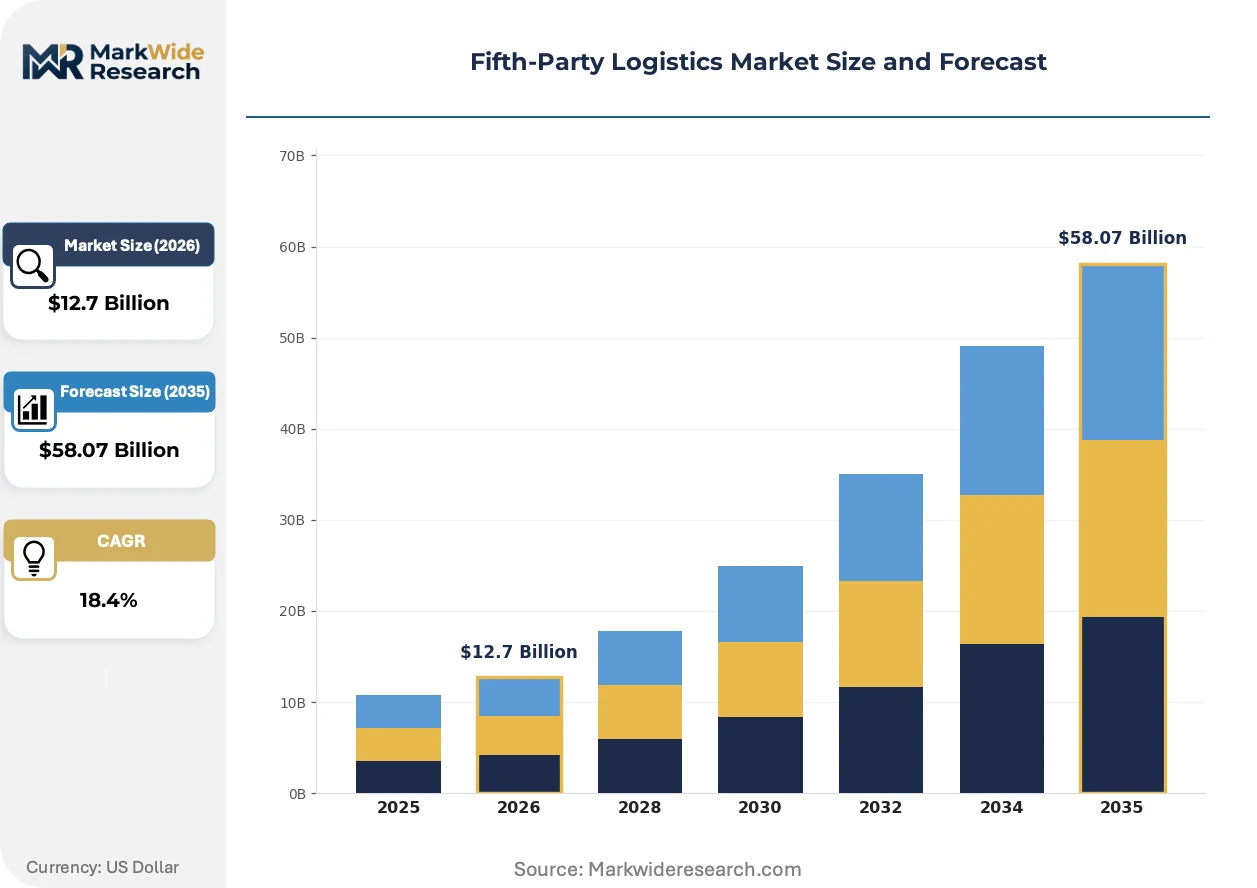
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Inventory Management, Order Fulfillment Deployment Model: On-premises, Cloud-based, Hybrid, Dedicated Customer Type: Retailers, Manufacturers, Distributors, E-commerce Technology: IoT, Big Data Analytics, Artificial Intelligence, Blockchain |
| Companies Covered | 5PL Logistics Solutions LLC, DHL Supply Chain, Toll Holdings Ltd, Kuehne + Nagel, C.H. Robinson, XPO Logistics, Maine Pointe, Bain & Company, Boston Consulting Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fifth-Party Logistics Market Emerging Trajectories
Distributed ledger architectures and predictive routing engines are restructuring how logistics networks self-coordinate, shifting competitive advantage from asset ownership toward algorithmic network design.
Digital twin simulation for supply chain stress-testing is supplanting static network modeling in pharmaceutical and automotive verticals. Manufacturers in the Rhine-Ruhr corridor deploy these tools to pre-validate contingency responses before supplier disruptions materialize. This capability compression is collapsing the traditional separation between strategic network design and operational execution.
REACH delegated acts on chemical substance tracking are tightening documentation requirements for cross-border EU movements. 5PL operators must embed ECHA-compliant workflow engines directly into routing systems or forfeit pharmaceutical and specialty chemical contracts. German chemical manufacturers are responding by consolidating vendor panels to providers with pre-certified hazardous-materials modules.
Buyer procurement committees now mandate API-native visibility as a table-stakes requirement, displacing quarterly business review relationships. Automotive OEMs in Bavaria and Baden-Württemberg lead this shift, embedding 5PL platforms directly into their MES layers for supplier-managed inventory programs. This behavioral pivot concentrates contract value with orchestrators possessing real-time WMS-TMS-ERP trilateral integration.
Fifth-Party Logistics Market Segmentation
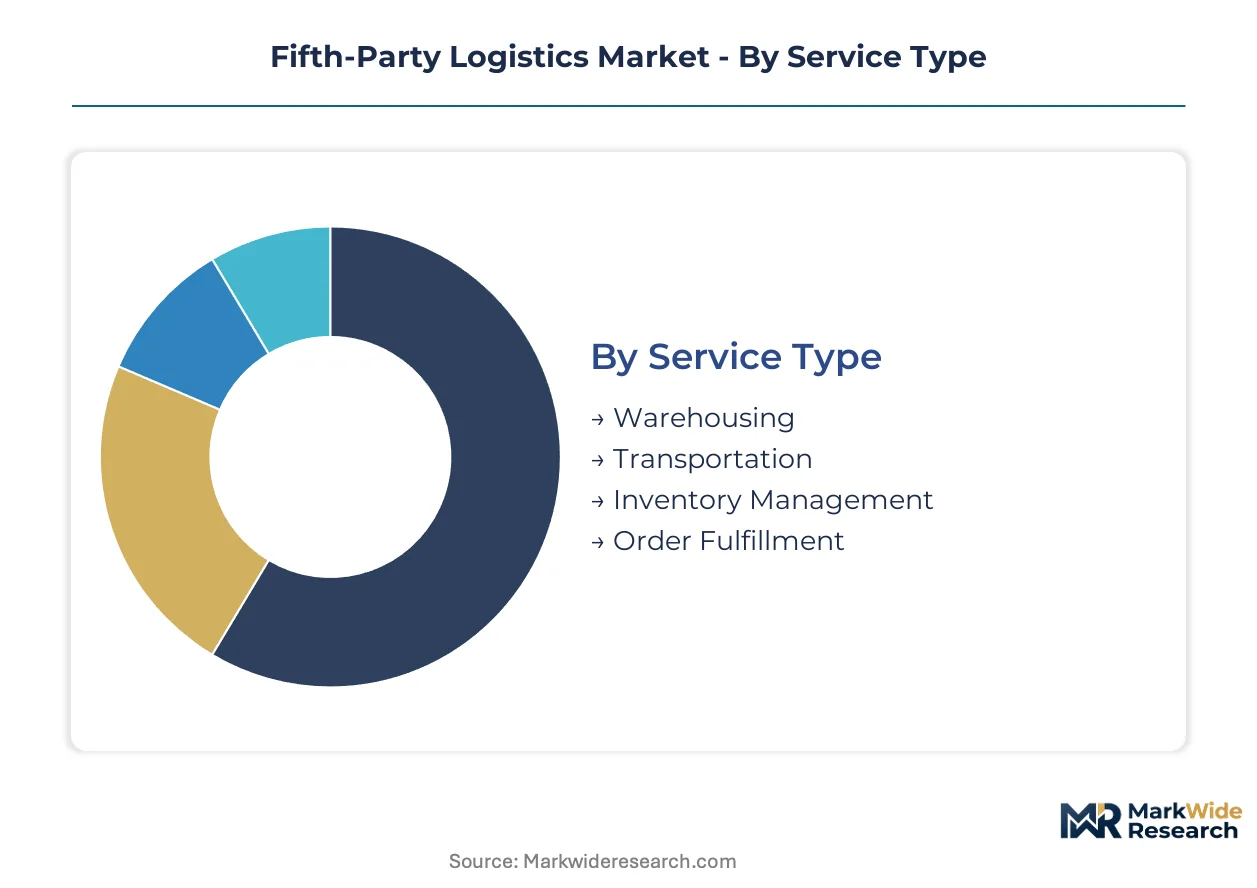
Segmentation in fifth-party logistics reveals how orchestration value concentrates across service layers and technology stacks. Understanding these partitions exposes where platform investments generate measurable network-effect returns versus commoditized execution.
Service Type:
Transportation commands the largest margin pool through dynamic routing algorithms and subcontractor arbitrage, while inventory management modules capture expanding software-as-a-service premiums.
- Warehousing:Physical storage orchestration spans ambient, temperature-controlled, and bonded facilities coordinated through WMS APIs. Demand clusters in the Rhine-Ruhr corridor where dense manufacturing clusters require real-time synchronization across tiered supplier networks.
- Transportation:Multi-modal freight procurement and dynamic carrier matching constitute the revenue anchor, leveraging algorithmic load consolidation across fragmented European trucking bases. Pharmaceutical cold chain networks in Germany and the Netherlands expand reliance on 5PL orchestrators for temperature-sensitive distribution.
- Inventory Management:Safety-stock optimization and demand-sensing algorithms drive fastest expansion as retailers adopt AI-driven replenishment without capital-intensive WMS upgrades.
- Order Fulfillment:Last-mile orchestration and returns-loop coordination complete the service stack, with micro-fulfillment configurations gaining traction among urban e-commerce operators.
Transportation holds installed capacity. Inventory Management is rotating up the share rankings.
Deployment Model:
Cloud-based architectures concentrate growth capital as manufacturers demand elastic compute for demand-sensing algorithms without infrastructure commitments.
- Cloud-based:API-first platforms provision orchestration software through subscription models, eliminating capital expenditure for shippers. E-commerce customer types pull providers toward scalable micro-fulfillment configurations.
- Hybrid:Split architectures combine private control-tower instances with public cloud burst capacity for seasonal demand spikes. Automotive OEMs in Bavaria embed these models directly into MES layers for supplier-managed inventory.
- On-premises:Legacy dedicated installations persist in defense and pharmaceutical verticals with stringent data sovereignty requirements.
- Dedicated:Single-tenant infrastructure deployments serve large manufacturers requiring isolated network stacks for competitive confidentiality.
Cloud-based deployment captures the steepest expansion trajectory. Hybrid models are climbing fastest among mid-market manufacturers.
Customer Type:
Margin accretion varies sharply by buyer sophistication, with e-commerce platforms paying premiums for real-time visibility while manufacturers negotiate on total landed cost.
- E-commerce:Pure-play digital retailers demand micro-fulfillment network design and returns-loop integration, accepting premium pricing for closed-loop visibility. Urban last-mile densification creates white space for specialized orchestrators.
- Manufacturers:Industrial shippers prioritize total landed cost reduction and service-level consistency, particularly in automotive and pharmaceutical verticals. German chemical manufacturers consolidate vendor panels to providers with pre-certified hazardous-materials modules.
- Retailers:Omnichannel operators require AI-driven safety-stock optimization across distributed inventory pools.
- Distributors:Wholesale intermediaries seek subcontractor fleet optimization under strict driver-hours compliance regimes.
Manufacturers hold installed capacity. E-commerce is rotating up the share rankings.
Technology:
Artificial Intelligence and Big Data Analytics concentrate venture investment, while IoT sensor networks and blockchain traceability mature toward baseline infrastructure.
- Artificial Intelligence:Machine learning models power demand-sensing algorithms and predictive routing engines that restructure network self-coordination. Talent scarcity for hybrid supply chain and ML expertise constrains European deployment velocity.
- Big Data Analytics:Real-time visibility dashboards aggregate telemetry across multi-tier supplier networks, compressing coordination costs that legacy EDI systems cannot match.
- IoT:Sensor networks provide temperature and location telemetry for pharmaceutical cold chain compliance, with EU Green Deal emissions mandates accelerating platform investments in carbon tracking.
- Blockchain:Distributed ledger architectures enable ECHA-compliant chemical substance tracking for REACH documentation requirements.
Big Data Analytics holds installed capacity. Artificial Intelligence is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity shapes 5PL adoption patterns across major economies. Germany's pharmaceutical exports and China's manufacturing output create divergent orchestration requirements. The Netherlands' port logistics and India's e-commerce expansion complete the demand matrix.
Germany
Pharmaceutical cold chain exports to Asia and North America drive demand for temperature-controlled orchestration. The KBA enforces strict driver-hours compliance that 5PL networks must algorithmically optimize across subcontractor fleets. The Rhine-Ruhr corridor anchors dense manufacturing clusters requiring real-time inventory synchronization across tiered supplier networks.
United States
E-commerce fulfillment velocity and automotive supplier networks generate parallel orchestration requirements. The FDA's pharmaceutical distribution security mandates compel serialization tracking integration into 5PL platforms. The Midwest manufacturing belt and California tech corridors concentrate demand for cloud-based deployment models.
China
Dual carbon goals and manufacturing export consolidation reshape logistics procurement criteria. The MEE's emissions reporting requirements for transport operators accelerate platform investments in carbon tracking tools. The Yangtze River Delta and Pearl River Delta manufacturing clusters deploy AI-driven safety-stock optimization across fragmented supplier bases.
Netherlands
Rotterdam port throughput and pharmaceutical distribution hubs create multimodal orchestration demand. REACH documentation requirements for chemical-handling workflows favor providers with integrated customs capabilities. The Randstad logistics corridor concentrates 5PL platform deployment for EU-wide distribution networks.
India
Domestic e-commerce expansion and pharmaceutical export growth drive cloud-based orchestration adoption. The PLI scheme for manufacturing incentivizes supply chain digitization among contract manufacturers. The Maharashtra and Gujarat industrial corridors deploy micro-fulfillment configurations for urban last-mile densification.
Fifth-Party Logistics Market Vendor Landscape
Concentration sits with integrated logistics conglomerates and specialized consulting firms. The market structure spans asset-heavy operators, technology-first platforms, and advisory-driven orchestrators. Three archetypes dominate: proprietary control-tower providers, digital freight-matching platforms, and strategy-consulting hybrids. Competitive moves center on API-first integration partnerships and embedded carbon-accounting capabilities.
Within the integrated logistics tier, DHL Supply Chain and Kuehne + Nagel represent established European anchors with proprietary network architectures. C.H. Robinson occupies a position exemplifying North American digital freight-matching scale. Among advisory-driven operators, Bain & Company and Boston Consulting Group sit within the strategy-consulting hybrid archetype, embedding supply chain design into broader transformation mandates.
| Leading Market Players |
|---|
| 5PL Logistics Solutions LLC |
| DHL Supply Chain |
| Toll Holdings Ltd |
| Kuehne + Nagel |
| C.H. Robinson |
| XPO Logistics |
| Maine Pointe |
| Bain & Company |
| Boston Consulting Group |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emissions mandates gate both platform qualification and price differentiation simultaneously, compelling shippers to pay premiums for orchestrators with embedded carbon-accounting APIs while disqualifying spreadsheet-dependent brokers from pharmaceutical and automotive contract panels.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing stratified across premium, standard, and economy tiers differentiated by API integration depth and real-time visibility granularity. Price differentiation hinges on ISO 27001 certification tier and embedded AI routing capability. Cost compression in the standard tier intensifies as cloud infrastructure commoditizes, while pharmaceutical manufacturers show least price sensitivity for REACH-compliant hazardous-materials modules.
Supply Chain Analysis
Inventory velocity and lead-time compression requirements concentrate platform development talent in Germany, the Netherlands, and the United States. Software engineering draws from cloud-computing hubs in Ireland and India. Single-source vulnerability sits with proprietary WMS-TMS-ERP trilateral integration stacks. Distribution runs through API-first orchestration layers rather than traditional freight brokerage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where embedded compliance workflows create switching costs that commodity brokers cannot replicate.
For Market Incumbents: Compound platform stickiness by deepening backward integration into proprietary IoT sensor networks for cold chain verification, and accelerate TISAX certification investment to extend automotive sales cycles from threat exposure. Capacity addition in the Rhine-Ruhr corridor captures manufacturing cluster density. For New Entrants and Emerging Players: Returns-loop integration for apparel and electronics retailers represents the most penetrable service layer, as incumbent orchestrators under-serve reverse logistics visibility. Target urban micro-fulfillment configurations in India's Maharashtra industrial corridor, positioning via CSRD-aligned disclosure services as the go-to-market wedge. For Investors and Strategic Acquirers: REACH delegated acts on chemical substance tracking reshape the acquisition landscape toward providers with pre-certified hazardous-materials modules. Long-term viability centers on platform orchestrators with embedded data-science capabilities rather than asset-heavy operators. Watch for API-native visibility mandates from automotive OEMs in Bavaria as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Automotive OEMs in Baden-Württemberg embed 5PL layers directly into MES systems for supplier-managed inventory. |
| Carbon-Accounting API Development | EU Green Deal delegated acts compel shippers to replace spreadsheet tracking with embedded emissions verification tools. |
| Micro-Fulfillment Network Expansion | E-commerce operators in India's Gujarat corridor deploy dark-store synchronization for urban last-mile densification. |
| REACH Compliance Module Certification | German chemical manufacturers consolidate vendor panels to orchestrators with ECHA-compliant workflow engines. |
| AI-Driven Safety-Stock Optimization | Retailers adopt elastic cloud compute for demand-sensing algorithms without capital-intensive WMS infrastructure. |
Methodological Framework
A spread of perspectives from 5PL platform engineers, pharmaceutical supply chain directors, automotive procurement leads, and EU regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from ECHA substance tracking databases, KBA enforcement records, SEC filings of listed logistics providers, and EU delegated act texts. Bottom-up service-type segmentation triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled encompass service type, deployment architecture, customer vertical, and technology stack intensity across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves and replacement-cycle timing. Forecast inputs incorporated pharmaceutical cold chain expansion rates and e-commerce fulfillment velocity benchmarks.
Forecasts assume regulatory continuity in EU Green Deal implementation and REACH enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market