
 AD-Blocking Software Market | 2026-2036
AD-Blocking Software Market Size, Share, and Industry Trends Forecast 2026-2036
AD-Blocking Software Market Insights
Fragmentation across enterprise security buyers is repositioning how AD-blocking vendors allocate engineering resources and sales coverage. Adblock Plus leverages its filter-list ecosystem to sustain developer mindshare among technically sophisticated users. Ghostery competes on privacy-dashboard depth, while AdGuard anchors its position through cross-platform browser and DNS-layer integration.
AD-blocking software comprises client-side or network-intercept programs that filter HTTP requests, DOM elements, or DNS resolutions against curated rule sets to suppress advertising content, tracking pixels, and malvertising payloads. The technology operates through pattern-matching engines, subscription-based filter lists, and increasingly machine-learning classifiers that identify ad-serving infrastructure without explicit domain blacklisting. Browser Extension deployments retain the largest installed base, though margin pools are shifting toward SaaS-delivered Network-Level Solutions where recurring revenue and multi-tenant management consoles command stronger unit economics. Enterprise end-user contracts represent the fastest-expanding structural segment as CISOs bundle ad-blocking into zero-trust architecture procurement, while Individual Users remain the most price-sensitive cohort with limited willingness to migrate beyond free tiers.
The European Commission's Digital Services Act and GDPR, enforced by national data protection authorities including France's CNIL and Germany's BfDI, are mandating algorithmic transparency in content filtering and restricting cross-border data flows that underpin behavioral advertising. These frameworks elevate compliance burdens for vendors but simultaneously expand addressable demand among risk-averse enterprise purchasers. Stakeholders must monitor evolving interpretations of platform liability across German, French, and US regulatory regimes to anticipate whether interoperability mandates will force operating-system-level ad-blocking APIs.
Market Dynamics
Enterprise CISOs are consolidating endpoint security procurement into bundled zero-trust contracts, forcing ad-blocking vendors to reposition from consumer browser extensions toward network-layer SaaS architectures with multi-tenant management consoles.
Growth Catalysts
- GDPR enforcement by Germany's BfDI:Investigations into ad-tech data practices are accelerating corporate adoption of DNS-level blocking solutions across DAX-listed enterprises.
- Malvertising payload sophistication:Financial services and healthcare end-users are deploying client-side filters to intercept malicious creative assets before browser rendering.
- Filter-list machine learning:Pattern-matching engines trained on ad-serving infrastructure signatures are reducing dependency on manually curated domain blacklists.
Market Restraints
- Acceptable Ads program friction:Whitelist fee structures create revenue conflicts that erode trust among privacy-conscious user segments and complicate vendor positioning.
- Platform API restrictions:Apple's WebKit extension limitations and Mozilla's manifest v3 enforcement are constraining filter-rule granularity on Safari and Firefox deployments.
- Cross-border data flow restrictions:GDPR Article 44 transfer mechanisms are complicating cloud-hosted filter-list synchronization for vendors with EU-based enterprise clients.
Strategic Opportunities
- Enterprise SaaS pivot:Recurring-revenue network solutions with centralized policy consoles are capturing procurement budgets previously allocated to perimeter firewalls.
- Router-integrated DNS filtering:OEM partnerships with Wi-Fi hardware manufacturers are embedding blocking capabilities at the network edge for unmanaged device fleets.
- EU Digital Services Act transparency mandates:Algorithmic disclosure requirements are creating compliance-driven demand for auditable filtering architectures among platform operators.
Industry Challenges
- Filter-list maintainer talent scarcity:Specialized expertise in adversarial pattern recognition and evasion-countermeasure development commands premium compensation in competitive labor markets.
- Multi-platform rendering engine fragmentation:Chromium, Gecko, and WebKit divergence forces vendors to maintain separate filter-injection codebases, inflating QA overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AD-Blocking Software Market |
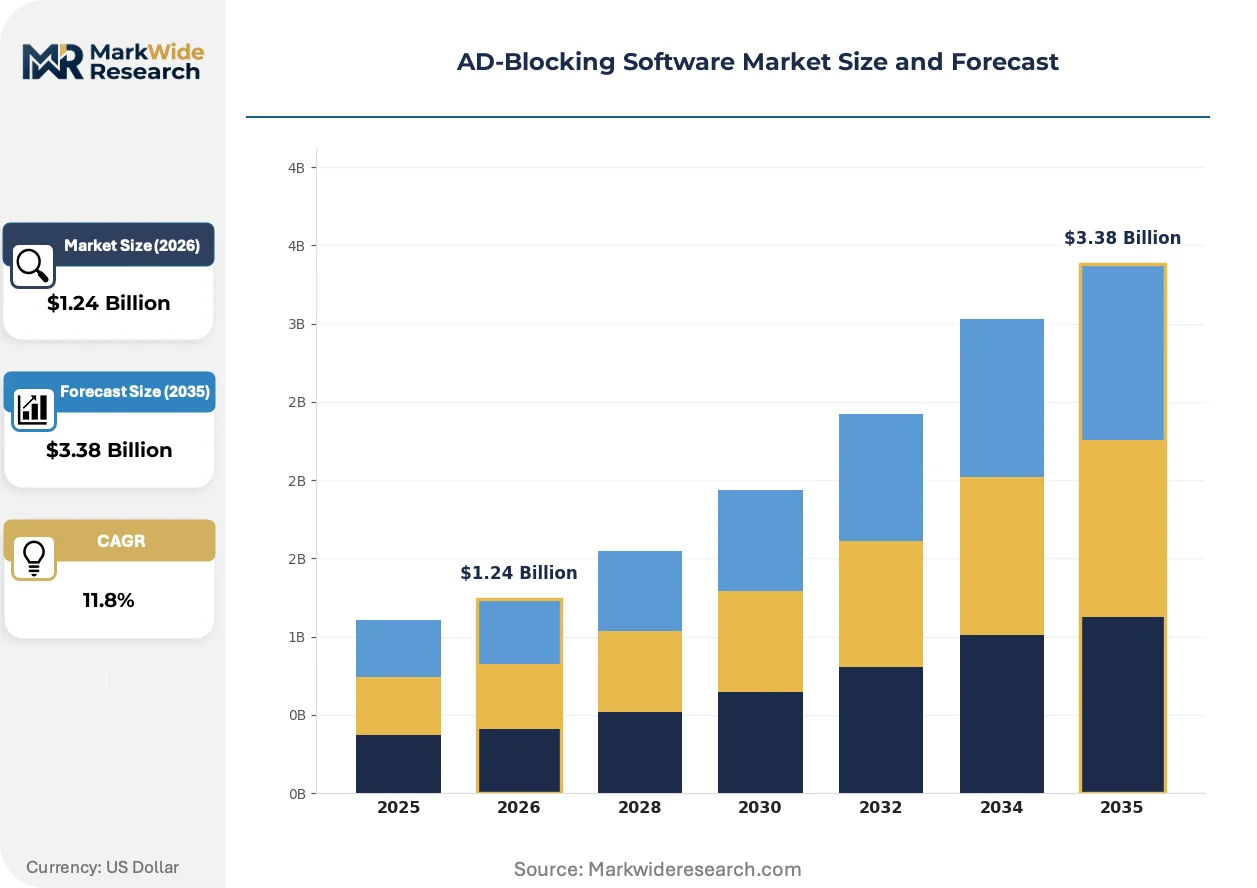
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $3.38 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Browser Extension, Mobile App, Standalone Software, Network-Level Solution End User: Individual Users, Small Businesses, Enterprises, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Technology: Machine Learning, Heuristic Filtering, Blacklist/Whitelist, Content Blocking |
| Companies Covered | Adblock Plus, AdGuard, uBlock Origin, AdBlock, Ghostery, AdLock, Blokada, AdClear, Privacy Badger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AD-Blocking Software Market Trends and Innovations
Filtering architectures are migrating from signature-based domain blacklists toward behavioral inference models that identify ad-serving patterns without explicit list curation, compressing latency while expanding coverage.
On-device machine learning classifiers are electrifying how endpoint agents identify advertising content. These models analyze DOM structure, resource loading sequences, and canvas fingerprinting attempts in real time. Enterprise security teams are piloting these capabilities within zero-trust endpoint agents. The technology is electrifying competitive positioning by enabling blocking efficacy without centralized list infrastructure that creates compliance audit trails.
France's CNIL has intensified enforcement of GDPR Article 82 regarding cookie consent mechanism validity. The regulator's penalty precedents are compelling publishers to adopt less intrusive monetization models. French media groups are responding by accelerating server-side ad insertion deployments that bypass client-side filters entirely.
Security-conscious buyers are unbundling ad-blocking from bundled endpoint suites and procuring standalone solutions with dedicated privacy dashboards. Channel partners in Germany and the Netherlands are building specialized practices around these discrete procurement cycles. This pattern is most visible among mid-market financial services firms with dedicated data protection officers.
AD-Blocking Software Market Segmentation
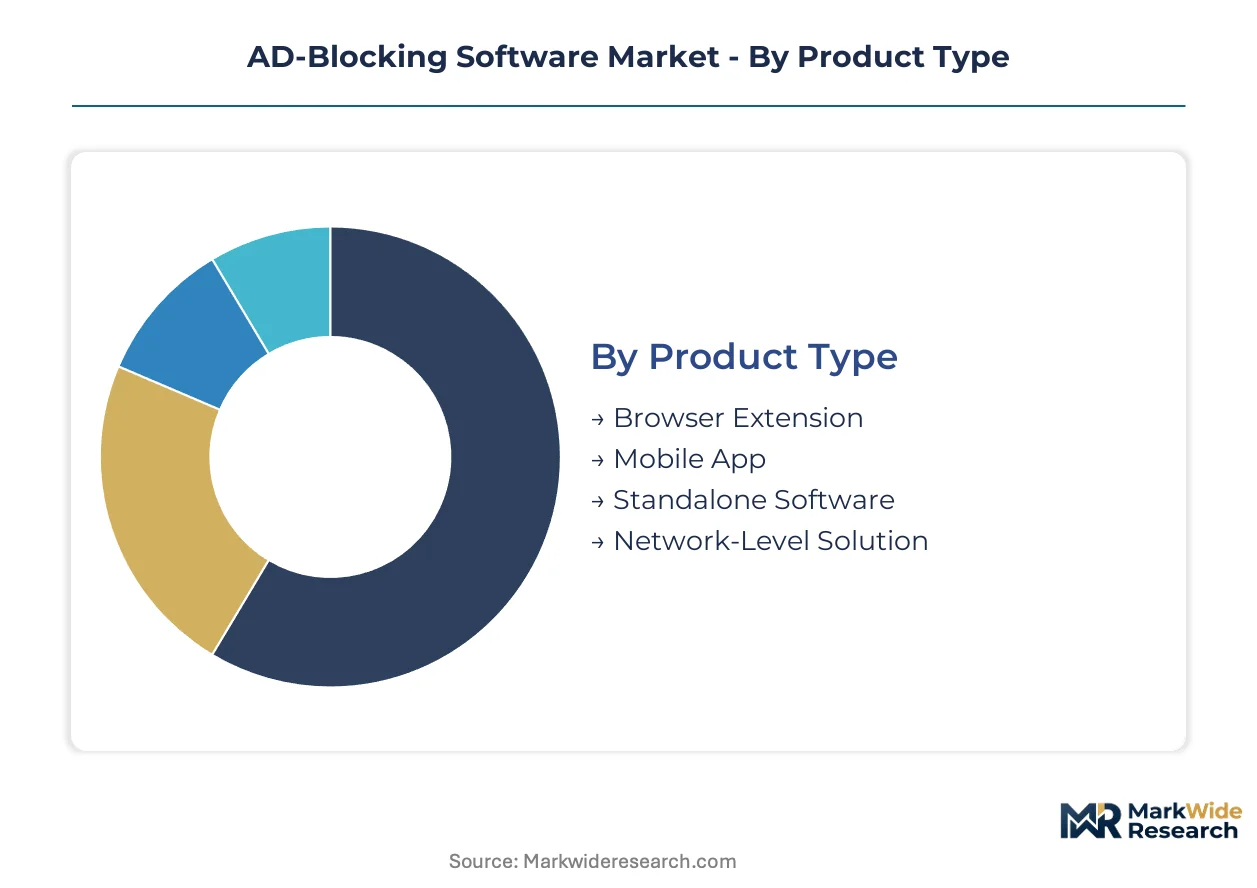
Segmentation in the AD-blocking software market determines vendor resource allocation across divergent technical architectures and buyer procurement patterns. Each dimension carries distinct margin profiles, compliance burdens, and integration complexity that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across product architectures, with network-level infrastructure demanding substantial upfront engineering investment while browser extensions leverage existing platform APIs.
- Browser Extension:Lightweight client-side modules inject filtering rules directly into rendering engines through extension APIs. Individual users in Germany and France drive installed base volume, though manifest v3 restrictions on Chromium and WebKit are constraining rule-set granularity and forcing vendors toward declarative filtering models.
- Network-Level Solution:DNS-intercept or proxy-based architectures filter traffic before endpoint arrival, requiring server infrastructure and TLS certificate management. Enterprise procurement teams in financial services and healthcare concentrate demand here, drawn by centralized policy enforcement and audit logging that satisfies GDPR Article 32 security requirements.
- Mobile App:System-level VPN or local DNS configurations extend blocking to iOS and Android environments. Limited OS API access elevates development cost relative to desktop counterparts.
- Standalone Software:Desktop applications with independent rendering pipelines. Niche positioning among privacy-conscious technical users unwilling to trust browser extension permissions.
Most installed capacity flows through Browser Extension deployments. Expansion is steepest in Network-Level Solution architectures as CISOs consolidate zero-trust procurement.
End User:
Buyer sophistication and procurement scale segment the market into divergent pricing tolerance and contract structures.
- Enterprises:Multi-year contracts with centralized deployment and compliance reporting. German DAX-listed corporations and French banking groups anchor demand, responding to BfDI and CNIL enforcement actions that elevate ad-tech data practices to board-level risk registers.
- Individual Users:Price-sensitive adopters with near-zero willingness to pay beyond freemium tiers. Filter-list community contributions sustain product value without direct revenue capture.
- Small Businesses:Managed service attachments through MSP channel partners. Limited IT staffing drives preference for SaaS-delivered consoles with minimal configuration overhead.
- Educational Institutions:Procurement through regional education authorities with standardized security mandates. Budget constraints favor bundled endpoint suite inclusion over standalone solutions.
Enterprise contracts generate the highest per-seat revenue. Small Business adoption is climbing fastest as channel partners build specialized practices.
Deployment:
Delivery model selection trades operational control against infrastructure burden and update velocity.
- SaaS:Vendor-hosted filtering infrastructure with browser-based management consoles. German and Dutch mid-market firms prefer this model for GDPR Article 28 processor agreement simplicity and rapid filter-list synchronization without on-premises maintenance.
- Cloud-Based:Enterprise-controlled cloud tenancy with dedicated instance isolation. Financial services buyers in Frankfurt and Paris demand this architecture for data residency and encryption key custody.
- Hybrid:Split processing between edge nodes and central policy engines. Balances latency performance against centralized logging requirements.
- On-Premises:Air-gapped or sovereign-cloud deployments for classified environments. Highest capital expenditure and staffing commitment.
SaaS deployments dominate new contract volume. Cloud-Based configurations are expanding most quickly among regulated industries.
Technology:
Detection methodology determines efficacy against evasion techniques and computational overhead on endpoint resources.
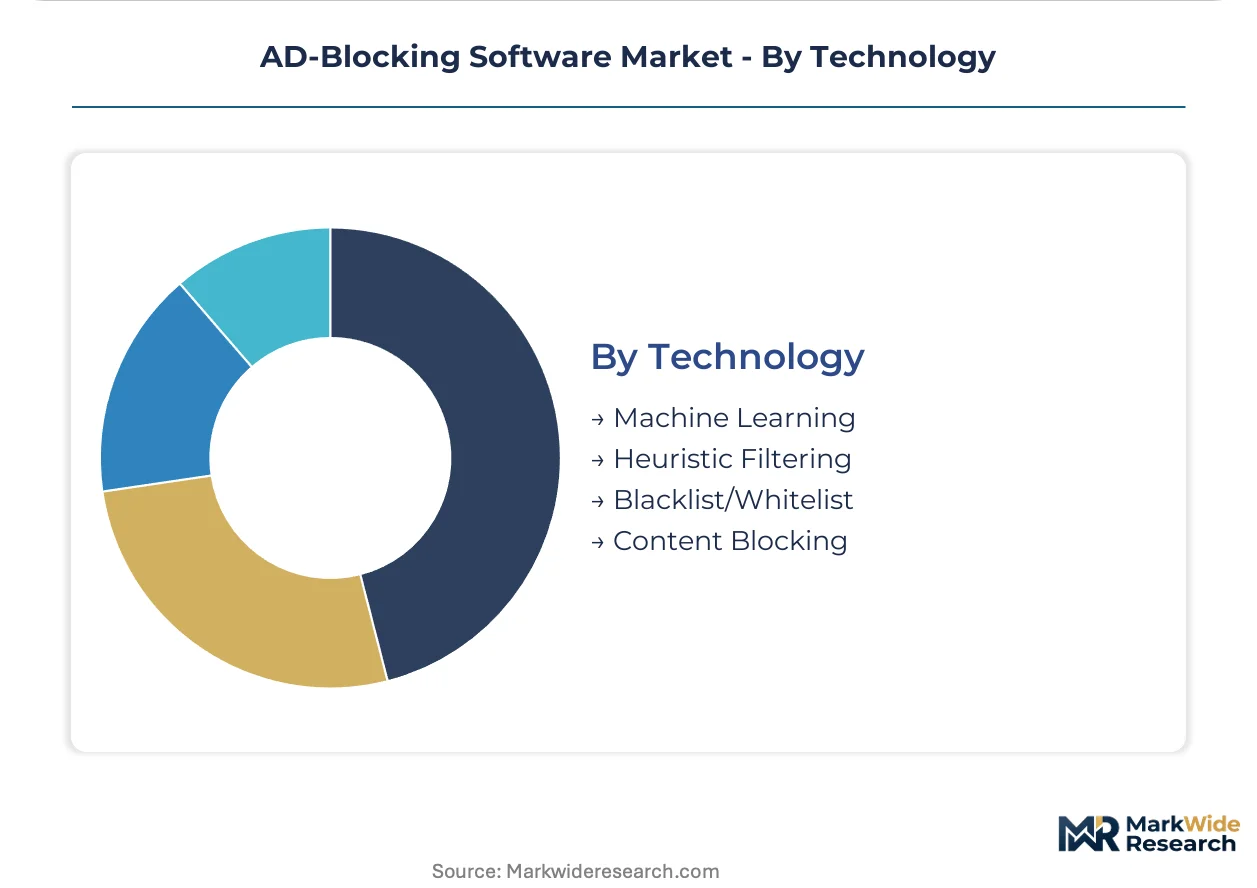
- Machine Learning:On-device classifiers analyze DOM structure, resource loading patterns, and canvas fingerprinting attempts without centralized list dependency. Enterprise security teams pilot these within zero-trust endpoint agents to reduce compliance audit surface area.
- Heuristic Filtering:Rule engines detect ad-serving patterns through behavioral signatures rather than domain enumeration. Lower latency than list-based approaches but higher false-positive rates on dynamically obfuscated content.
- Blacklist/Whitelist:Curated domain and element selectors maintained by distributed filter-list communities. Foundation of browser extension efficacy but vulnerable to rapid infrastructure rotation by ad-tech operators.
- Content Blocking:Pattern-matching against creative asset signatures and script injection behaviors. Effective against malvertising payloads but requires frequent signature updates.
Blacklist/Whitelist foundations retain the largest installed base. Machine Learning integration is gaining share fastest as vendors differentiate on reduced infrastructure dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data protection specialists in Germany's BfDI enforcement division anchor the regulatory talent pool reshaping corporate procurement patterns across Europe. Privacy engineering clusters in Berlin and Munich concentrate vendor development resources responding to compliance-driven demand.
Germany
Bundesdatenschutzbehörde investigations into ad-tech data practices drive DAX-listed enterprises toward DNS-level blocking solutions. GDPR Article 82 enforcement creates procurement urgency among Frankfurt financial institutions. Berlin's privacy-tech startup cluster attracts filter-list engineering talent from across the EU.
United States
CISOs at healthcare systems and financial services firms bundle ad-blocking into zero-trust architecture contracts. FTC scrutiny of cross-border data transfers elevates compliance review for SaaS-delivered filtering vendors. Silicon Valley engineering teams develop on-device machine learning classifiers for endpoint deployment.
France
CNIL intensifies cookie consent mechanism enforcement under GDPR Article 82, compelling publishers toward server-side ad insertion. Paris-based media groups accelerate infrastructure bypassing client-side filters. Lyon cybersecurity consultancies build specialized practices around discrete ad-blocking procurement.
United Kingdom
Post-Brexit data adequacy negotiations complicate cloud-hosted filter-list synchronization for vendors serving EU enterprise clients. London financial services procurement teams demand dedicated privacy dashboards unbundled from endpoint suites. Manchester MSP channel partners expand small business attachment sales.
Netherlands
Amsterdam's data protection authority aligns enforcement with Brussels transparency mandates under the Digital Services Act. Dutch mid-market firms prefer SaaS-delivered consoles for GDPR Article 28 processor agreement simplicity. Eindhoven router manufacturers embed DNS filtering capabilities through OEM partnerships.
AD-Blocking Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across browser extension, network-level, and mobile deployment architectures. The vendor base spans three strategic tiers: open-source community projects sustaining filter-list ecosystems, cross-platform integrators anchoring enterprise SaaS pivots, and privacy-dashboard specialists differentiating on transparency depth. Dominant competitive moves include M&A consolidation of network-layer infrastructure capabilities and strategic partnerships embedding DNS filtering into Wi-Fi hardware OEM channels.
Within the cross-platform integration tier, AdGuard and Adblock Plus exemplify archetypes competing for enterprise procurement budgets, while Ghostery occupies a position among privacy-dashboard specialists targeting security-conscious individual users. These named entities represent distinct engineering resource allocation patterns visible across the competitive set: AdGuard anchors multi-tenant management console development, Adblock Plus sustains developer mindshare through filter-list ecosystem maintenance, and Ghostery concentrates investment on algorithmic transparency interfaces responding to EU regulatory mandates.
| Leading Market Players |
|---|
| Adblock Plus |
| AdGuard |
| uBlock Origin |
| AdBlock |
| Ghostery |
| AdLock |
| Blokada |
| AdClear |
| Privacy Badger |
| Others |
Pricing and Supply Chain Analysis
EU Digital Services Act transparency mandates gate both qualified supply and premium-tier pricing access, compelling vendors to embed auditable filtering architectures that satisfy German BfDI and French CNIL enforcement before commanding enterprise SaaS rates. Compliance engineering costs concentrate margin capture among vendors with pre-existing network-layer infrastructure, while price-sensitive individual users remain stranded in freemium browser extensions with limited vendor investment.
Pricing Analysis
Bundled endpoint security suites versus unbundled standalone solutions split pricing power across buyer segments. Three-tier pricing structure across premium, standard, and economy levels dominates enterprise SaaS contracts, with GDPR Article 28 processor agreement complexity and multi-tenant management console depth driving differentiation. Cost compression in individual user tiers intensifies because filter-list community contributions sustain product value without direct revenue capture. Enterprise CISOs demonstrate least price sensitivity, while individual users in Germany and France resist migration beyond free tiers.
Supply Chain Analysis
Filter-list engineering talent scarcity in Berlin and Munich clusters elevates recruitment costs for vendors maintaining adversarial pattern recognition capabilities. Software development concentrates in Germany, the United States, and Estonia, with cloud infrastructure provisioning drawing from AWS Frankfurt, Azure Paris, and Amsterdam-based sovereign hosting providers. Single-source vulnerability in machine learning training data pipelines poses structural risk as on-device classifier development hinges on limited adversarial example datasets. Distribution runs through direct enterprise sales teams in Frankfurt and Paris, MSP channel partners in Manchester and Amsterdam, and OEM router integrations via Eindhoven hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AD-blocking software market functions as a stable compounder, with regulatory enforcement of GDPR Article 82 and the Digital Services Act generating durable procurement tailwinds across European enterprise segments. Compliance-driven replacement cycles sustain recurring revenue visibility for vendors with established network-layer architectures.
For Market Incumbents: Hedge against platform API restrictions by accelerating DNS-layer SaaS development that circumvents browser extension manifest v3 constraints. Acquire specialized filter-list engineering teams in Berlin and Munich to defend talent moats against emerging entrants. Vertical integration into router OEM partnerships secures network-edge positioning before mid-market competitors replicate Eindhoven distribution channels. For New Entrants and Emerging Players: On-device machine learning classifiers offer a technology-first wedge into enterprise zero-trust procurement cycles seeking reduced compliance audit surface area. Small business MSP channels in the Netherlands and United Kingdom present the most penetrable white-space, with limited incumbent presence below DAX-listed enterprise scale. Go-to-market execution through Lyon cybersecurity consultancies specializing in discrete ad-blocking procurement accelerates credibility among French mid-market financial services. For Investors and Strategic Acquirers: Roll-up economics work for network-layer infrastructure specialists because enterprise procurement consolidation into zero-trust bundles favors vendors with centralized policy consoles and GDPR Article 32 audit capabilities. Long-term viability across the analysis window rests on recurring-revenue SaaS models displacing perpetual license browser extensions. Acquisition targets should demonstrate proven BfDI or CNIL compliance engagements. The signal to watch is server-side ad insertion adoption rates among French media groups, which would compress client-side filter efficacy and trigger architecture pivots.| Strategic Initiative | Industry Significance |
|---|---|
| Network-Layer SaaS Pivot | Captures CISO procurement budgets consolidating endpoint security into zero-trust architecture contracts. |
| Router OEM Partnership | Embeds DNS filtering at network edge for unmanaged device fleets via Eindhoven hardware channels. |
| Machine Learning Classifier Development | Reduces dependency on centralized filter-list infrastructure that creates GDPR Article 44 transfer compliance burdens. |
| Filter-List Engineering Acquisition | Consolidates scarce adversarial pattern recognition talent concentrated in Berlin and Munich privacy-tech clusters. |
| GDPR Article 28 Processor Certification | Unlocks German and Dutch mid-market SaaS preference for simplified data controller-processor agreements. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down filter-list ecosystem tracking forms the analytical core of this study. Primary interviews with CISOs at German DAX-listed corporations, French banking group data protection officers, Dutch MSP channel partners, and Berlin-based privacy engineering teams combined with secondary validation against BfDI enforcement disclosures, CNIL penalty precedents, and SEC filings from publicly traded cybersecurity vendors. Top-down triangulation against cloud infrastructure provisioning data and browser extension repository metrics completes the demand-supply reconciliation.
Input-output matrices map deployment model adoption, organization size tiering, vertical industry concentration, integration complexity levels, and regional regulatory cluster patterns across the projection horizon. CAGRs derive from segment-level unit economics modeling and procurement cycle velocity analysis. Machine learning classifier penetration rates and server-side ad insertion infrastructure deployment serve as industry-specific forecast inputs alongside GDPR enforcement intensity indices.
The model holds under sustained regulatory enforcement of GDPR Article 82 and Digital Services Act transparency mandates; deviation in platform API restriction severity or cross-border data adequacy negotiations would shift enterprise architecture preferences and vendor competitive positioning. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Website Monitoring Software Market
Security Software
Global Password Management Software Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Data Privacy Software Market
Security Software
Global Network Encryption Market
Security Software
BYOD Security Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Smart Video Doorbell Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Software Defined Perimeter (SDP) Market
Security Software
Decentralized Identity Software Market
Security Software
Anomaly Detection Tools Market
Security Software
Global Optical Encryption Market
Security Software
Data Leakage Prevention Product Market
Security Software
Door Phone Market