
 Asia-Pacific Fraud Detection & Prevention Market | 2026-2036
Asia-Pacific Fraud Detection & Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fraud Detection & Prevention Market Insights
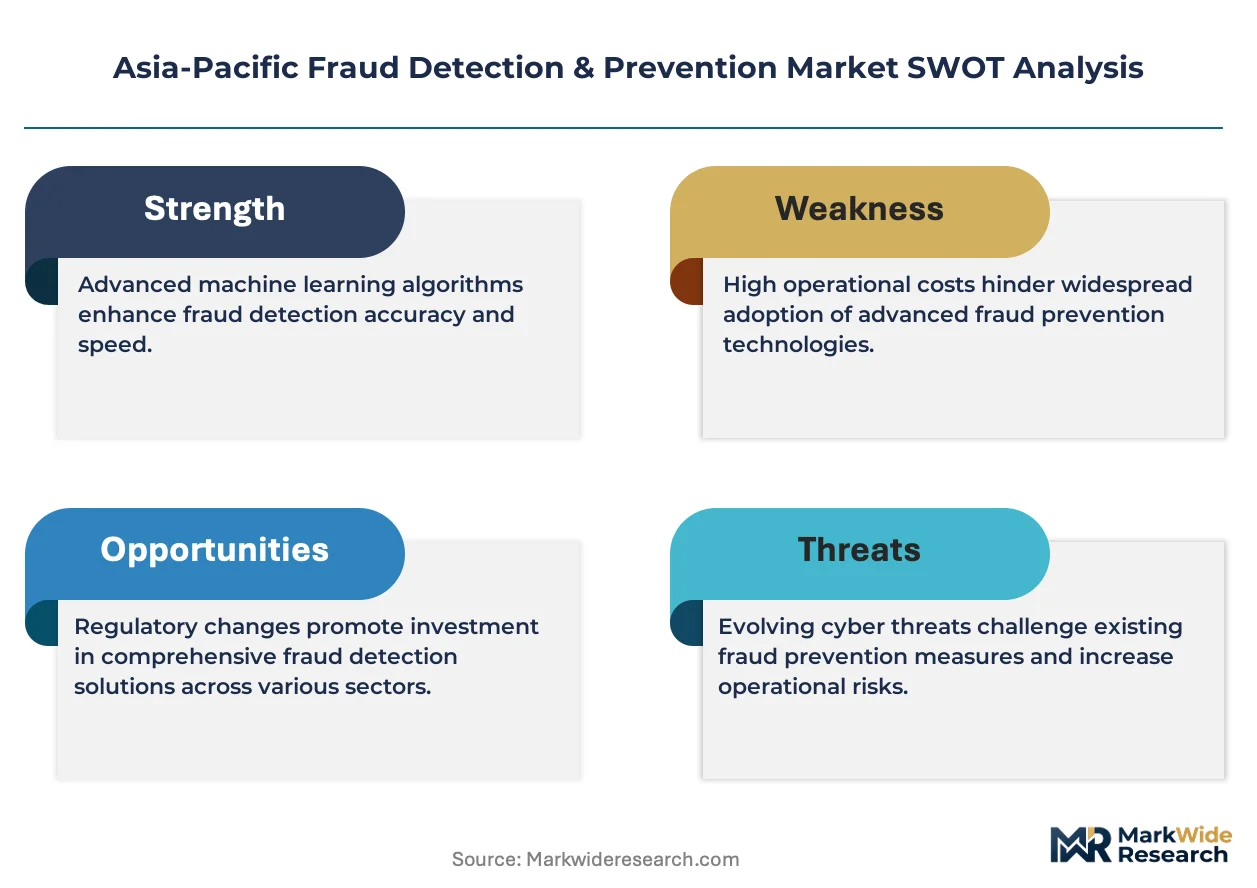
Data science talent scarcity across Singapore and Sydney is reorganizing vendor delivery models and forcing platform providers to localize engineering centers. IBM Corporation leverages its regional cloud infrastructure to embed fraud analytics within core banking stacks. Oracle Corporation anchors its position through database-level integration that reduces latency for real-time scoring. SAS Institute Inc. competes on statistical modeling depth for insurance underwriting fraud.
Fraud detection and prevention encompasses software systems, algorithms, and analytical workflows engineered to identify, verify, and intercept deceptive transactions, synthetic identities, and anomalous behavioral patterns before financial loss occurs. These systems process structured and unstructured data streams through rule engines, statistical models, and neural networks to generate risk scores that trigger automated holds, step-up authentication, or manual review queues. Behavioral analytics and identity verification solutions command the deepest margin pools as banks absorb premium pricing for biometric liveness detection and device fingerprinting. Cloud-based deployment models are expanding fastest among mid-tier e-commerce platforms in Indonesia and Vietnam that lack capital for on-premises infrastructure.
India's RBI mandates transaction monitoring standards for payment system operators, while Australia's APRA enforces CPS 234 requirements for information security capability that directly shape procurement specifications. Singapore's MAS Technology Risk Management Guidelines and Hong Kong's HKMA Fraud Risk Management Circular collectively push financial institutions toward AI-augmented detection layers with explainable output requirements. Stakeholders must weigh regulatory divergence against platform standardization when architecting multi-jurisdiction fraud stacks.
Market Dynamics
Real-time payment infrastructure rollouts across Southeast Asia are compressing fraud detection latency requirements from batch-based overnight scoring to sub-200 millisecond decisioning, forcing vendors to re-architect platform architectures around edge computing nodes.
Growth Catalysts
- India's RBI Digital Payment Security Framework:Mandated multi-factor authentication and transaction monitoring standards for payment system operators are accelerating procurement of behavioral analytics platforms by neobanks and UPI aggregators.
- Biometric liveness detection:Device fingerprinting and facial liveness engines command premium pricing as Australian banks absorb 40-60% cost premiums for anti-spoofing capabilities in mobile banking applications.
- Singapore-Sydney talent corridor:Data science scarcity is reorganizing vendor delivery models and forcing platform providers to localize engineering centers with direct university pipeline partnerships.
Market Restraints
- Cloud infrastructure concentration:Mid-tier Indonesian and Vietnamese e-commerce platforms face vendor lock-in risks as hyperscaler availability zones concentrate in Singapore and Sydney, creating cross-border latency and data sovereignty complications.
- Explainable AI mandates:Singapore's MAS Technology Risk Management Guidelines require auditable decision trails that increase model development cycles and constrain neural network architectures for black-box detection systems.
- Legacy core banking integration:COBOL-based transaction processing systems at established Australian and Indian banks create API friction that extends deployment timelines for real-time scoring modules.
Strategic Opportunities
- Vietnam's underpenetrated e-commerce fraud stack:Domestic payment gateways lack sophisticated device intelligence, creating whitespace for behavioral biometrics vendors targeting Shopee and Lazada merchant ecosystems.
- Philippine remittance corridor:OFW payment flows through informal channels present application whitespace for blockchain-anchored identity verification and transaction monitoring solutions.
- Australia's APRA CPS 234:Information security capability requirements are driving bank procurement of AI-augmented detection layers with mandated board-level reporting on fraud risk posture.
Industry Challenges
- Model drift management:Synthetic identity fraud patterns mutate faster than retraining cycles, forcing banks to maintain parallel rule-engine fallbacks that increase operational complexity and false positive rates.
- Cross-jurisdiction explainability standards:Hong Kong's HKMA Fraud Risk Management Circular demands human-interpretable outputs while India's RBI emphasizes automated decisioning, complicating multi-country platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fraud Detection & Prevention Market |
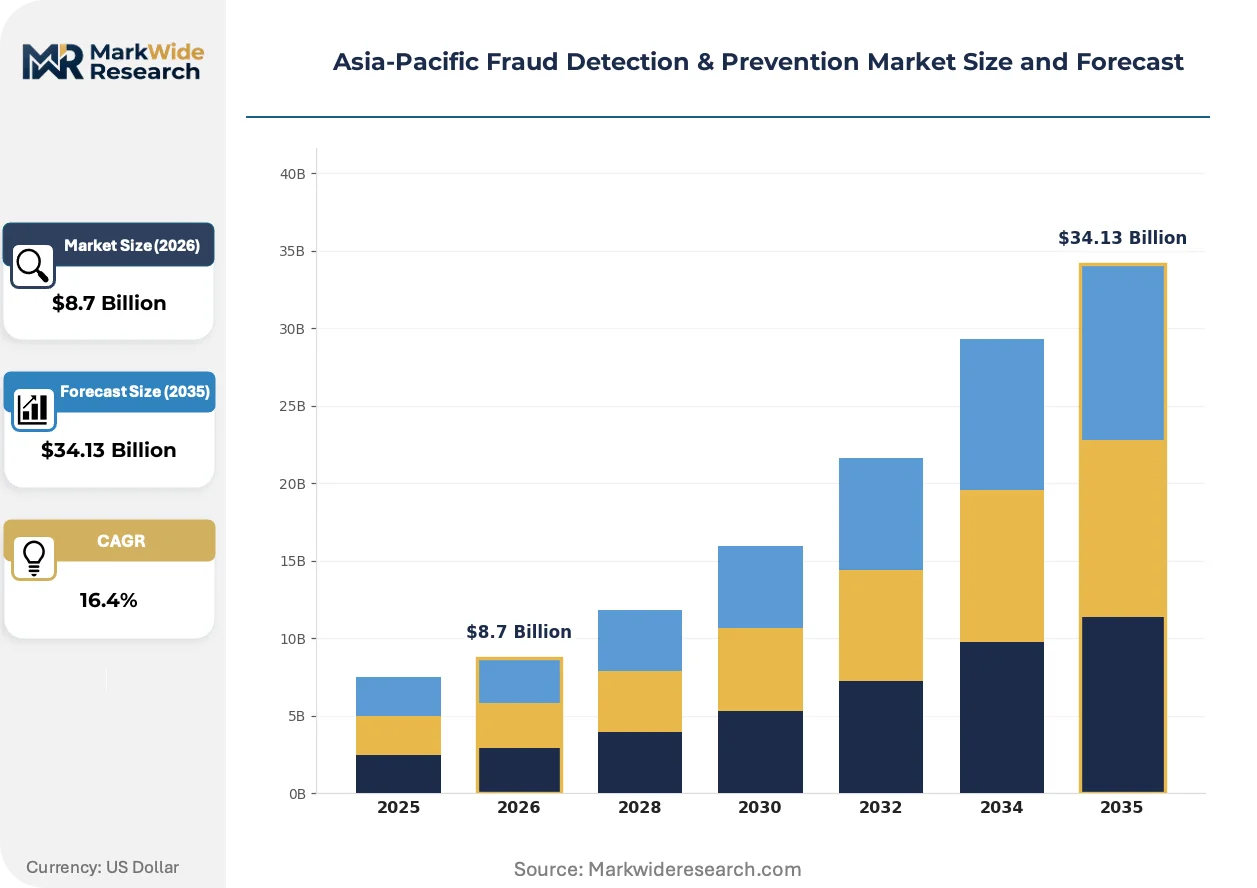
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Behavioral Analytics, Identity Verification, Transaction Monitoring, Case Management Deployment Model: Cloud-based, On-premises, Hybrid, Managed Service End User: Banks, E-commerce, Insurance, Telecom Technology: Machine Learning, Artificial Intelligence, Big Data Analytics, Blockchain |
| Companies Covered | IBM Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., ACI Worldwide Inc, Fiserv Inc, NICE Ltd., BAE Systems PLC, Dell Technologies Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fraud Detection & Prevention Market Trends and Innovations
Neural network architectures for fraud detection are fragmenting between cloud-scale transformer models and lightweight edge-deployed ensembles, with deployment location becoming the primary technical differentiator rather than algorithmic sophistication alone.
Graph neural networks for relationship-based fraud detection is bifurcating vendor roadmaps. Tier-one banks in Australia and Singapore are adopting full-stack graph databases for mule account detection, while mid-tier ASEAN institutions deploy simplified entity-resolution overlays on existing relational warehouses. The technology is compressing time-to-detection for synthetic identity rings from weeks to hours but requires specialized data engineering talent scarce outside Bangalore and Sydney.
Australia's APRA CPS 234 information security standard is tightening third-party risk management obligations for cloud-hosted fraud platforms. Banks must now demonstrate continuous monitoring of vendor security posture, not just point-in-time certification. The regulation is accelerating procurement of software-as-a-service solutions with pre-baked compliance documentation, disadvantaging on-premises deployments at regional Australian banks.
Merchant acquirers in Indonesia and Vietnam are unbundling fraud protection from core processing relationships. E-commerce platforms previously captive to bank-provided scoring are procuring standalone device intelligence and behavioral analytics from specialized vendors. This shift is most visible in Jakarta's fintech corridor, where ride-hailing and food delivery apps now operate multi-vendor fraud stacks with best-of-breed component selection.
Asia-Pacific Fraud Detection & Prevention Market Segmentation
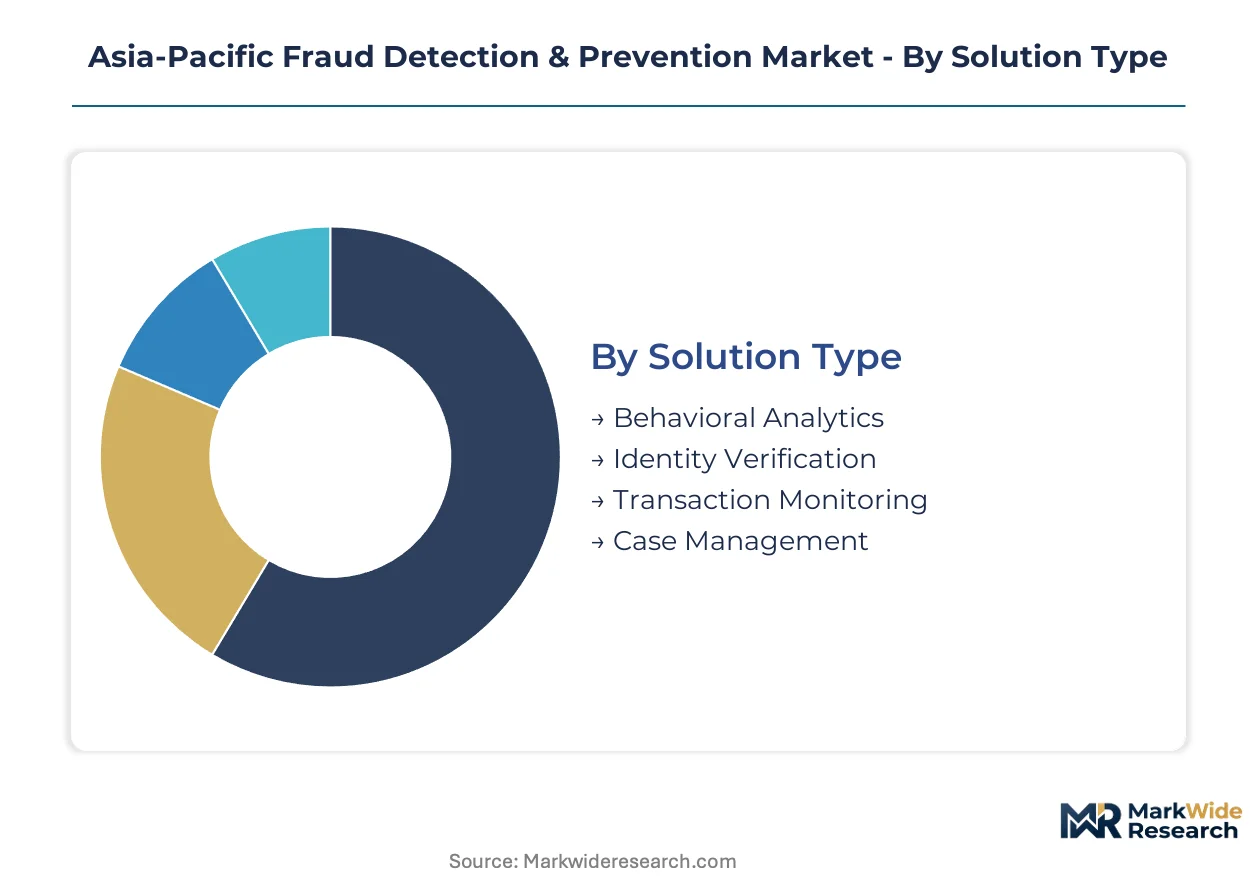
Fraud detection architectures diverge sharply across Asia-Pacific jurisdictions based on regulatory latency requirements and data sovereignty mandates. Procurement patterns reveal distinct technology stacks emerging in India's UPI corridors versus Australia's APRA-regulated banking hubs.
Solution Type:
India's RBI mandates transaction monitoring for payment system operators while Australia's APRA enforces CPS 234 information security standards that directly shape solution specifications.
- Behavioral Analytics:Biometric liveness detection and device fingerprinting engines process mobile banking interactions in under 200 milliseconds. Australian banks absorb substantial cost premiums for anti-spoofing capabilities in mobile applications. Established volume favors behavioral analytics; emerging adoption favors case management automation.
- Identity Verification:Synthetic identity detection systems anchor onboarding workflows for neobanks across India's fintech corridor. Singapore's MAS Technology Risk Management Guidelines mandate explainable outputs that constrain neural network architectures for identity scoring layers.
- Transaction Monitoring:Real-time payment infrastructure rollouts across Southeast Asia compress decisioning latency from batch overnight to sub-200 millisecond thresholds.
- Case Management:Investigation workflow platforms integrate with regulatory reporting requirements in Hong Kong's HKMA Fraud Risk Management Circular framework.
Behavioral analytics commands premium pricing in Australian mobile banking; identity verification scales fastest across India's digital payment corridors.
Deployment Model:
Cost tier differentiation separates capital-constrained mid-tier e-commerce platforms from established banks with legacy infrastructure commitments.
- Cloud-based:SaaS fraud platforms with pre-baked compliance documentation accelerate procurement among regional Australian banks facing APRA CPS 234 third-party risk obligations. Mid-tier Indonesian and Vietnamese e-commerce platforms favor cloud deployment to bypass on-premises capital requirements.
- On-premises:COBOL-based core banking systems at established Australian and Indian institutions create API friction that extends deployment timelines for real-time scoring modules. Established volume favors on-premises deployments; emerging adoption favors cloud-based delivery.
- Hybrid:Edge computing nodes for latency-sensitive decisioning combine with cloud-based model training for synthetic identity pattern recognition.
- Managed Service:Outsourced fraud operations appeal to Philippine remittance corridors and Vietnam's underpenetrated e-commerce gateways lacking internal data science capacity.
Hybrid architectures gain traction where real-time scoring meets model retraining requirements; managed services expand where talent scarcity constrains internal operations.
End User:
Application intensity varies by sector exposure to synthetic identity fraud and real-time payment velocity.
- Banks:Tier-one institutions in Australia and Singapore deploy full-stack graph databases for mule account detection, compressing time-to-identification from weeks to hours. APRA CPS 234 mandates drive board-level reporting on fraud risk posture.
- E-commerce:Jakarta's ride-hailing and food delivery apps operate multi-vendor fraud stacks with unbundled device intelligence procurement separate from core processing relationships. Established volume favors banking sector procurement; emerging adoption favors e-commerce platform investment.
- Insurance:Underwriting fraud detection concentrates statistical modeling depth requirements among Australian general insurers.
- Telecom:Subscriber identity verification for SIM registration compliance drives demand across India's digital identity infrastructure.
Banking retains the deepest procurement budgets; e-commerce represents the steepest expansion trajectory as merchant acquirers unbundle fraud protection from core processing.
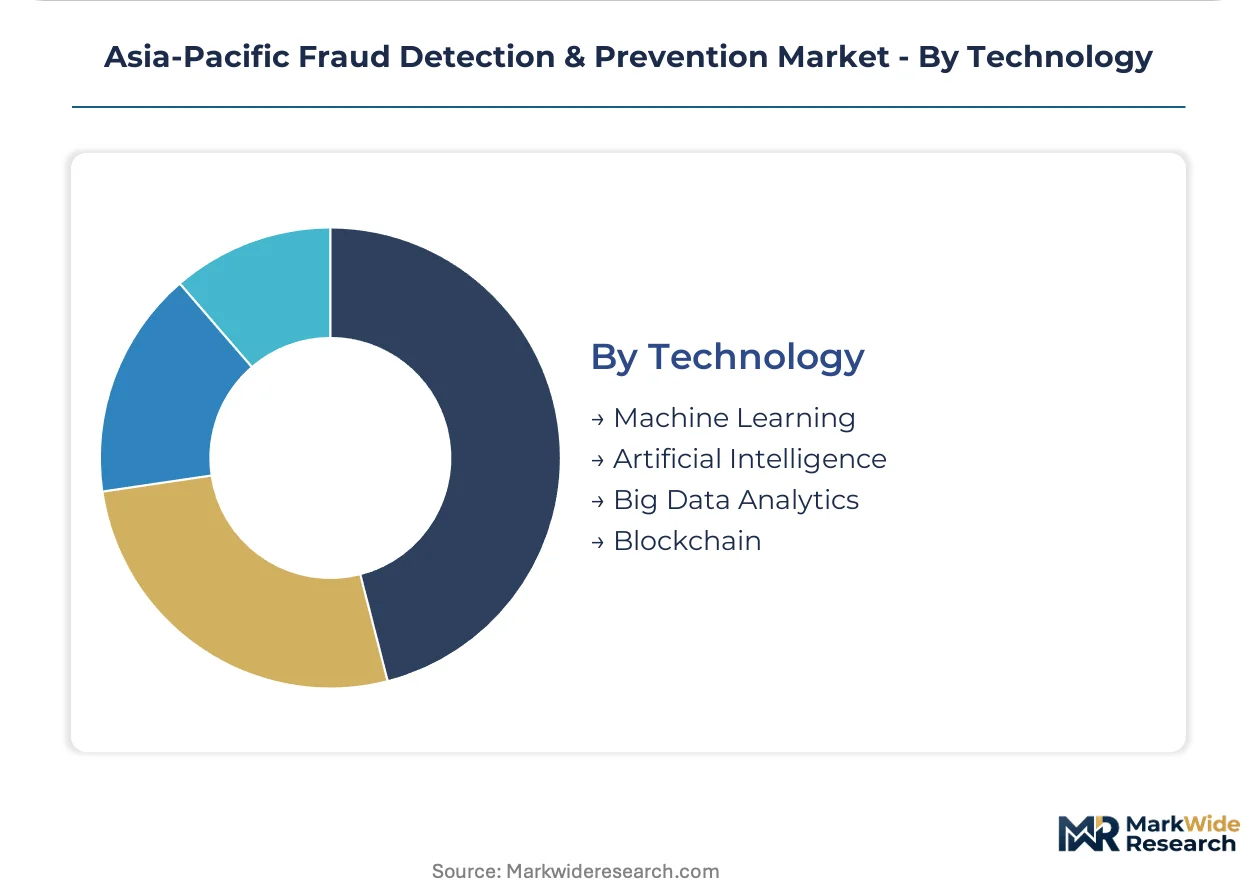
Technology:
Supply concentration for specialized data engineering talent shapes technology adoption feasibility outside Bangalore and Sydney.
- Machine Learning:Lightweight edge-deployed ensembles serve latency-constrained Southeast Asian payment networks. Model drift management forces parallel rule-engine fallbacks that increase operational complexity.
- Artificial Intelligence:Transformer-scale neural networks compete with edge architectures, with deployment location becoming the primary technical differentiator rather than algorithmic sophistication alone. Established volume favors machine learning implementations; emerging adoption favors artificial intelligence platforms.
- Big Data Analytics:Entity-resolution overlays on existing relational warehouses serve mid-tier ASEAN institutions lacking graph database infrastructure.
- Blockchain:Distributed ledger identity verification targets Philippine OFW remittance flows through informal channels.
Big data analytics dominates current procurement volumes; blockchain applications remain exploratory with limited production deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's RBI anchors procurement intensity across the Asia-Pacific fraud detection landscape through mandated multi-factor authentication and transaction monitoring standards for payment system operators. The region's $8.7 billion base concentrates in India's fintech corridor and Australia's banking hubs, with Southeast Asian real-time payment rollouts compressing decisioning latency requirements.
India
Neobanks and UPI aggregators drive behavioral analytics procurement under RBI's Digital Payment Security Framework. The central bank mandates transaction monitoring standards that accelerate cloud platform adoption among payment system operators. Mumbai and Bangalore's fintech corridor concentrates vendor engineering centers responding to data science talent scarcity.
Australia
Tier-one banks absorb 40-60% cost premiums for biometric liveness detection in mobile banking applications. APRA's CPS 234 information security standard enforces third-party risk management obligations for cloud-hosted fraud platforms. Sydney anchors procurement of AI-augmented detection layers with mandated board-level fraud risk reporting.
Singapore
MAS Technology Risk Management Guidelines require explainable AI outputs that constrain neural network architectures for black-box detection systems. The city-state's talent corridor with Sydney reorganizes vendor delivery models through localized engineering centers. Financial institutions here deploy full-stack graph databases for mule account detection.
Vietnam
Domestic payment gateways lack sophisticated device intelligence, creating whitespace for behavioral biometrics vendors. Mid-tier e-commerce platforms favor cloud deployment to bypass on-premises capital requirements. Ho Chi Minh City's ride-hailing and food delivery apps operate multi-vendor fraud stacks with unbundled procurement.
Indonesia
Merchant acquirers unbundle fraud protection from core processing relationships as e-commerce platforms procure standalone device intelligence. Hyperscaler availability zone concentration in Singapore creates cross-border latency complications for Jakarta-based platforms. The capital's fintech corridor sees fastest cloud-based deployment expansion among capital-constrained operators.
Asia-Pacific Fraud Detection & Prevention Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with database-level integration and statistical modeling depth serving as primary differentiation vectors. The upper tier embeds fraud analytics within core banking infrastructure, while specialists compete on biometric liveness detection and device fingerprinting capabilities. Two dominant competitive moves reshape positioning: hyperscaler partnerships for regional cloud infrastructure access, and university pipeline partnerships to address data science talent scarcity. Vendors also re-architect platform architectures around edge computing nodes to meet sub-200 millisecond decisioning thresholds.
Among the integrated tier, IBM Corporation leverages regional cloud infrastructure to embed fraud analytics within core banking stacks, while Oracle Corporation anchors its position through database-level integration that reduces latency for real-time scoring. SAS Institute Inc. occupies a distinct position competing on statistical modeling depth for insurance underwriting fraud applications. These three exemplify the strategic archetypes of infrastructure-embedded platforms, database-native solutions, and specialized analytics engines that define competitive positioning across the region's procurement landscape.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| ACI Worldwide Inc |
| Fiserv Inc |
| NICE Ltd. |
| BAE Systems PLC |
| Dell Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Sub-200 millisecond latency requirements compress vendor delivery timelines to 90-120 days for edge computing node deployment, concentrating pricing power with hyperscalers operating Singapore and Sydney availability zones while forcing mid-tier ASEAN platforms toward SaaS absorption models that trade customization for speed-to-market.
Pricing Analysis
Australian banks absorb 40-60% cost premiums for biometric liveness detection versus Indonesian e-commerce platforms procuring standardized device fingerprinting modules. Three-tier pricing structure across premium, standard, and economy levels segments by explainable AI certification depth and real-time scoring latency guarantees. Pricing pressure stems from mid-tier Vietnamese merchant acquirers unbundling fraud protection from core processing relationships. Neobanks in India's UPI corridor exhibit highest price sensitivity; APRA-regulated Australian tier-one institutions prioritize compliance documentation over unit cost.
Supply Chain Analysis
Singapore and Sydney anchor cloud infrastructure delivery for real-time scoring platforms serving Southeast Asian payment networks. Specialized data engineering talent draws from Bangalore's fintech corridor and Australia's university pipeline partnerships. Supply chain risk centers on single-source vulnerability for graph database licensing from US-based vendors. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with embedded compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time payment infrastructure rollouts across Southeast Asia compress fraud detection latency requirements from batch overnight to sub-200 millisecond thresholds, creating structural disruption for incumbent vendors and white-space opportunities for edge-native specialists.
For Market Incumbents: Consolidate around database-level integration capabilities that reduce latency for core banking stacks, while acquiring specialized behavioral biometrics firms to offset unbundling pressure from Indonesian merchant acquirers. Anchor engineering centers in Bangalore and Sydney through direct university pipeline partnerships that address data science talent scarcity. For New Entrants and Emerging Players: Differentiate on lightweight edge-deployed ensembles serving Vietnam's underpenetrated e-commerce fraud stack and Philippine OFW remittance corridors lacking sophisticated device intelligence. Target Jakarta's ride-hailing and food delivery apps with unbundled procurement models that separate device intelligence from core processing relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from regional Australian banks divesting on-premises fraud operations under APRA CPS 234 third-party risk obligations. Long-term viability favors SaaS platforms with pre-baked compliance documentation serving multi-jurisdiction architectures. Watch for inflection where Singapore's MAS explainable AI mandates converge with India's RBI automated decisioning emphasis, forcing architectural standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Node Deployment | Sub-200 millisecond decisioning meets Southeast Asian real-time payment latency requirements. |
| University Pipeline Partnership | Localized engineering centers in Bangalore and Sydney address data science talent scarcity. |
| Regulatory Compliance Documentation | Pre-baked APRA CPS 234 and MAS Technology Risk Management Guidelines accelerate procurement. |
| Graph Database Integration | Full-stack mule account detection compresses time-to-identification from weeks to hours. |
| Biometric Liveness Certification | Anti-spoofing capabilities command premium pricing in Australian mobile banking applications. |
Research Methodology
A spread of perspectives from fraud analytics platform engineers, APRA compliance officers, neobank CTOs, and payment system operator procurement leads converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from RBI circulars, MAS Technology Risk Management Guidelines, APRA CPS 234 prudential standards, and hyperscaler availability zone disclosures. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation with regional banking IT expenditure patterns anchored volume estimates.
Segmentation dimensions modeled span solution type, deployment architecture, end-user sector, and technology layer across the analysis window. CAGRs derive from regression against real-time payment infrastructure rollout timelines and regulatory mandate effective dates. Synthetic identity fraud pattern mutation rates and explainable AI development cycle extensions serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained RBI enforcement intensity or hyperscaler availability zone expansion would require recalibration. Forecasts reflect documented assumptions regarding edge computing cost curves and data engineering talent pipeline development. Recalibration cycles align with material shifts in MAS Technology Risk Management Guidelines revisions or APRA third-party risk management obligation updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Employee Fraud Detection Market
Security Software
Decentralized Identity Software Market
Security Software
Secure Flash Drive Market
Security Software
Source Code Escrow Market
Security Software
Antivirus Software Package Market
Security Software
Global Reputation Protection Software Market
Security Software
Geofencing Market
Security Software
Global Security Software in Telecom Market
Security Software
Mobile Security Market
Security Software
Network Camera and Video Analytics Market
Security Software
Global Digital Signature Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Global Enterprise Key Management Market
Security Software
Mobile Data Protection Solutions and Services Market