
 US and Latin America Identity and Access Management (IAM) Market | 2026-2036
US and Latin America Identity and Access Management (IAM) Market Size, Share, and Industry Trends Forecast 2026-2036
US and Latin America Identity and Access Management (IAM) Market Analytics
Subscription-based financing and managed-security service leases are tilting competitive dynamics toward providers with capital-efficient delivery models. Microsoft leverages its Azure ecosystem to anchor enterprise identity workloads across Fortune 500 accounts. Ping Identity specializes in zero-trust architectures for regulated US healthcare networks. CyberArk dominates privileged access management through deep R&D investment in secrets vaulting technology.
Identity and Access Management encompasses the policies, technologies, and processes that authenticate users and authorize their access to organizational resources, typically integrating directory services, provisioning workflows, and real-time risk engines operating at sub-second authentication latency. The primary commercial purpose centers on preventing unauthorized data exposure while enabling workforce productivity across distributed cloud and legacy on-premises infrastructure. Cloud deployment now leads new contract value as enterprises abandon capital-intensive on-premises identity stacks, while multi-factor authentication solutions capture accelerating demand following US federal zero-trust directives. Governance and compliance modules command premium pricing due to complex cross-border data sovereignty requirements affecting US-Latin America operations.
US federal agencies operate under NIST cybersecurity framework mandates and OMB zero-trust architecture directives that compel continuous authentication upgrades, while Brazil's Central Bank and Mexico's CNBV impose granular access-control standards on financial institutions that drive IAM procurement intensity. The SEC's cybersecurity disclosure rules now require US public companies to document identity breach materiality, expanding audit-scope demand for governance solutions. Stakeholders must weigh sovereign data localization requirements against cloud-native platform scalability when architecting IAM infrastructure spanning US and Latin American jurisdictions.
Market Dynamics
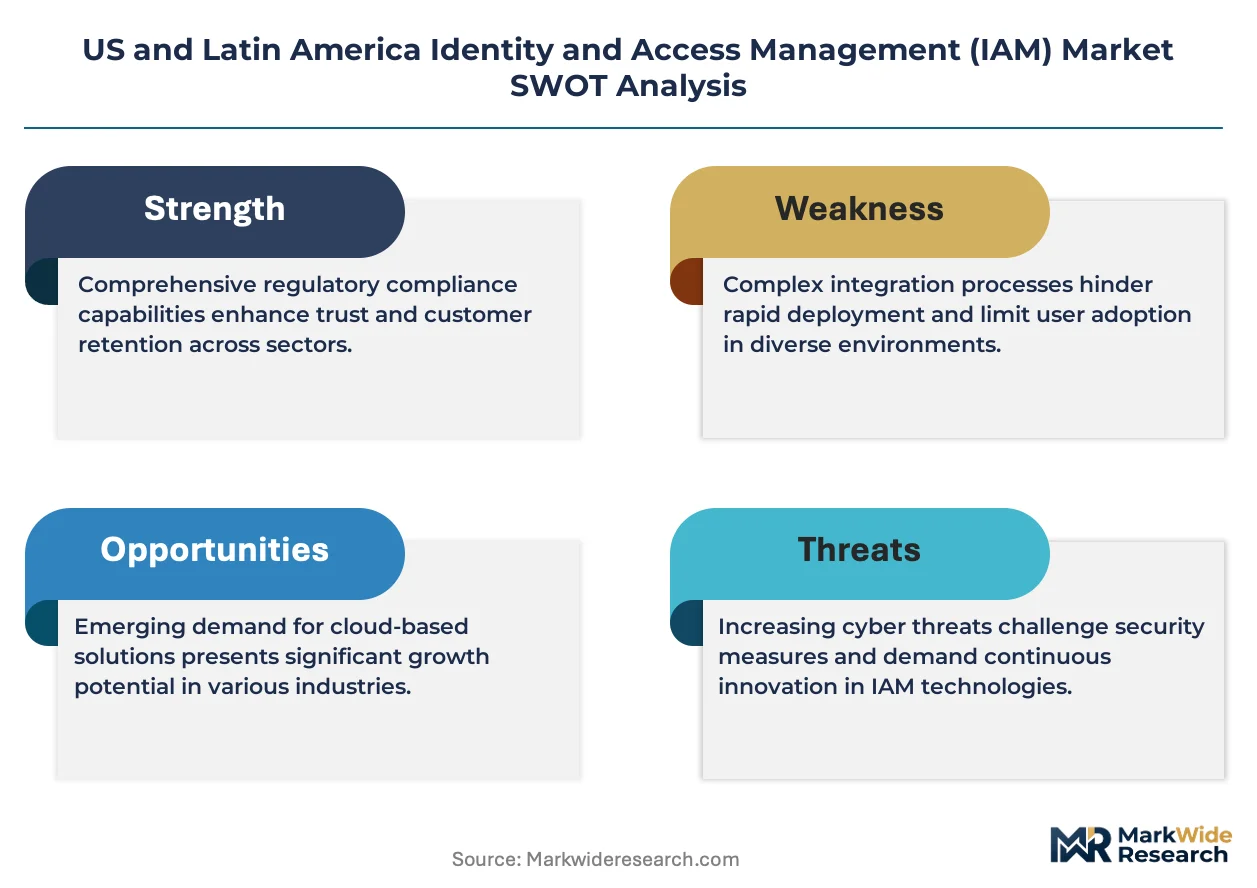
Cloud-native identity architectures are compressing deployment cycles from months to weeks across US federal contractors and Brazilian financial institutions, forcing established vendors to restructure delivery models around consumption-based pricing.
Growth Catalysts
- Zero-trust architecture mandates:OMB directives compel continuous authentication upgrades across US federal agencies. Cloud access security brokers capture expanding procurement budgets as agencies retire perimeter-based security models.
- Brazilian financial regulation:Central Bank cybersecurity standards require granular privileged access controls at tier-one and tier-two banks. Compliance deadlines drive concentrated IAM procurement through 2026.
- Hybrid cloud workload expansion:US defense contractors managing classified and unclassified data streams require converged identity fabrics. Multi-cloud orchestration tools integrate directory services across Azure Government and AWS Secret Region environments.
Market Restraints
- Specialized talent scarcity:Zero-trust architecture design and secrets vaulting engineering skills command 40% wage premiums in São Paulo and Washington DC metro markets. Staffing bottlenecks extend implementation timelines.
- Cross-border data sovereignty friction:Mexico's data localization requirements under its federal data protection framework conflict with US cloud providers' centralized infrastructure models. Architecture compromises reduce platform scalability.
- Legacy directory integration complexity:Active Directory forests deployed during the 2000s resist cloud-native migration without complete identity re-architecture. Technical debt accumulates interest in workforce productivity losses.
Strategic Opportunities
- Colombian and Chilean banking modernization:Superintendencia Financiera de Colombia and CMF Chile are drafting cybersecurity frameworks modeled on Brazilian standards. Early-mover IAM providers capture reference architecture influence.
- Biometric authentication convergence:Facial recognition APIs and behavioral analytics engines merge into continuous authentication pipelines. Healthcare networks in Texas and Florida pilot passwordless workforce access.
- Managed security service provider channel expansion:Regional MSSPs in Mexico City and São Paulo lease IAM capabilities to mid-market enterprises lacking capital for platform ownership. Subscription economics penetrate price-sensitive segments.
Industry Challenges
- Certification timeline compression:FedRAMP authorization processes for cloud identity platforms now span 18-24 months. Vendor engineering teams divert resources from feature development to compliance documentation.
- Multi-generational system integration:Mainframe-based core banking systems at Mexican financial institutions resist API-native identity federation. Custom middleware development consumes 30-40% of implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Latin America Identity and Access Management (IAM) Market |
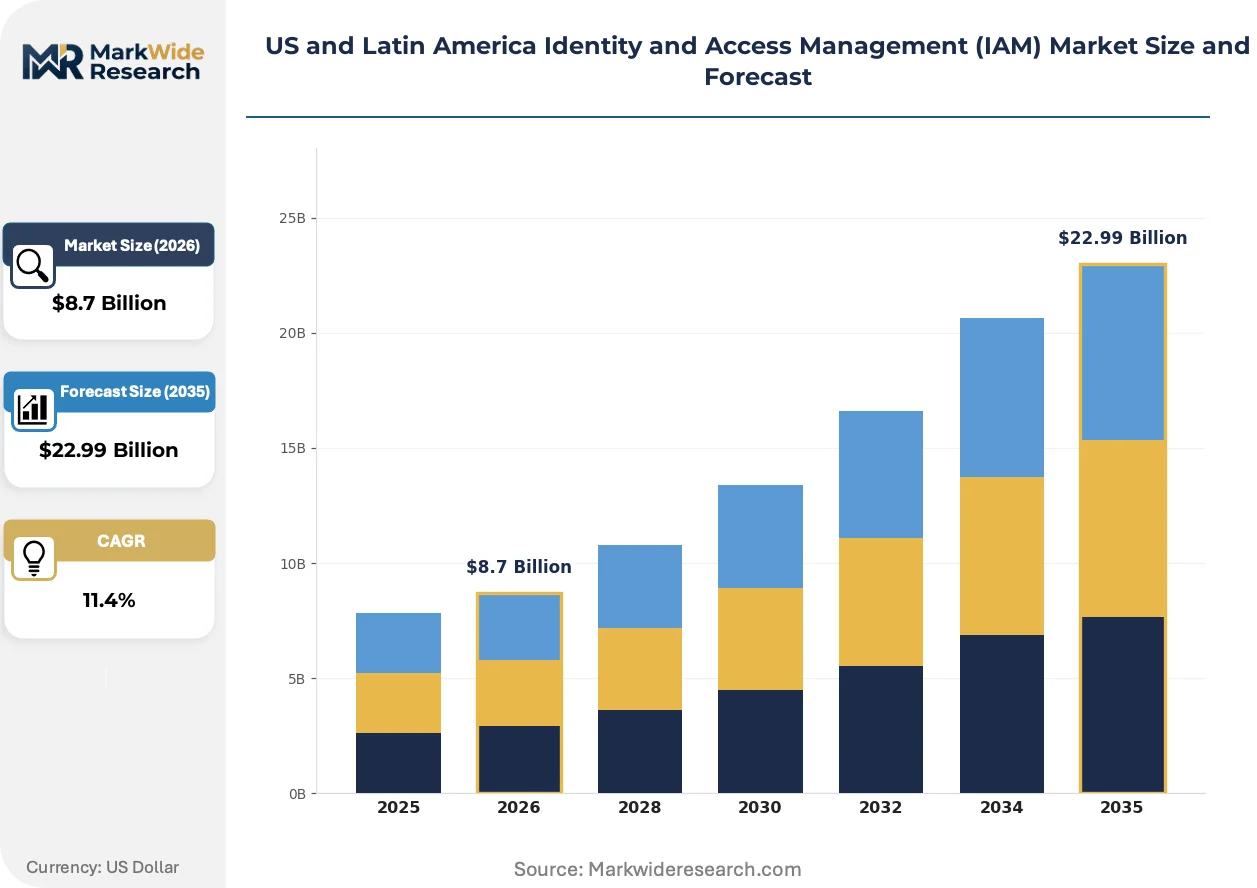
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Managed Service End User: Healthcare, BFSI, Retail, Government Solution: Single Sign-On, Multi-Factor Authentication, Access Management, Governance Technology: Biometric, OAuth, SAML, LDAP |
| Companies Covered | Microsoft, IBM, Ping Identity, Okta, Oracle, Amazon Web Services, SailPoint, CyberArk, SecureAuth, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Latin America Identity and Access Management (IAM) Market Evolving Landscape
Artificial intelligence is embedding risk scoring directly into authentication flows, compressing decision latency while expanding the data signals that identity platforms ingest and analyze.
Decentralized identity standards are digitizing credential verification across healthcare and financial services workflows. Large hospital systems in California and New York pilot portable provider credentials that eliminate repetitive background checks. Verifiable credential wallets reduce administrative overhead while improving audit trail integrity.
Brazil's Central Bank Resolution 4.893 imposes granular access-control standards on payment institutions and fintechs. Compliance deadlines accelerate procurement of privileged access management solutions with native session recording. Tier-two Brazilian banks prioritize vendors with local data center presence to satisfy operational resilience requirements.
Consumption-based licensing is displacing perpetual software ownership across Fortune 500 identity programs. Chief information security officers in manufacturing and energy verticals favor operational expenditure treatment for authentication infrastructure. Annual contract value calculations now weight monthly active user volumes above named user entitlements.
US and Latin America Identity and Access Management (IAM) Market Segmentation
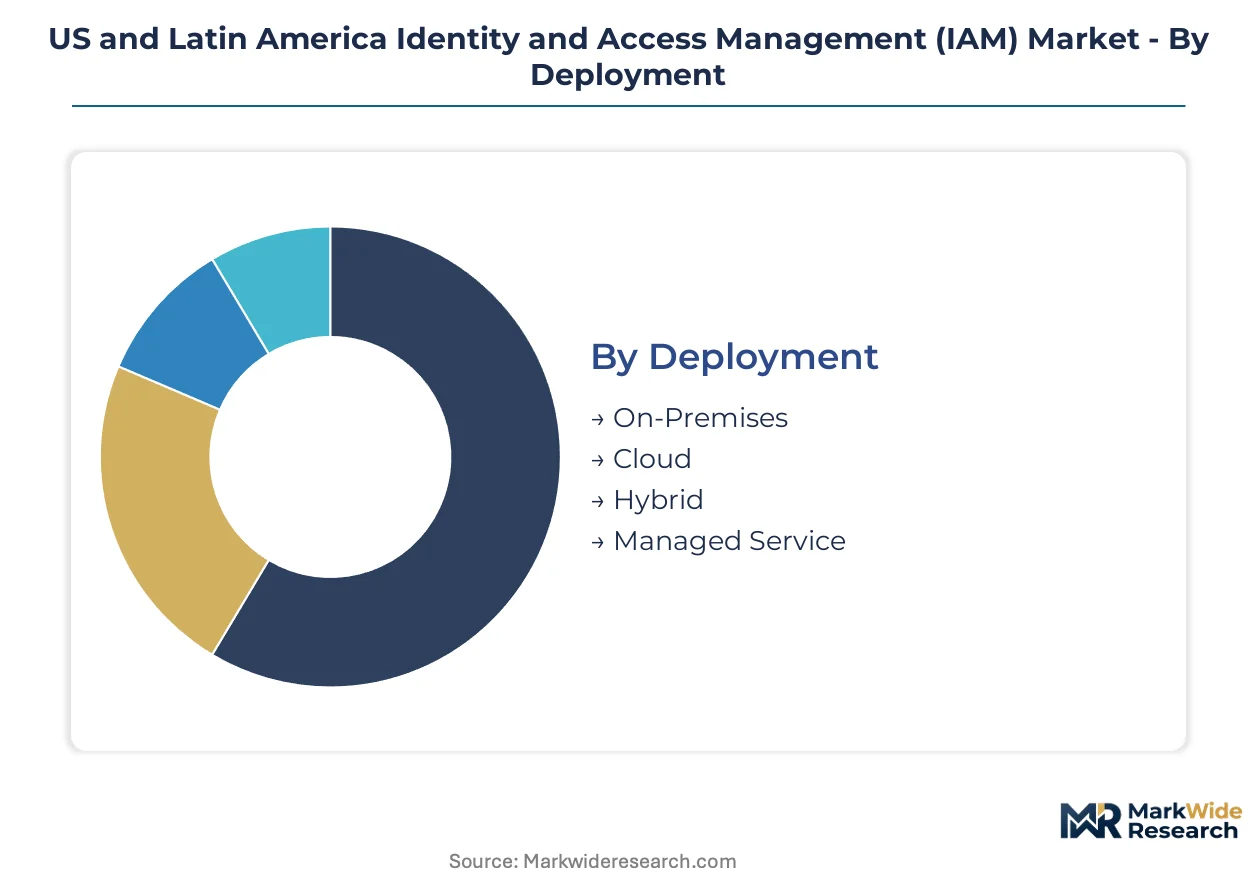
IAM procurement patterns diverge sharply across deployment architectures and regulatory environments, with cloud-native solutions commanding premium contract values while legacy on-premises installations require intensive integration services. Understanding segment-level demand concentration enables vendors to align engineering roadmaps with compliance-driven purchasing cycles across US federal agencies and Latin American financial institutions.
Deployment:
Post-implementation support intensity varies dramatically by deployment model, with managed service arrangements demanding continuous operational engagement and on-premises installations requiring periodic upgrade cycles.
- Cloud:Native SaaS identity platforms eliminate infrastructure ownership burdens while enabling elastic scaling across multi-tenant architectures. US federal contractors migrating classified workloads to Azure Government and AWS Secret Region environments drive concentrated demand for FedRAMP-authorized cloud identity services.
- Hybrid:Converged architectures synchronize directory services across on-premises Active Directory forests and cloud-native identity providers. Brazilian tier-one banks managing core banking system integration with cloud access security brokers prioritize hybrid configurations to satisfy Central Bank operational resilience mandates.
- On-Premises:Capital-intensive perpetual license models persist in defense and intelligence segments with air-gapped security requirements.
- Managed Service:Third-party operational responsibility appeals to mid-market enterprises lacking specialized identity engineering capabilities.
Cloud holds the largest share; momentum sits with Hybrid.
End User:
Compliance burden intensity shapes procurement sophistication, with regulated verticals demanding granular audit trails and continuous authentication mechanisms.
- BFSI:Financial institutions face the most stringent access-control mandates across the segment spectrum. Brazil's Central Bank Resolution 4.893 and Mexico's CNBV cybersecurity frameworks compel tier-one and tier-two banks to deploy privileged access management with native session recording and secrets vaulting capabilities.
- Government:US federal agencies operate under binding OMB zero-trust architecture directives and NIST cybersecurity framework requirements. Continuous authentication upgrades and cloud access security broker procurement dominate agency identity modernization budgets.
- Healthcare:HIPAA-covered entities in Texas and Florida pilot passwordless workforce access using converged biometric and behavioral analytics pipelines.
- Retail:Customer-facing identity verification for digital commerce platforms drives demand for frictionless authentication experiences.
BFSI generates the highest contract values; Government shows the steepest expansion trajectory.
Solution:
Integration complexity escalates from single-point authentication tools toward comprehensive governance platforms requiring cross-functional stakeholder alignment.
- Multi-Factor Authentication:Sub-second risk-scoring engines now embed machine learning directly into authentication flows. US federal zero-trust directives and Brazilian financial regulations mandate MFA deployment across all privileged access scenarios, compressing implementation timelines.
- Governance:Policy orchestration and compliance reporting modules command premium pricing due to cross-border data sovereignty complexity. SEC cybersecurity disclosure rules requiring identity breach materiality documentation expand audit-scope demand among US public companies.
- Single Sign-On:Workforce productivity tools consolidate application access behind unified identity provider portals.
- Access Management:Real-time authorization engines enforce dynamic policy decisions across distributed cloud and legacy infrastructure.
Governance captures the highest margins; Multi-Factor Authentication is expanding most quickly.
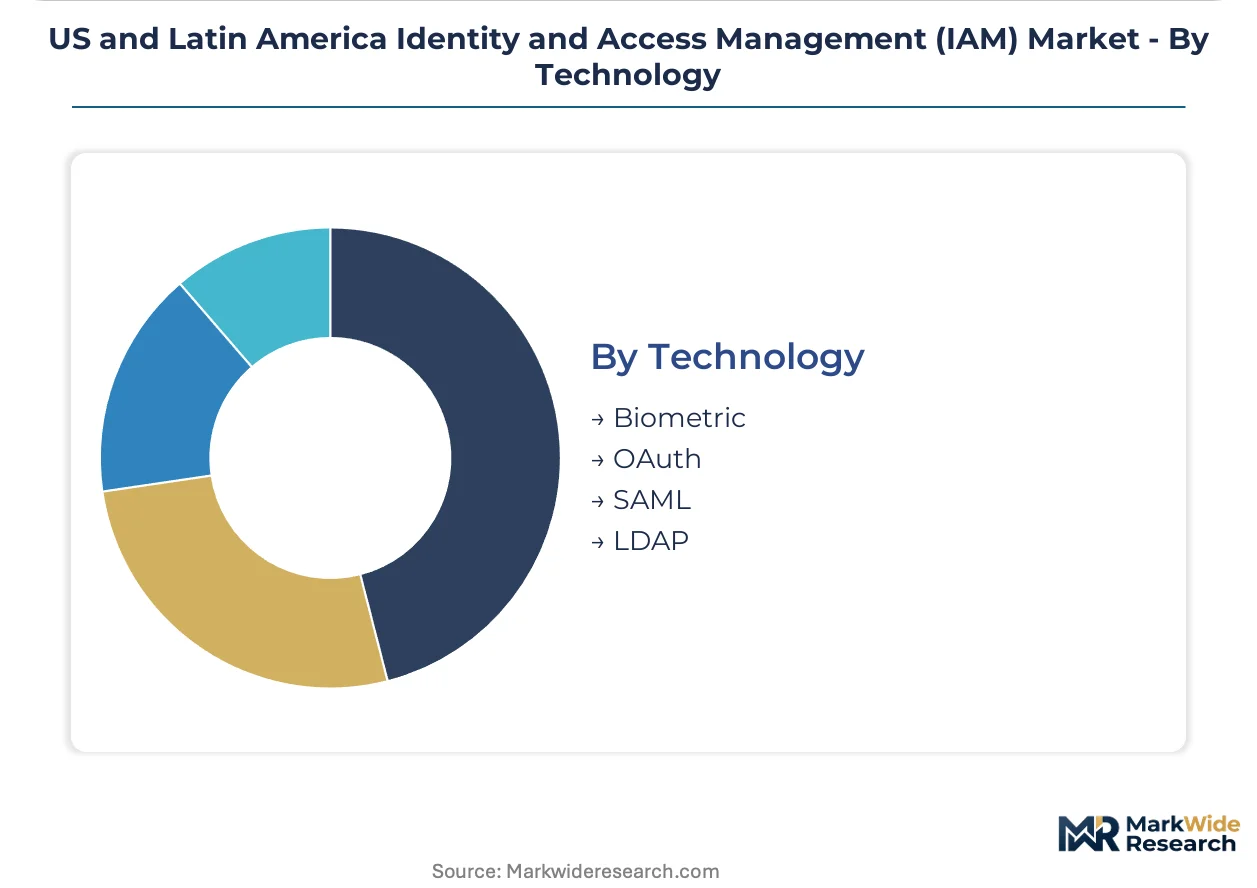
Technology:
Standard maturity and interoperability certification determine enterprise adoption velocity, with legacy protocols persisting in mainframe-connected environments.
- OAuth:Modern authorization framework enables secure delegated access across cloud-native application ecosystems. API-first architecture patterns at Colombian and Chilean fintechs prioritize OAuth 2.0 and OpenID Connect implementations for customer-facing identity flows.
- Biometric:Facial recognition APIs and behavioral analytics engines merge into continuous authentication pipelines. Large hospital systems in California and New York pilot portable provider credentials using verifiable credential wallets.
- SAML:XML-based federation standard maintains enterprise presence for legacy SaaS application integration.
- LDAP:Directory access protocol persists in on-premises authentication scenarios requiring Active Directory integration.
OAuth dominates new implementations; Biometric is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US and Latin America IAM market exhibits distinct import-export characteristics, with US-based cloud providers exporting identity services southward while Brazilian and Mexican financial institutions drive regional demand concentration through compliance-heavy procurement cycles.
United States
Federal zero-trust mandates and defense contractor classified workload migration anchor domestic demand intensity. OMB directives and NIST cybersecurity framework requirements compel continuous authentication upgrades across civilian and military agencies. Washington DC and Northern Virginia host concentrated vendor engineering operations serving Azure Government and AWS Secret Region deployments.
Brazil
Central Bank Resolution 4.893 imposes granular privileged access controls on tier-one and tier-two banks, compressing implementation timelines through 2026. São Paulo's financial district generates the highest contract values for secrets vaulting and session recording solutions. Local data center presence has become a vendor selection prerequisite for operational resilience compliance.
Mexico
CNBV cybersecurity frameworks and federal data localization requirements create architectural friction for US cloud providers. Mexico City concentrates fintech IAM procurement as payment institutions modernize core banking integrations. Custom middleware development consumes substantial implementation budgets for mainframe-connected identity federation.
Colombia
Superintendencia Financiera de Colombia is drafting cybersecurity frameworks modeled on Brazilian standards, opening early-mover opportunities for reference architecture influence. Bogotá's banking sector pilots OAuth 2.0 implementations for customer-facing identity flows. Regulatory alignment with regional neighbors accelerates procurement sophistication.
Chile
CMF Chile's emerging cybersecurity standards create compliance-driven demand mirroring Brazilian and Colombian precedents. Santiago's financial services sector demonstrates preference for hybrid deployment architectures balancing cloud scalability with sovereign data controls. Regional MSSP channels penetrate mid-market segments through subscription-based IAM leasing.
US and Latin America Identity and Access Management (IAM) Market Competitive Landscape
On the supply side, the industry is consolidating around ecosystem-anchored hyperscalers and specialized security vendors with deep compliance expertise. Strategic archetypes include cloud-native platform providers bundling identity into broader infrastructure stacks, privileged access management specialists with secrets vaulting differentiation, and zero-trust architecture boutiques serving regulated verticals. Dominant competitive moves encompass FedRAMP authorization investments compressing vendor qualification timelines, and managed security service provider channel expansion penetrating price-sensitive mid-market segments.
Among ecosystem-anchored hyperscalers, Microsoft and Amazon Web Services occupy positions leveraging cloud infrastructure dominance to capture enterprise identity workloads. Within the specialized security tier, CyberArk exemplifies privileged access management depth through concentrated R&D in secrets vaulting technology, while Ping Identity represents zero-trust architecture specialization for regulated healthcare and federal networks. These three vendors illustrate the competitive bifurcation between scale-driven platform bundling and compliance-focused technical differentiation.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Ping Identity |
| Okta |
| Oracle |
| Amazon Web Services |
| SailPoint |
| CyberArk |
| SecureAuth |
| Others |
Value Network & Pricing Analysis
Miami-São Paulo data corridor freight economics concentrate vendor delivery costs for FedRAMP-authorized cloud identity platforms, compressing margin structures for providers lacking local data center presence while amplifying price differentiation between sovereign-compliant and standard SaaS tiers across Brazilian financial procurement cycles.
Pricing Analysis
US federal contractors anchor pricing structures around consumption-based SaaS licensing with monthly active user metering, while Brazilian tier-one banks negotiate premium premiums for local operational resilience certification. Price differentiation separates FedRAMP-authorized deployments from standard commercial tiers, with customization for legacy mainframe integration commanding project-based surcharges. Pricing pressure stems from managed security service provider channel expansion into mid-market segments. Fintechs in Mexico City demonstrate highest price sensitivity; defense contractors show lowest.
Supply Chain Analysis
US export control restrictions on cryptographic technology limit cross-border flows of certain authentication hardware and secrets vaulting appliances to Latin American financial institutions. Engineering talent concentrates in Washington DC metro, São Paulo, and Mexico City development clusters. Component dependencies include specialized semiconductors for hardware security modules, biometric sensor arrays, and cloud infrastructure from hyperscale providers. Single-source vulnerability runs through concentrated FedRAMP authorization consultancies. Distribution runs through direct enterprise sales with regional system integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among US federal agencies and Brazilian tier-one banks through consolidated procurement frameworks, fragmenting pricing leverage for vendors without compliance-specialized delivery models.
For Market Incumbents: Entrench FedRAMP authorization depth as competitive moat against emerging cloud-native challengers, expanding São Paulo engineering presence to satisfy Central Bank operational resilience mandates. Prioritize backward integration into secrets vaulting semiconductor sourcing to offset hardware security module supply constraints. For New Entrants and Emerging Players: Pursue Colombian and Chilean banking modernization cycles as reference architecture entry points before regulatory frameworks mature to Brazilian complexity levels. Target mid-market Mexican fintechs through regional managed security service provider channel partnerships with consumption-based pricing. For Investors and Strategic Acquirers: Zero-trust architecture boutiques with healthcare network specialization represent the most defensible acquisition profile for long-term IAM market positioning. Watch for OMB directive acceleration signals indicating federal procurement timeline compression as inflection indicator requiring portfolio recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Compresses vendor qualification timelines for Azure Government and AWS Secret Region contract eligibility. |
| Local Data Center Expansion | Satisfies Brazilian Central Bank Resolution 4.893 operational resilience requirements for tier-one bank procurement. |
| Managed Security Service Provider Channel Development | Penetrates price-sensitive mid-market segments through subscription-based IAM capability leasing. |
| Biometric Authentication Pipeline Integration | Captures healthcare network passwordless workforce access pilots in Texas and Florida markets. |
| Legacy Mainframe Middleware Development | Enables identity federation for Mexican financial institutions resisting API-native core banking migration. |
Research Methodology
A standing panel of chief information security officers, federal procurement officers, Brazilian Central Bank compliance leads, and Latin American system integrator architects provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against SEC cybersecurity disclosure filings, FedRAMP authorization databases, Central Bank regulatory circulars, and hyperscaler capex disclosures. Bottom-up contract value analysis triangulated against top-down market sizing from infrastructure deployment tracking.
Scenario-bracketing anchored quantitative outputs across deployment architecture, end-user vertical, and regulatory jurisdiction dimensions over the projection horizon. CAGRs derived from segmented adoption curve modeling with cross-validation against historical procurement cycle analysis. Cloud migration velocity for classified workloads and biometric authentication pipeline integration rates served as industry-specific forecast sensitivity inputs.
Sensitivities concentrate around OMB zero-trust directive implementation pace, Brazilian Central Bank compliance deadline extensions, and cross-border data sovereignty framework evolution. Forecasts reflect documented assumptions on federal budget allocation continuity and regional regulatory alignment trajectories. Material shifts in US export control restrictions on cryptographic technology or FedRAMP authorization timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Digital Risk Protection Platform Market
Security Software
Europe Video Management System Market
Security Software
Content Protection and Watermarking Market
Security Software
US Evidence Management Market
Security Software
Mobile Identity Management Market
Security Software
Europe Anti-Money Laundering Software Market
Security Software
Disk Encryption Software Market
Security Software
Certification Authority Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
AD-Blocking Software Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Bot Mitigation Market
Security Software
Secure Email Gateway Market
Security Software
Internet Filter Software Market
Security Software
Website Monitoring Software Market
Security Software
Network Video Recorder (NVR) Market