
 Transient Voltage Suppressor (TVS) Diode Market | 2026-2036
Transient Voltage Suppressor (TVS) Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Transient Voltage Suppressor (TVS) Diode Market Analytics
AEC-Q101 automotive qualification is redrawing competitive entry barriers for discrete protection suppliers. Vishay Intertechnology sustains broad catalog depth across unidirectional and bidirectional architectures. Infineon Technologies AG anchors high-reliability automotive sockets with silicon avalanche technology. Littelfuse specializes in application-specific multi-stage arrays for telecommunications infrastructure.
A Transient Voltage Suppressor (TVS) Diode is a semiconductor clamping device engineered to limit voltage spikes to safe levels by entering avalanche breakdown within picoseconds, typically rated from 5V to 440V standoff and dissipating surge currents from 200W to 30kW peak pulse power. Its core industrial purpose centers on protecting integrated circuits, MOSFETs, and communication interfaces from electrostatic discharge and lightning-induced transients. Bidirectional TVS variants command premium positioning in differential signal lines and balanced RF ports where polarity symmetry matters. Surface mount form factors dominate volume shipments as PCB miniaturization accelerates across consumer electronics and automotive control modules. Silicon technology retains manufacturing scale advantages though Zener-based alternatives occupy niche precision-clamping segments.
FCC Part 15 emissions rules in the United States, ESD immunity standards under IEC 61000-4-2 across European markets, and China's GB/T 17626 surge test protocols collectively elevate baseline protection requirements for equipment OEMs. EMA and FDA pathways indirectly shape medical device-grade TVS specifications where leakage current and biocompatibility constraints apply. Stakeholders must monitor how ISO 26262 functional safety tiers propagate into diode derating and qualification documentation for next-generation automotive platforms.
Market Dynamics
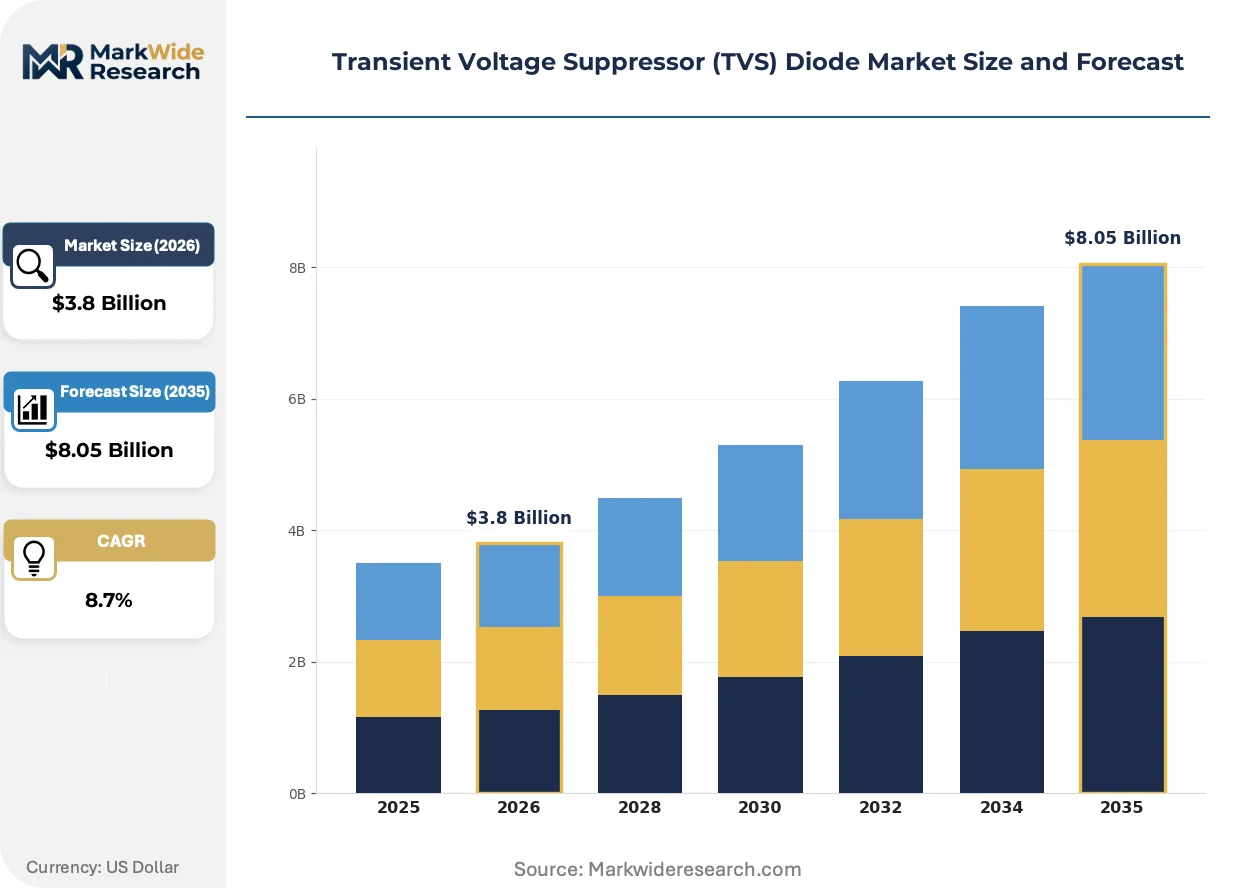
The TVS diode market is experiencing structural pressure from automotive electrification architectures that multiply protection nodes per vehicle while tightening AEC-Q101 qualification thresholds.
Growth Catalysts
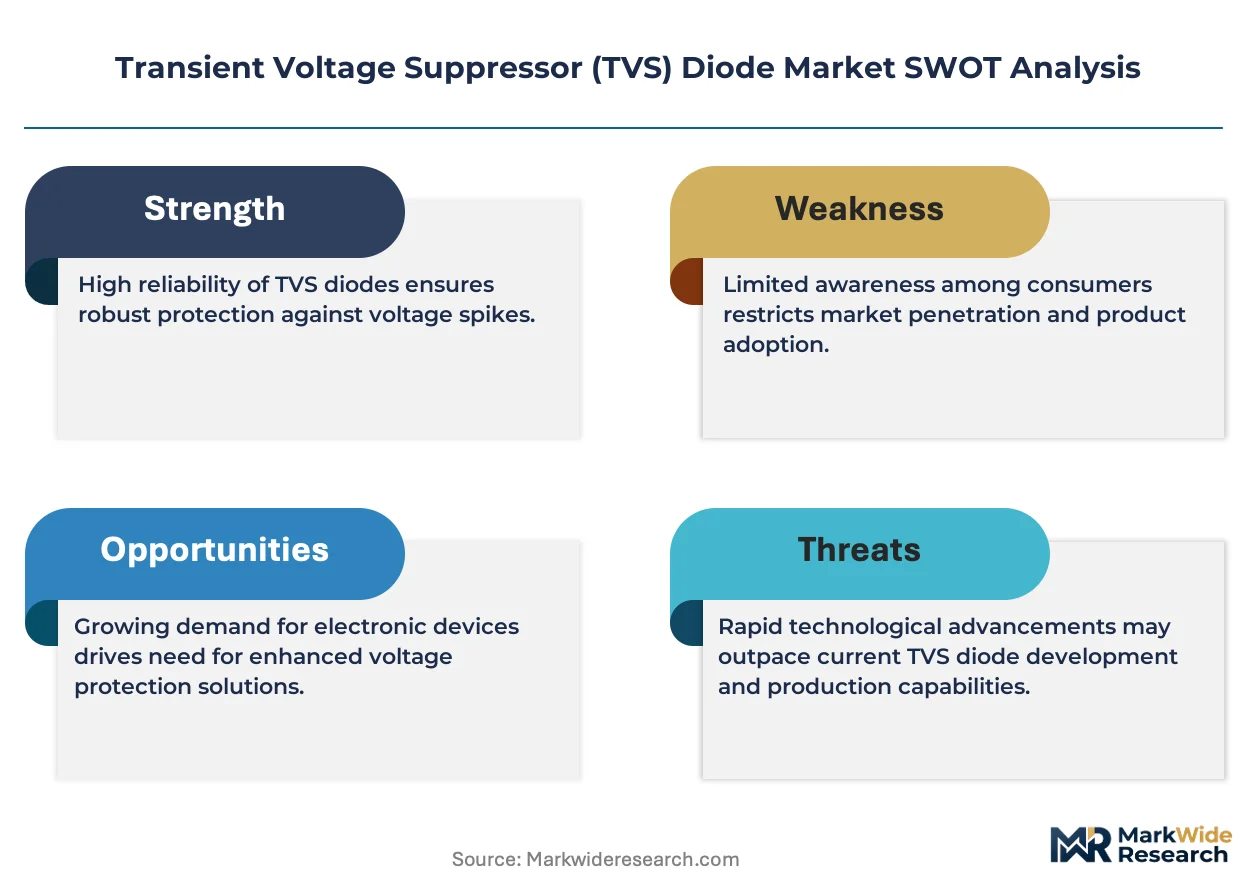
- EV Powertrain Proliferation:Battery management systems and onboard chargers in electric vehicles require dedicated surge protection at every high-voltage node, expanding unit demand per platform.
- IEC 61000-4-5 Compliance Mandates:Industrial equipment OEMs across European markets must integrate certified protection to meet surge immunity standards for CE marking authorization.
- Silicon Carbide Adoption:Wide-bandgap semiconductors in traction inverters operate at higher switching frequencies, necessitating faster-response TVS devices with lower clamping voltages.
Market Restraints
- Wafer Supply Concentration:Advanced silicon substrate production clusters in Taiwan and South Korea create vulnerability to geographic disruption for discrete component foundries.
- Raw Material Cost Volatility:Copper and gold bonding wire prices fluctuate with commodity cycles, compressing margins for high-volume surface-mount package lines.
- Technical Performance Ceiling:Silicon avalanche technology faces fundamental limits in energy density compared to metal-oxide varistor alternatives for extreme surge events.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are drawing TVS module assembly investments to serve domestic automotive and telecom demand.
- ADAS Sensor Protection:LiDAR and radar modules in autonomous driving platforms require ultra-low capacitance TVS arrays for high-speed data line integrity.
- 5G Base Station Deployment:Massive MIMO antenna architectures in China's telecommunications infrastructure create multi-channel protection requirements at scale.
Industry Challenges
- AEC-Q101 Qualification Timeline:Automotive-grade certification demands 1,000-hour high-temperature reverse bias testing, extending product development cycles by 12-18 months.
- Legacy System Integration:Industrial automation retrofits require backward-compatible protection schemes that interface with established 24V control voltage standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transient Voltage Suppressor (TVS) Diode Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unidirectional, Bidirectional, Application Specific, Multi-Stage Technology: Silicon, Zener, Gas Discharge, Transient Voltage Suppressor End User: Electronics, Automotive, Industrial Equipment, Telecommunications Form Factor: Surface Mount, Through-Hole, Chip, Integrated |
| Companies Covered | STMicroelectronics N.V., Nexperia, Vishay Intertechnology Inc., Diodes Inc., On Semiconductor Corporation, Littelfuse Inc., Infineon Technologies AG, Taiwan Semiconductor Manufacturing Company Limited, Bourns Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transient Voltage Suppressor (TVS) Diode Market Evolving Landscape
TVS technology trajectories are diverging between automotive high-reliability requirements and consumer electronics miniaturization pressures, with material science and packaging innovation at the center of competitive differentiation.
Silicon-germanium TVS architectures are bifurcating the market between precision-clamping applications and high-energy surge suppression. Automotive tier-one suppliers in Germany and Japan are adopting SiGe variants for ADAS camera modules where picosecond response times prevent latch-up in CMOS image sensors. This material transition is compressing demand for traditional Zener-based alternatives in sub-100V protection categories.
China's GB/T 17626 surge test protocols are tightening electromagnetic compatibility enforcement for industrial equipment sold domestically. The State Administration for Market Regulation now requires third-party certification for power distribution equipment, forcing domestic OEMs to upgrade from unqualified metal-oxide varistors to certified TVS diode arrays. Heavy machinery and renewable energy inverter manufacturers face the steepest compliance transition costs.
Consolidated procurement by automotive electronics distributors is compressing supplier margins while demanding extended liability warranties. Tier-one distributors in the United States and Germany now require 15-year traceability documentation and failure analysis support, displacing spot-market purchasing for critical safety applications. This behavioral shift favors vertically integrated manufacturers with captive wafer fabrication over fabless competitors in high-volume automotive sockets.
Transient Voltage Suppressor (TVS) Diode Market Segmentation
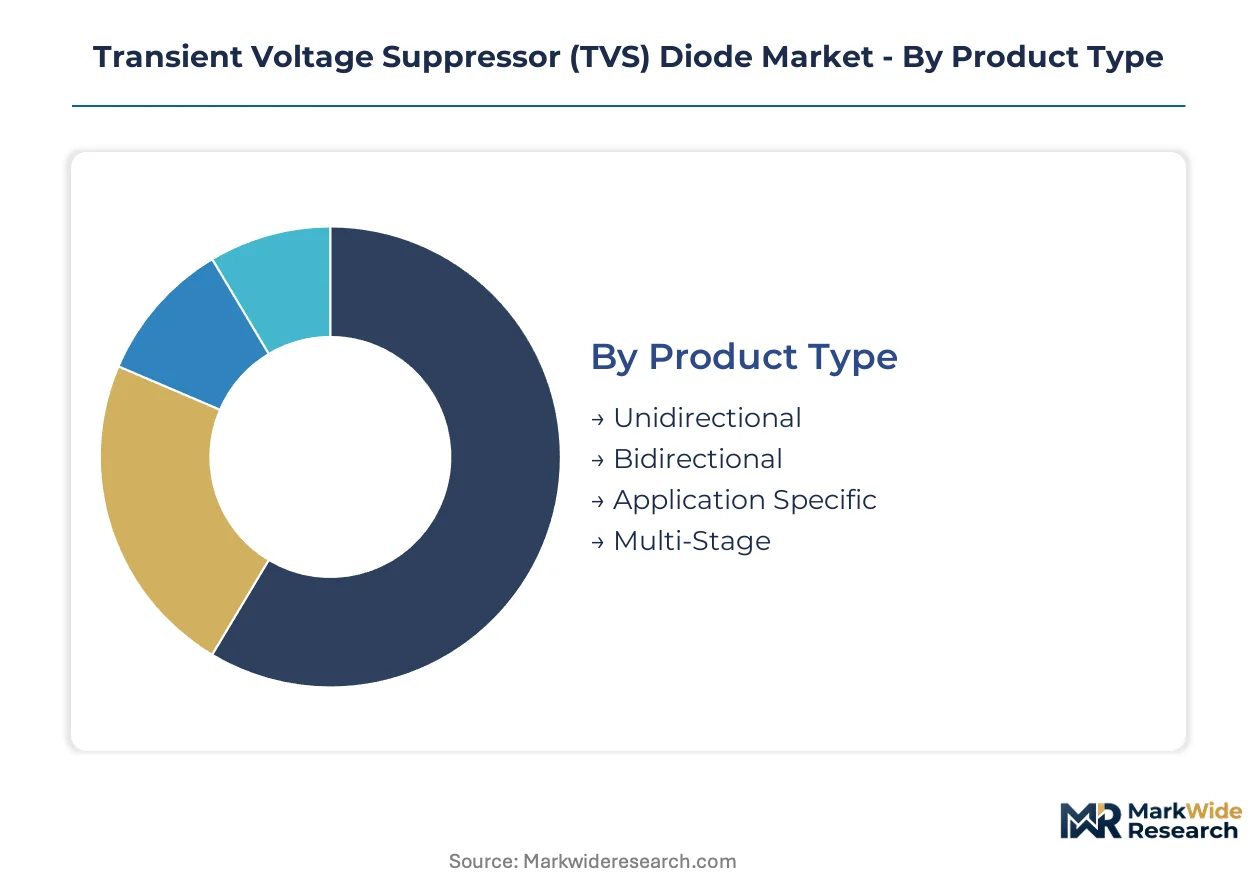
TVS diode procurement patterns diverge sharply between automotive tier-one suppliers demanding AEC-Q101 traceability and consumer electronics assemblers prioritizing surface-mount density. Understanding these segment boundaries clarifies where silicon avalanche technology commands premium positioning versus where Zener alternatives retain cost advantages.
Product Type:
Domestic consumption in China and Germany absorbs the majority of unidirectional and bidirectional output, while application-specific and multi-stage variants ship disproportionately to export-led telecommunications infrastructure projects in India and Southeast Asia.
- Bidirectional:Symmetrical clamping architecture protects differential signal lines and balanced RF ports in automotive ADAS modules and 5G base stations. German automotive tier-one suppliers specify bidirectional arrays for LiDAR interfaces where polarity-agnostic protection prevents CMOS sensor latch-up during load-dump events.
- Unidirectional:Single-polarity suppression dominates DC power rail applications in consumer electronics and industrial 24V control systems. China's domestic appliance manufacturers source unidirectional TVS in surface-mount packages for white goods motor drives subject to IEC 61000-4-5 surge testing.
- Application Specific:Pre-configured arrays integrate matched capacitance for USB-C and HDMI port protection.
- Multi-Stage:Cascaded protection schemes combine primary and secondary suppression for telecommunications central office equipment.
Unidirectional variants command the established base. The steepest expansion runs through bidirectional architectures.
Technology:
Cost tiers separate silicon avalanche devices in high-volume automotive sockets from precision Zener clamps in medical instrumentation, with gas discharge technology occupying extreme-surge industrial niches.
- Silicon:Avalanche breakdown technology achieves picosecond response times and dominates EV powertrain protection nodes. Taiwan and South Korean foundries supply the substrate for silicon TVS deployed across battery management systems in Chinese and US electric vehicle platforms.
- Zener:Precision voltage reference characteristics suit low-leakage medical device applications where FDA biocompatibility constraints apply. Swiss and German diagnostic equipment manufacturers specify Zener-based TVS for patient-connected instrumentation requiring sub-microamp leakage.
- Gas Discharge:High-energy handling exceeds silicon density limits for lightning protection in cellular tower infrastructure.
- Transient Voltage Suppressor:Composite architectures blend multiple suppression mechanisms for hybrid protection schemes.
Silicon avalanche technology anchors volume manufacturing. Zener precision-clamping gains share fastest in medical and test instrumentation.
End User:
Automotive and industrial equipment procurement concentrates in Germany, the United States, and Japan, while electronics and telecommunications demand fragments across contract manufacturing hubs in China, Vietnam, and Mexico.
- Automotive:EV architectures multiply protection nodes per vehicle with dedicated TVS at every high-voltage junction. Battery management systems and onboard chargers in Chinese and European electric platforms require AEC-Q101 qualified devices with 15-year traceability documentation.
- Electronics:PCB miniaturization drives surface-mount TVS adoption in smartphones, laptops, and wearables. South Korean and Taiwanese ODMs specify ultra-low capacitance arrays for high-speed data line integrity in consumer device port protection.
- Industrial Equipment:IEC 61000-4-5 compliance mandates drive replacement of unqualified varistors in European machinery.
- Telecommunications:Massive MIMO antenna deployments in China's 5G infrastructure create multi-channel protection requirements at scale.
Electronics consumption represents the largest volume base. Automotive electrification generates the steepest expansion trajectory.
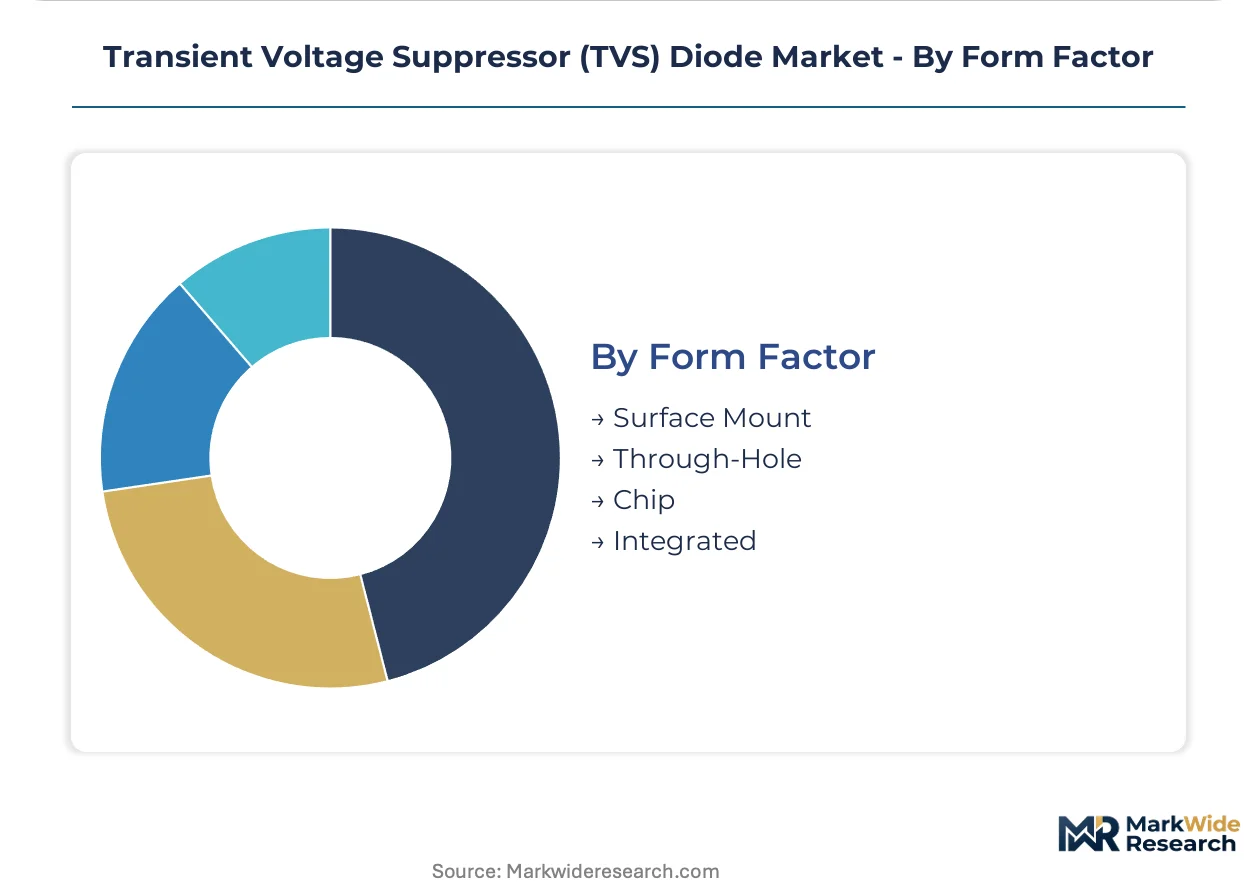
Form Factor:
Surface mount devices flow through high-volume consumer and automotive electronics channels, while through-hole and integrated packages serve industrial retrofit and system-in-package applications respectively.
- Surface Mount:Miniaturized packages below 2.0mm footprint dominate smartphone and automotive control module assembly. German and Japanese tier-one automotive suppliers specify surface-mount TVS for engine control units and transmission modules where PCB space constraints apply.
- Through-Hole:Axial and radial lead configurations persist in industrial automation retrofits requiring backward compatibility with established 24V control voltage standards.
- Chip:Bare die formats enable system-in-package integration for space-constrained medical implants.
- Integrated:Multi-function protection modules combine TVS with filtering and isolation functions.
Surface mount formats command the established base. Integrated protection modules climb fastest in medical and aerospace system packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electronics buyers in Germany, China, and the United States concentrate procurement for AEC-Q101 qualified TVS components. Industrial equipment OEMs across these markets face tightening IEC 61000-4-5 compliance mandates.
Germany
EV powertrain production and ADAS module assembly drive demand from Bavarian and Baden-Württemberg automotive clusters. The KBA enforces stringent electromagnetic compatibility verification for vehicle type approval. Stuttgart-based tier-one suppliers specify bidirectional TVS arrays for LiDAR interfaces in autonomous driving platforms.
China
Battery management systems for domestic electric vehicle platforms multiply protection nodes per vehicle. SAMR mandates third-party GB/T 17626 surge test certification for power distribution equipment sold domestically. Yangtze River Delta foundries in Shanghai and Suzhou concentrate silicon substrate fabrication for high-volume TVS production.
United States
Telecommunications infrastructure deployment and medical device manufacturing absorb specialized TVS arrays. FCC Part 15 emissions rules elevate baseline protection requirements for equipment OEMs. Texas and California electronics manufacturing corridors source surface-mount packages for 5G base station and patient-connected instrumentation applications.
Japan
Precision-clamping applications in CMOS image sensors and industrial automation create demand for picosecond-response devices. METI oversees JIS standards alignment with international IEC surge immunity protocols. Kansai region manufacturers around Osaka specify SiGe TVS variants for ADAS camera modules.
South Korea
Consumer electronics ODMs and memory semiconductor fabs drive ultra-low capacitance array consumption. MFDS regulates medical device-grade specifications where leakage current constraints apply. Seoul Capital Area contract manufacturers specify miniaturized surface-mount TVS for smartphone and wearable port protection.
Transient Voltage Suppressor (TVS) Diode Market Competitive Landscape
Player mix skews toward diversified semiconductor conglomerates with captive wafer fabrication, supplemented by specialized discrete component suppliers and foundry-dependent fabless designers. The supplier base organizes into three archetypes: vertically integrated manufacturers with in-house silicon production, application-specific array specialists, and scale-driven commodity suppliers. Competitive maneuvering centers on AEC-Q101 qualification acceleration and strategic partnerships with automotive tier-one distributors.
Among diversified semiconductor suppliers, STMicroelectronics N.V., Infineon Technologies AG, and Vishay Intertechnology Inc. occupy positions spanning automotive, industrial, and consumer electronics sockets. STMicroelectronics exemplifies the European integrated device manufacturer archetype with broad catalog coverage. Infineon anchors high-reliability automotive demand through German engineering heritage. Vishay represents the North American diversified component supplier model with extensive unidirectional and bidirectional product breadth.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Nexperia |
| Vishay Intertechnology Inc. |
| Diodes Inc. |
| On Semiconductor Corporation |
| Littelfuse Inc. |
| Infineon Technologies AG |
| Taiwan Semiconductor Manufacturing Company Limited |
| Bourns Inc. |
| Others |
Value Network & Pricing Analysis
Twenty-six-week wafer lead times at Taiwan foundries concentrate pricing power among captive silicon producers while compressing margins for fabless TVS suppliers dependent on spot-market substrate allocation. Automotive tier-one distributors exploit this asymmetry to extract extended liability warranties and 15-year traceability documentation without commensurate price premiums.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate high-volume surface-mount package procurement from German and Japanese tier-one suppliers. Price differentiation separates AEC-Q101 automotive-grade devices with full qualification documentation from industrial-grade alternatives certified only to IEC 61000-4-5. Pricing pressure intensifies in consumer electronics sockets as South Korean ODMs consolidate procurement around single-source annual agreements. Medical device manufacturers exhibit lowest price sensitivity due to FDA biocompatibility constraints and sub-microamp leakage requirements that disqualify commodity substitutes.
Supply Chain Analysis
Strait of Malacca transit routes underpin 70 percent of advanced silicon substrate movement from Taiwan and South Korea to packaging houses in China and Southeast Asia. Raw material dependencies center on 300mm silicon wafers, gold bonding wire, and epoxy molding compounds sourced from Japanese chemical specialists. Single-source vulnerability concentrates at the substrate fabrication layer where TSMC and Samsung captive production prioritizes logic IC allocation over discrete component foundry slots. Distribution runs through authorized automotive electronics distributors in Germany and the United States who enforce qualified manufacturer lists and bar spot-market purchasing for safety-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AEC-Q101 qualification capability functions as the binding constraint separating viable automotive suppliers from relegated industrial-grade competitors, with only six manufacturers globally maintaining in-house high-temperature reverse bias testing infrastructure.
For Market Incumbents: Secure captive wafer supply through long-term substrate agreements with Taiwan foundries before logic IC allocation crowds out discrete component capacity. Accelerate silicon-germanium TVS development for ADAS camera modules where picosecond response times prevent CMOS latch-up, defending against emerging SiGe specialists in Japan and Germany. Reinforce distributor relationships through dedicated failure analysis support teams co-located with Stuttgart and Detroit automotive clusters. For New Entrants and Emerging Players: Aftermarket service gaps in legacy industrial automation retrofits present accessible entry points where established suppliers under-invest in 24V control voltage backward compatibility. Target India's PLI scheme incentives for semiconductor packaging to serve domestic automotive and telecom demand with lower qualification overhead than AEC-Q101 automotive sockets. Pursue design-win partnerships with Yangtze River Delta power distribution equipment manufacturers facing mandatory GB/T 17626 certification upgrades. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized discrete semiconductor divisions lacking automotive qualification infrastructure. Five-to-ten-year viability hinges on migration toward wide-bandgap protection architectures for silicon carbide traction inverters. Monitor Infineon and STMicroelectronics AEC-Q101 certification acceleration timelines as inflection indicators for competitive entry barrier height.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q101 Qualification Acceleration | Shrinks product development cycles by 12-18 months for automotive tier-one approval. |
| Silicon-Germanium Architecture Transition | Captures ADAS camera module sockets where picosecond response prevents sensor latch-up. |
| India Packaging Footprint Expansion | Accesses PLI scheme subsidies serving domestic automotive and telecom protection demand. |
| Long-Term Wafer Supply Agreement | Secures substrate allocation priority ahead of logic IC production crowding at Taiwan foundries. |
| Automotive Distributor Partnership Deepening | Meets 15-year traceability and failure analysis requirements for safety-critical applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of AEC-Q101 qualification databases, IEC 61000-4-5 test laboratory certifications, and automotive electronics distributor procurement records. Semiconductor process engineers, tier-one supplier quality directors, and power distribution OEM procurement managers provided operational validation. SEC 10-K filings from diversified component suppliers, SAMR GB/T 17626 enforcement notices, and KBA vehicle type approval records supplied quantitative anchoring. Bottom-up unit demand modeling across EV powertrain protection nodes triangulates against top-down semiconductor industry revenue aggregates.
Segmentation dimensions modeled include product architecture (unidirectional, bidirectional, multi-stage), technology substrate (silicon avalanche, Zener precision, silicon-germanium), end-use vertical (automotive, industrial, telecommunications, medical), and form factor (surface-mount, through-hole, integrated module). CAGRs derive from installed base growth in electric vehicle platforms and 5G infrastructure deployment curves cross-referenced with protection nodes per system estimates. Silicon carbide adoption trajectories and ADAS sensor proliferation rates inform technology transition assumptions across the projection horizon.
Underlying assumptions cover AEC-Q101 qualification timeline stability, Taiwan wafer supply continuity, and copper commodity price band persistence, with deviation risk concentrated in geopolitical disruption to substrate fabrication and accelerated wide-bandgap semiconductor substitution. Practitioners should keep alternative scenarios live as IEC 61000-4-5 enforcement stringency and automotive functional safety tier propagation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market