
 Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market | 2026-2036
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market Outlook
The premium head-mounted display tier is repositioning away from consumer entertainment toward industrial-grade spatial computing, while commodity handheld AR devices serve mass-market retail and education applications. HTC Corporation leverages its Vive enterprise platform to anchor high-fidelity training simulations across Taiwanese electronics factories. Sony Corporation sustains optical component dominance through proprietary micro-OLED supply chains that feed multiple regional headset manufacturers. ByteDance competes aggressively on software ecosystem breadth, integrating AR creation tools with its content distribution infrastructure.
Asia-Pacific Augmented Reality and Mixed Reality encompasses computer-generated perceptual information overlaid onto or merged with physical environments through optical see-through or video see-through displays, typically requiring sub-20 millisecond motion-to-photon latency to prevent user discomfort. These systems serve industrial visualization, remote assistance, and immersive training by rendering contextual data spatially locked to real-world coordinates. Head-mounted displays command the dominant margin pool due to precision optics complexity and enterprise willingness to pay for ergonomic all-day wearability, while handheld devices represent the highest volume trajectory as smartphone-tethered AR lowers entry barriers for retail and education deployments. Enterprise end users currently absorb the majority of systems integration revenue, though consumer gaming applications are accelerating fastest in South Korea and Japan.
Japan's METI promotes cross-industry XR standards through its Society 5.0 framework, while China's MIIT mandates electromagnetic compatibility and eye-safety testing for near-eye display devices entering commercial channels. South Korea's MFDS regulates AR-based medical visualization tools as Class II software devices, creating compliance hurdles for healthcare market entry. Stakeholders must monitor divergent national certification timelines and prioritize modular hardware architectures that adapt to fragmented regulatory requirements across the region.
Market Dynamics
Japan's Society 5.0 framework is compressing certification timelines for spatial computing hardware, forcing manufacturers to modularize optical architectures for simultaneous compliance across multiple national regimes.
Growth Catalysts
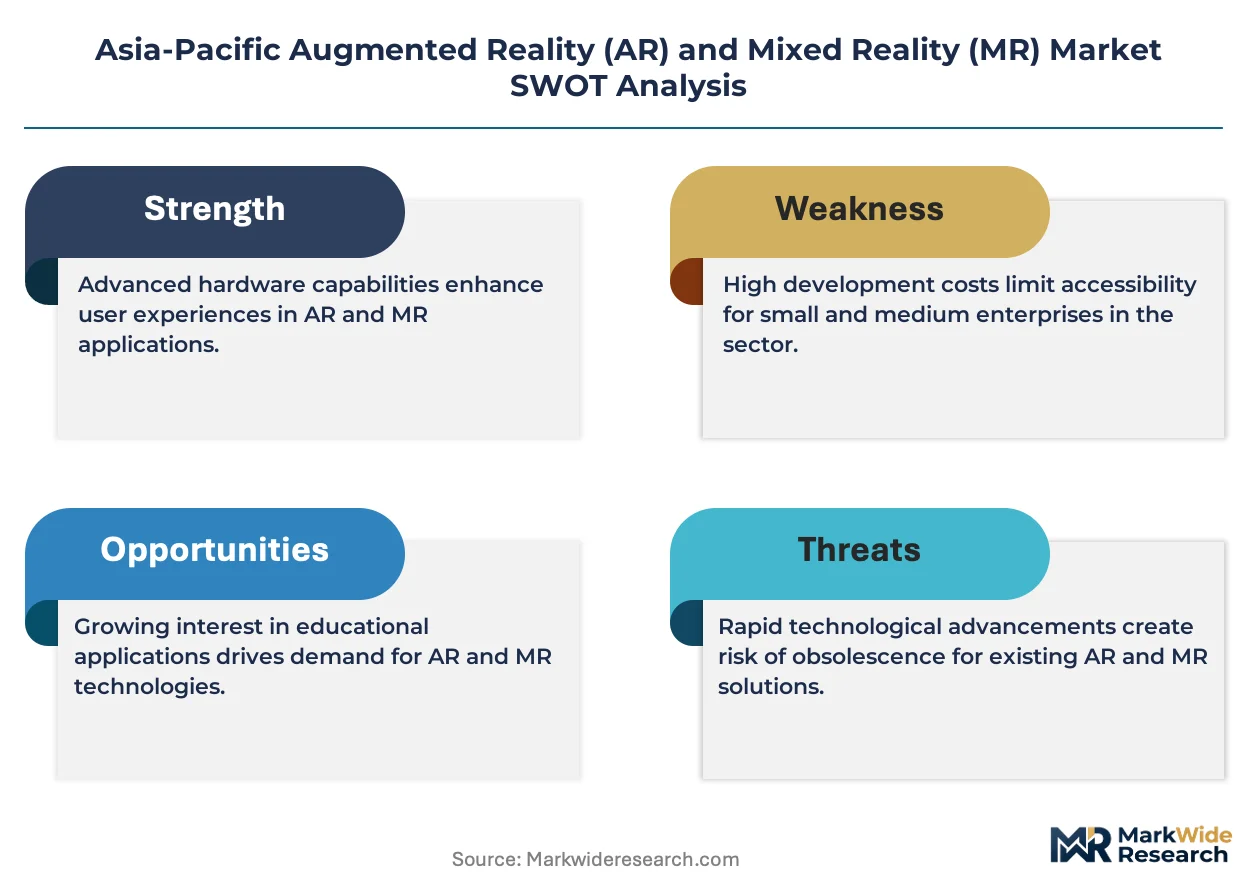
- MIIT Near-Eye Display Standards:China's tightening electromagnetic compatibility and eye-safety testing mandates are accelerating product quality differentiation, pushing domestic manufacturers toward precision optical engineering investments.
- Surgical Training Visualization:Japanese healthcare providers are deploying AR-guided instruction modules for complex procedures, creating sustained demand for sub-20 millisecond latency systems.
- Manufacturing Quality Control:South Korean electronics assemblers are integrating mixed reality inspection stations across production floors, generating enterprise hardware procurement cycles.
Market Restraints
- Micro-OLED Supply Concentration:Proprietary optical component supply chains centered on Japanese and Taiwanese manufacturers create bottleneck risks for headset producers scaling beyond niche volumes.
- MFDS Medical Software Classification:South Korea's Class II device regulations impose extended validation timelines on AR-based surgical visualization tools, delaying healthcare market penetration.
- Motion-to-Photon Latency Thresholds:Sub-20 millisecond performance requirements demand specialized sensor fusion hardware, elevating bill-of-materials costs beyond mass-market price elasticity.
Strategic Opportunities
- Enterprise Remote Assistance:Untapped deployment potential exists across Southeast Asian logistics networks, where field technician support gaps favor AR-enabled expert guidance systems.
- Content Distribution Convergence:Integration of AR creation tools with short-form video platforms is electrifying consumer education applications, lowering creator entry barriers.
- Cross-Border Standards Harmonization:METI-led regional alignment initiatives could reduce fragmented certification burdens, enabling modular hardware platforms to serve multiple national markets from single production bases.
Industry Challenges
- Optical Engineering Talent Scarcity:Precision waveguide design and micro-display calibration expertise concentrates in Japanese and Taiwanese research clusters, constraining workforce scaling for new market entrants.
- Legacy System Integration:Industrial AR deployments require seamless interoperability with existing manufacturing execution systems, creating protracted customization cycles and implementation risk.
- Multi-Regulatory Certification Pipelines:Simultaneous navigation of China's GB standards, Japan's JIS frameworks, and South Korea's KC marking creates timeline fragmentation for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market |
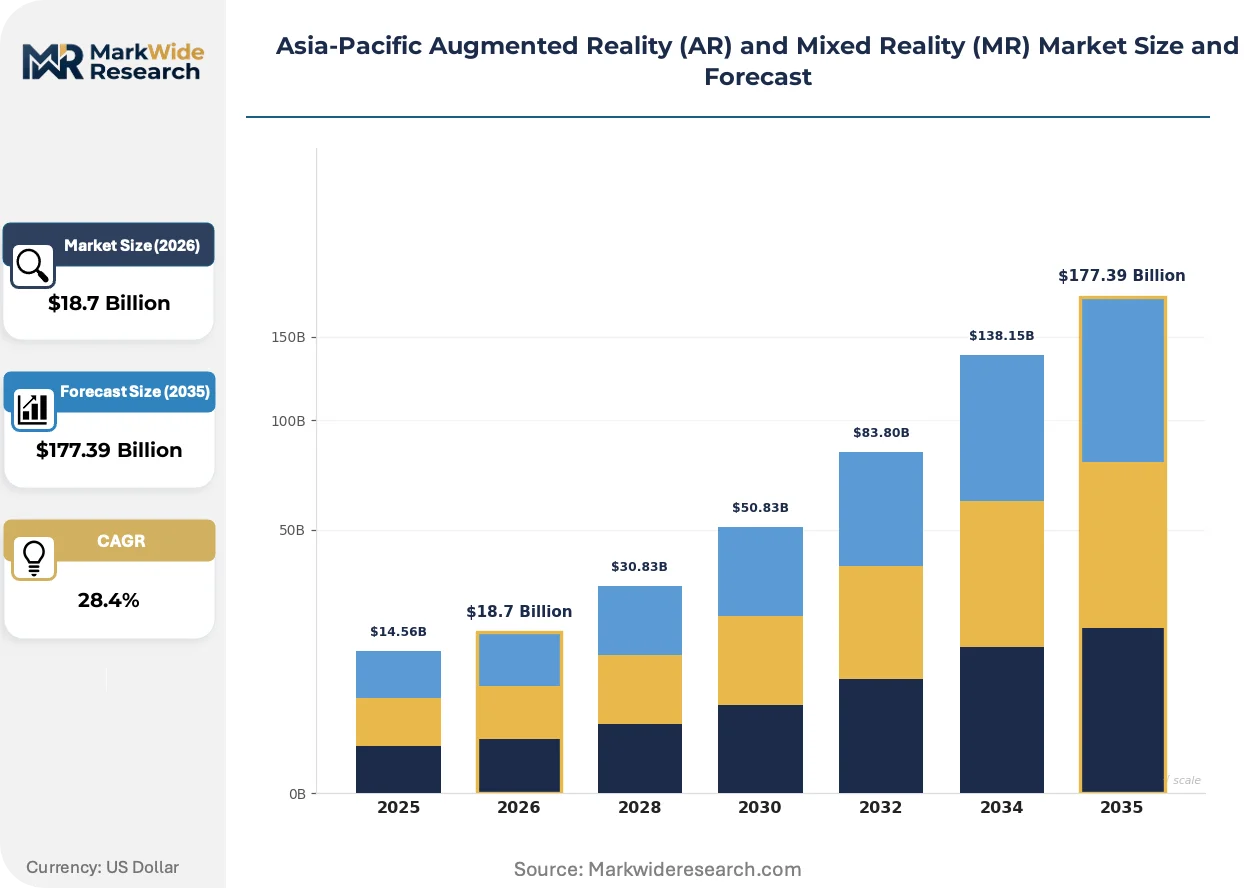
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Handheld Devices, Wearable Displays, Head-Mounted Displays Application: Gaming, Education, Healthcare, Retail Technology: Marker-Based, Markerless, Projection-Based, Superimposition End User: Enterprises, Consumers, Government, Educational Institutions |
| Companies Covered | HTC Corporation, Seiko Epson Corporation, Sony Corporation, Maxst Co., LTD., Lenovo, ByteDance, Samsung, Huawei, DPVR, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market Strategic Shifts
Spatial computing hardware is bifurcating into industrial-grade head-mounted systems and smartphone-tethered handheld devices, with software ecosystems determining competitive differentiation more than optical specifications alone.
Micro-OLED display technology is electrifying enterprise headset performance through self-emissive pixel architectures that eliminate backlight layers, enabling higher luminance in compact form factors. Japanese precision manufacturers are adopting these panels for all-day wearable inspection systems. The technology is electrifying margin structures by commanding premium pricing for ergonomic, thermally efficient designs.
METI's cross-industry XR standardization initiatives are mandating interoperable spatial anchoring protocols across Japanese industrial consortia. This regulatory pressure is fragmenting proprietary ecosystem strategies among platform providers. Healthcare and manufacturing verticals are responding by demanding hardware-agnostic software licenses to preserve procurement flexibility.
Enterprise procurement patterns are consolidating around integrated solution contracts bundling hardware, software licenses, and training services. System integrators are displacing standalone device distributors in South Korean manufacturing verticals. This shift is most visible in automotive assembly networks, where total-cost-of-ownership calculations favor multi-year service agreements over capital expenditure purchases.
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market Segmentation
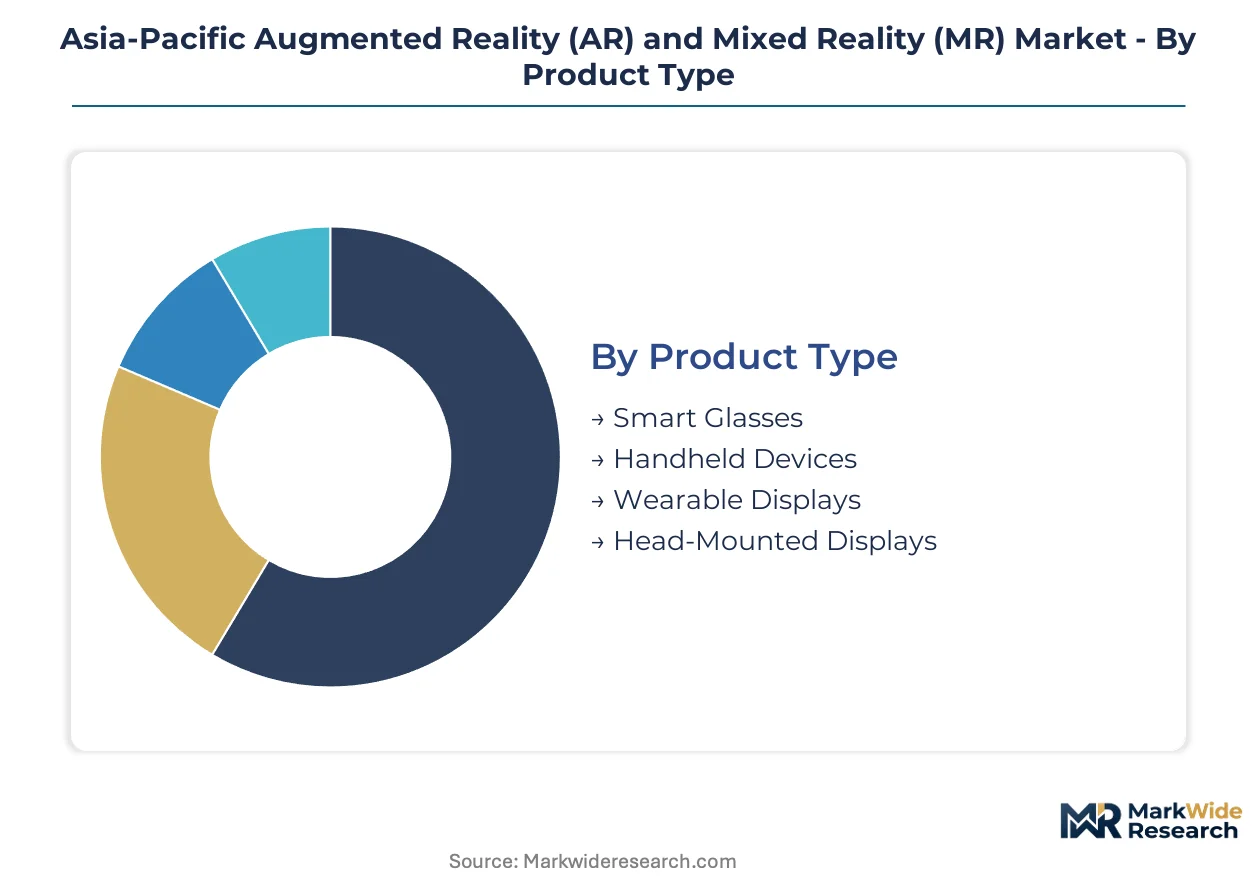
Hardware form factors and software integration depth vary dramatically across deployment contexts in Asia-Pacific spatial computing. Procurement patterns split between precision-engineered enterprise systems and volume-oriented consumer devices, with regulatory compliance requirements further complicating cross-border standardization.
Product Type:
Customization intensity spans from fully configurable optical engines to mass-produced smartphone peripherals across this hardware taxonomy.
- Head-Mounted Displays:Precision optical waveguide assemblies with sub-20 millisecond motion-to-photon latency dominate enterprise training and surgical visualization deployments in Japan. Japanese healthcare providers and South Korean electronics manufacturers absorb the majority of premium-tier procurement volumes.
- Smart Glasses:Lightweight monocular or binocular designs tether to edge computing infrastructure for logistics and field service applications. Demand concentrates in Southeast Asian warehouse networks where hands-free barcode scanning and remote expert guidance reduce technician error rates.
- Handheld Devices:Smartphone-dependent AR experiences leverage existing device penetration for retail and education mass-market deployment.
- Wearable Displays:Chest-worn or belt-clip projection systems serve niche industrial inspection workflows requiring peripheral vision preservation.
Most installed capacity flows through Head-Mounted Displays. Expansion is steepest in Smart Glasses.
Application:
Revenue concentration shifts toward vertical-specific software stacks rather than horizontal platform plays across these use-case clusters.
- Healthcare:AR-guided surgical training and preoperative visualization systems command premium pricing in Japanese academic medical centers. South Korea's MFDS Class II software classification creates compliance friction that filters out non-specialized vendors.
- Gaming:Location-based entertainment venues and mobile AR titles drive consumer hardware attachment in South Korea and Japan.
- Education:K-12 STEM visualization and vocational training modules spread through government procurement channels.
- Retail:Virtual try-on and spatial merchandising tools deploy through franchise networks seeking differentiation against pure e-commerce competitors.
Healthcare absorbs the highest average selling prices. Gaming claims the largest cumulative unit volumes.
Technology:
Tracking fidelity requirements and environmental robustness tradeoffs differentiate these spatial computing architectures.
- Markerless:Simultaneous localization and mapping (SLAM) systems enable unconstrained indoor-outdoor operation without physical fiducial deployment. Japanese industrial consortia under METI's Society 5.0 framework are standardizing interoperable spatial anchoring protocols for these systems.
- Marker-Based:Visual fiducial recognition delivers centimeter-accurate registration for controlled manufacturing and laboratory environments. South Korean automotive assembly lines specify these systems for quality control stations where lighting conditions remain constant.
- Projection-Based:Spatial light modulation projects synthetic imagery directly onto physical surfaces without user-worn optics.
- Superimposition:Object recognition overlays contextual data onto identified real-world artifacts for maintenance and repair workflows.
Markerless systems command the steepest R&D investment trajectories. Marker-Based retains the largest installed base in industrial settings.
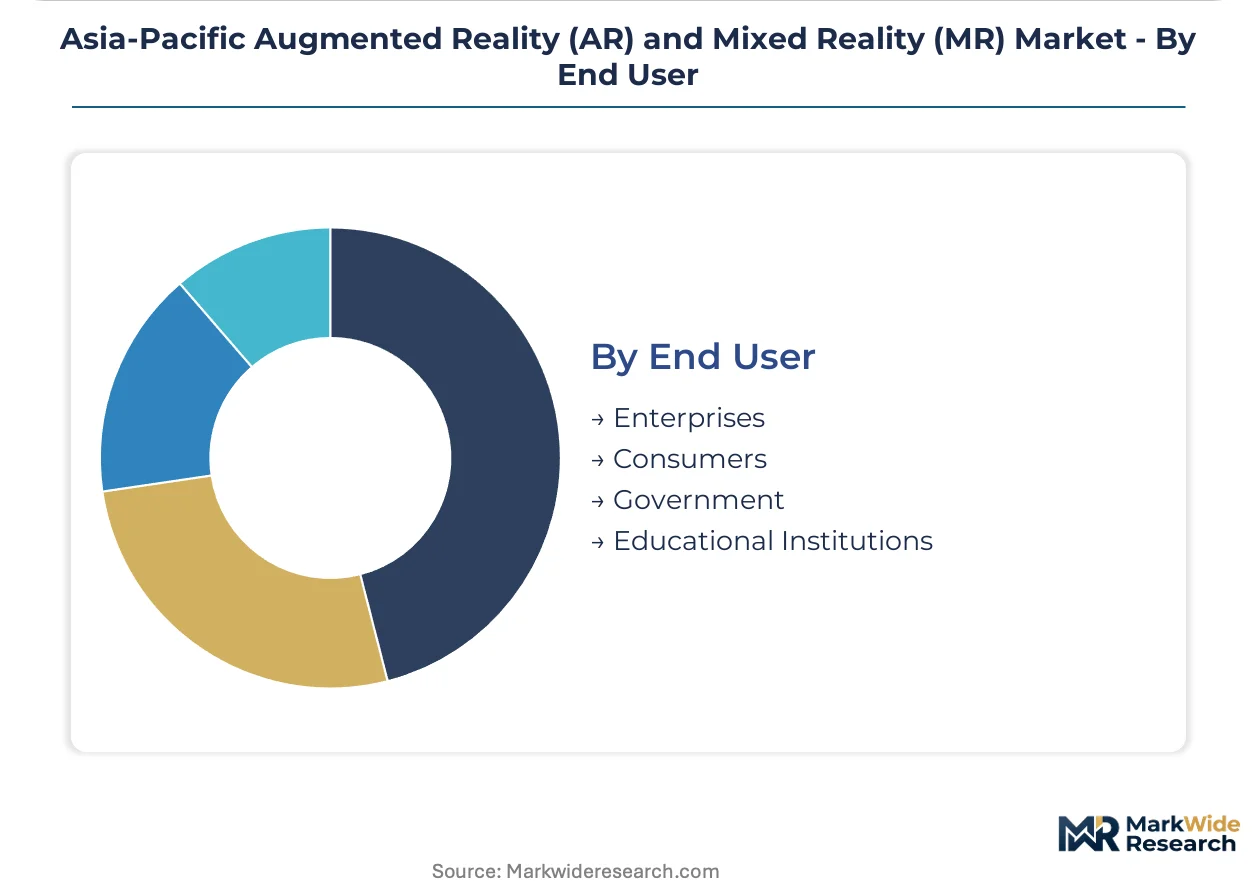
End User:
Procurement authority and budget cycle predictability separate these demand constituencies.
- Enterprises:Multi-year total-cost-of-ownership contracts bundle hardware, software licenses, and training services. South Korean manufacturing verticals favor integrated solution procurement over standalone device purchases.
- Consumers:Price-sensitive adoption flows through content platform ecosystems rather than dedicated hardware marketing.
- Government:Defense and public safety applications specify ruggedized variants with classified data handling certifications.
- Educational Institutions:Ministry-funded pilot programs drive batch procurement with extended evaluation timelines.
Enterprises generate the highest service attach rates. Consumers represent the volume expansion frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent clusters in Japanese and Taiwanese research centers anchor regional supply capacity, while South Korean system integrators and Chinese platform developers compete on deployment scale and software ecosystem breadth.
Japan
Healthcare providers in Tokyo and Osaka academic medical centers deploy AR-guided surgical training modules for complex procedures. METI's Society 5.0 framework compresses certification timelines for spatial computing hardware through cross-industry XR standardization. Precision manufacturers in the Chubu region around Nagoya adopt micro-OLED panels for all-day wearable inspection systems.
China
Domestic manufacturers accelerate precision optical engineering investments to meet tightening product certification requirements. MIIT mandates electromagnetic compatibility and eye-safety testing for near-eye display devices entering commercial channels. Shenzhen and Beijing hardware clusters focus on modular optical architectures enabling simultaneous compliance across multiple national regimes.
South Korea
Samsung and local system integrators deploy mixed reality systems for assembly line quality control across electronics manufacturing campuses. MFDS regulates AR-based medical visualization tools as Class II software devices, creating compliance hurdles for healthcare market entry. The Seoul Capital Area concentrates enterprise procurement of integrated solution contracts bundling hardware, software licenses, and training services.
Taiwan
HTC Corporation leverages its Vive enterprise platform to anchor high-fidelity training simulations across electronics factories in Hsinchu and Taichung. Proprietary micro-OLED supply chains centered on Taiwanese and Japanese manufacturers create bottleneck risks for headset producers scaling beyond niche volumes. The island's precision optics ecosystem feeds multiple regional headset manufacturers with optical component supply.
Australia
Enterprise remote assistance deployments remain underpenetrated across logistics networks, where field technician support gaps favor AR-enabled expert guidance systems. TGA regulates medical device software classifications with alignment to international harmonization frameworks. Sydney and Melbourne technology consultancies pilot smartphone-tethered AR for retail and education mass-market deployment.
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market Competitive Environment
Top-tier vendors anchor precision optical component supply, while mid-tier system integrators and software platform developers compete on vertical solution bundling. The vendor base stratifies across three archetypes: optical component specialists controlling micro-display supply chains, enterprise platform providers monetizing through multi-year service agreements, and consumer ecosystem operators leveraging content distribution infrastructure. Strategic moves concentrate on modular hardware architectures for multi-regulatory compliance and integrated solution contracts displacing standalone device distribution.
Within the optical component tier, Sony Corporation and Seiko Epson Corporation exemplify supply-side concentration through proprietary display technologies. HTC Corporation anchors the enterprise platform vector, while ByteDance occupies a position exemplifying content ecosystem competition. Samsung sits within the integrated hardware-software archetype, representing scale-driven manufacturing capacity. These three groupings—Japanese precision optics, Taiwanese enterprise systems, and Chinese platform operators—structure competitive positioning across the regional landscape.
| Leading Market Players |
|---|
| HTC Corporation |
| Seiko Epson Corporation |
| Sony Corporation |
| Maxst Co., LTD. |
| Lenovo |
| ByteDance |
| Samsung |
| Huawei |
| DPVR |
| Others |
Value Chain & Pricing Dynamics
METI's Society 5.0 sustainability mandates gate qualified micro-OLED supply and premium-tier pricing access for industrial-grade spatial computing hardware. Japanese precision manufacturers command pricing power through proprietary display technologies that meet sub-20 millisecond latency thresholds, while commodity handheld AR devices face margin compression from smartphone-tethered alternatives.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes enterprise procurement from consumer transactions. Integrated solution contracts bundling hardware, software licenses, and training services command premium positioning in South Korean manufacturing verticals, while standalone device distribution faces price erosion. Price differentiation rests on certification tier—MIIT electromagnetic compliance and MFDS Class II medical software classification—and customization depth for legacy manufacturing execution system integration. Cost compression in smartphone-tethered handheld tiers intensifies as ByteDance and domestic Chinese platforms subsidize hardware to capture content ecosystem share. Enterprise buyers show lowest price sensitivity due to total-cost-of-ownership calculations, while educational institutions and retail franchises exhibit highest elasticity.
Supply Chain Analysis
Freight cost volatility from Taiwanese and Japanese optical component clusters elevates landed costs for headset manufacturers scaling beyond niche volumes. Micro-OLED display supply concentrates in Japan and Taiwan, with waveguide calibration expertise anchored in Hsinchu and Nagoya research centers. Raw material dependencies span rare-earth phosphors for self-emissive pixels, precision glass substrates, and electromagnetic shielding alloys. Single-source vulnerability from proprietary Sony and Seiko Epson display architectures creates bottleneck risks for regional headset producers. Distribution runs through system integrators in Seoul and Shenzhen, displacing standalone device distributors with multi-year service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways as micro-OLED cost curves decline and enterprise buyers shift from capital expenditure to subscription-based procurement models.
For Market Incumbents: Anticipate regulatory fragmentation across China's MIIT, Japan's METI, and South Korea's MFDS by modularizing optical architectures for simultaneous multi-national compliance. Deepen backward integration into precision waveguide manufacturing to defend against emerging Chinese optical engineering investments. Prioritize certification pipeline capacity to compress product launch timelines as cross-border standards harmonization stalls. For New Entrants and Emerging Players: Markerless SLAM software stacks offer a technology-first wedge into Southeast Asian logistics networks where field technician support gaps remain unaddressed by incumbent platforms. Target warehouse and remote assistance deployments in Australia and Vietnam where enterprise AR penetration lags manufacturing-intensive markets. Pursue hardware-agnostic software licensing to circumvent micro-OLED supply concentration and accelerate time-to-revenue. For Investors and Strategic Acquirers: Roll-up economics work for enterprise platform specialists because South Korean manufacturing verticals are consolidating procurement around integrated solution providers with multi-year service track records. The 5-10 year viability window favors vendors with captive optical component relationships or software-defined differentiation. Monitor METI-led regional standards alignment initiatives as an inflection signal—successful harmonization would enable modular hardware platforms to serve multiple national markets from single production bases, restructuring competitive economics for scale players.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ByteDance's AR creation tools embedded in content distribution infrastructure capture creator economies across Chinese education verticals. |
| Backward Integration | HTC's captive waveguide manufacturing in Taichung reduces dependency on Japanese optical component supply bottlenecks. |
| Regulatory Certification Investment | Samsung's MFDS Class II software validation accelerates healthcare market entry against non-specialized competitors. |
| Strategic Partnership | Sony's micro-OLED supply agreements with multiple regional headset manufacturers monetize optical dominance without direct systems competition. |
| Geographic Expansion | Enterprise remote assistance deployments in Australian logistics networks address underpenetrated technician support gaps with lower competitive intensity. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with hardware engineering directors at Taiwanese and Japanese optical manufacturers, enterprise procurement leads at South Korean electronics assemblers, regulatory affairs specialists navigating MIIT and MFDS frameworks, and software platform architects at Chinese content distributors. Secondary validation drew from MIIT near-eye display standard filings, METI Society 5.0 framework documentation, MFDS medical software classification databases, and hyperscaler AR capex disclosures. Bottom-up component cost modeling and top-down enterprise spending surveys were triangulated against installation base estimates.
Historical reference periods anchored the projection horizon through comparable-period analysis of spatial computing hardware adoption cycles in industrial training and surgical visualization verticals. The analytical framework modeled segmentation across hardware form factor, application vertical, tracking technology architecture, and end-user procurement authority, with particular attention to enterprise solution bundling patterns. CAGRs were derived from installed base growth trajectories and average selling price evolution across premium head-mounted and volume handheld tiers. Industry-specific inputs included motion-to-photon latency compliance costs and cross-border certification timeline fragmentation.
The model holds under stable regulatory divergence across national regimes; deviation in METI-led standards harmonization success or MIIT certification timeline compression would shift competitive positioning toward modular hardware specialists. Forecasts reflect assumptions of sustained micro-OLED supply concentration and enterprise subscription procurement adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market