
 Global Augmented Reality Headsets Market | 2026-2036
Global Augmented Reality Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented Reality Headsets Market Analysis
Market Dynamics
Supply chain sourcing for optical waveguide components is consolidating around a smaller set of qualified foundries as device makers abandon multi-source strategies for critical displays. Microsoft Corporation leverages its HoloLens enterprise installed base to sustain defense and industrial contracts across NATO-aligned procurement frameworks. Meta Platforms, Inc. anchors its Reality Labs division with heavy R&D commitments despite near-term losses on consumer hardware. Apple Inc. differentiates through proprietary silicon-software integration and premium pricing architecture.
Technology and Segmentation
Augmented reality headsets are wearable computing devices that overlay digital information onto the physical world through transparent or pass-through displays, typically employing waveguide optics with field-of-view specifications between 30 and 50 degrees for enterprise-grade units. Their primary commercial purpose spans remote assistance, surgical navigation, immersive training, and spatial computing workflows. Head-mounted displays lead current revenue contribution due to enterprise deployment scale, while smart glasses compete for fastest trajectory as weight and battery constraints resolve. Healthcare application demand concentrates where FDA-cleared surgical navigation systems command premium reimbursement pathways.
Regulatory Environment
FDA premarket notification requirements for AR-guided surgical devices and FCC radio equipment authorization for millimeter-wave connectivity modules create dual compliance burdens for manufacturers targeting the United States. The EU AI Act risk-classification framework and CE marking under the MDR impose additional conformity costs for headsets deployed in European healthcare settings. EMA coordination with notified bodies on software-as-medical-device determinations further complicates cross-border product registration. Stakeholders must monitor evolving electromagnetic exposure limits and biocompatibility standards for prolonged skin contact before committing regional launch sequencing.
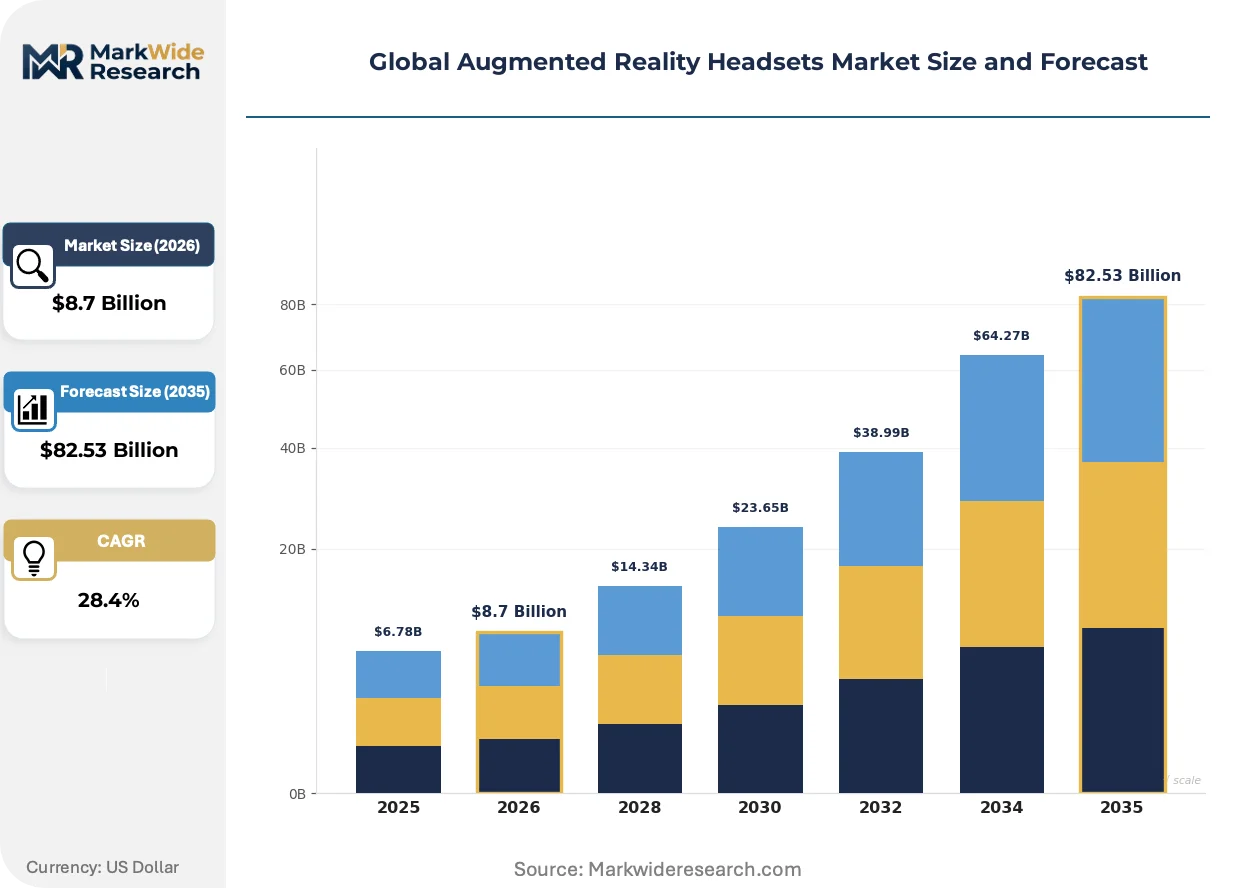
Market Dynamics
Optical waveguide foundry consolidation is compressing supplier options for AR headset manufacturers, forcing device makers toward single-source dependencies for critical display components and reshaping procurement risk profiles across the value chain.
Growth Catalysts
- Enterprise manufacturing deployment:Assembly line digitization in automotive and aerospace plants is pulling AR headsets into quality assurance and guided workflow applications, with Germany and the United States building dedicated industrial metaverse testbeds.
- FDA surgical navigation clearance:Premarket notification pathways for AR-guided orthopedic and neurosurgical systems are unlocking premium reimbursement codes in US hospital procurement frameworks.
- EU AI Act implementation:Risk-classification requirements for high-stakes AI systems are accelerating validation investments by headset vendors targeting European healthcare settings, creating competitive moats for early certifiers.
Market Restraints
- Waveguide input concentration:Lithography-grade glass substrates and precision embossing equipment for surface relief gratings concentrate among Taiwanese and Korean material suppliers, exposing device makers to geopolitical supply interruptions.
- Millimeter-wave module costs:FCC-authorized radio components for low-latency wireless tethering carry 40-60% premiums over unlicensed alternatives, compressing margin structures in price-sensitive enterprise tenders.
- Battery energy density ceiling:Lithium-polymer cell chemistry limits currently constrain all-day wearability in smart glasses form factors below 80 grams, restricting addressable use cases.
Strategic Opportunities
- Indian industrial training:PLI scheme subsidies for electronics manufacturing and CDSCO regulatory harmonization efforts are positioning India as an underpenetrated deployment zone for technician upskilling applications.
- EMA software-as-medical-device coordination:Streamlined notified body determinations for AR surgical systems across EU member states offer registration pathway advantages for vendors with existing MDR infrastructure.
- Spatial computing-robotics convergence:Integration of AR visualization with collaborative robot programming interfaces is opening new application layers in precision manufacturing verticals.
Industry Challenges
- Optical engineering talent scarcity:Waveguide design and pupil expansion optimization require specialized photonics expertise that outpaces current graduate program output in the United States and Germany.
- Multi-jurisdiction certification timelines:Simultaneous FDA 510(k), CE MDR, and NMPA registration for surgical AR systems extends commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented Reality Headsets Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Head-Mounted Displays, Handheld Devices, Smart Helmets Application: Gaming, Retail, Education, Healthcare End User: Enterprises, Consumers, Educational Institutions, Healthcare Providers Technology: Marker-Based, Markerless, Projection-Based, Superimposition |
| Companies Covered | Microsoft Corporation, Meta Platforms, Inc., Apple Inc., Magic Leap, Inc., XREAL, Vuzix Corporation, Lenovo Group Limited, Google LLC, Sony Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented Reality Headsets Market Emerging Trajectories
Waveguide optics technology is consolidating market structure as manufacturers abandon refractive lens architectures. Regulatory divergence between FDA and EMA pathways is fragmenting go-to-market strategies. Procurement behavior is hardening around certification-driven supplier qualification.
Diffractive waveguide architectures are consolidating technical roadmaps across the AR headset industry. These nanostructured surface relief gratings expand eyeboxes while thinning optical stacks. Automotive HUD suppliers and surgical device manufacturers are adopting the technology fastest. Single-source dependencies on qualified embossing foundries is consolidating pricing power upstream.
The EU AI Act risk-classification framework is reshaping product development cycles for European healthcare deployments. High-risk AI system designations trigger mandatory conformity assessments and post-market monitoring obligations. Surgical navigation headset vendors are responding by front-loading clinical validation investments and restricting feature sets to pre-certified functionality bundles.
Hospital procurement committees are tightening vendor qualification around simultaneous FDA clearance and CE marking status. Large health system tenders in the United States now require dual-certification as a baseline eligibility filter. This behavioral shift is compressing competitive sets to established medical device incumbents and excluding consumer-electronics entrants lacking regulatory infrastructure.
Global Augmented Reality Headsets Market Segmentation
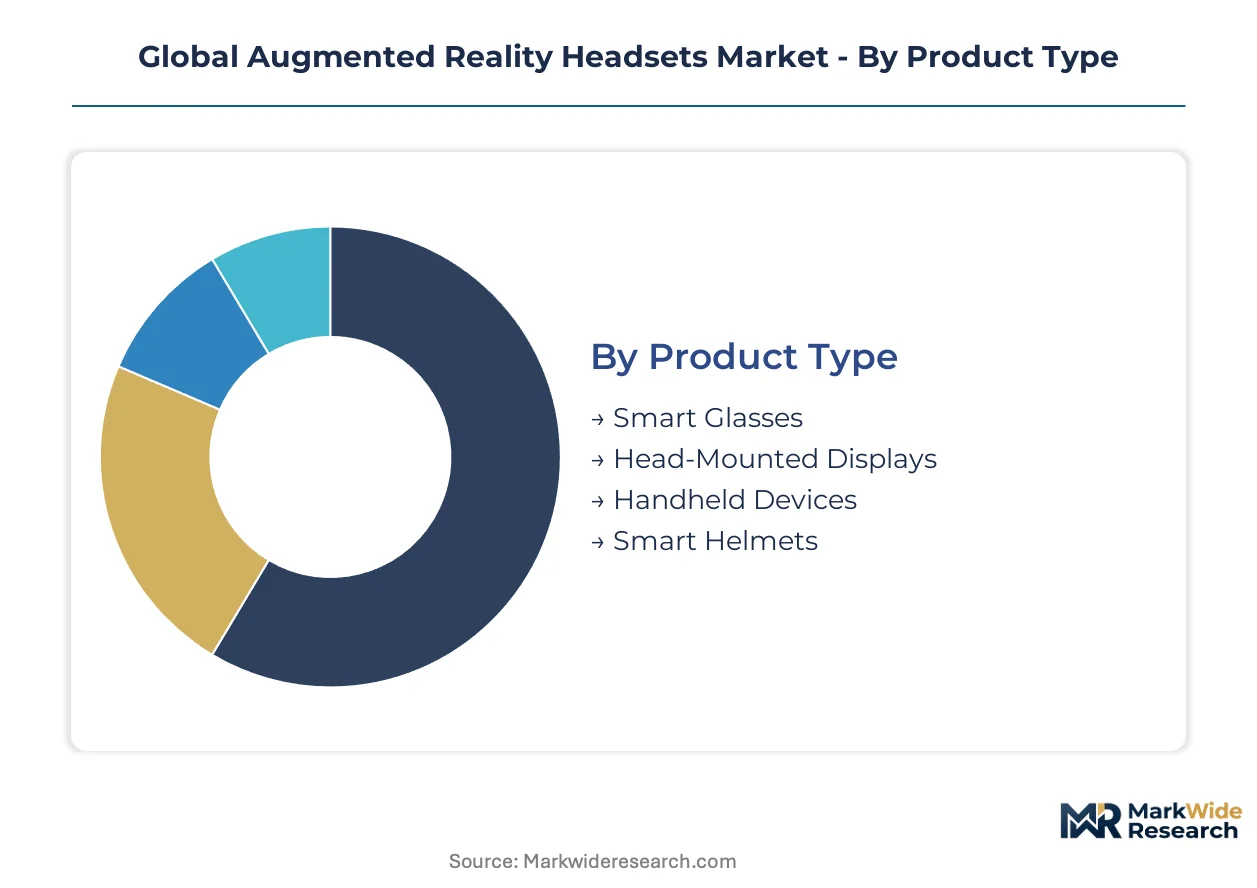
AR headset purchasing decisions hinge on form-factor tradeoffs between optical performance and wearability, with procurement committees weighting field-of-view specifications against battery endurance and total cost of ownership across deployment scales.
Product Type:
Enterprise buyers prioritize display fidelity and thermal management over consumer-grade aesthetics, driving specification divergence between industrial deployments and personal use cases.
- Head-Mounted Displays:These tethered or standalone units integrate waveguide optics with 30-50 degree fields-of-view and active cooling systems for sustained operation. Manufacturing assembly lines in Germany and the United States anchor procurement volume, pulled by guided workflow digitization mandates in automotive and aerospace plants.
- Smart Glasses:Lightweight sub-80 gram designs employing micro-LED or laser-scanning projection sacrifice immersion for all-day wearability. Demand concentrates among field service technicians in the United States where remote assistance applications justify per-unit premiums through reduced truck-roll costs.
- Smart Helmets:Integrated hard-hat form factors combine impact protection with monocular or binocular overlays for construction and energy sector deployments.
- Handheld Devices:Smartphone-tethered viewers and tablet-based AR viewers serve occasional-use scenarios where dedicated headset procurement cannot be justified.
Volume sits with Head-Mounted Displays; growth tilts toward Smart Glasses.
Application:
Reimbursement pathway availability and regulatory clearance status determine healthcare procurement velocity, while gaming and retail deployments track consumer hardware refresh cycles.
- Healthcare:Surgical navigation systems command premium positioning through FDA-cleared orthopedic and neurosurgical applications, with hospital procurement committees requiring simultaneous CE marking under MDR for vendor qualification. German university hospitals and US academic medical centers lead adoption.
- Gaming:Consumer entertainment applications drive volume through mobile-tethered and standalone headsets, constrained by content library depth and developer ecosystem maturity.
- Education:Immersive training modules for vocational and medical instruction see procurement from Indian technical institutes under PLI scheme subsidies and CDSCO regulatory harmonization efforts.
- Retail:Virtual try-on and spatial merchandising applications serve flagship store deployments rather than fleet rollouts, limiting addressable market scale.
Procurement volume clusters in Healthcare; Education offers the steepest expansion trajectory.
End User:
Budget authority and deployment scale separate enterprise procurement frameworks from individual purchasing decisions, with institutional buyers demanding multi-year support commitments and certification documentation.
- Enterprises:Manufacturing, logistics, and energy sector deployments specify MIL-STD-810G durability ratings and ISO 13485 quality management for medical adjacent applications. NATO-aligned defense contracts through Microsoft sustain this segment's revenue concentration.
- Healthcare Providers:Hospital systems and ambulatory surgical centers require FDA 510(k) or De Novo clearance for surgical navigation headsets, with procurement committees filtering on dual-certification status.
- Educational Institutions:Vocational training centers and medical schools pilot AR modules for technician upskilling and surgical resident education.
- Consumers:Individual purchasers respond to content ecosystem depth and social platform integration rather than raw optical specifications.
Enterprises dominate current volume; Healthcare Providers are climbing the fastest.
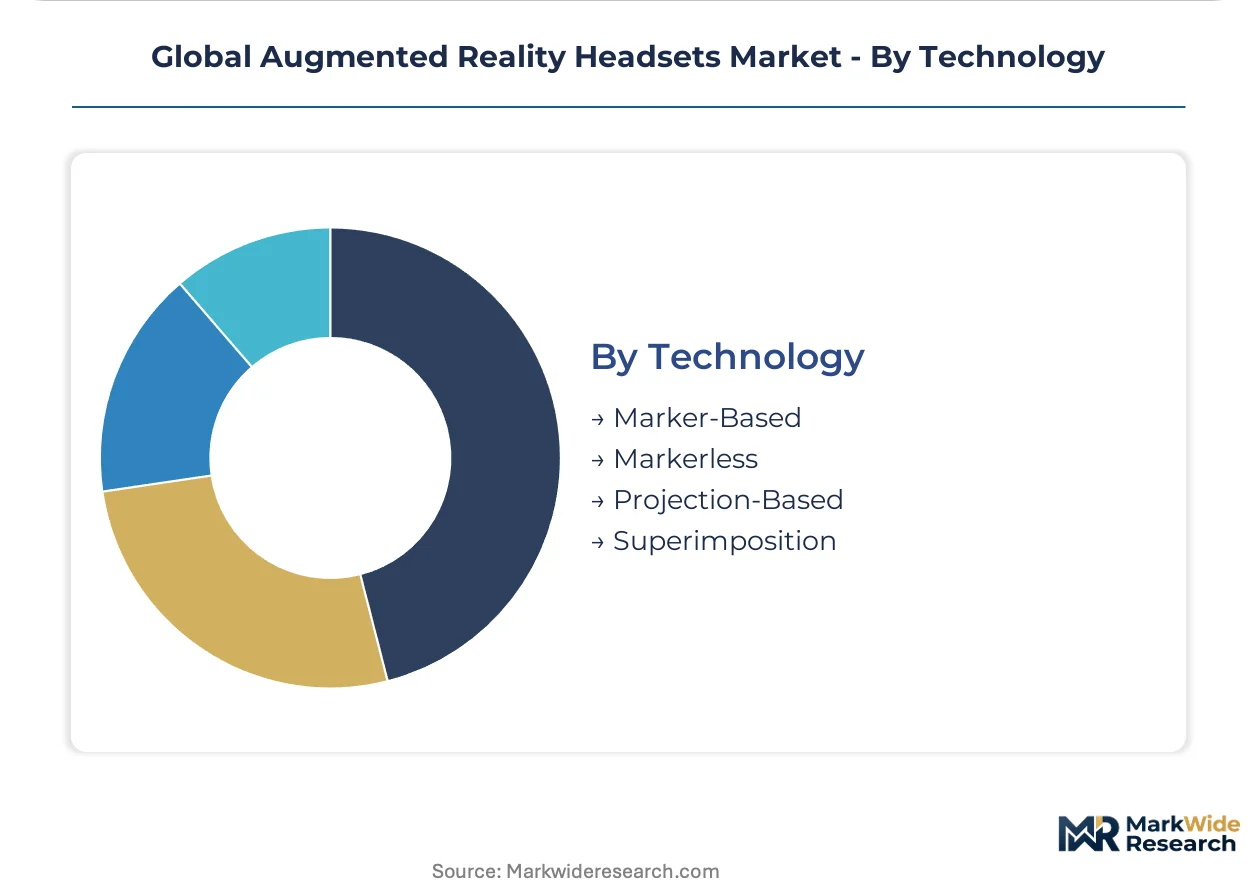
Technology:
Tracking precision and environmental robustness determine technology selection, with outdoor and industrial deployments favoring markerless approaches despite higher computational requirements.
- Markerless:SLAM-based spatial mapping and inside-out tracking enable operation in uncontrolled environments without fiducial placement. Manufacturing floors in the United States and Germany deploy these systems for dynamic assembly guidance where physical markers would obstruct workflows.
- Marker-Based:Image recognition of printed or projected fiducials delivers sub-millimeter registration accuracy for surgical navigation and precision assembly applications.
- Projection-Based:Spatial augmented reality projects digital content directly onto physical surfaces without wearable optics, serving collaborative design review scenarios.
- Superimposition:Object recognition overlays digital models onto detected physical items, applied in maintenance and repair guidance.
Markerless systems capture procurement volume; Marker-Based retains position in regulated surgical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithography-grade glass substrate foundries in Taiwan and Korea anchor optical waveguide supply chains, while device assembly and enterprise deployment concentrate in industrial clusters across the United States, Germany, and China.
United States
Defense procurement through NATO-aligned frameworks and FDA-cleared surgical navigation systems drive headset demand. FCC radio equipment authorization for millimeter-wave modules shapes product development timelines. Greater Boston and Seattle-Tacoma host concentrated enterprise pilot programs in manufacturing assembly guidance.
Germany
Automotive and aerospace digitization mandates pull AR headsets into quality assurance workflows. EU AI Act risk-classification requirements accelerate validation investments for healthcare deployments. Bavaria's industrial metaverse testbeds anchor manufacturing adoption clusters around Munich and Nuremberg.
China
NMPA registration pathways and MIIT standards for wearable devices structure domestic market entry. Dual carbon goals pressure energy sector adoption for remote inspection applications. Yangtze River Delta electronics manufacturing corridors supply waveguide components to global device makers.
India
PLI scheme subsidies for electronics manufacturing and CDSCO regulatory harmonization attract training-focused deployments. Technician upskilling applications in vocational institutes drive procurement volume. Karnataka and Telangana host pilot programs for industrial AR instruction modules.
South Korea
MFDS medical device clearance and SAMR-coordinated standards facilitate cross-border healthcare product registration. Precision embossing equipment for surface relief gratings concentrates among domestic material suppliers. Seoul Capital Area anchors display technology R&D clusters serving global headset manufacturers.
Global Augmented Reality Headsets Market Vendor Landscape
Strategic partnerships dominate the current landscape as device makers secure single-source waveguide supply commitments and defense contractors lock in multi-year procurement frameworks. The vendor base stratifies across three tiers: silicon-software integrators with proprietary chip architectures, enterprise-focused systems houses with regulatory infrastructure, and component specialists supplying optical engines. Two competitive vectors define positioning: backward integration into waveguide foundry capacity, and geographic expansion into Indian and Southeast Asian training markets.
Within the enterprise-systems tier, Microsoft Corporation exemplifies the defense-industrial complex archetype through NATO-aligned procurement sustainment. Meta Platforms, Inc. occupies the scale-driven R&D commitment position despite near-term hardware losses. Apple Inc. anchors the premium-tier vector through proprietary silicon-software integration and pricing architecture that excludes price-sensitive tenders. These three entities collectively represent divergent strategic bets on enterprise versus consumer pathway dominance.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms, Inc. |
| Apple Inc. |
| Magic Leap, Inc. |
| XREAL |
| Vuzix Corporation |
| Lenovo Group Limited |
| Google LLC |
| Sony Group Corporation |
| Others |
Supply Flow & Price Mechanics
Lithography-grade glass substrate costs cascade through waveguide foundry pricing tiers before reaching device makers, with Taiwanese and Korean material suppliers commanding premiums that stratify headset procurement budgets across defense, healthcare, and industrial segments.
Pricing Analysis
Warranty and multi-year service bundling separate enterprise procurement tiers from consumer offerings, with manufacturing buyers demanding ISO 13485-compliant support packages that inflate upfront commitments. Three-tier pricing structure across premium, standard, and economy levels tracks certification density: FDA-cleared surgical systems with CE MDR dual-marking occupy the premium band, while uncertified training headsets compete on unit economics. Pricing pressure stems from millimeter-wave module FCC authorization costs that compress margins in price-sensitive enterprise tenders. Healthcare providers exhibit lowest price sensitivity due to reimbursement pathway capture, whereas vocational training institutes in India operate under strict PLI scheme budget caps.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gates restrict waveguide foundry participation to a narrow qualified supplier base, with device makers facing extended validation timelines for any new optical source. Taiwan, South Korea, and Germany anchor lithography-grade glass and precision embossing equipment supply. Surface relief grating masters and nanoimprint lithography systems draw from specialized photonics equipment manufacturers. Single-source vulnerability concentrates around Taiwanese substrate foundries exposed to geopolitical logistics chokepoints. Distribution runs through direct enterprise sales teams for defense and healthcare contracts, supplemented by systems integrator channels for manufacturing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waveguide foundry capacity scarcity props pricing power upstream, with qualified optical substrate output insufficient to match accelerating enterprise demand across NATO defense contracts and FDA-cleared surgical navigation systems.
For Market Incumbents: Deploy backward integration into captive waveguide embossing capacity to secure supply continuity against Taiwanese foundry concentration risk. Lock multi-year procurement frameworks with NATO-aligned defense contractors before emerging silicon-photonics entrants qualify alternative display architectures. Fortify regulatory infrastructure investments to maintain dual-certification moats that exclude consumer-electronics challengers lacking FDA 510(k) and CE MDR filing capabilities. For New Entrants and Emerging Players: Begin with technician upskilling applications in Indian vocational institutes where CDSCO regulatory harmonization and PLI scheme subsidies lower market entry barriers. Target field service remote assistance in the United States where per-unit premiums justify hardware costs through truck-roll reduction metrics. Pursue partnership-led distribution through industrial systems integrators rather than direct enterprise sales builds. For Investors and Strategic Acquirers: EMA software-as-medical-device coordination announcements are the leading indicator that European healthcare registration pathways are stabilizing for surgical AR vendors. Five-to-ten year viability hinges on waveguide design talent acquisition and regulatory filing infrastructure rather than consumer hardware scale. Prioritize mid-cap optical engine specialists with existing notified body relationships and precision embossing equipment assets.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Foundry Acquisition | Captures scarce lithography-grade glass capacity serving FDA-cleared surgical headset manufacturers. |
| Dual-Certification Fast-Track | Unlocks hospital procurement committee eligibility requiring simultaneous FDA 510(k) and CE MDR status. |
| Indian PLI Scheme Partnership | Accesses subsidized electronics manufacturing capacity for vocational training module deployments. |
| Millimeter-Wave Module Authorization | Secures FCC radio equipment clearance for low-latency wireless tethering in enterprise manufacturing settings. |
| Spatial Computing-Robotics Integration | Opens precision manufacturing verticals through collaborative robot programming interface convergence. |
Methodological Framework
Multi-period observation of waveguide foundry capacity utilization, FDA 510(k) clearance timelines, and NATO defense procurement award patterns anchored the trend analysis, supplemented by interviews with AR headset product managers, optical engineering directors, hospital biomedical equipment committees, and industrial systems integrators. Secondary validation drew from FDA premarket notification databases, EMA MDR certification registries, SEC R&D expenditure disclosures, and EU AI Act implementation guidance documents. Bottom-up unit economics modeling triangulated against top-down enterprise deployment forecasts across manufacturing, healthcare, and defense segments.
Segment-weighting applied differential growth assumptions across head-mounted displays, smart glasses, and smart helmets, with technology trajectories further disaggregated by markerless versus marker-based tracking architectures and regional regulatory cluster patterns. CAGRs derived from installed base expansion rates, replacement cycle compression, and average selling price evolution across certification tiers. Industry-specific forecast inputs incorporated waveguide yield improvement curves and battery energy density constraints affecting all-day wearability thresholds.
Underlying measurement precision varies by segment; FDA-cleared surgical navigation systems carry tighter precision than consumer gaming headsets due to transparent regulatory filing data. Forecasts embed assumptions regarding EU AI Act risk-classification implementation timelines and electromagnetic exposure limit revisions that could accelerate or delay commercialization cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market