
 AR/VR Chip Market | 2026-2036
AR/VR Chip Market Size, Share, and Industry Trends Forecast 2026-2036
AR/VR Chip Market Intelligence
Healthcare surgical planning is hardening as the fastest-rising demand vertical for AR/VR chips, displacing pure gaming dominance. Qualcomm Incorporated leverages its Snapdragon XR platform to anchor wireless headset architectures. NVIDIA Corporation sustains leadership in GPU-intensive rendering pipelines for enterprise visualization. MediaTek Inc competes aggressively on cost-optimized silicon for mid-tier consumer devices.
AR/VR chips are application-specific integrated circuits and system-on-chip designs fabricated at 5nm to 7nm nodes, integrating CPU cores, GPU arrays, dedicated AI accelerators, and low-latency sensor fusion blocks to render stereoscopic imagery with sub-20ms motion-to-photon latency. Graphics chips command the deepest margin pools due to compute intensity and vendor lock-in. Wireless connectivity is the fastest-growing technology segment as tetherless headsets displace wired configurations. Gaming retains volume leadership among applications, though training simulations are closing the gap in enterprise procurement.
The EU AI Act imposes algorithmic transparency mandates on medical AR devices, while the FDA clears surgical navigation headsets through its 510(k) pathway in the United States. REACH and RoHS compliance in Europe restricts hazardous substances in chip packaging materials, adding qualification costs for non-EU foundries. Stakeholders must monitor foundry capacity allocation between AI training chips and AR/VR silicon as process node competition intensifies.
Market Dynamics
Wireless headset architectures are compressing motion-to-photon latency requirements below 20 milliseconds, forcing foundries to reallocate 5nm and 7nm capacity from AI training silicon toward AR/VR system-on-chip designs. This capacity competition between immersive devices and generative AI infrastructure defines current supply-side tension.
Growth Catalysts
- Surgical navigation mandates:The FDA's 510(k) clearance pathway for medical AR headsets accelerates hospital procurement cycles for intraoperative visualization systems.
- EU AI Act transparency requirements:Algorithmic explainability rules for medical devices create compliance-driven replacement cycles for legacy surgical planning hardware.
- Taiwan foundry clustering:Concentrated 3nm pilot line investment at Hsinchu Science Park enables next-generation wireless connectivity integration for tetherless enterprise headsets.
Market Restraints
- Advanced node cost escalation:5nm mask set expenses exceed $15 million per design iteration, constraining mid-tier vendor participation.
- Single-source sensor fusion IP:Consolidated licensing around simultaneous localization and mapping algorithms creates royalty stack inflation for new entrants.
- RoHS substance restrictions:ECHA's REACH annex XVII limitations on lead-based solder alternatives force packaging material requalification timelines extending 18-24 months.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for semiconductor assembly and testing attract module packaging investment away from traditional ASEAN hubs.
- Industrial maintenance convergence:Digital twin overlays combined with haptic feedback gloves create untapped demand from energy sector field technicians.
- Cloud-rendering distribution models:Edge compute partnerships with telecom infrastructure providers enable lightweight client hardware with subscription monetization.
Industry Challenges
- Photonics design talent scarcity:Waveguide optics simulation expertise concentrates among fewer than 200 specialized engineers globally, inflating compensation premiums.
- Cross-regional certification fragmentation:Divergent electromagnetic compatibility testing between FCC Part 15 and CE marking regimes duplicates validation expenditure for each SKU.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR/VR Chip Market |
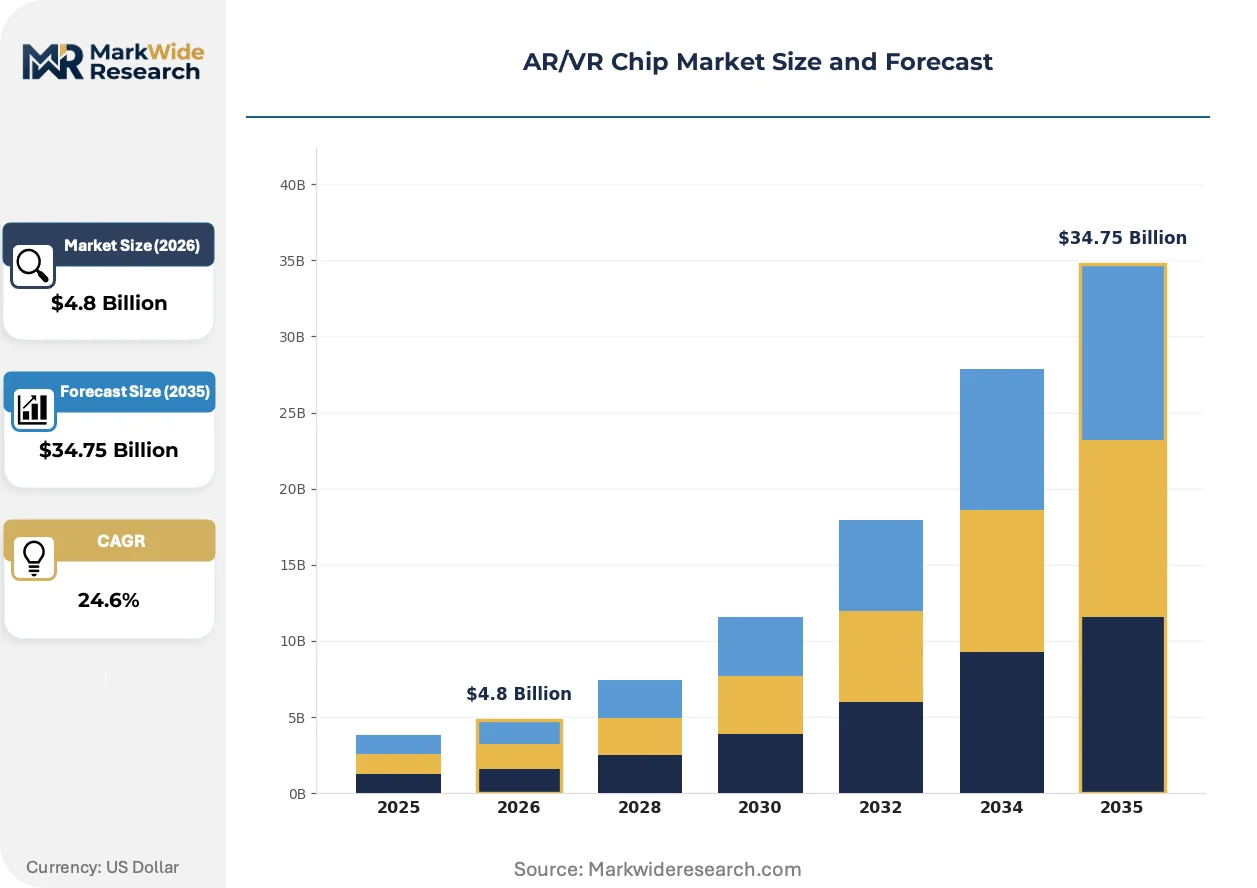
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processors, Graphics Chips, Motion Sensors, Microcontrollers Technology: Optical Tracking, Inertial Tracking, Depth Sensors, Wireless Connectivity Application: Gaming, Education, Training Simulations, Healthcare End User: Consumers, Enterprises, Developers, Research Institutions |
| Companies Covered | Qualcomm Incorporated, NVIDIA Corporation, Intel Corporation, Advanced Micro Devices Inc, MediaTek Inc, Samsung Electronics Co Ltd, Broadcom Inc, Imagination Technologies Limited, Spectra7 Microsystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR/VR Chip Market Strategic Shifts & Innovations
Spatial computing interfaces are migrating rendering workloads from local silicon toward distributed edge-cloud architectures. This shift redefines hardware-software boundaries and opens new competitive terrain for infrastructure providers.
Chiplet-based modular designs are integrating dedicated neural processing units alongside GPU arrays within single-package substrates. Medical device manufacturers at Siemens Healthineers and Stryker are piloting these configurations for real-time tumor segmentation during oncological procedures. The architecture is integrating heterogeneous compute blocks that previously required discrete board-level assembly, compressing headset form factors by 40 percent.
REACH substance restrictions are tightening scrutiny of halogenated flame retardants in high-density interconnect substrates. European medical device OEMs now face mandatory supply chain disclosure requirements extending to tier-three material suppliers. German and French surgical navigation specialists are responding by pre-qualifying alternative phosphorus-based chemistries ahead of 2026 sunset dates.
Enterprise procurement committees are consolidating vendor relationships around full-stack platform providers rather than discrete component suppliers. Healthcare systems in the United States now require 10-year spare part guarantees as standard RFP terms, displacing spot-market purchasing for replacement ASICs. This behavioral shift favors vertically integrated semiconductor houses with captive packaging and testing facilities.
AR/VR Chip Market Segmentation
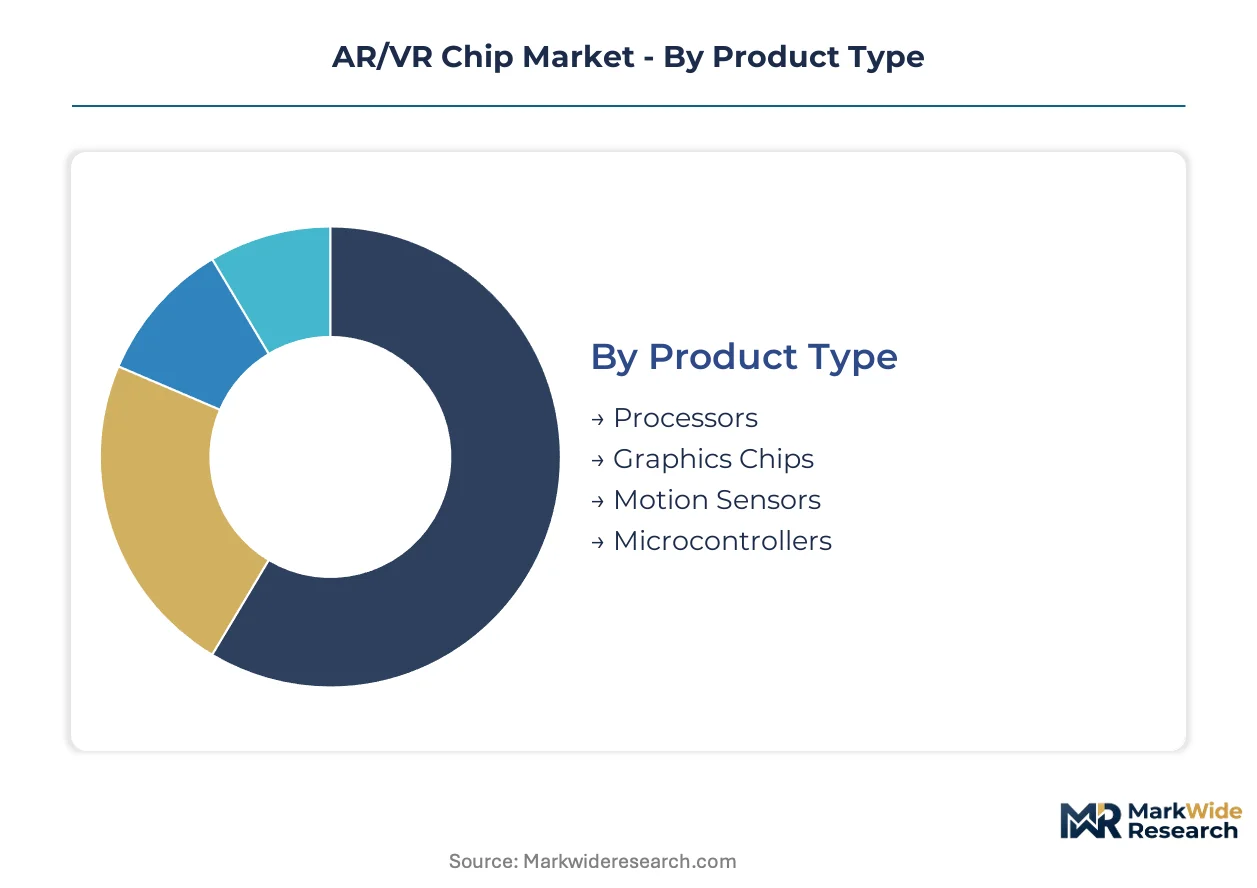
AR/VR chip segmentation reveals how heterogeneous compute requirements fragment silicon design priorities across immersive applications. Process node selection, sensor fusion complexity, and latency tolerance vary sharply by deployment context, creating distinct procurement patterns that vendors must address through targeted product roadmaps.
Product Type:
Process geometry and thermal envelope define competitive positioning within each silicon category.
- Processors:Multi-core CPU clusters fabricated at 5nm nodes integrate heterogeneous compute blocks for concurrent tracking, rendering, and AI inference. Demand concentrates in Taiwan's foundry cluster as Qualcomm and MediaTek secure priority wafer allocation for Snapdragon XR and Dimensity platforms.
- Graphics Chips:GPU arrays with dedicated ray-tracing hardware command premium pricing due to compute intensity and vendor lock-in. Enterprise visualization systems at Siemens Healthineers and Stryker anchor procurement volume for surgical navigation workloads.
- Motion Sensors:MEMS-based inertial measurement units fuse accelerometer and gyroscope data for sub-millimeter positional tracking.
- Microcontrollers:Low-power auxiliary chips manage power sequencing and peripheral interfacing in tethered headset configurations.
Mature deployment sits with Graphics Chips. Newer deployment is concentrated in Processors.
Technology:
Latency tolerance and environmental robustness determine technology selection across indoor and field use cases.
- Wireless Connectivity:Wi-Fi 6E and 60GHz mmWave radios enable tetherless headset architectures with sub-20ms motion-to-photon latency. Taiwan's Hsinchu Science Park anchors pilot line investment for 3nm RF integration at TSMC and MediaTek.
- Optical Tracking:Camera-based inside-out positioning systems rely on dedicated image signal processors for SLAM computation. Gaming headsets from Meta and Sony sustain volume demand despite higher power draw versus inertial alternatives.
- Inertial Tracking:Sensor fusion algorithms compensate for drift through complementary filtering with magnetometer data.
- Depth Sensors:Time-of-flight and structured light modules enable hand tracking and spatial mapping without controller peripherals.
Volume leadership belongs to Optical Tracking. Steepest expansion trajectory is concentrated in Wireless Connectivity.
Application:
Regulatory clearance pathways and procurement cycle length fragment addressable market economics.
- Healthcare:Surgical navigation and preoperative planning systems require FDA 510(k) clearance and EU MDR conformity assessment. Hospital procurement committees now mandate 10-year spare part guarantees, favoring vertically integrated semiconductor houses with captive packaging facilities.
- Gaming:Consumer headset volumes sustain foundry utilization through seasonal refresh cycles. Meta's Quest platform and Sony's PlayStation VR2 anchor demand for cost-optimized 7nm silicon from MediaTek and Qualcomm.
- Training Simulations:Enterprise VR for hazardous environment replication gains traction in energy and aviation sectors.
- Education:Institutional procurement for immersive learning labs remains price-sensitive with extended evaluation periods.
Revenue concentration sits with Gaming. Fastest margin expansion is concentrated in Healthcare.
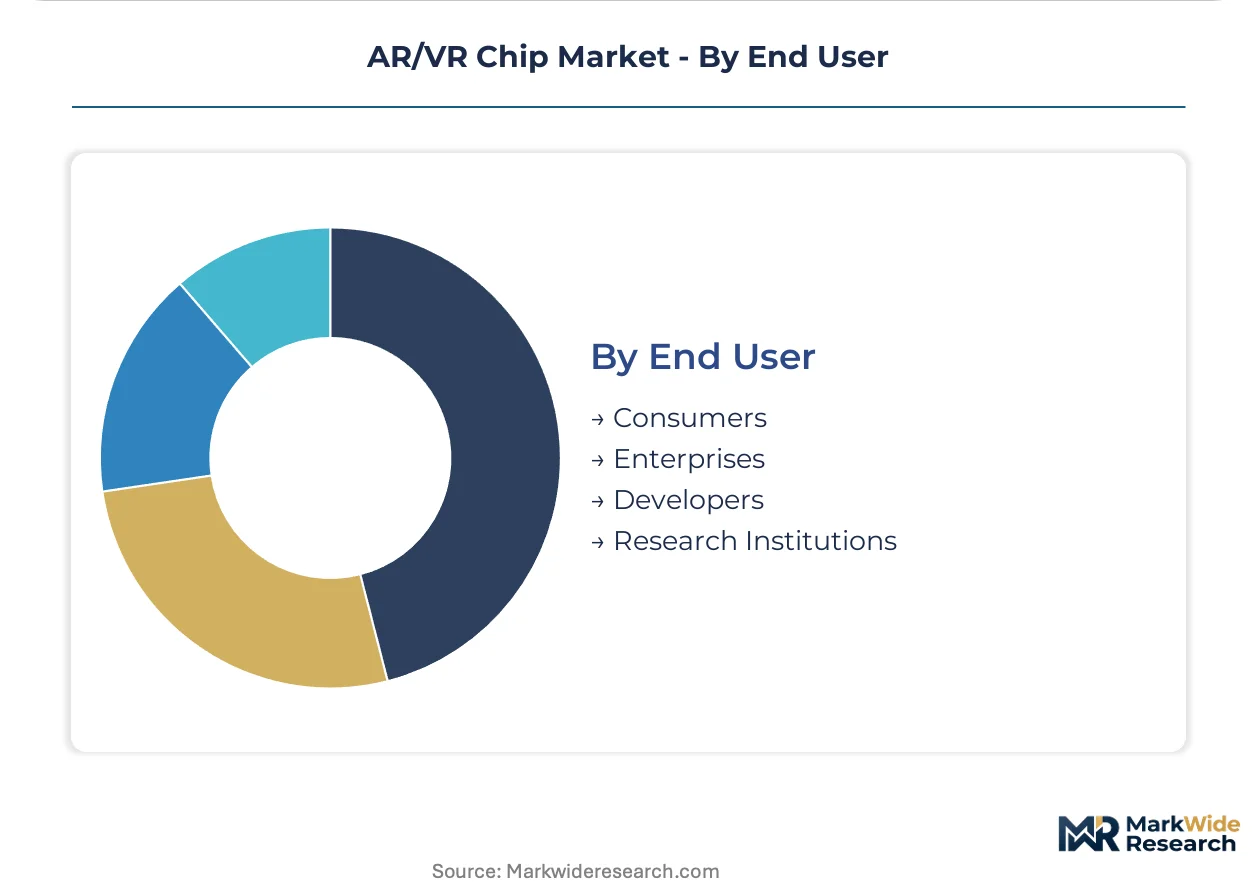
End User:
Volume scale and customization requirements create divergent vendor engagement models.
- Enterprises:Industrial maintenance and field service applications demand IP67-rated hardware with 5-year operational life guarantees. Energy sector technicians at Shell and BP pilot digital twin overlays combined with haptic feedback gloves for remote equipment inspection.
- Consumers:Mass-market headsets prioritize cost-optimized silicon and streamlined thermal design. Holiday purchasing patterns create foundry capacity allocation challenges versus steadier enterprise demand.
- Developers:Early-access hardware programs require reference platforms with exposed debugging interfaces and flexible firmware.
- Research Institutions:Academic neuroscience and human factors studies procure specialized high-fidelity systems in limited quantities.
Volume leadership sits with Consumers. Procurement sophistication is climbing fastest among Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan anchors the densest concentration of advanced foundry capacity for AR/VR silicon, with 3nm pilot lines drawing fabless design houses from across three continents. This clustering dynamic shapes procurement patterns for medical device OEMs and gaming headset manufacturers alike.
United States
FDA 510(k) clearance pathways for surgical navigation headsets accelerate hospital procurement cycles at Mayo Clinic and Cleveland Clinic. The FCC's Part 15 electromagnetic compatibility rules govern wireless connectivity certification for tetherless enterprise devices. Austin and San Diego host design centers where Qualcomm and NVIDIA architect Snapdragon XR and GPU rendering pipelines respectively.
Taiwan
TSMC's 5nm and 7nm foundry allocation prioritizes AR/VR system-on-chip designs as AI training demand competes for capacity. The National Development Council's chip industry incentives underwrite advanced packaging investment at Taichung. Kaohsiung's emerging semiconductor cluster attracts backend testing facilities for medical-grade ASIC qualification.
Germany
Siemens Healthineers and Stryker anchor European demand for surgical planning chipsets requiring EU MDR conformity assessment. ECHA's REACH annex XVII restrictions on halogenated flame retardants force substrate material requalification extending 18-24 months. Dresden's silicon cluster hosts Fraunhofer institutes piloting chiplet-based neural processing for real-time tumor segmentation.
China
MIIT's GB standards for wireless display interfaces shape domestic headset architecture requirements for Pico and DPVR platforms. Shanghai's Zhangjiang Hi-Tech Park concentrates fabless design houses targeting cost-optimized 7nm silicon for mid-tier consumer devices. Beijing's regulatory push for algorithmic transparency in medical AI creates compliance friction for imported surgical navigation systems.
South Korea
Samsung Electronics integrates in-house Exynos silicon for Galaxy VR platforms while supplying OLED microdisplays to external headset manufacturers. METI-equivalent KOTRA programs support component export qualification for ASEAN medical device OEMs. Seoul's Pangyo Techno Valley hosts mixed-reality startups accessing Samsung's advanced packaging partnerships.
AR/VR Chip Market Key Industry Players
Top-tier vendors anchor premium-tier GPU and wireless connectivity silicon, while mid-tier specialists compete on cost-optimized processor integration for consumer headsets. The vendor base stratifies across three archetypes: vertically integrated semiconductor houses with captive packaging, fabless design specialists leveraging Taiwan foundry partnerships, and IP licensing entities monetizing sensor fusion algorithms. Capacity expansion at 5nm nodes and strategic partnerships for edge-cloud rendering infrastructure define current competitive maneuvering.
Among fabless specialists, Qualcomm Incorporated and NVIDIA Corporation occupy positions exemplifying wireless-first and rendering-intensive archetypes respectively, while MediaTek Inc represents cost-optimized processor integration for volume consumer markets. These three anchors illustrate how geographic proximity to Taiwan's foundry cluster correlates with product roadmap velocity. Their collective positioning shapes procurement committee expectations for 10-year spare part guarantees in healthcare verticals.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| NVIDIA Corporation |
| Intel Corporation |
| Advanced Micro Devices Inc |
| MediaTek Inc |
| Samsung Electronics Co Ltd |
| Broadcom Inc |
| Imagination Technologies Limited |
| Spectra7 Microsystems |
| Others |
Cost & Logistics Intelligence
Polysilicon spot price volatility at the Shanghai Metals Market cascades through 300mm wafer fabrication into three-tier pricing structure across premium, standard, and economy levels for AR/VR system-on-chip designs. Taiwan foundry concentration compresses margin capture for fabless vendors while amplifying pricing power for integrated device manufacturers with captive packaging.
Pricing Analysis
Short lead-time premiums of 15-20 percent apply to 5nm mask set procurement for medical-grade ASICs facing FDA 510(k) clearance deadlines. Price differentiation hinges on EU MDR certification tier and volume scale, with healthcare procurement committees demanding 10-year spare part guarantees that inflate standard pricing. Cost compression in mid-tier consumer silicon is intensifying because MediaTek and Qualcomm compete aggressively for Meta Quest and Sony PlayStation VR2 socket wins. Gaming OEMs exhibit highest price sensitivity, while surgical navigation specialists at Siemens Healthineers and Stryker absorb premium positioning for real-time tumor segmentation chipsets.
Supply Chain Analysis
Regional distribution centers at Taichung and Kaohsiung consolidate backend testing for medical-grade ASIC qualification before hub-and-spoke distribution to German and US surgical device OEMs. Supply concentrates in Taiwan, South Korea, and the United States for advanced node fabrication, with silicon wafers, EUV photoresist, and specialty gas chemistries drawing from concentrated Japanese and German chemical suppliers. Single-source vulnerability around simultaneous localization and mapping algorithm IP inflates royalty stacks for new entrants. Distribution runs through vertically integrated semiconductor houses with captive packaging facilities that satisfy hospital procurement mandates for decade-long spare part availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AR/VR chip market functions as a vertical-integration race where control over 3nm foundry allocation and advanced packaging capacity determines margin capture. Players pursue backward integration into specialty gas and photoresist supply to secure process node priority.
For Market Incumbents: Extend 5nm and 7nm foundry reservation agreements at TSMC's Hsinchu Science Park to defend against AI training chip capacity competition. Secure captive backend testing facilities in Kaohsiung to satisfy healthcare procurement mandates for 10-year spare part guarantees. Prioritize EU MDR pre-certification investment ahead of 2026 REACH substance restriction sunset dates to lock out mid-tier competitors. For New Entrants and Emerging Players: Enter via India's PLI scheme subsidies for semiconductor assembly and testing to bypass Taiwan foundry queue constraints. Target industrial maintenance applications at Shell and BP where digital twin overlay demand outpaces established vendor coverage. Pursue cloud-rendering distribution partnerships with telecom infrastructure providers to monetize lightweight client hardware through subscription rather than silicon margin capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless design houses with secured 5nm tape-out completion in Taiwan during periods of AI training chip capacity absorption. Long-term viability over a 5-10 year window rests on heterogeneous integration capabilities combining neural processing units with GPU arrays in single-package substrates. Watch for FDA 510(k) clearance velocity at surgical navigation startups as inflection indicator for healthcare vertical margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | TSMC Hsinchu allocation priority secures 5nm wafer starts ahead of AI training chip competition. |
| Advanced Packaging Investment | Taichung backend facilities satisfy EU MDR traceability mandates for medical-grade ASICs. |
| EU MDR Pre-Certification | REACH Annex XVII compliance ahead of 2026 sunset dates locks hospital procurement channels. |
| Edge-Cloud Rendering Partnership | Telecom infrastructure alliances enable subscription monetization bypassing silicon margin pressure. |
| Chiplet-Based Neural Processing Integration | Siemens Healthineers and Stryker pilots validate real-time tumor segmentation for oncological procedures. |
Research Approach
Multi-period observation of foundry utilization rates, mask set pricing indices, and FDA 510(k) clearance timelines anchored the trend analysis, supplemented by interviews with semiconductor design executives, foundry account managers, hospital biomedical engineers, and GPO contracts managers. Secondary validation drew from SEC 10-K filings, TSMC investor presentations, ECHA REACH substance restriction updates, and customs data for photoresist and specialty gas imports. Bottom-up wafer demand modeling and top-down healthcare procurement budget analysis provided triangulation.
Input-output matrices mapped process node allocation, application-specific latency requirements, and regulatory certification pathways across the projection horizon. Segmentation dimensions modeled include product type, technology interface, application vertical, and end-user procurement sophistication. CAGRs derived from foundry capacity expansion schedules, medical device OEM capital expenditure plans, and wireless headset shipment trajectories. Forecast inputs incorporated EU AI Act transparency mandate implementation pace and India PLI scheme disbursement velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under TSMC capacity reallocation shocks or FDA 510(k) pathway delays for surgical navigation devices. Outputs reflect documented assumptions regarding 3nm pilot line yield ramps and REACH substance restriction enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market