
 Location-Based VR Entertainment Market | 2026-2036
Location-Based VR Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Location-Based VR Entertainment Market Intelligence
Market Context
China's Shenzhen manufacturing corridor is rewriting supply dynamics for location-based VR hardware. Sandbox VR leverages proprietary motion-tracking arenas to sustain premium positioning across Asian and North American metros. HTC anchors headset supply for third-party arcade operators through its Vive Focus series. Meta competes by extending Quest for Business licensing into family entertainment centers.
Technical Definition and Segment Structure
Location-based VR entertainment denotes commercial installations where users access immersive digital environments through shared physical spaces, typically employing 6DoF tracking systems with sub-20ms motion-to-photon latency to minimize simulator sickness. These venues generate revenue through time-blocked session sales rather than hardware ownership, serving experiential retail and out-of-home leisure markets. Arcade Games and Escape Rooms command the dominant share of service-type revenue, while Haptic Feedback technology captures expanding margin pools as operators differentiate through full-body immersion. Corporate Groups within customer-type segmentation represent the fastest-growing demand channel as enterprises adopt VR for team-building and training off-sites.
Regulatory Environment and Outlook
FCC equipment authorization governs wireless VR headset deployment in US commercial venues, while China's MIIT enforces GB standards for electromagnetic compatibility in public entertainment hardware. CE marking under EU MDR and RoHS directives shapes product access for European operators importing Asian-manufactured systems. Stakeholders must monitor evolving building-code adaptations for VR-specific occupancy loads and fire-safety egress requirements as municipal jurisdictions grapple with immersive venue classifications.
Market Dynamics
Motion-to-photon latency compression below 20ms is virtualizing physical entertainment infrastructure, forcing venue operators to rebuild around real-time rendering pipelines rather than static arcade hardware.
Growth Catalysts
- Enterprise off-site demand:Corporate training budgets are redirecting into immersive team-building installations as HR departments seek experiential alternatives to conventional retreat formats.
- MIIT hardware certification:China's streamlined GB standards for electromagnetic compatibility are accelerating factory-to-venue deployment timelines for Asian-manufactured headsets.
- Haptic suit penetration:Full-body force-feedback systems are expanding per-session revenue at premium venues through differentiated sensory depth.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in real-time ray-tracing silicon creates vulnerability for operators scaling render-intensive multiplayer arenas.
- Wireless spectrum congestion:FCC equipment authorization processes for 6GHz VR headsets impose 4-6 month pre-deployment delays in dense urban markets.
- Physical footprint economics:Square-meter yields at mall-based installations struggle against rising commercial real estate premiums in tier-one metros.
Strategic Opportunities
- Secondary city penetration:Underserved entertainment corridors in Austin, Nashville, and Manchester UK present first-mover expansion potential outside saturated LA-Orlando-Shenzhen clusters.
- Educational institution partnerships:University STEM programs are piloting curriculum-integrated VR labs as recruitment and research differentiators.
- RoHS directive alignment:EU MDR and CE marking convergence is creating unified certification pathways for hardware vendors targeting European family entertainment centers.
Industry Challenges
- Technical talent scarcity:Unreal Engine and Unity specialists with venue-scale multiplayer networking experience command premium compensation in tight labor pools.
- Municipal code ambiguity:Fire-safety egress standards for immersive occupancy loads remain undefined across most US county jurisdictions, delaying permitting.
Report Scope
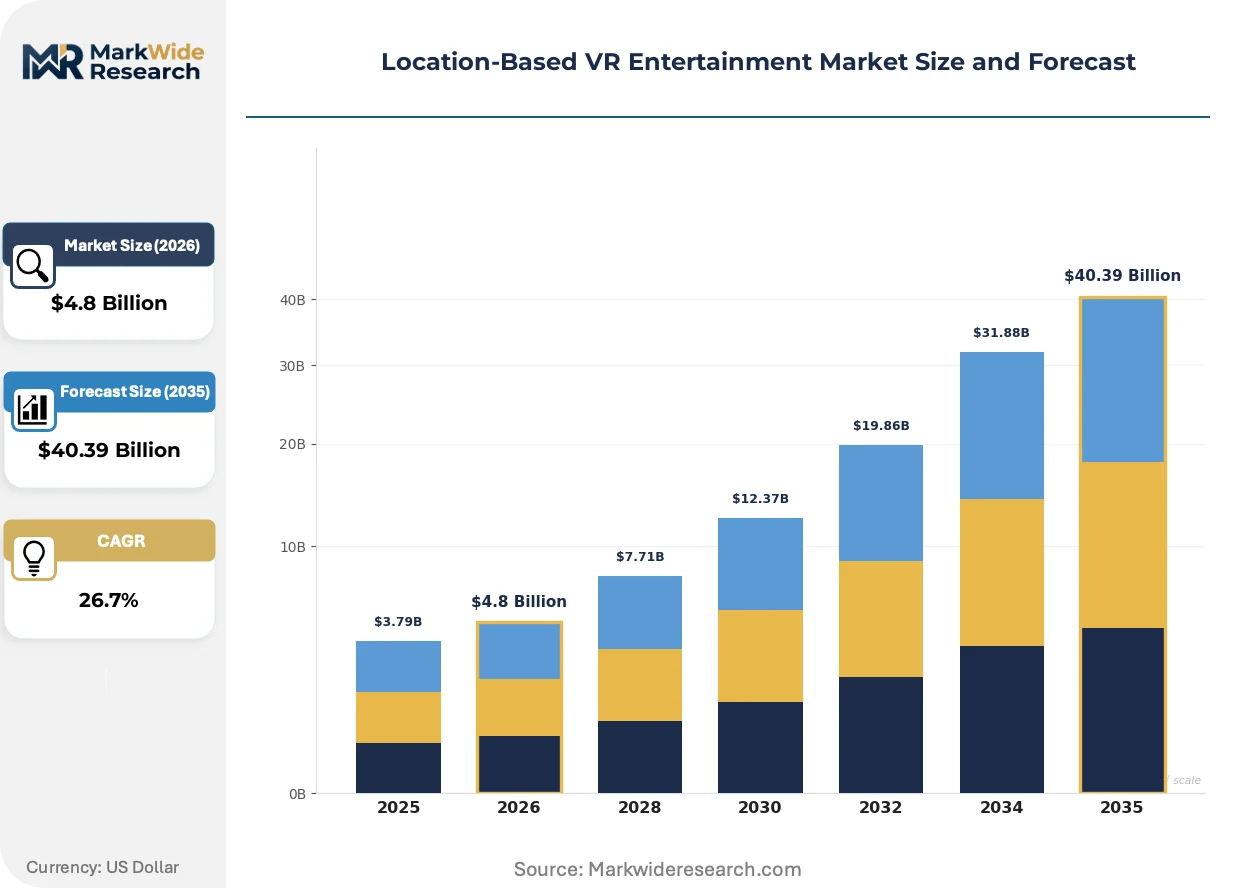
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location-Based VR Entertainment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Arcade Games, Escape Rooms, VR Cinemas, Theme Parks Technology: Immersive Headsets, Motion Tracking, Spatial Audio, Haptic Feedback Customer Type: Families, Corporate Groups, Tourists, Enthusiasts Content Type: Multiplayer Experiences, Single Player Adventures, Educational Programs, Simulation Training |
| Companies Covered | VRChat, Beat Games, Sandbox VR, Meta, Unity Technologies, The Park Playground, Schell Games, HTC, Interstellar Arc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location-Based VR Entertainment Market Strategic Shifts & Innovations
Real-time cloud rendering is dissolving the hardware-performance ceiling that previously constrained venue economics, enabling operators to deploy lighter headsets while centralizing compute overhead.
Inside-out tracking arrays are virtualizing the external base-station infrastructure that once dominated warehouse-scale installations. Family entertainment centers in suburban Dallas and Osaka are adopting camera-native headsets to eliminate lighthouse calibration downtime. The technology is compressing venue setup costs and expanding retrofit feasibility for legacy bowling alleys and cinema lobbies.
EU MDR classification of haptic feedback devices as Class I medical-adjacent equipment is triggering CE marking documentation requirements that Asian OEMs had not previously maintained. German and French import distributors are now demanding IEC 60601-1-2 electromagnetic compatibility test reports as standard procurement preconditions. Venue operators in Berlin and Lyon are absorbing 8-12 week certification delays into expansion timelines.
Session-based revenue unbundling is fragmenting the traditional hourly-rate model across corporate and consumer segments. Enterprise buyers in pharmaceutical and financial services verticals are negotiating outcome-priced contracts tied to retention or training efficacy metrics. Los Angeles-based operators report 40% of Q3 corporate bookings now specify custom content development rather than off-the-shelf experiences.
Location-Based VR Entertainment Market Segmentation
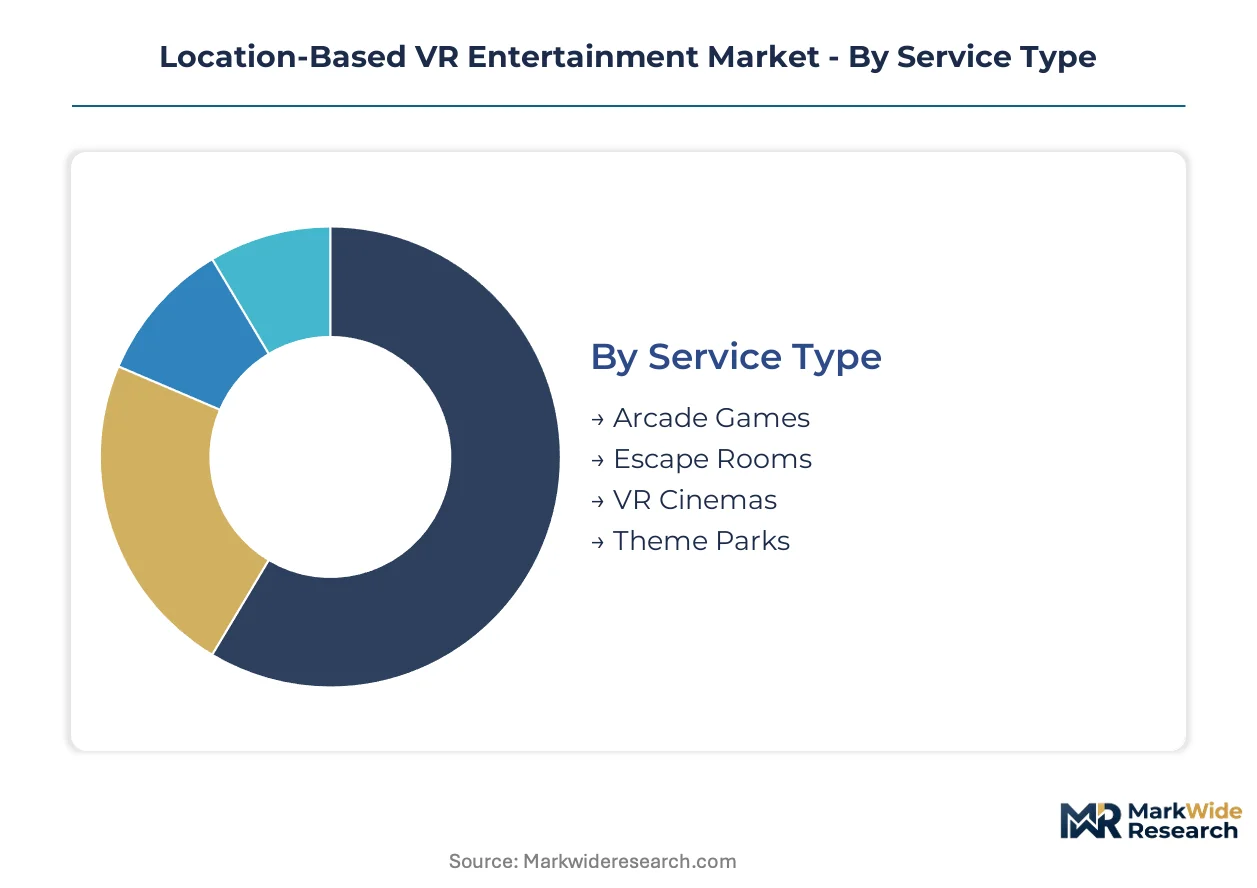
Segmentation in location-based VR entertainment reveals how venue operators balance hardware investment against session economics. Each dimension—service format, sensory technology, audience profile, and content architecture—creates distinct margin structures and capital requirements.
Service Type:
Mature formats dominate revenue floors while emerging concepts reshape per-capita spending.
- Arcade Games:Time-blocked competitive experiences with 6DoF tracking and sub-20ms latency. Demand concentrates in Los Angeles and Orlando entertainment corridors where mall operators seek traffic-driving anchors. Revenue per square meter struggles against rising commercial real estate premiums.
- Escape Rooms:Narrative-driven puzzle environments requiring synchronized multiplayer networking. Corporate off-site bookings in Dallas and Austin represent the fastest-climbing demand channel as HR departments abandon conventional retreat formats.
- VR Cinemas:Seated passive viewing with 180-degree field-of-view headsets. Asian manufacturing corridors supply cost-optimized hardware for budget-conscious suburban installations.
- Theme Parks:Warehouse-scale free-roam arenas with full-body haptic integration. Shenzhen production clusters feed premium venue buildouts across Asian metros.
Arcade Games retain volume leadership; Escape Rooms hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensory depth from accessible entry points.
- Immersive Headsets:6DoF inside-out tracking arrays with camera-native positioning eliminate external base-station calibration. Operators in Osaka and suburban Dallas retrofit legacy bowling alleys with lighter, cheaper deployment.
- Motion Tracking:Sub-millimeter precision systems for warehouse-scale multiplayer synchronization. Proprietary arena configurations command premium positioning in tier-one metros.
- Spatial Audio:Head-related transfer function modeling for directional soundscapes. Standard inclusion across mid-tier and above installations.
- Haptic Feedback:Full-body force-feedback suits expanding per-session revenue through differentiated sensory immersion. EU MDR classification as Class I medical-adjacent equipment triggers CE marking documentation delays for Asian OEMs.
Immersive Headsets dominate unit deployment; Haptic Feedback commands the widest margin spreads.
Customer Type:
Application focus shifts from leisure consumption toward outcome-based enterprise procurement.
- Families:Weekend session buyers seeking accessible entertainment center experiences. Price sensitivity limits hardware upgrade cycles at suburban mall installations.
- Corporate Groups:Enterprise training and team-building budgets redirecting into immersive off-sites. Pharmaceutical and financial services verticals negotiate outcome-priced contracts tied to retention metrics.
- Tourists:One-time high-spend visitors at destination entertainment clusters. Orlando and Los Angeles venue operators optimize for throughput over repeat visitation.
- Enthusiasts:Hardcore gamers demanding maximum fidelity and custom content. Los Angeles operators report custom development requests in 40% of corporate bookings.
Families sustain baseline occupancy; Corporate Groups generate the highest per-capita yield expansion.
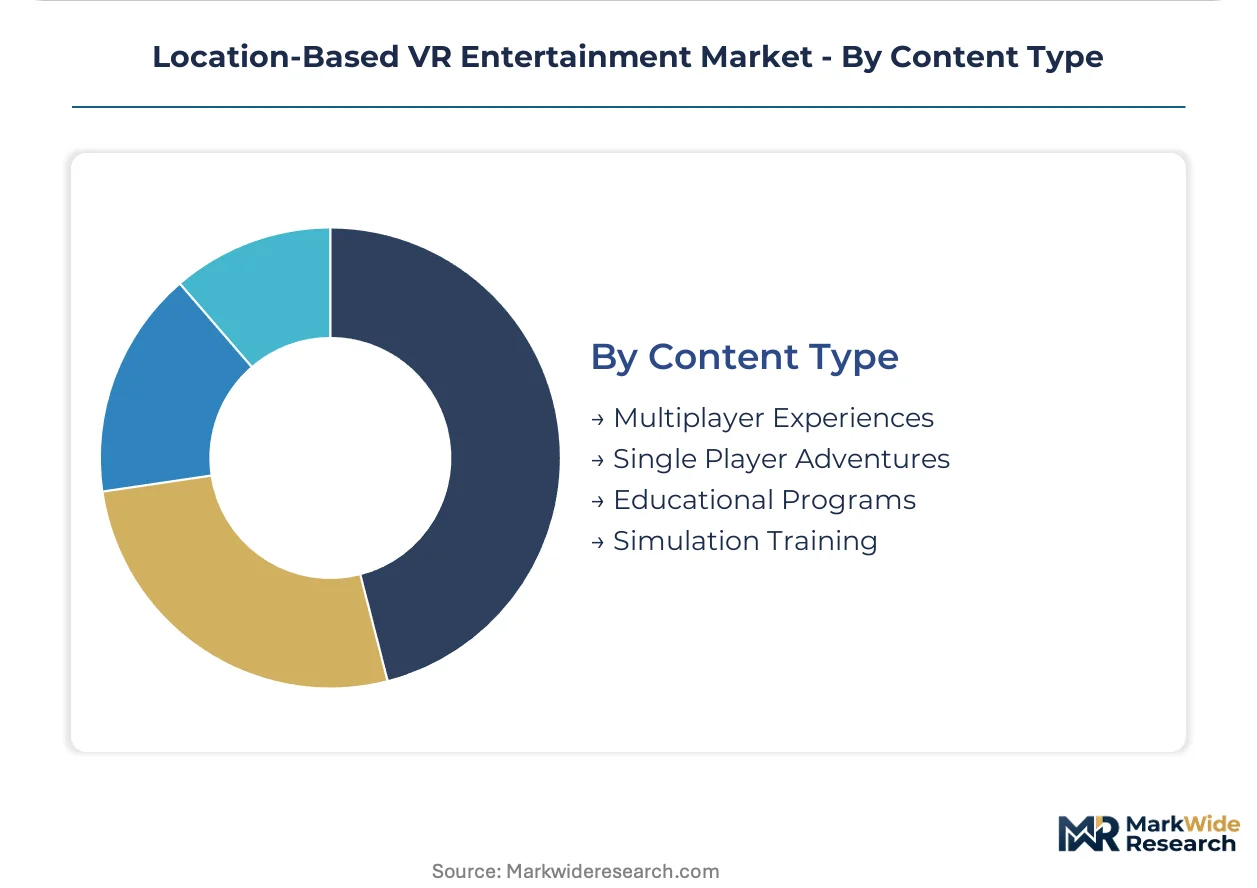
Content Type:
Volume concentration favors multiplayer architectures while single-player retains retrofit economics.
- Multiplayer Experiences:Synchronized arena-scale networking for 4-8 concurrent users. Technical talent scarcity in Unreal Engine and Unity specialists constrains content pipeline expansion.
- Single Player Adventures:Self-contained narrative modules requiring minimal infrastructure. Preferred format for cinema lobby conversions and legacy arcade retrofits.
- Educational Programs:Curriculum-integrated STEM labs at university pilot sites. Manchester UK and Austin present first-mover partnership opportunities.
- Simulation Training:Enterprise efficacy-measured modules for skills transfer. Custom development contracts replace off-the-shelf licensing in advanced procurement negotiations.
Multiplayer Experiences anchor revenue concentration; Educational Programs climb fastest in institutional procurement pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization governs wireless VR headset deployment in US commercial venues, establishing the regulatory baseline for the industry's largest revenue pool. China's MIIT enforces GB standards for electromagnetic compatibility, compressing factory-to-venue timelines for Asian-manufactured systems. European operators navigate CE marking under EU MDR and RoHS directives, with German and French distributors now demanding IEC 60601-1-2 test reports as standard procurement preconditions.
United States
Corporate training budgets redirect into immersive team-building installations as HR departments abandon conventional retreat formats. FCC equipment authorization processes for 6GHz VR headsets impose 4-6 month pre-deployment delays in dense urban markets. Los Angeles and Orlando entertainment corridors concentrate demand, with mall operators seeking traffic-driving anchors amid rising commercial real estate premiums.
China
Shenzhen manufacturing corridors feed premium venue buildouts across Asian metros with compressed hardware certification timelines. MIIT guidelines on immersive content standards accelerate factory-to-venue deployment for domestic and export markets. Pearl River Delta production clusters supply cost-optimized headsets for budget-conscious suburban installations throughout the region.
Germany
EU MDR classification of haptic feedback devices as Class I medical-adjacent equipment triggers CE marking documentation requirements. Berlin venue operators absorb 8-12 week certification delays into expansion timelines as Asian OEMs adapt compliance protocols. North Rhine-Westphalia industrial zones host import distributors demanding IEC 60601-1-2 electromagnetic compatibility test reports.
United Kingdom
Manchester presents first-mover partnership opportunities for university STEM programs piloting curriculum-integrated VR labs. RoHS directive alignment creates unified certification pathways for hardware vendors targeting European family entertainment centers. Greater London venue operators optimize for throughput over repeat visitation among tourist-heavy destination clusters.
Japan
METI standards coordination supports domestic venue operators adopting camera-native headsets to eliminate lighthouse calibration downtime. Osaka family entertainment centers compress venue setup costs through inside-out tracking arrays. Kanto region enterprises negotiate outcome-priced contracts tied to training efficacy metrics rather than hourly-rate models.
Location-Based VR Entertainment Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where proprietary arena configurations command premium positioning against mass-deployment hardware licensors. The vendor base spans motion-tracking specialists, headset manufacturers, content studios, and venue operators with overlapping vertical interests. Three archetypes dominate: technology licensors extending enterprise licensing into entertainment channels, proprietary arena operators sustaining differentiated sensory depth, and platform-agnostic content studios serving fragmented venue demand. Competitive moves concentrate on strategic partnerships between hardware vendors and venue chains, plus geographic expansion into secondary entertainment corridors outside saturated tier-one metros.
Within the proprietary arena tier, Sandbox VR exemplifies premium positioning through captive motion-tracking infrastructure. Among technology licensors, Meta and HTC occupy positions at opposite ends of the enterprise-to-consumer spectrum, with the former extending Quest for Business licensing and the latter anchoring headset supply for third-party arcade operators through its Vive Focus series.
| Leading Market Players |
|---|
| VRChat |
| Beat Games |
| Sandbox VR |
| Meta |
| Unity Technologies |
| The Park Playground |
| Schell Games |
| HTC |
| Interstellar Arc |
| Others |
Cost & Logistics Intelligence
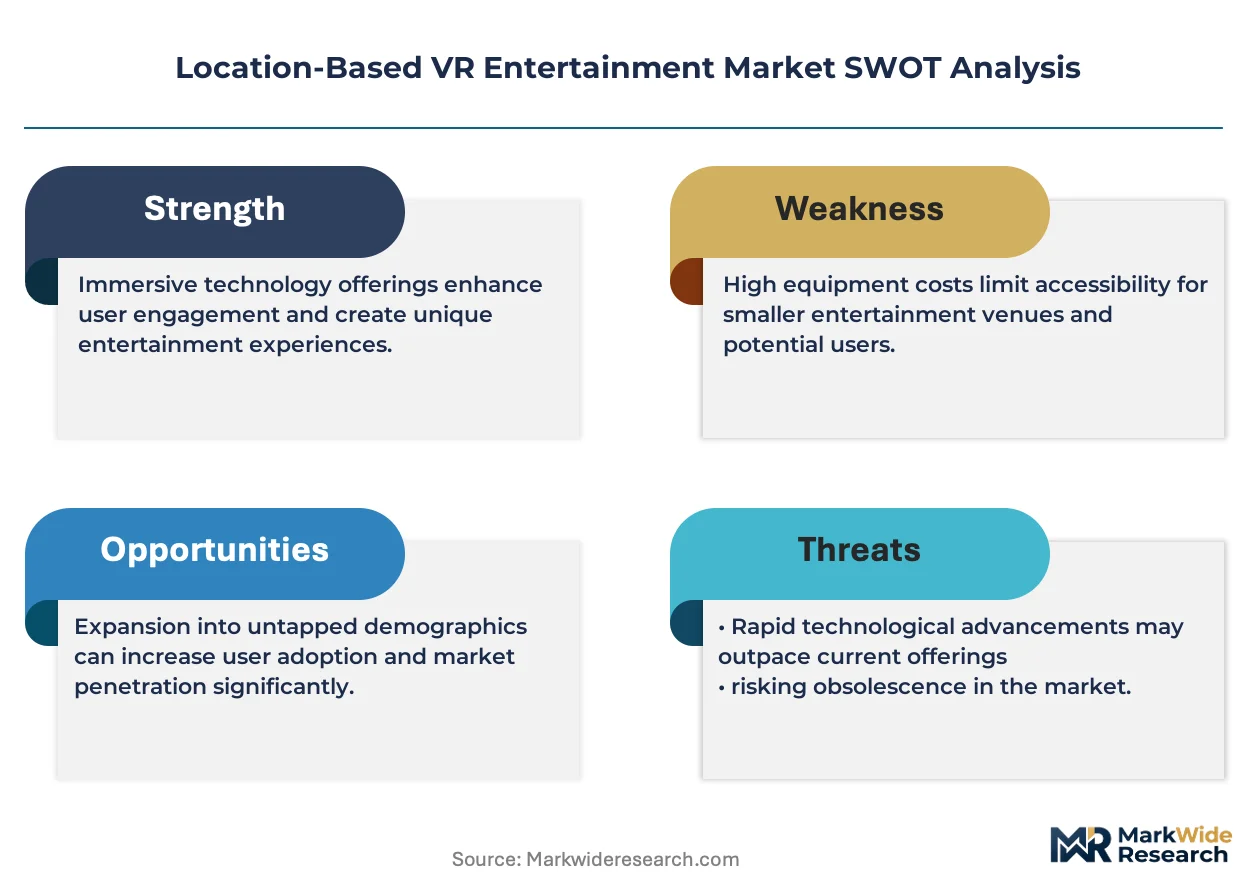
Single-source dependency on NVIDIA ray-tracing silicon determines both the 40-60% price spreads between premium haptic-enabled arenas and economy headset-only installations and the Shenzhen-to-venue supply chain shape that compresses Asian OEM margins while elevating US operator hardware costs.
Pricing Analysis
Los Angeles venue operators charge 3-4x session rates compared to suburban Dallas family entertainment centers for equivalent duration experiences. Three-tier pricing structure across premium, standard, and economy levels separates full-body haptic arenas from 6DoF tracking rooms from seated VR cinema retrofits. Cost compression in the economy tier is intensifying because Shenzhen manufacturers flood budget headset supply into secondary US metros. Corporate group buyers show lowest price sensitivity as HR departments negotiate outcome-based contracts tied to training efficacy metrics.
Supply Chain Analysis
US Commerce Department export controls on advanced GPU and semiconductor manufacturing equipment to China limit flows of critical ray-tracing silicon to Shenzhen assembly corridors. Supply concentrates in China for headset final assembly, Taiwan for display panel fabrication, and South Korea for memory components. Raw material dependencies include gallium nitride substrates, rare-earth magnets for haptic actuators, and high-purity lithium for wireless headset batteries. Single-source vulnerability around NVIDIA's real-time rendering silicon creates chokepoint risk for operators scaling multiplayer arenas. Distribution runs through HTC and Meta licensing programs for third-party arcade operators, plus direct procurement relationships for proprietary arena chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home-based VR headset penetration approaching console-scale install bases threatens location-based venue economics, forcing incumbents to defend through irreplaceable physical immersion depth that consumer hardware cannot replicate.
For Market Incumbents: Build captive motion-tracking infrastructure moats through proprietary arena configurations that sustain 6DoF precision impossible in residential spaces. Defend against Meta's Quest for Business licensing encroachment by deepening exclusive content partnerships with Unreal Engine studios. Absorb 8-12 week CE marking delays into European expansion timelines rather than ceding Berlin and Lyon to faster-moving competitors. For New Entrants and Emerging Players: Build out university STEM lab partnerships in Manchester UK and Austin where curriculum integration creates sticky institutional demand outside saturated entertainment corridors. Target educational program content development as the most penetrable segment, with custom simulation training modules for pharmaceutical and financial services verticals offering outcome-based pricing premiums. Pursue white-label haptic suit distribution to third-party venue operators rather than competing directly for prime real estate. For Investors and Strategic Acquirers: EU MDR reclassification of haptic feedback devices as Class I medical-adjacent equipment reshapes the acquisition landscape by elevating compliance documentation from procurement preference to mandatory precondition. Long-term viability rests on content pipeline depth rather than hardware deployment scale, favoring studios with Unreal Engine multiplayer networking capabilities over pure venue operators. Watch for MIIT hardware certification timeline compression as the signal indicating which Asian OEMs can sustain export competitiveness against domestic Chinese venue buildouts.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Arena Configuration | Sandbox VR's captive motion-tracking infrastructure commands premium positioning against licensed hardware deployments. |
| Enterprise Licensing Extension | Meta's Quest for Business program penetrates family entertainment centers through familiar consumer brand recognition. |
| Educational Institution Partnership | University STEM lab pilots in Manchester UK create recruitment differentiators and curriculum-integrated revenue streams. |
| Haptic Feedback Certification Investment | Asian OEMs adapting IEC 60601-1-2 documentation regain access to German and French import distribution channels. |
| Secondary City Geographic Expansion | Austin and Nashville entertainment corridors present first-mover potential outside saturated LA-Orlando-Shenzhen clusters. |
Research Approach
The analysis maps arcade games, escape rooms, VR cinemas, and theme park installations, each validated through venue operators, hardware procurement managers, content studio technical directors, and corporate training buyers. Primary interviews with these stakeholders combined with secondary validation against MIIT certification databases, FCC equipment authorization filings, and EU MDR CE marking registries. Bottom-up venue deployment counts triangulate against top-down hardware shipment data from Shenzhen and Taipei manufacturing clusters.
Assumptions held fixed include FCC 6GHz equipment authorization timelines, MIIT GB standard compliance protocols, and NVIDIA GPU supply allocation priorities across gaming and datacenter segments. Segmentation dimensions modeled encompass service format, sensory technology tier, customer type, and content architecture across the projection horizon. CAGRs derive from installed base expansion curves weighted by per-session revenue trajectories. Forecast inputs include commercial real estate premium indices for tier-one metros and Unreal Engine specialist labor pool tightness metrics.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration into haptic suit manufacturing by arena operators would shift outcomes. Material shifts in US Commerce Department GPU export control scope or MIIT hardware certification acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality in Therapy Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market