
 US and Europe Crypto Asset Management Market | 2026-2036
US and Europe Crypto Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe Crypto Asset Management Market Analytics
Institutional investors are bifurcating from retail participants as the dominant fee-paying client base in crypto asset management. Coinbase Global leverages its exchange infrastructure to anchor institutional custody and prime brokerage workflows. Fidelity Digital Assets sustains competitive pressure through its broker-dealer heritage and compliance-first positioning. Anchorage Digital specializes in bank-grade custody technology that satisfies US OCC charter requirements for federally regulated digital asset banks.
Crypto asset management encompasses the professional oversight, safekeeping, and strategic allocation of digital assets through institutional-grade infrastructure, typically involving multi-signature wallet architectures, cold storage protocols, and real-time blockchain analytics for portfolio attribution. Its primary commercial purpose centers on delivering risk-adjusted exposure to cryptocurrency markets while satisfying fiduciary obligations around asset protection and regulatory reporting. Custodial services command the deepest margin pools given infrastructure intensity and insurance requirements, while advisory services represent the fastest-expanding segment as traditional wealth managers seek white-label crypto allocation frameworks. Portfolio management through integrated solutions is gaining share against standalone web-based platforms as institutions demand unified reporting across traditional and digital asset books.
The US SEC and the European Banking Authority shape product access through divergent registration regimes, with the former emphasizing securities law compliance for ETF structures and the latter operationalizing MiCA's asset-referenced token classifications. AML/KYC compliance obligations under FinCEN rules and the EU's AMLD6 framework directly determine which custodians qualify for institutional mandates on either side of the Atlantic. Stakeholders must monitor how the US OCC's conditional banking charter evolution interacts with ECB digital euro timelines to assess whether euro-denominated crypto products fragment across separate custody and settlement rails.
Market Dynamics
Institutional capital flows are compressing fee structures across custody and advisory tiers as pension funds and sovereign wealth vehicles mandate bank-grade infrastructure for digital asset exposure.
Growth Catalysts
- MiCA framework operationalization:The European Union's Markets in Crypto-Assets regulation provides passportable licensing for asset-referenced tokens, enabling cross-border product distribution from Luxembourg and Ireland domiciles.
- Pension fund allocation mandates:US public retirement systems in Wisconsin and Florida have initiated pilot programs for alternative investment sleeves that include regulated crypto custody.
- Multi-signature cold storage protocols:Hardware security module integration with biometric authentication layers satisfies fiduciary insurance requirements for institutional mandates.
Market Restraints
- Specialized custody infrastructure costs:SOC 2 Type II certification and Lloyd's of London crime insurance premiums impose fixed cost barriers exceeding eight figures annually for new entrants.
- Qualified custodian fragmentation:The US OCC has granted conditional banking charters to fewer than five federally regulated digital asset custodians, concentrating institutional-grade supply in a handful of entities.
- Cross-border settlement latency:Euro-denominated crypto products face fragmentation between TARGET2 integration timelines and proprietary stablecoin settlement rails.
Strategic Opportunities
- Wealth manager white-label frameworks:Registered investment advisors seek turnkey crypto allocation models that embed within existing portfolio reporting systems without separate account infrastructure.
- German Spezialfonds vehicle expansion:Germany's fund legislation now permits institutional special funds to allocate up to twenty percent to crypto assets, creating a regulatory tailwind for custody providers with BaFin licensing.
- Blockchain analytics convergence:Real-time attribution tools merging on-chain surveillance with traditional risk management software enable unified reporting across digital and legacy asset books.
Industry Challenges
- Digital asset forensic accounting skills:Qualified professionals who understand both GAAP fair value measurement and blockchain transaction tracing command compensation premiums that strain mid-tier advisory operations.
- SEC no-action letter uncertainty:Custodians face extended legal review periods for novel product structures, compressing time-to-market for ETF-adjacent vehicles.
- Legacy portfolio management system integration:Mainframe-dependent asset servicers require substantial middleware development to ingest blockchain-derived position data into existing NAV calculation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe Crypto Asset Management Market |
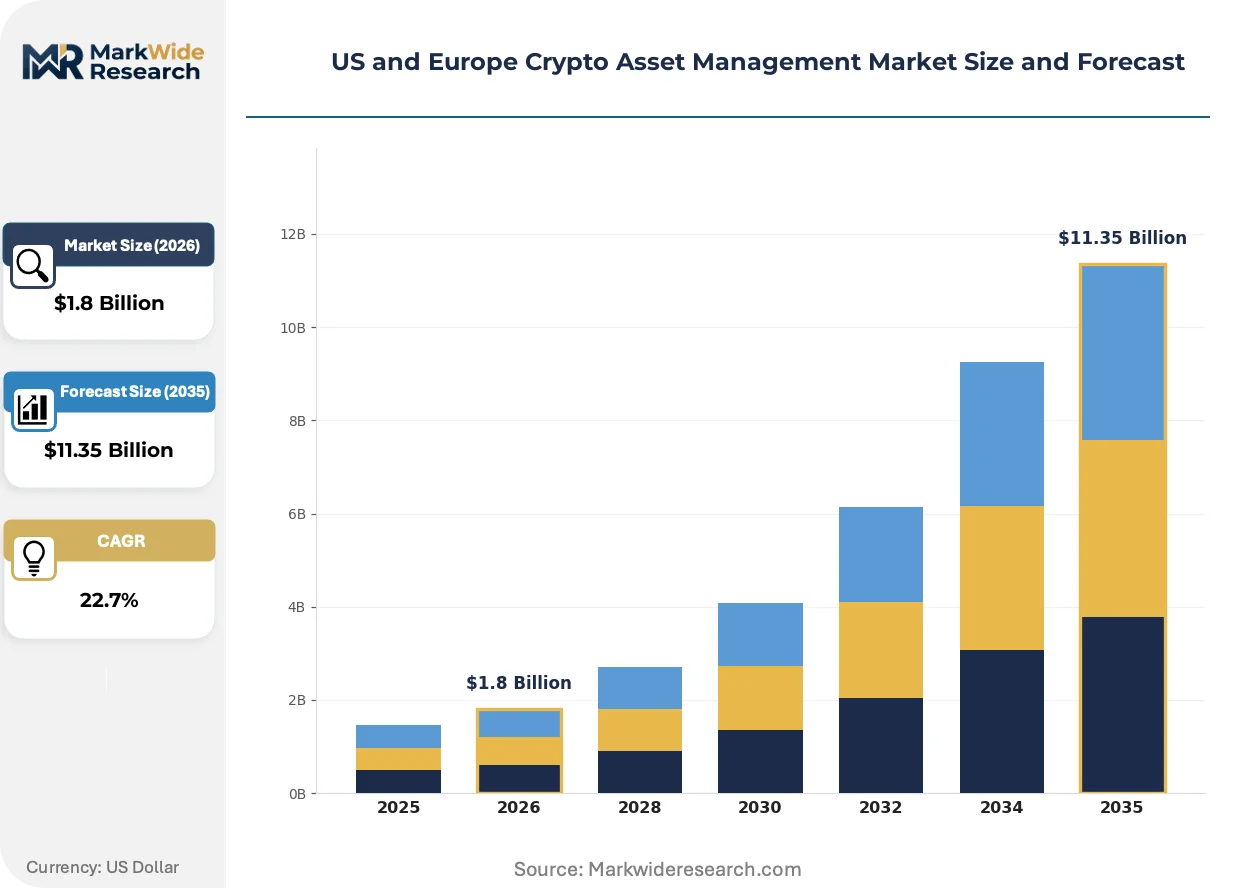
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Advisory Services, Portfolio Management, Custodial Services, Trading Services Client Type: Institutional Investors, Retail Investors, High-Net-Worth Individuals, Corporations Platform Type: Web-Based Platforms, Mobile Applications, Desktop Applications, Integrated Solutions Regulatory Compliance: AML/KYC Compliance, Tax Compliance, Securities Regulations, Licensing Requirements |
| Companies Covered | Coinbase Global, Inc., Gemini Trust Company, LLC, BitGo Inc., Fidelity Digital Assets, Bakkt Holdings, Inc., Paxos Trust Company, LLC, Ledger SAS, Anchorage Digital, CRYPTO FINANCE AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe Crypto Asset Management Market Evolving Landscape
Technology convergence between traditional finance infrastructure and distributed ledger systems is redefining operational boundaries for asset servicers on both sides of the Atlantic.
Multi-party computation (MPC) wallet architecture distributes private key fragments across geographically separated hardware enclaves, eliminating single-point-of-failure risks that plague traditional cold storage. Institutional allocators in the Netherlands and Switzerland are mandating MPC implementation for mandates exceeding fifty million euros. This security model is miniaturizing the minimum viable scale for bank-grade custody, enabling mid-tier asset managers to compete for pension fund business previously reserved for bulge-bracket providers.
The SEC's evolving stance on spot bitcoin ETF custody arrangements is forcing prime brokers to restructure sub-custody relationships with qualified custodians. Sponsor applications now face heightened scrutiny of wallet segregation and bankruptcy remoteness provisions. US-registered investment companies are responding by consolidating vendor relationships with OCC-chartered entities that can provide direct regulatory attestation.
Advisory fee compression in traditional wealth management is accelerating experimentation with crypto-native subscription models. Fee-only planners in California and New York are unbundling digital asset allocation from comprehensive financial planning, offering standalone crypto sleeve construction at basis-point tiers below conventional alternatives. This unbundling is most visible among solo practitioners seeking differentiation in saturated metropolitan markets.
US and Europe Crypto Asset Management Market Segmentation
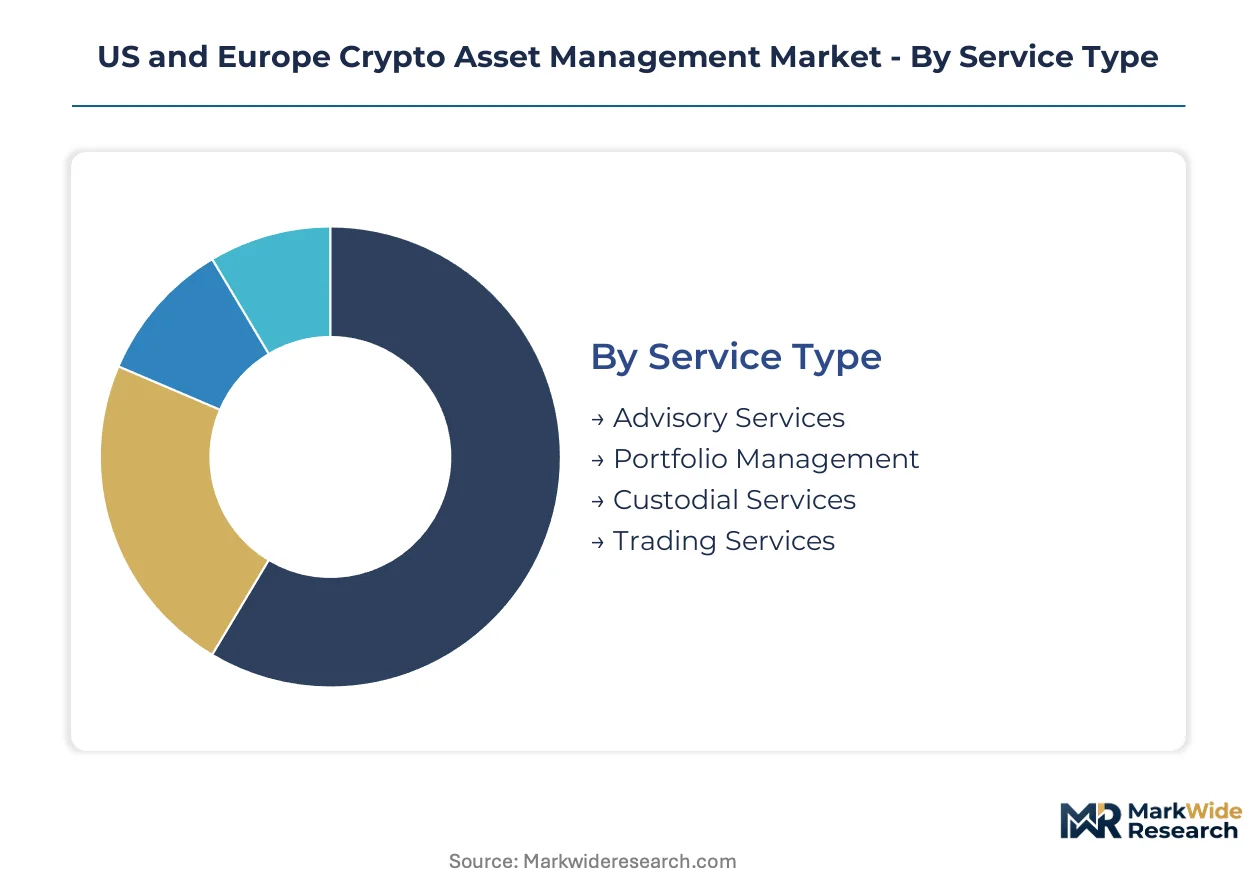
Service differentiation across custody, advisory, and trading functions determines competitive positioning in the US and Europe Crypto Asset Management Market. Client sophistication levels and platform architecture choices further stratify provider economics and regulatory compliance burdens.
Service Type:
Advisory and custody services concentrate demand domestically within each jurisdiction due to licensing constraints, while trading functions exhibit more cross-border fluidity.
- Advisory Services:Fee-based allocation guidance for digital asset portfolios integrates with traditional wealth planning workflows. Demand clusters among registered investment advisors in California and New York seeking white-label crypto sleeve construction without separate infrastructure investment.
- Portfolio Management:Active rebalancing and risk-adjusted exposure strategies across cryptocurrency allocations. Institutional mandates in Germany and Switzerland drive adoption of unified reporting tools that merge blockchain-derived positions with legacy asset books.
- Custodial Services:Bank-grade safekeeping through multi-signature architectures and cold storage protocols. US OCC charter requirements limit qualified supply to federally regulated entities, compressing margins through infrastructure intensity.
- Trading Services:Execution and liquidity provision across spot and derivative markets. European MiCA passporting enables cross-border distribution from Luxembourg and Ireland domiciles.
Custodial services hold the largest share; momentum sits with advisory services as traditional wealth managers seek turnkey allocation frameworks.
Client Type:
Cost tier stratification separates institution-facing infrastructure investments from retail-accessible platform economics.
- Institutional Investors:Pension funds, asset managers, and sovereign wealth vehicles mandate SOC 2 Type II certification and Lloyd's of London crime insurance. Wisconsin and Florida public retirement systems have initiated pilot programs for alternative investment sleeves.
- High-Net-Worth Individuals:Family offices and private wealth clients require bespoke custody arrangements with biometric authentication layers. Swiss private banks and Dutch wealth managers are mandating multi-party computation for mandates exceeding fifty million euros.
- Retail Investors:Self-directed allocation through web and mobile platforms with simplified KYC workflows. European neobanks and US fintech platforms compete on onboarding friction and educational content integration.
- Corporations:Treasury management and balance sheet diversification strategies. German Spezialfonds legislation now permits institutional special funds to allocate up to twenty percent to crypto assets.
Institutional investors hold the largest share; high-net-worth individuals are expanding most quickly as private banking divisions build dedicated digital asset desks.
Platform Type:
Application maturity determines integration depth with existing portfolio management systems and reporting infrastructure.
- Integrated Solutions:Unified platforms connecting custody, trading, and reporting through API architectures. US-registered investment companies favor vendors offering direct NAV calculation ingestion and consolidated statements across traditional and digital holdings.
- Web-Based Platforms:Browser-accessible interfaces with cloud-hosted wallet infrastructure. Mid-tier European asset servicers deploy these for cost efficiency, though mainframe-dependent legacy systems require substantial middleware development.
- Mobile Applications:Smartphone-native interfaces targeting retail accessibility and real-time position monitoring. Fee-only planners in saturated metropolitan markets use these to unbundle crypto allocation from comprehensive planning.
- Desktop Applications:Installed software with enhanced security controls for professional traders. Niche demand persists among quantitative funds requiring low-latency execution and custom algorithm deployment.
Integrated solutions hold the largest share; mobile applications are climbing the fastest as advisor-facing tools democratize access.
Regulatory Compliance:
Compliance function intensity varies by jurisdictional enforcement posture and product complexity.
- AML/KYC Compliance:Customer identification and transaction monitoring under FinCEN rules and EU AMLD6. These obligations directly determine custodian qualification for institutional mandates on either side of the Atlantic.
- Securities Regulations:SEC registration for ETF structures and MiCA asset-referenced token classifications. Sponsor applications face extended legal review periods for novel custody arrangements.
- Tax Compliance:Reporting and withholding obligations across capital gains and income characterization. Blockchain analytics tools now merge on-chain surveillance with traditional tax software for unified obligation calculation.
- Licensing Requirements:BaFin licensing in Germany, OCC conditional banking charters in the US, and passportable MiCA authorizations. Fragmentation concentrates institutional-grade supply among fewer than five federally regulated US custodians.
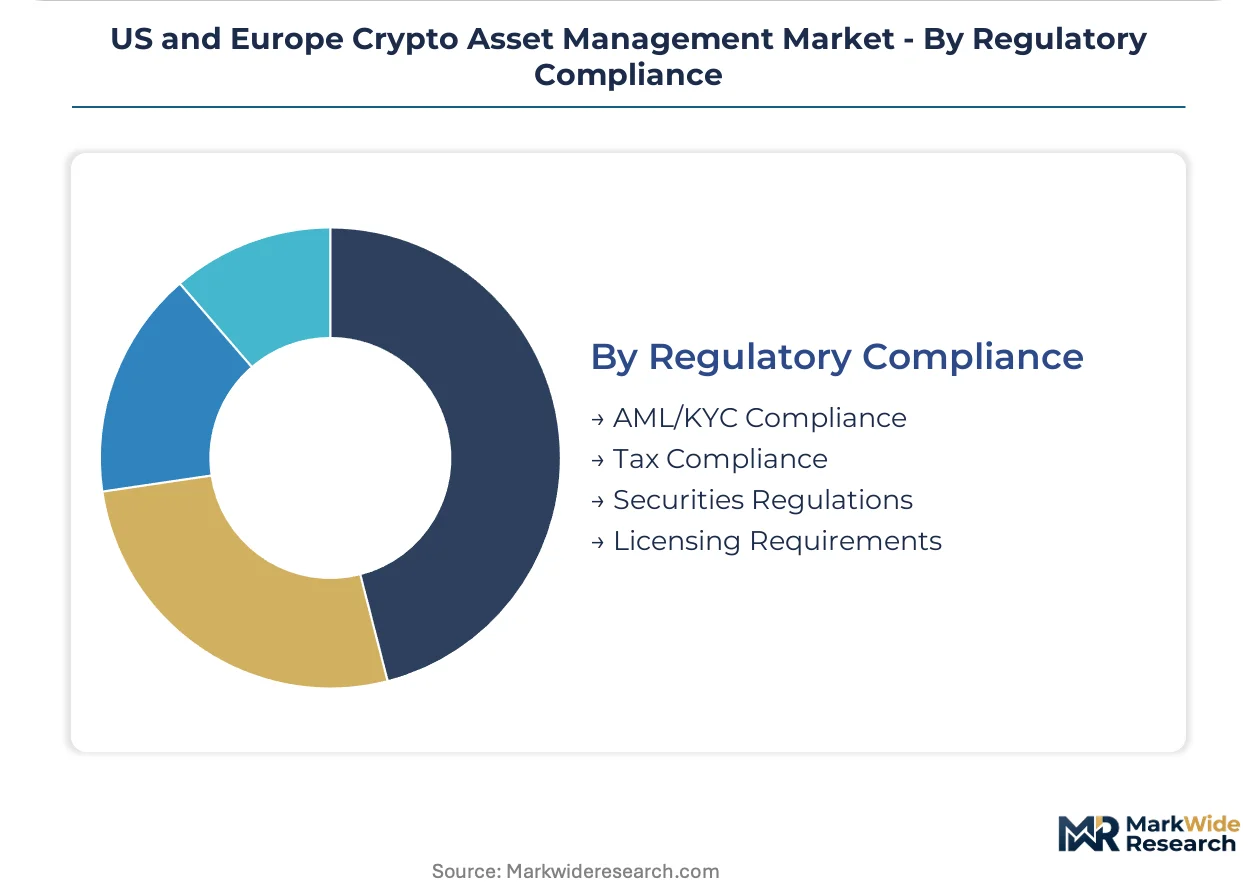
AML/KYC compliance holds the largest share; securities regulations are gaining share fastest as spot ETF approval pathways reshape product registration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber cable infrastructure connecting financial centers in New York, London, and Frankfurt underwrites the geography's role as the dominant corridor for crypto asset management. Low-latency data transmission enables real-time settlement between US and European custody networks. Regulatory arbitrage across this corridor shapes product innovation velocity.
United States
Pension fund pilot programs in Wisconsin and Florida drive institutional mandate growth. The SEC's evolving spot ETF approval framework restructures custody attestation requirements. New York and Chicago anchor the custody provider cluster where OCC-chartered entities consolidate prime brokerage relationships.
Germany
Spezialfonds legislation permits twenty percent crypto allocations in institutional special funds. BaFin licensing requirements concentrate qualified custodians in Frankfurt and Munich. The Eurex clearing infrastructure enables euro-denominated derivative settlement for crypto-linked products.
Switzerland
Private banking divisions in Zurich and Geneva mandate multi-party computation for mandates exceeding fifty million euros. FINMA guidance on digital asset custody permits bank-grade segregation standards. The Crypto Valley cluster in Zug anchors blockchain analytics and wallet technology development.
United Kingdom
Family offices in London require bespoke custody with biometric authentication layers. The FCA's registration regime for cryptoasset firms filters institutional-grade supply. The Canary Wharf fintech corridor hosts integrated platform providers serving wealth manager white-label demand.
Netherlands
Dutch pension funds and asset managers drive demand for unified reporting across traditional and digital books. DNB supervision of crypto service providers mandates compliance with EU AMLD6 obligations. Amsterdam's trading infrastructure cluster supports euro-denominated stablecoin settlement rails.
US and Europe Crypto Asset Management Market Competitive Landscape
Listed leaders compete with private specialists across regulatory charter access. The market structure concentrates institutional-grade supply among fewer than ten federally regulated entities. Three archetypes dominate: exchange-anchored custodians with prime brokerage workflows, bank-affiliated digital asset divisions leveraging compliance heritage, and standalone technology specialists with OCC charter authorization. Competitive moves center on strategic partnerships with traditional wealth platforms and technology licensing for white-label deployment.
Within the exchange-anchored tier, Coinbase Global and Gemini Trust Company exemplify infrastructure-led positioning. Fidelity Digital Assets occupies a position among bank-affiliated divisions, while Anchorage Digital anchors the standalone technology specialist archetype. These entities represent the spectrum of regulatory compliance strategies required for institutional mandate capture across US and European jurisdictions.
| Leading Market Players |
|---|
| Coinbase Global, Inc. |
| Gemini Trust Company, LLC |
| BitGo Inc. |
| Fidelity Digital Assets |
| Bakkt Holdings, Inc. |
| Paxos Trust Company, LLC |
| Ledger SAS |
| Anchorage Digital |
| CRYPTO FINANCE AG |
| Others |
Value Network & Pricing Analysis
Multi-party computation wallet architecture replacing traditional cold storage vaults is redrawing custody provider economics and compressing infrastructure cost curves across both US and European markets. This substitution simultaneously decentralizes supply geography beyond OCC-chartered banking hubs and enables mid-tier asset managers to bid for pension fund mandates previously reserved for bulge-bracket providers.
Pricing Analysis
Volume-discount tiering structures dominate institutional custody contracts, with basis-point fees scaling inversely against assets under custody and mandate duration. Price differentiation centers on SOC 2 Type II certification status and Lloyd's of London crime insurance coverage limits, with uninsured or self-insured providers occupying economy tiers. Pricing pressure stems from pension fund procurement teams mandating fee compression alongside bank-grade infrastructure requirements. Retail-facing platforms exhibit highest price sensitivity, while sovereign wealth vehicles prioritize security architecture over marginal cost.
Supply Chain Analysis
Strait of Hormuz transit risk for hardware security module manufacturing concentrates supply vulnerability among Asia-Pacific semiconductor foundries serving European and US custody technology vendors. Geographic supply concentration centers on Taiwan, South Korea, and Japan for HSM chip fabrication, with final assembly distributed across Germany, Switzerland, and the United States. Raw material dependencies include silicon wafers, biometric sensor components, and specialized cryptographic processors. Supply chain risk manifests as single-source vulnerability for FIPS 140-2 Level 4 certified modules. Distribution runs through direct OEM relationships with custody technology providers, bypassing traditional IT distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
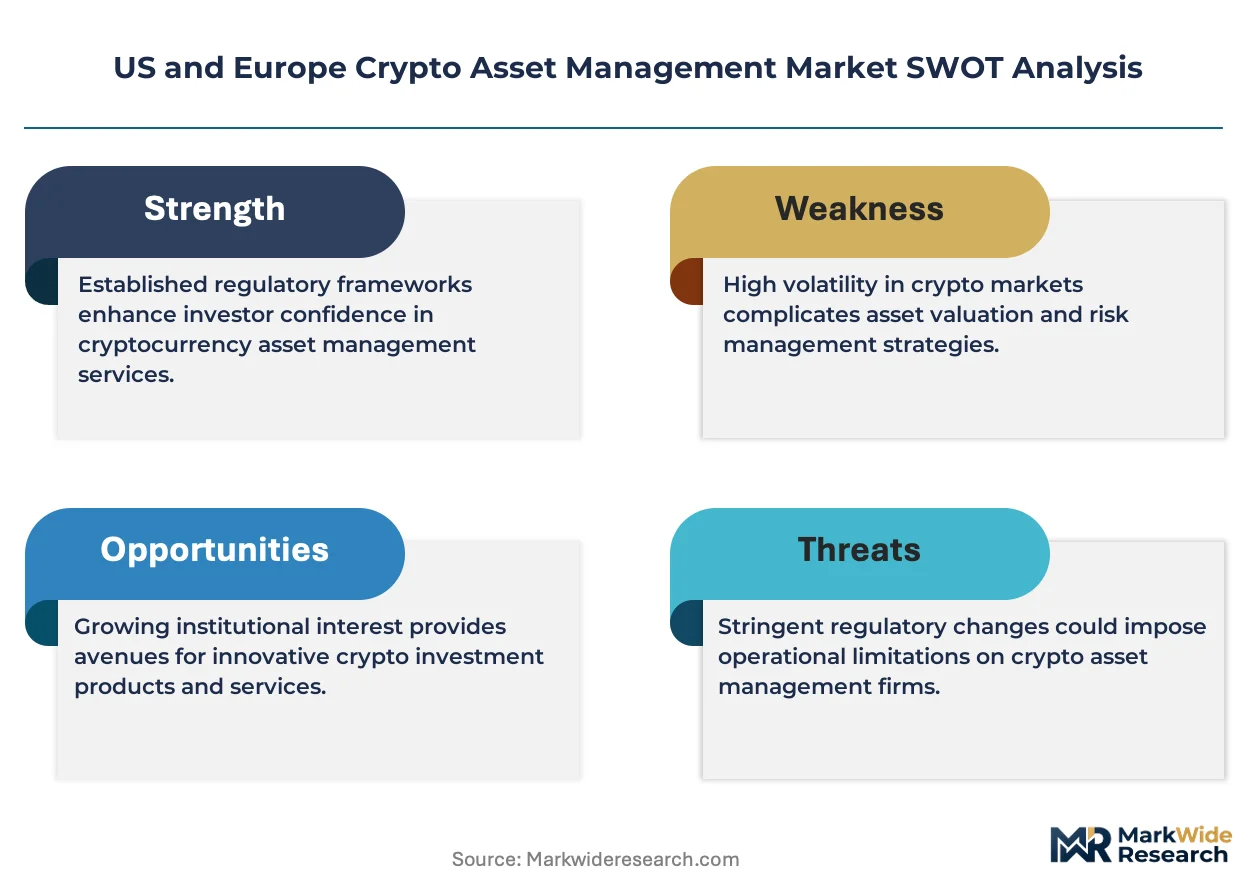
The US and Europe Crypto Asset Management Market represents a high-growth disruption as MiCA framework operationalization and SEC spot ETF approval pathways create the first harmonized transatlantic regulatory corridor for institutional digital asset products.
For Market Incumbents: Secure prime brokerage relationships with OCC-chartered custodians before qualified supply concentrates further among fewer than five federally regulated entities. Invest in backward integration into hardware security module supply chains to mitigate Taiwan and South Korea foundry concentration risk. Defensive consolidation around BaFin-licensed entities in Germany captures Spezialfonds allocation mandate growth.
For New Entrants and Emerging Players: White-label advisory frameworks for registered investment advisors in California and New York represent the most penetrable service-layer gap, as incumbents under-serve solo practitioners seeking turnkey crypto sleeve construction without infrastructure investment. Target wealth manager unbundling trends in saturated metropolitan markets. Go-to-market angle emphasizes API-first integration with existing portfolio management systems rather than standalone platform displacement.
For Investors and Strategic Acquirers: Capital is best deployed toward standalone technology specialists with conditional banking charter authorization or MiCA passportable licensing, as regulatory moats widen competitive separation from unlicensed competitors. Long-term viability favors entities with unified custody-advisory-trading infrastructure spanning both US and EU jurisdictions. Monitor SEC no-action letter velocity for novel ETF-adjacent custody structures as inflection indicator for product innovation runway.
| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Passporting Authorization | Enables cross-border product distribution from Luxembourg and Ireland domiciles into German and Dutch markets. |
| OCC Conditional Banking Charter | Qualifies custodians for US-registered investment company mandates and prime brokerage sub-custody relationships. |
| Multi-Party Computation Implementation | Satisfies Swiss and Dutch institutional allocator requirements for mandates exceeding fifty million euros. |
| BaFin Licensing Acquisition | Positions providers for German Spezialfonds twenty percent crypto allocation mandate capture. |
| Blockchain Analytics Platform Integration | Delivers unified reporting across digital and legacy asset books for institutional risk management workflows. |
Research Methodology
A spread of perspectives from custody technology executives, pension fund alternative investment officers, regulatory affairs leads at digital asset banks, and wealth platform integration specialists converged on the working assumptions. Primary interview insights combined with secondary validation from SEC no-action letter filings, BaFin authorization registers, MiCA implementation guidance, EBA technical standards, and OCC conditional charter disclosures. Bottom-up triangulation across service-type revenue pools and top-down cross-check against institutional AUM allocation trends anchored the market sizing.
Segmentation dimensions modeled include service type, client sophistication tier, platform architecture maturity, and regulatory compliance intensity across the analysis window. CAGRs derived from historical mandate growth patterns, pension fund pilot program expansion timelines, and ETF product registration velocity assumptions. Forecast inputs incorporated hardware security module cost curve trajectories and qualified custodian supply concentration dynamics.
Forecasts assume regulatory continuity in SEC securities law interpretation and EU MiCA operationalization; material policy shifts would require re-modeling. Specific risk factors include OCC charter revocation events, ECB digital euro timeline acceleration fragmenting euro-denominated settlement rails, and AMLD6 enforcement escalation disqualifying existing custodians. Practitioners should keep alternative scenarios live as transatlantic regulatory coordination and central bank digital currency development evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market