
 Smart Contracts Platforms Market | 2026-2036
Smart Contracts Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Contracts Platforms Market Insights
Buyer concentration in financial services is decoupling from traditional banking hierarchies as decentralized finance protocols and institutional custody platforms fragment demand across new entrant categories. Ethereum leverages its first-mover position in programmable contract standards to sustain developer network effects. Solana competes on transaction throughput architecture, while Hyperledger Fabric specializes in permissioned enterprise deployments for regulated industries.
Smart contracts platforms are distributed computing environments that execute deterministic agreement logic when predefined conditions are cryptographically verified, typically operating on consensus mechanisms with finality thresholds ranging from sub-second to several minutes depending on network architecture. Their primary commercial purpose is eliminating intermediary reliance in multi-party transactions. Public blockchain deployments currently lead transaction volume metrics, though private blockchain configurations capture disproportionate margin pools in enterprise procurement given customization premiums. Cloud-based deployment models represent the fastest-expanding delivery mode as hyperscale providers integrate managed node infrastructure.
The SEC, EU MiCA framework, and Singapore's Monetary Authority shape platform viability through divergent classification standards for native tokens versus utility instruments, directly constraining which contract types achieve legal enforceability. The EU AI Act adds algorithmic audit requirements for automated decision systems embedded in contract execution logic. Stakeholders must monitor regulatory divergence between jurisdictions to determine where to domicile contract settlement layers and associated liability structures.
Market Dynamics
Financial institutions are dismantling legacy settlement infrastructure in favor of deterministic execution environments, creating a structural vacuum that smart contracts platforms exploit through programmable finality and cryptographic verification mechanisms.
Growth Catalysts
- EU MiCA Framework:The Markets in Crypto-Assets regulation establishes legal certainty for tokenized financial instruments, enabling institutional deployment of automated settlement infrastructure across European capital markets.
- Tokenized Real Assets:Commodity traders and real estate funds are migrating physical asset ownership records to on-chain registries, generating demand for custody-integrated contract execution layers.
- Singapore:The Monetary Authority of Singapore's Project Guardian initiative validates institutional-grade DeFi protocols, attracting asset managers seeking regulated on-chain yield generation.
Market Restraints
- Validator Concentration:Proof-of-stake networks exhibit stake accumulation among a handful of custodial providers, creating systemic liveness risk for mission-critical financial settlements.
- Oracle Dependency:Price feed manipulation attacks on Chainlink and similar data bridges expose smart contracts to external data corruption, limiting deployment in high-value derivatives markets.
- Energy Input Costs:Proof-of-work validation remains economically viable only where stranded hydroelectric or flared natural gas supplies subsidize computational overhead.
Strategic Opportunities
- Trade Finance:Letter-of-credit automation through conditional escrow releases addresses the trillion-dollar documentary trade gap, with Dubai and Mumbai emerging as pilot hubs.
- AI-Contract Convergence:Natural language processing engines generating Solidity bytecode from legal prose compress deployment timelines for non-technical legal teams.
- Carbon Credit Verification:Satellite-attested reforestation data triggering automatic credit minting creates verifiable supply for compliance markets under Article 6 of the Paris Agreement.
Industry Challenges
- Formal Verification Talent:Mathematical proof engineering for contract security remains concentrated among fewer than five hundred practitioners globally, constraining audit capacity for institutional deployments.
- Legacy Core Banking Integration:SWIFT messaging protocols and mainframe settlement systems require expensive middleware development to achieve atomic cross-chain settlement.
- Cross-Border Enforcement:Jurisdictional recognition of pseudonymous contract signatures creates legal ambiguity for dispute resolution in London and New York courts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Contracts Platforms Market |
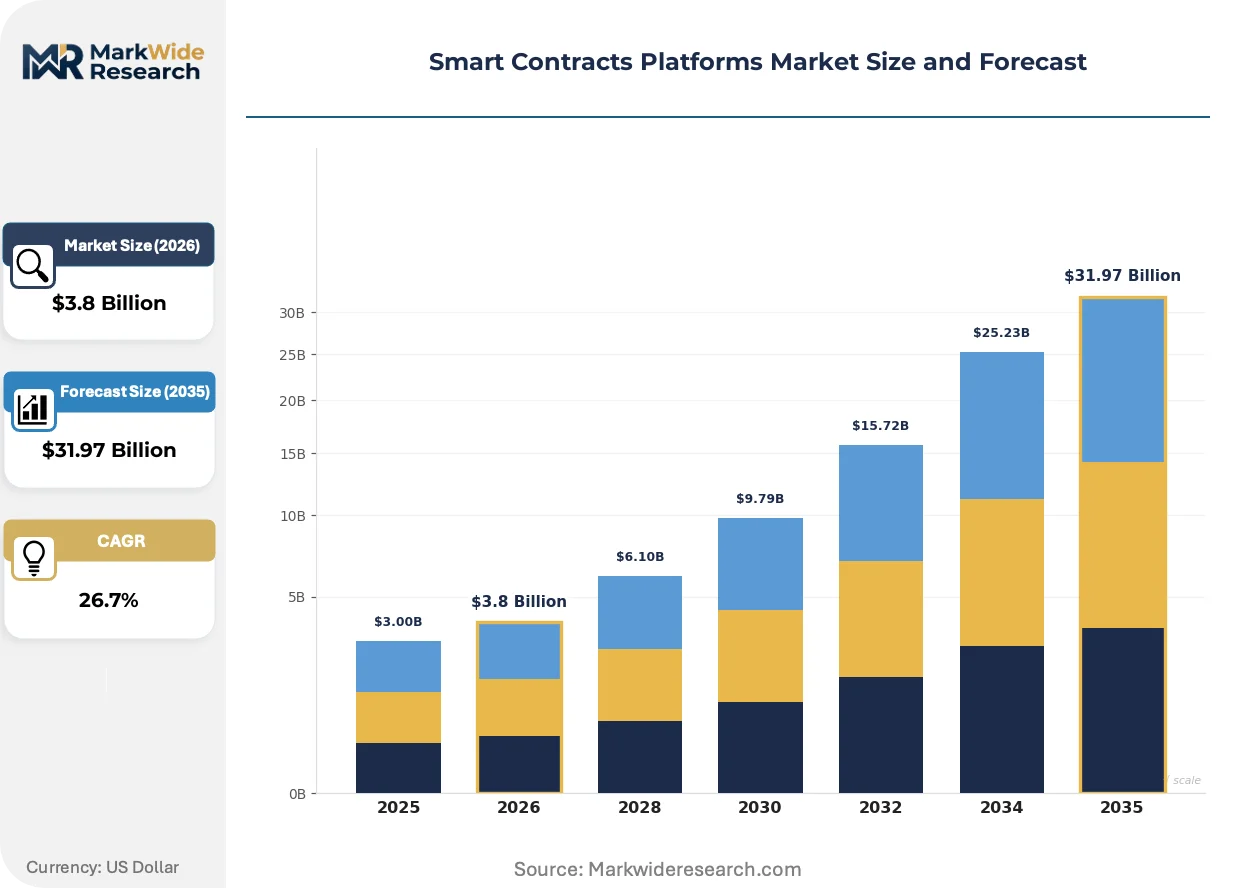
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $31.97 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Public Blockchain, Private Blockchain, Hybrid Blockchain, Consortium Blockchain Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual End User: Financial Services, Supply Chain, Healthcare, Real Estate Technology: Ethereum, Hyperledger, Corda, EOS |
| Companies Covered | Ethereum, Solana, Binance Smart Chain, Polkadot, Cardano, BNB Smart Chain, Cosmos, Hyperledger Fabric, NEAR Protocol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Contracts Platforms Market Trends and Innovations
Zero-knowledge proof systems are compressing verification overhead while expanding privacy-preserving computation, enabling regulatory-compliant confidentiality without sacrificing auditability for institutional counterparties.
Account abstraction via ERC-4337 is rewriting wallet interaction patterns by separating key management from transaction authorization. Retail neobanks in South Korea and Brazil are piloting social recovery mechanisms that eliminate seed phrase exposure. This architecture is compressing user onboarding friction for mass-market DeFi applications previously confined to sophisticated self-custody practitioners.
The EU AI Act imposes algorithmic audit requirements on automated decision systems embedded in contract execution logic. Financial institutions domiciling settlement layers in Frankfurt and Paris must document training data provenance and decision boundaries for smart contract oracles. Custody platforms are responding by segregating deterministic code paths from machine-learning price prediction modules.
Enterprise procurement teams are unbundling infrastructure decisions from token speculation, separating node operation contracts from native asset holdings. Asset managers in Zurich and Boston now negotiate service-level agreements with validator-as-a-service providers without taking balance sheet exposure to underlying network tokens. This behavioral pivot is stabilizing revenue models for platform infrastructure vendors.
Smart Contracts Platforms Market Segmentation
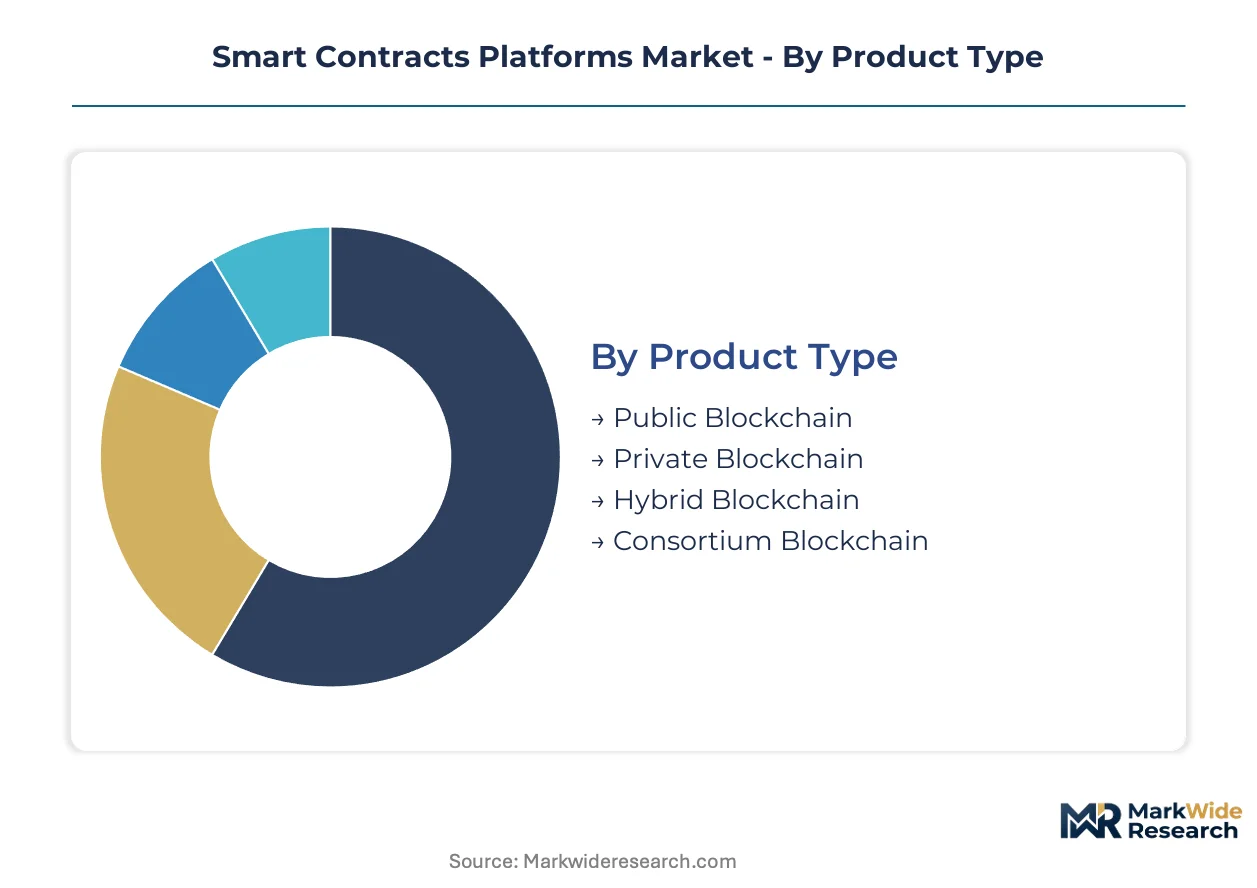
Smart contracts platforms fragment across architectural choices that determine finality speed, privacy guarantees, and regulatory exposure. Procurement teams select infrastructure based on counterparty verification requirements and jurisdictional recognition standards.
Product Type:
Architectural design choices determine consensus participation rights and cryptographic verification boundaries.
- Public Blockchain:Permissionless networks execute transparent settlement logic through open validator sets. Demand concentrates in decentralized finance protocols and retail-facing applications where censorship resistance outweighs throughput constraints. The EU MiCA framework recognizes these deployments for retail tokenized instruments.
- Private Blockchain:Restricted node participation enables sub-second finality and configurable privacy layers. Singaporean trade finance consortia and Swiss private banking networks favor this architecture for confidential multi-party settlement.
- Hybrid Blockchain:Selective disclosure mechanisms anchor sensitive data on private ledgers while publishing cryptographic proofs to public networks.
- Consortium Blockchain:Pre-approved validator sets among industry competitors balance decentralization with operational control.
Mature deployment sits with Private Blockchain. Newer deployment is concentrated in Hybrid Blockchain.
Deployment Model:
Delivery infrastructure choices reflect trade-offs between operational sovereignty and capital expenditure flexibility.
- Cloud-Based:Managed node infrastructure from hyperscale providers eliminates data center capital requirements. Asset managers in London and Zurich accelerate procurement through validator-as-a-service agreements without balance sheet exposure to underlying network tokens.
- On-Premises:Self-operated hardware delivers maximum key custody control for systemically important financial institutions. German Bundesbank pilot programs and Bank of France wholesale CBDC trials mandate this deployment mode.
- Hybrid:Sensitive signing operations remain on-premises while archival nodes sync to cloud infrastructure.
- Virtual:Containerized node software abstracts hardware dependencies for rapid network switching.
Cloud-Based captures the steepest expansion trajectory as procurement teams unbundle infrastructure from token speculation. On-Premises retains dominance in monetary authority deployments.
End User:
Vertical adoption patterns diverge based on legacy system replacement urgency and regulatory clarity.
- Financial Services:Settlement infrastructure modernization drives demand for atomic cross-border payment finality. Singapore's Project Guardian validates institutional-grade protocols, while Dubai Islamic Bank pilots programmable Sukuk issuance.
- Supply Chain:Documentary trade automation through conditional escrow releases addresses trillion-dollar financing gaps. Mumbai and Rotterdam port authorities pilot bill-of-lading tokenization.
- Healthcare:Clinical trial data integrity and pharmaceutical supply chain provenance attract pilot deployments.
- Real Estate:Fractional ownership registries and automated rental distribution contracts gain traction in tokenized property funds.
Financial Services commands established procurement budgets. Supply Chain exhibits the fastest climb as commodity traders migrate physical asset records to on-chain registries.
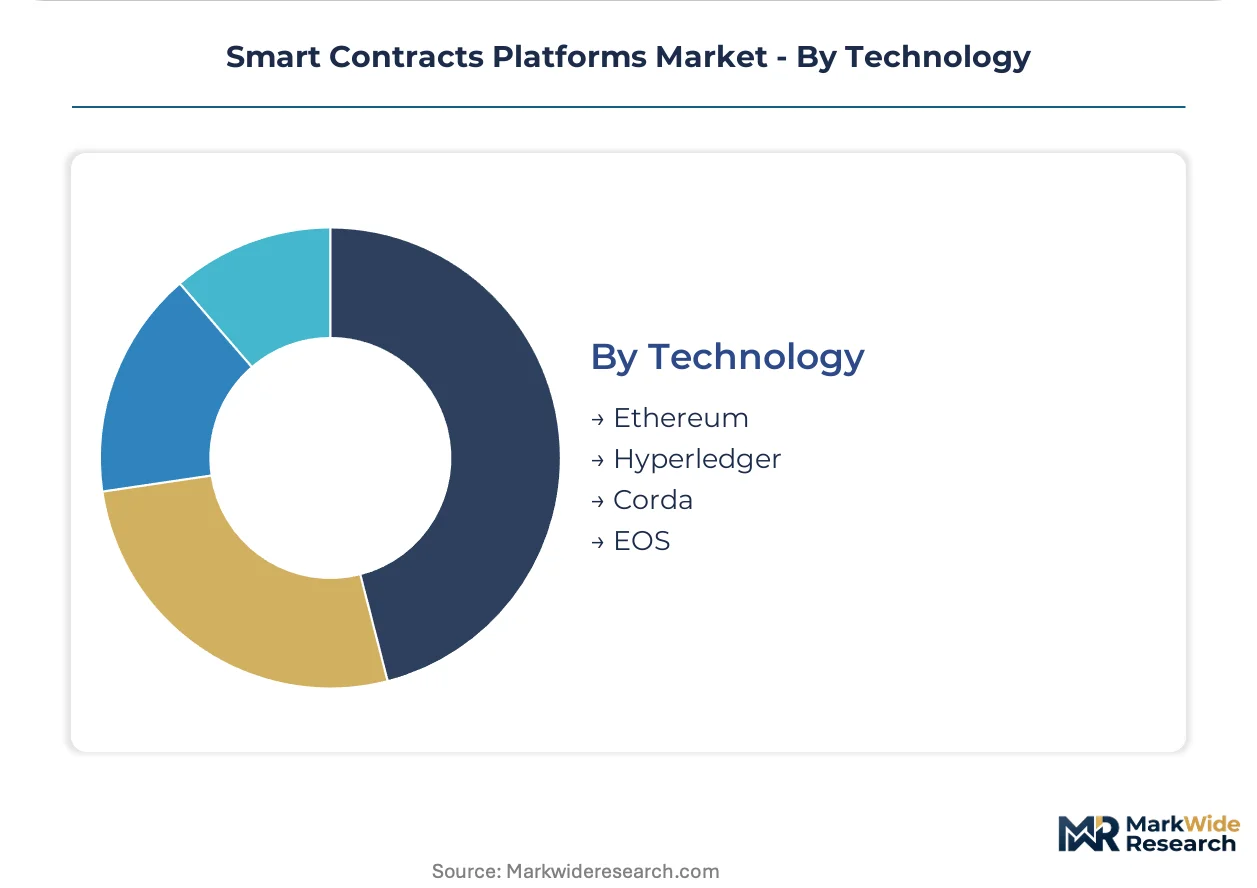
Technology:
Protocol selection locks development teams into specific programming languages, tooling ecosystems, and validator economics.
- Ethereum:Solidity programming standards and maximal developer tooling concentration sustain first-mover network effects. The protocol's transition to proof-of-stake validation reduced energy overhead while preserving smart contract composability.
- Hyperledger:Modular permissioned architecture serves regulated industries requiring identity-verified counterparties. IBM Food Trust and TradeLens deployments demonstrate enterprise supply chain viability.
- Corda:Point-to-point transaction privacy suits correspondent banking and syndicated loan markets.
- EOS:Delegated proof-of-stake governance enables feeless transaction models for high-frequency applications.
Ethereum anchors developer talent concentration. Hyperledger Fabric dominates permissioned enterprise procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in Singapore, Germany, the United States, Switzerland, and the United Arab Emirates are driving procurement concentration for smart contracts infrastructure, with each jurisdiction deploying distinct regulatory frameworks that determine where settlement layers achieve legal enforceability.
United States
The SEC's classification standards for native tokens versus utility instruments constrain which contract types achieve legal enforceability, while institutional custody platforms in New York and Chicago fragment demand across decentralized finance protocols. Asset managers in Boston negotiate service-level agreements with validator-as-a-service providers without taking balance sheet exposure to underlying network tokens.
Singapore
The Monetary Authority of Singapore's Project Guardian initiative validates institutional-grade DeFi protocols, attracting asset managers seeking regulated on-chain yield generation. Trade finance automation through conditional escrow releases addresses documentary trade gaps, with Dubai and Mumbai emerging as complementary pilot hubs for letter-of-credit infrastructure.
Germany
The Bundesbank mandates on-premises deployment for wholesale CBDC trials, delivering maximum key custody control for systemically important financial institutions. Frankfurt's concentration of monetary authority pilot programs contrasts with Zurich and London asset managers accelerating procurement through cloud-based validator-as-a-service agreements.
Switzerland
Swiss private banking networks favor private blockchain architecture for confidential multi-party settlement, while Zurich asset managers unbundle infrastructure decisions from token speculation. The country's regulatory clarity for tokenized financial instruments enables institutional deployment of automated settlement infrastructure across European capital markets.
United Arab Emirates
Dubai Islamic Bank pilots programmable Sukuk issuance, leveraging the city's emergence as a trade finance automation hub alongside Mumbai and Rotterdam port authorities. The Dubai International Financial Centre provides jurisdictional recognition frameworks that reduce legal ambiguity for pseudonymous contract signatures in cross-border enforcement scenarios.
Smart Contracts Platforms Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular permissioned deployments for regulated industries. The vendor base concentrates around three maturity tiers: first-mover public blockchain protocols sustaining developer network effects, high-throughput competitors optimizing transaction architecture, and enterprise-focused frameworks specializing in identity-verified counterparties. Strategic differentiation centers on validator-as-a-service expansion and formal verification audit capacity.
Within the enterprise permissioned tier, Hyperledger Fabric represents modular architecture serving regulated industries, while Ethereum exemplifies first-mover positioning in programmable contract standards. Solana occupies a position on the high-throughput vector, competing for applications where censorship resistance must balance against finality speed requirements.
| Leading Market Players |
|---|
| Ethereum |
| Solana |
| Binance Smart Chain |
| Polkadot |
| Cardano |
| BNB Smart Chain |
| Cosmos |
| Hyperledger Fabric |
| NEAR Protocol |
| Others |
Pricing and Supply Chain Analysis
The EU AI Act's algorithmic audit requirements for automated decision systems gate both qualified supply and premium-tier pricing access, as infrastructure vendors bearing compliance certification capture margin premiums while uncertified competitors face exclusion from Frankfurt and Paris settlement layer deployments.
Pricing Analysis
Volume concentrates in cloud-based validator-as-a-service agreements where asset managers negotiate service-level contracts without token exposure, while margin pools accrue to on-premises deployments for monetary authority pilots demanding hardware sovereignty. Price differentiation hinges on formal verification audit depth and jurisdictional recognition status under MiCA or SEC frameworks. Pricing pressure stems from hyperscale provider commoditization of managed node infrastructure. Financial services procurement teams exhibit lowest price sensitivity given systemic risk mandates, while retail-facing protocol developers face acute cost compression.
Supply Chain Analysis
Formal verification engineering talent scarcity in Estonia, Switzerland, and Singapore constrains audit capacity expansion for institutional-grade deployments. Specialized hardware for zero-knowledge proof acceleration and secure enclave processors draws from Taiwan semiconductor fabrication and Dutch lithography equipment. Supply chain risk centers on single-source vulnerability for cryptographic proof libraries. Distribution runs through validator-as-a-service aggregators in London and Zurich, with direct enterprise licensing for Bundesbank-style custody requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MiCA framework's legal certainty provisions for tokenized instruments create a cost-of-compliance barrier that entrenches certified infrastructure vendors while excluding undercapitalized entrants from European capital market procurement.
For Market Incumbents: Cement network effects by deepening formal verification audit capacity through acquisition of specialized mathematical proof engineering teams in Tallinn and Zurich. Expand validator-as-a-service geographic footprint to capture Singapore Project Guardian institutional demand before compliance requirements harden. Threat vector: emerging zero-knowledge rollup competitors displacing base-layer settlement volume. For New Entrants and Emerging Players: The mid-market pricing gap between premium formal-verified deployments and economy-tier cloud node services opens white-space in hybrid blockchain orchestration for Indian trade finance consortia and Brazilian neobank pilots. Target supply chain automation verticals where legacy SWIFT integration costs deter incumbent expansion. Go-to-market angle: AI-generated Solidity bytecode compressing legal team deployment timelines. For Investors and Strategic Acquirers: Monetary authority pilot program announcements in Frankfurt, Singapore, and Dubai are the leading indicator that wholesale CBDC infrastructure demand is crossing from experimental to procurement-phase viability. Long-term positioning favors validator-as-a-service platforms with existing MiCA compliance documentation and segregated oracle architecture. Acquisition archetype: formal verification audit shops with demonstrated Bundesbank or MAS engagement history. Signal to watch: central bank requests-for-proposal specifying atomic cross-chain settlement requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Formal Verification Audit Capacity Expansion | Mathematical proof engineering scarcity in Tallinn and Zurich limits institutional deployment velocity. |
| Validator-as-a-Service Geographic Expansion | Singapore Project Guardian validation attracts asset managers seeking regulated on-chain yield infrastructure. |
| Zero-Knowledge Proof System Integration | Privacy-preserving computation enables regulatory-compliant confidentiality for Swiss private banking networks. |
| AI-Contract Convergence Platform Launch | Natural language processing engines compress deployment timelines for non-technical legal teams in São Paulo. |
| Carbon Credit Verification Oracle Deployment | Satellite-attested reforestation data triggers automatic credit minting under Paris Agreement Article 6. |
Research Methodology
Multi-period observation of regulatory filing patterns, central bank pilot program announcements, and validator node distribution metrics anchored the trend analysis, supplemented by interviews with smart contract platform engineering leads, institutional custody procurement officers, regulatory affairs specialists at EU financial authorities, and formal verification audit firm partners. Secondary validation drew from MiCA implementation guidance documents, SEC enforcement action records, MAS Project Guardian technical reports, and hyperscale provider infrastructure capex disclosures. Bottom-up transaction volume estimates triangulated against top-down infrastructure spending projections.
Input-output matrix modeling segmented deployment models, blockchain architecture types, end-user verticals, and jurisdictional regulatory clusters across the projection horizon. CAGRs derived from validator node count trajectories, enterprise procurement pipeline visibility, and tokenized real asset migration rates. Industry-specific forecast inputs included formal verification talent pool expansion rates and central bank digital currency pilot progression stages.
Inputs from regulatory authority guidance publications and infrastructure vendor service-level agreement templates were available through the study window; gaps in proprietary validator revenue breakdowns and undisclosed oracle fee structures introduce uncertainty bands around cloud-based deployment forecasts. Assumptions regarding MiCA enforcement timing and SEC classification stability underpin the analysis. Regulatory divergence between Frankfurt, Singapore, and New York settlement layer recognition standards warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market