
 Cambodia Telecom Market | 2026-2036
Cambodia Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Telecom Market Analysis
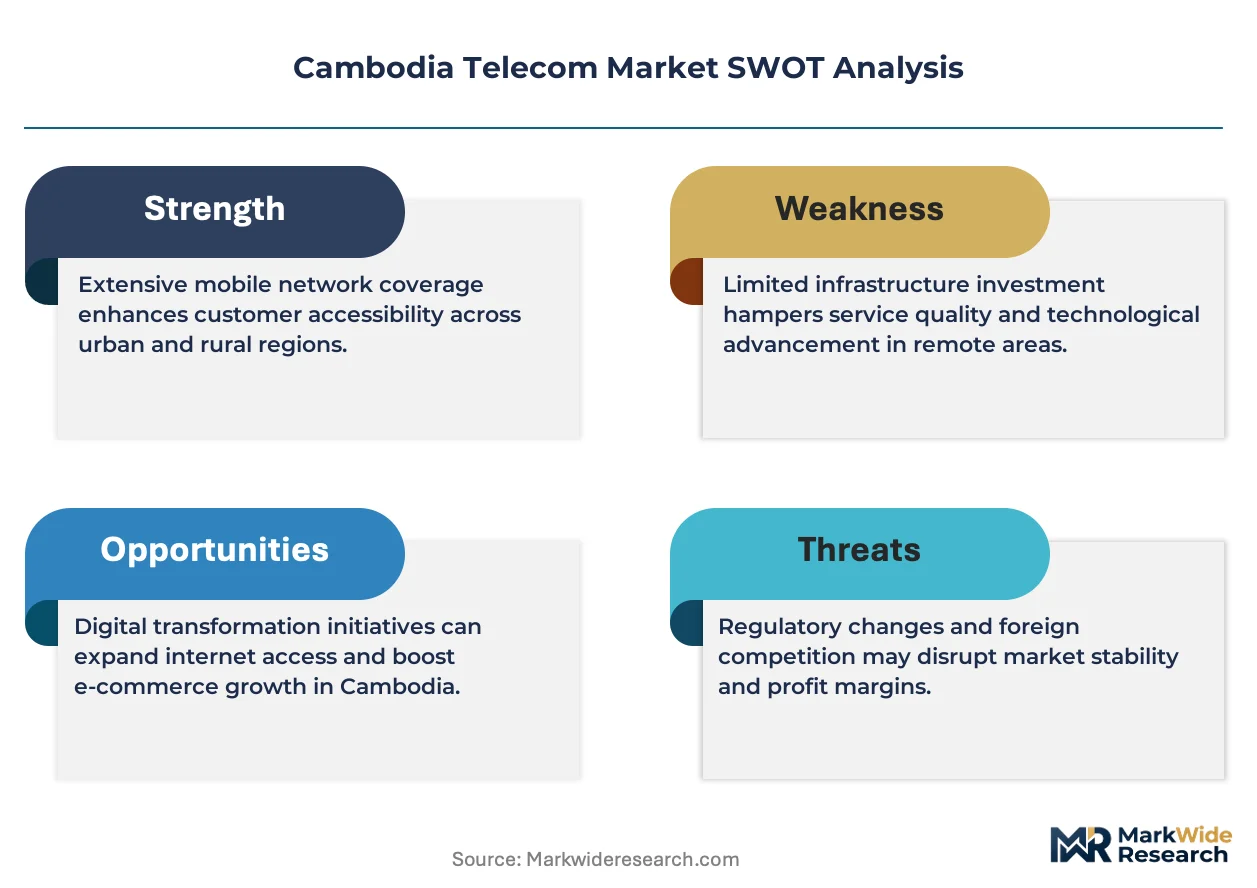
ISO 27001 certification is reorganizing vendor qualification for government contracts in Cambodia. Smart Axiata leverages its 4G spectrum position to anchor enterprise connectivity in Phnom Penh. Cellcard competes on prepaid mobile penetration across provincial districts. Metfone dominates the fixed-line backbone through its state-affiliated infrastructure holdings.
Cambodia telecom encompasses the transmission of voice, data, and video across wireless and wireline infrastructure operating between 700 MHz and 3.5 GHz spectrum bands, primarily serving commercial communication and digital service delivery. Mobile Services generate the largest revenue pool through prepaid voice and data bundles, while Internet Services represent the fastest-expanding segment driven by fiber-to-the-home rollouts. 4G technology holds the dominant subscriber base, though VoIP adoption accelerates among Small Businesses seeking cost-efficient enterprise voice.
Cambodia's Telecom Regulator mandates infrastructure-sharing frameworks that reduce duplication costs, while the country's national standards body enforces equipment certification for network hardware imports. The Ministry of Posts and Telecommunications shapes spectrum allocation timelines that directly gate market entry for new operators. Stakeholders must monitor pending data localization requirements and spectrum auction schedules to calibrate capital deployment timing.
Market Dynamics
Cambodia's telecom sector is restructuring around infrastructure-sharing mandates issued by the Telecom Regulator, which compel operators to pool fiber and tower assets rather than duplicate deployments. This policy is compressing capital intensity for new market entrants while entrenching incumbents with existing backbone holdings.
Growth Catalysts
- Rural Mobile Financial Services:Agricultural cooperatives outside Phnom Penh are adopting mobile payment platforms for crop financing and supply chain settlements, expanding addressable subscriber bases beyond urban corridors.
- ISO 27001 Certification:Government procurement rules now require information security certification for vendors bidding on public sector connectivity contracts, creating qualified supplier advantages for certified operators.
- Fiber-to-the-Home Rollouts:Dense urban deployment in Phnom Penh and Siem Reap is saturating premium residential segments with gigabit-capable access infrastructure.
Market Restraints
- Mandatory SIM Registration:Subscriber identity verification requirements impose customer acquisition friction and operational compliance costs on prepaid-heavy business models.
- Fixed-Line Infrastructure Concentration:State-affiliated backbone holdings create asymmetric access pricing for competitors seeking national coverage.
- 4G Spectrum Scarcity:Limited sub-1 GHz allocation constrains rural propagation economics and indoor penetration performance.
Strategic Opportunities
- Provincial District Penetration:Prepaid mobile services remain underdeveloped in secondary urban centers beyond the Phnom Penh-Siem Reap corridor, offering subscriber growth headroom.
- VoIP Enterprise Adoption:Small businesses are displacing traditional PSTN services with internet-based voice, opening managed service revenue streams.
- Spectrum Auction Participation:Pending allocation timelines for additional bands present entry mechanisms for new operators and capacity expansion for incumbents.
Industry Challenges
- Equipment Certification Delays:National standards body import approvals for network hardware extend deployment timelines and inventory carrying costs.
- Data Localization Compliance:Pending domestic storage requirements would force infrastructure investment and architectural reconfiguration for existing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Telecom Market |
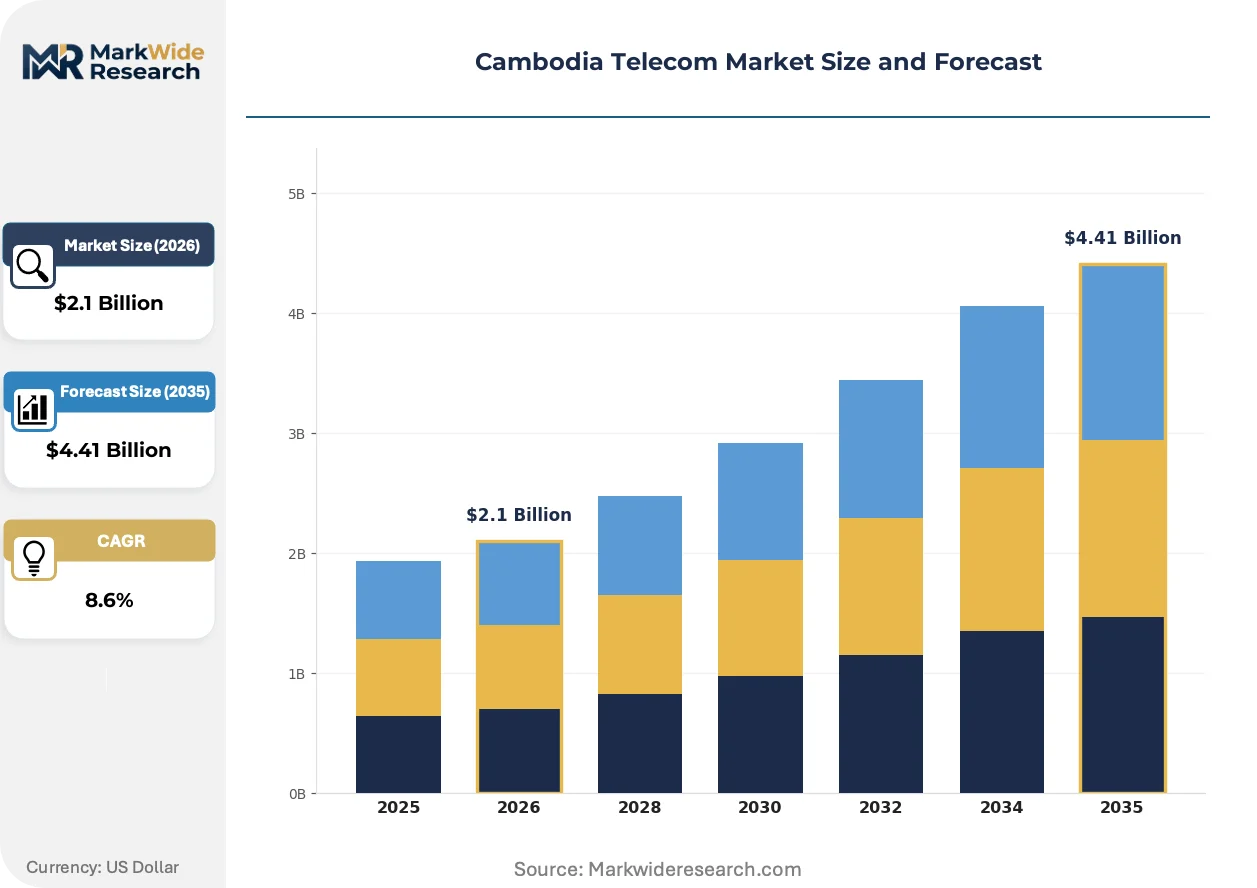
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed Line Services, Internet Services, Data Services Technology: 2G, 3G, 4G, VoIP End User: Residential, Small Businesses, Enterprises, Government Pricing Model: Prepaid, Postpaid, Bundled Plans, Data-Only Plans |
| Companies Covered | Metfone, Smart Axiata, Cellcard, Cootel, qb, Ezecom, Viettel Cambodia, Seatel, Angkornet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Telecom Market Emerging Trajectories
Network function virtualization is restructuring how Cambodian operators provision enterprise services, collapsing hardware dependency and accelerating service velocity. This architectural shift is enabling new competitive maneuvers across fixed and mobile domains.
Embedded SIM technology is miniaturizing device onboarding for IoT deployments in agricultural monitoring and logistics tracking. Plantation operators and freight consolidators are adopting eSIM-enabled sensors at scale. This capability is compressing activation timelines from weeks to hours while eliminating physical distribution logistics for connectivity provisioning.
Cambodia's Telecom Regulator is enforcing infrastructure-sharing frameworks that mandate co-location on towers and fiber ducts. The policy reduces redundant capital deployment across overlapping coverage footprints. Mobile operators in dense urban corridors are responding by consolidating radio access network operations into shared tenancy agreements.
Enterprise buyers are unbundling connectivity from managed service contracts, procuring raw bandwidth and layering security and cloud access independently. System integrators and IT consultancies are displacing traditional telecom resellers in this advisory role. This pattern is most visible among mid-market firms in Phnom Penh's commercial districts seeking vendor diversification.
Cambodia Telecom Market Segmentation
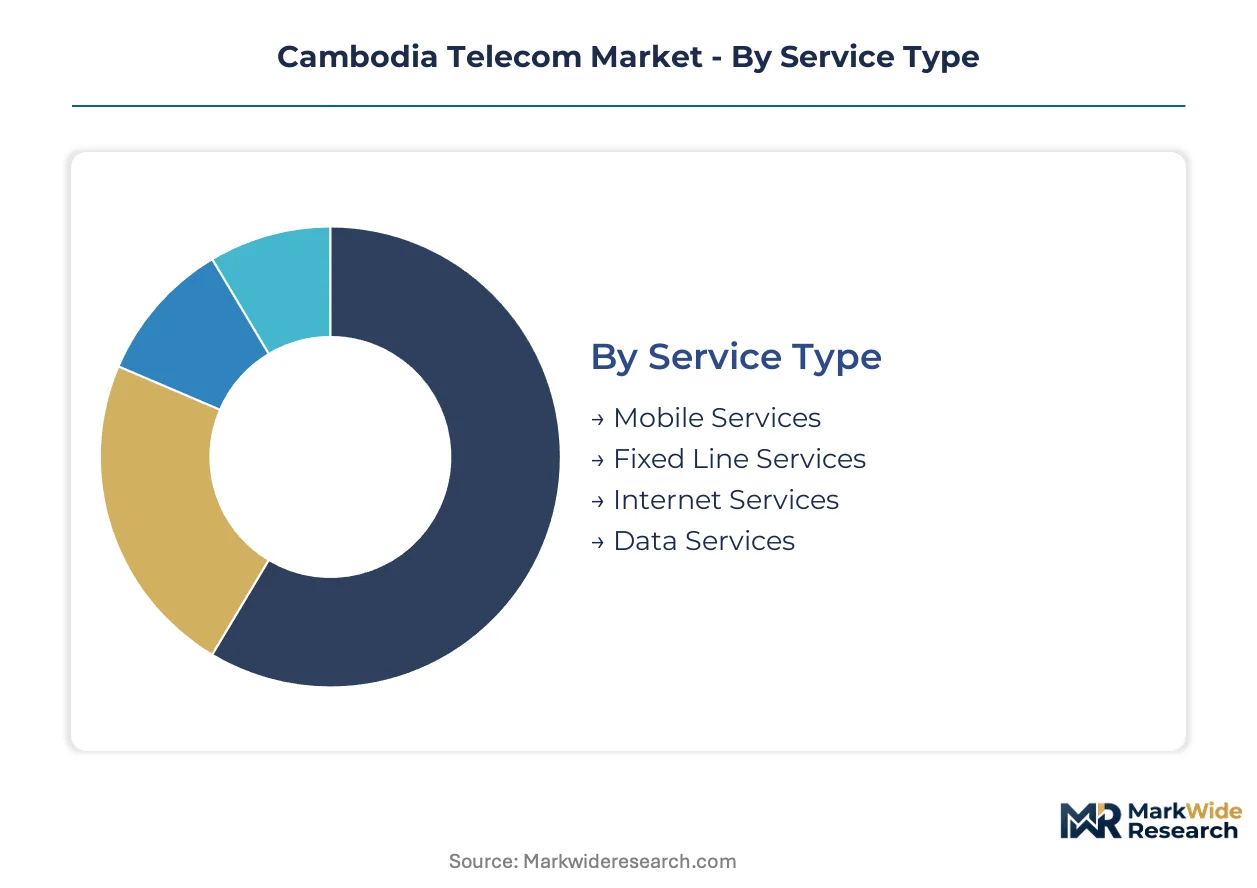
Service type and technology segments reveal distinct deployment economics across Cambodia's urban-rural divide. Pricing model segmentation exposes divergent customer acquisition strategies between prepaid-heavy provincial markets and postpaid enterprise corridors.
Service Type:
Mobile Services and Internet Services concentrate demand in Phnom Penh and Siem Reap, while Fixed Line Services and Data Services extend through state-affiliated backbone infrastructure into secondary districts.
- Mobile Services:Prepaid voice and data bundles generate the largest revenue pool through subscriber volume. Demand concentrates among agricultural cooperatives outside Phnom Penh adopting mobile financial services for crop financing and supply chain settlements.
- Internet Services:Fiber-to-the-home rollouts deliver gigabit-capable access infrastructure. Phnom Penh and Siem Reap corridors show densest deployment saturation as operators prioritize premium residential segments with highest ARPU potential.
- Fixed Line Services:Metfone dominates through state-affiliated infrastructure holdings creating asymmetric access pricing.
- Data Services:Enterprise connectivity contracts require ISO 27001 certification under government procurement rules.
Mobile Services holds the largest share; momentum sits with Internet Services.
Technology:
4G spectrum position anchors competitive economics, while legacy 2G and 3G maintain provincial coverage obligations and VoIP displaces traditional PSTN among cost-sensitive small businesses.
- 4G:Smart Axiata leverages sub-1 GHz and mid-band allocations to anchor enterprise connectivity in Phnom Penh. Limited spectrum scarcity constrains rural propagation economics and indoor penetration performance.
- VoIP:Internet-based voice protocols accelerate among Small Businesses seeking cost-efficient enterprise voice solutions. Adoption climbs fastest where fiber infrastructure enables quality-of-service guarantees.
- 3G:Transitional technology maintaining coverage in districts awaiting 4G upgrade cycles.
- 2G:Legacy network layer sustaining basic voice and SMS in remote agricultural zones.
4G dominates subscriber base; VoIP shows steepest expansion trajectory among enterprise adopters.
End User:
Residential and Small Business segments drive volume through prepaid consumption, while Enterprises and Government procure through certified vendor frameworks with stricter security requirements.
- Residential:Fiber-to-the-home saturation concentrates in Phnom Penh and Siem Reap premium segments. Gigabit-capable deployments target households with multiple connected devices and streaming consumption patterns.
- Government:ISO 27001 certification now mandatory for vendors bidding on public sector connectivity contracts. Procurement rules reorganize qualified supplier advantages toward certified operators with established security frameworks.
- Small Businesses:VoIP adoption displaces traditional PSTN services for cost efficiency.
- Enterprises:Unbundled connectivity procurement separates raw bandwidth from layered security and cloud access services.
Residential commands subscriber volume; Government contracts carry highest margin premiums.
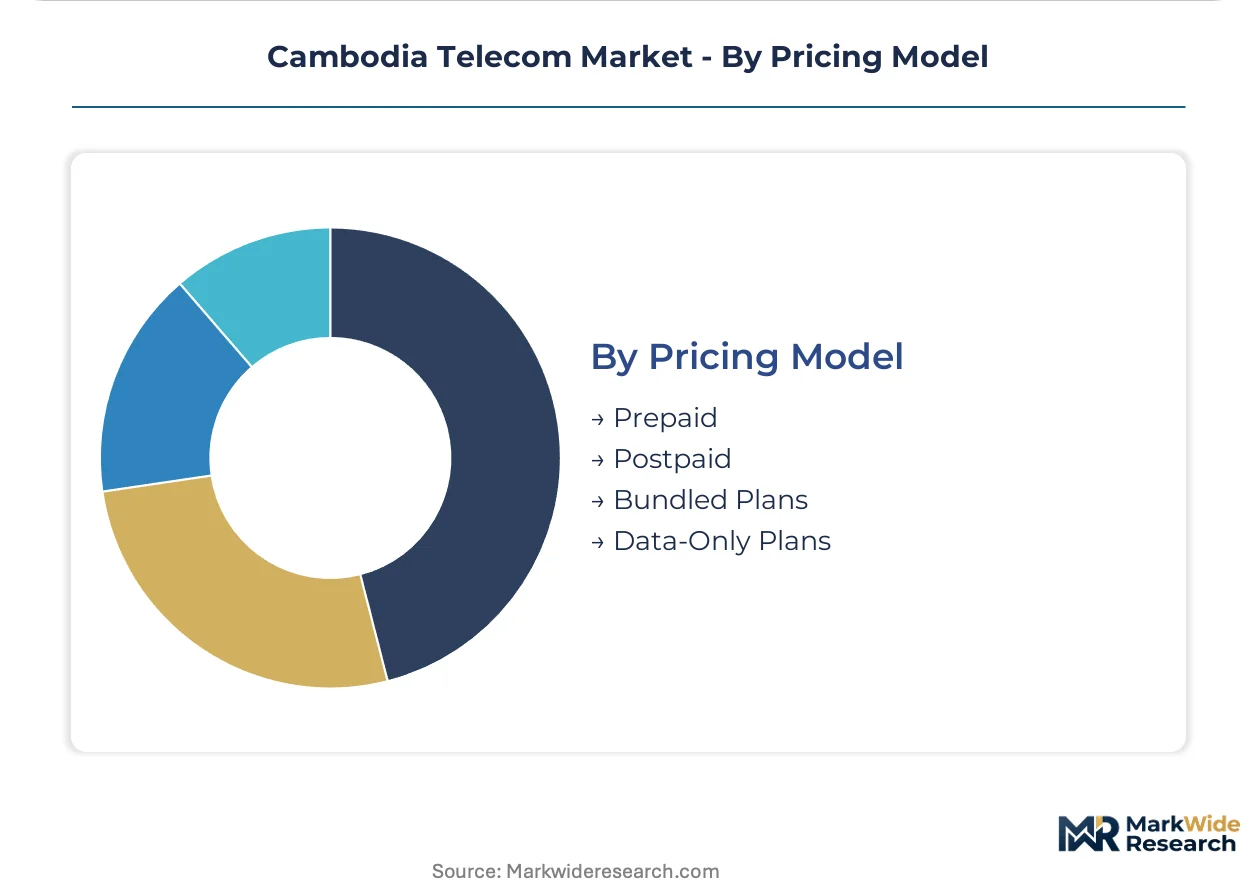
Pricing Model:
Prepaid mechanics dominate provincial customer acquisition, while postpaid and bundled structures penetrate urban enterprise accounts with predictable revenue streams.
- Prepaid:Cellcard competes across provincial districts with flexible top-up mechanisms suited to irregular income patterns. Mandatory SIM registration imposes customer acquisition friction and operational compliance costs.
- Bundled Plans:Operators combine voice, data, and mobile financial services into integrated offerings. Agricultural cooperatives adopt these packages for crop financing workflows and supply chain settlement platforms.
- Postpaid:Corporate accounts with credit-verified billing cycles.
- Data-Only Plans:IoT sensor deployments and secondary device connectivity.
Prepaid captures widest subscriber base; Bundled Plans gain share fastest through mobile financial service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers and agricultural cooperatives concentrate demand in distinct geographic pockets across Cambodia, with infrastructure deployment clustering around Phnom Penh and Siem Reap while rural mobile financial services penetrate provincial districts.
Phnom Penh Capital Region
Phnom Penh anchors national demand through enterprise connectivity contracts and fiber-to-the-home saturation. The Telecom Regulator's infrastructure-sharing mandates compress capital intensity for operators deploying in dense urban corridors. Smart Axiata leverages its 4G spectrum position to serve corporate accounts in Chamkarmon and Daun Penh commercial districts.
Siem Reap Corridor
Siem Reap concentrates premium residential fiber deployment alongside tourism-dependent hospitality connectivity. The Ministry of Posts and Telecommunications shapes spectrum allocation timelines that gate capacity expansion for operators serving the Angkor temple complex vicinity. Metfone's state-affiliated backbone holdings provide asymmetric access pricing for competitors seeking national coverage.
Battambang and Northwestern Provinces
Agricultural cooperatives in Battambang drive mobile financial services adoption for rice crop financing and supply chain settlements. Mandatory SIM registration requirements impose customer acquisition friction on prepaid-heavy business models targeting irregular income patterns. Cellcard competes across these provincial districts with flexible top-up mechanisms.
Kampong Cham and Mekong Lowlands
The Mekong corridor sustains transitional 3G coverage obligations while awaiting 4G upgrade cycles in remote agricultural zones. Equipment certification delays from the national standards body extend deployment timelines for network hardware imports. VoIP adoption accelerates among small businesses in Kampong Cham town seeking cost-efficient enterprise voice.
Coastal and Border Provinces
Sihanoukville and border districts with Vietnam and Thailand experience cross-border spectrum interference and roaming complexity. Pending data localization requirements would force infrastructure investment for domestic storage compliance. Provincial district penetration remains underdeveloped beyond the Phnom Penh-Siem Reap axis, offering subscriber growth headroom.
Cambodia Telecom Market Vendor Landscape
Player mix skews toward state-affiliated incumbents with backbone holdings and regional telecom groups with spectrum depth. Market structure consolidates around three dominant operators controlling fixed-line infrastructure and 4G subscriber bases. Strategic archetypes include state-backed national champions, ASEAN regional platforms, and specialized provincial prepaid competitors. Competitive moves center on infrastructure-sharing tenancy agreements and ISO 27001 certification for government contract eligibility.
Among the dominant tier, Metfone exemplifies the state-affiliated national champion archetype through its backbone infrastructure concentration. Smart Axiata occupies the ASEAN regional platform position leveraging group-level spectrum coordination. Cellcard represents the specialized provincial competitor archetype with prepaid-heavy district penetration. These three anchors illustrate how regulatory mandates around infrastructure sharing and security certification reshape qualified supplier advantages.
| Leading Market Players |
|---|
| Metfone |
| Smart Axiata |
| Cellcard |
| Cootel |
| qb |
| Ezecom |
| Viettel Cambodia |
| Seatel |
| Angkornet |
| Others |
Supply Flow & Price Mechanics
Fixed-line backbone scale economies in Cambodia concentrate supply-side power with Metfone's state-affiliated infrastructure holdings, compressing price floors for competitors while anchoring asymmetric access tariffs that cascade through provincial resale markets.
Pricing Analysis
Cost-plus tower tenancy contracts with inflation indexation dominate infrastructure-sharing arrangements mandated by Cambodia's Telecom Regulator. Pricing stratifies across premium fiber-to-the-home, standard 4G mobile, and economy 2G legacy tiers based on bandwidth guarantees and ISO 27001 certification status. Cost compression in prepaid mobile is intensifying because Cellcard's provincial district competition erodes subscriber acquisition margins. Agricultural cooperatives exhibit highest price sensitivity due to irregular crop income patterns, while government contracts show lowest sensitivity given security compliance premiums.
Supply Chain Analysis
Just-in-time equipment provisioning prevails for 4G base station deployments, though strategic stockpiling of sub-1 GHz radio units occurs ahead of anticipated spectrum auction timelines. Network hardware draws from China, South Korea, and Vietnam for radio access equipment, fiber optic cable, and power systems respectively. Tariff exposure on Chinese telecommunications equipment imports presents structural vulnerability given concentration of vendor relationships. Distribution runs through Phnom Penh-based system integrators serving provincial operator rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cambodia's telecom sector sits at a platform-economics inflection where mobile financial services interoperability with agricultural supply chains redefines subscriber stickiness beyond pure connectivity.
For Market Incumbents: Secure ISO 27001 certification lock-in for government contracts before spectrum auction timing opens procurement to new qualified suppliers. Fortify tower and fiber co-location tenancy agreements to entrench infrastructure-sharing economics against emerging provincial competitors. Vertical integration into mobile financial service platforms anchors subscriber retention as agricultural cooperatives displace cash-based crop financing. For New Entrants and Emerging Players: Differentiate on embedded SIM-enabled IoT service bundles for plantation operators and freight consolidators in Battambang and northwestern provinces. Target underpenetrated secondary urban centers beyond the Phnom Penh-Siem Reap corridor where prepaid mobile financial services adoption accelerates. Pursue direct-to-cooperative distribution partnerships bypassing traditional retail channel congestion. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with government-certified security frameworks and fixed-line backbone holdings that generate stable tenancy income. Long-term viability favors state-affiliated national champions with spectrum depth and infrastructure-sharing mandate compliance. Watch for data localization requirement finalization as inflection indicator forcing capital-intensive domestic storage infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Infrastructure-Sharing Tenancy Expansion | Reduces redundant capital deployment across overlapping 4G coverage footprints per Telecom Regulator mandates. |
| ISO 27001 Certification Investment | Creates qualified supplier advantage for Cambodia government connectivity procurement contracts. |
| Mobile Financial Services Platform Integration | Captures agricultural cooperative transaction flows for crop financing and supply chain settlements. |
| Embedded SIM Technology Deployment | Compresses IoT sensor activation timelines from weeks to hours for plantation monitoring applications. |
| Fiber-to-the-Home Urban Saturation | Targets premium residential segments in Phnom Penh and Siem Reap with highest ARPU potential. |
Methodological Framework
A standing panel of network operations executives, regulatory affairs specialists at Cambodia's Telecom Regulator, agricultural cooperative technology officers, and enterprise IT procurement managers provided ongoing calibration throughout the study period. Primary interview findings combined with secondary validation from Ministry of Posts and Telecommunications spectrum allocation announcements, equipment import certification records, and mobile financial services adoption surveys. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from infrastructure deployment filings.
Consistency checks validated volume and value outputs against external benchmarks including tower tenancy agreement disclosures and fiber route kilometer expansion records. Segmentation modeling spanned service type, technology generation, end-user category, and pricing model dimensions across the projection horizon. CAGRs derived from subscriber growth trajectories, ARPU compression curves, and infrastructure capital intensity ratios. Industry-specific inputs included spectrum scarcity constraints, mandatory SIM registration compliance costs, and mobile financial services penetration rates by provincial district.
The analysis sits within stated boundaries; outcomes outside infrastructure-sharing mandate enforcement, spectrum auction schedule adherence, or data localization requirement implementation would require recalibration. Forecasts reflect documented assumptions regarding regulatory continuity and equipment import certification processing timelines. Revision becomes warranted when mobile financial services interoperability standards or cross-border roaming agreements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Hungary ICT Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Global International Calling Apps Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Thailand ICT Market
Telecommunications
Video Door Phones Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Singapore Telecom Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
IP Telephony Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
5G System Integration Market